
 Package Closing Machines Market | 2026-2036
Package Closing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Package Closing Machines Market Analytics
Integration of servo-driven motion control and IoT-enabled predictive maintenance is tilting the competitive landscape toward intelligent closing platforms. Krones AG leverages its beverage packaging heritage to dominate high-speed rotary sealing applications. Syntegon Technology GmbH differentiates through pharmaceutical-grade containment and cleanroom-compatible designs. Coesia S.p.A. anchors its position via deep specialization in tobacco and confectionery wrapping systems.
Package closing machines mechanically seal, strap, or bond containers using heat, adhesive, or mechanical tension to secure contents for transport and shelf stability; typical systems operate at 30 to 600 cycles per minute depending on product format and automation level. Heat sealers lead the product type category due to their dominance in food tray lidding and flow-wrap applications where hermetic integrity is mandatory. Automatic technology commands the largest installed base, though semi-automatic units retain strongholds in contract packaging and short-run manufacturing where changeover flexibility outweighs throughput optimization. E-commerce end users represent the fastest-expanding demand pool as carton sealing and void-fill integration become critical to damage reduction in last-mile logistics.
The EU Machinery Directive and FDA cGMP regulations for pharmaceutical packaging equipment shape compliance requirements across export-oriented manufacturers, forcing upgrades to validated washdown designs and traceable control systems. ISO 9001 quality management and CE marking remain baseline prerequisites for market access in Europe and most developed economies. Stakeholders must monitor how extended producer responsibility laws in multiple jurisdictions reshape material compatibility requirements and retrofit demand for existing installed bases.
Market Dynamics
E-commerce fulfillment networks are compressing machine procurement cycles as parcel volumes force warehouse operators toward sub-12-month deployment timelines for automated carton sealing systems.
Growth Catalysts
- EU Green Deal packaging directives:The EU's extended producer responsibility mandates are accelerating paper-compatible heat-sealer retrofits across food and beverage packaging lines in Germany and France.
- Pharmaceutical serialization requirements:FDA cGMP track-and-trace regulations are driving validated washdown machine upgrades at sterile fill-finish facilities in the United States.
- Carton sealing automation:Third-party logistics providers in the United Kingdom are deploying void-fill integrated closing stations to reduce damage claims in last-mile delivery networks.
Market Restraints
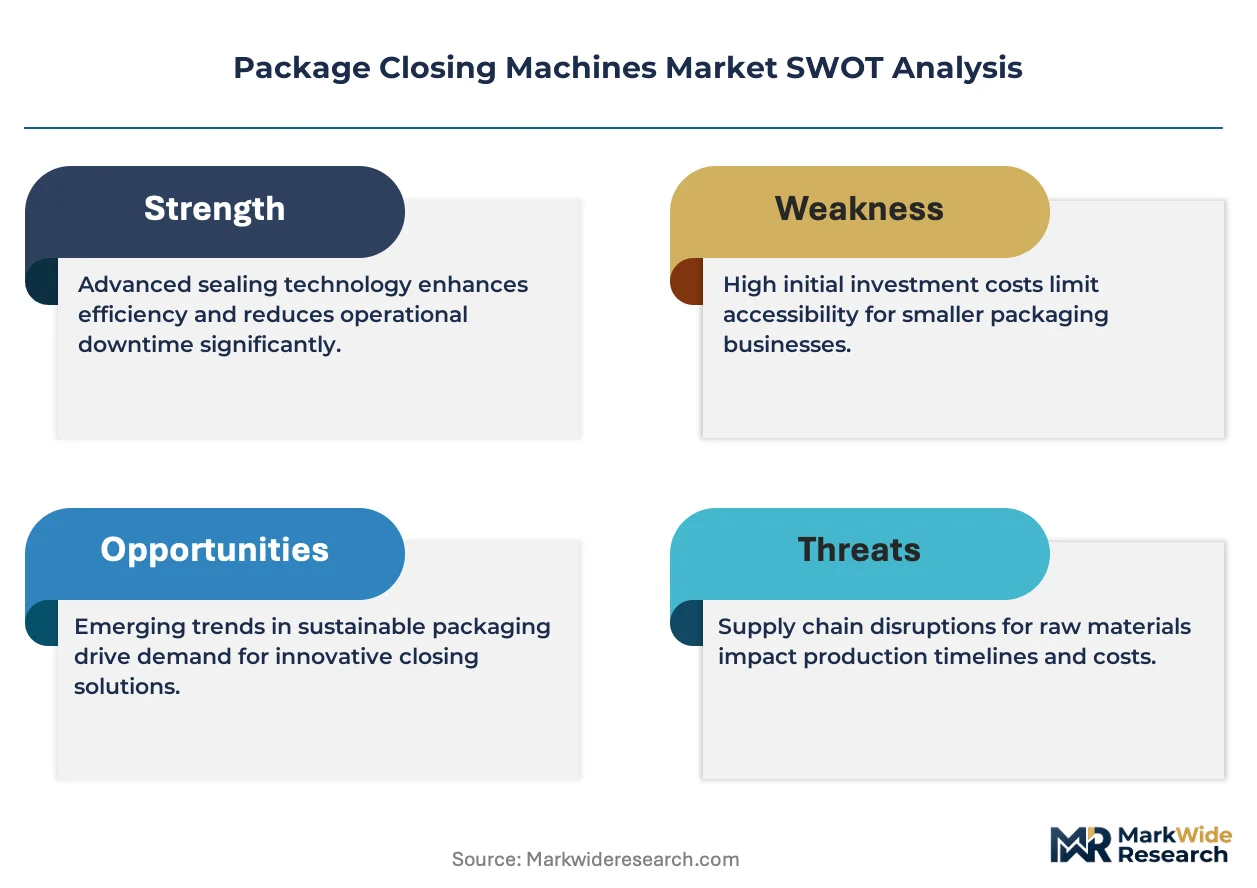
- Stainless steel price volatility:304-grade stainless input costs fluctuate with nickel futures, compressing margin buffers for European equipment fabricators.
- Servo motor supply concentration:Precision motion control components concentrate among Japanese and German suppliers, exposing OEMs to 16-week lead time extensions.
- Hermetic seal validation complexity:Pharmaceutical barrier testing protocols extend commissioning timelines by 4-8 weeks at sterile manufacturing sites.
Strategic Opportunities
- India contract packaging expansion:CDSCO's phased manufacturing program is attracting multinational pharma packaging investments to Ahmedabad and Hyderabad clusters.
- Biodegradable film sealing:PLA and PHA-compatible heat profiles represent unserved demand as Brazil's ANVISA advances sustainable packaging guidelines.
- Edge-computing predictive maintenance:Convergence of vibration sensors and machine-learning anomaly detection creates aftermarket service revenue streams for installed base operators.
Industry Challenges
- Mechatronics technician scarcity:Servo tuning and PLC programming skills gap extends commissioning timelines at automated installation sites.
- CE-MDR dual certification burden:Pharmaceutical equipment must satisfy both machinery safety and medical device regulations, doubling documentation requirements for EU-bound exports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Package Closing Machines Market |
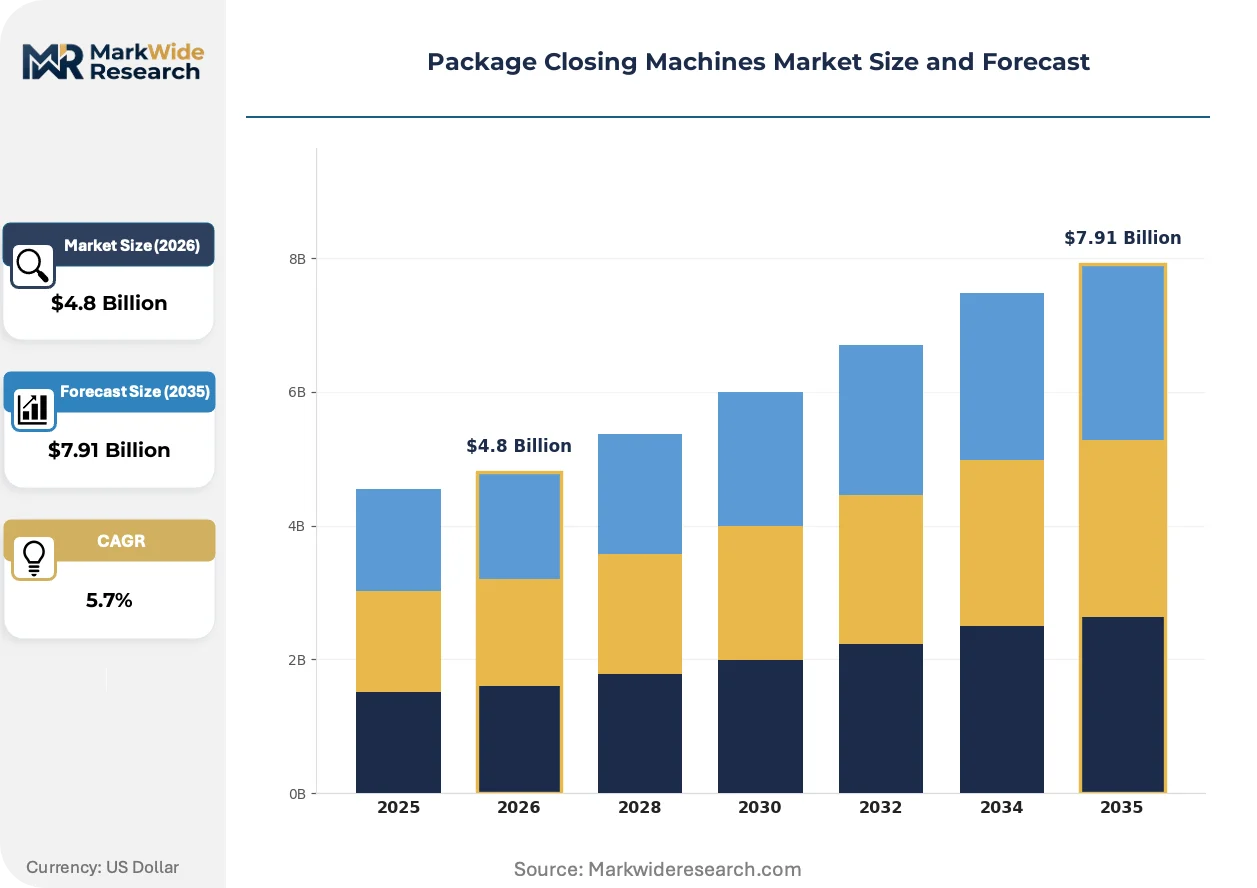
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Sealers, Adhesive Applicators, Strapping Machines, Banding Machines Technology: Automatic, Semi-Automatic, Manual, Low-Speed End User: Food Packaging, Household Products, Pharmaceuticals, E-Commerce Material: Plastic, Paper, Metal, Composite |
| Companies Covered | Tetra Pak, Krones AG, Coesia S.p.A., Barry-Wehmiller, Syntegon Technology GmbH, Multivac Sepp Haggenmüller, ProMach, Inc., Bosch Packaging Technology, GEA Group Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Package Closing Machines Market Evolving Landscape
Intelligent closing platforms are rewiring competitive advantage through predictive uptime guarantees and material-agnostic sealing architectures that compress changeover intervals.
Servo-driven rotary sealing technology is migrating from pneumatic cam systems in high-volume beverage canning operations. Coca-Cola bottlers in Spain and Mexico are retrofitting existing lines with direct-drive motion control to cut format changeover from 45 minutes to under 8 minutes. This migration from mechanical to electronic motion is compressing the viable supplier base to firms with in-house servo engineering capabilities.
The EU Machinery Directive's 2023 update to software safety requirements is forcing control system revalidations across exported equipment. Manufacturers must now document cybersecurity risk assessments for networked sealing controllers, adding 6-10 weeks to type-examination procedures. Pharmaceutical OEMs serving European markets are responding by segregating operational technology networks from enterprise IT infrastructure.
Asset-light contracting is displacing capital purchase models among mid-sized North American co-packers. Equipment-as-a-service arrangements now bundle maintenance, consumables, and throughput guarantees into per-unit sealing fees. This shift concentrates most visibly in California's wine and specialty food contract packaging corridor, where seasonal volume spikes favor operational flexibility over ownership.
Package Closing Machines Market Segmentation
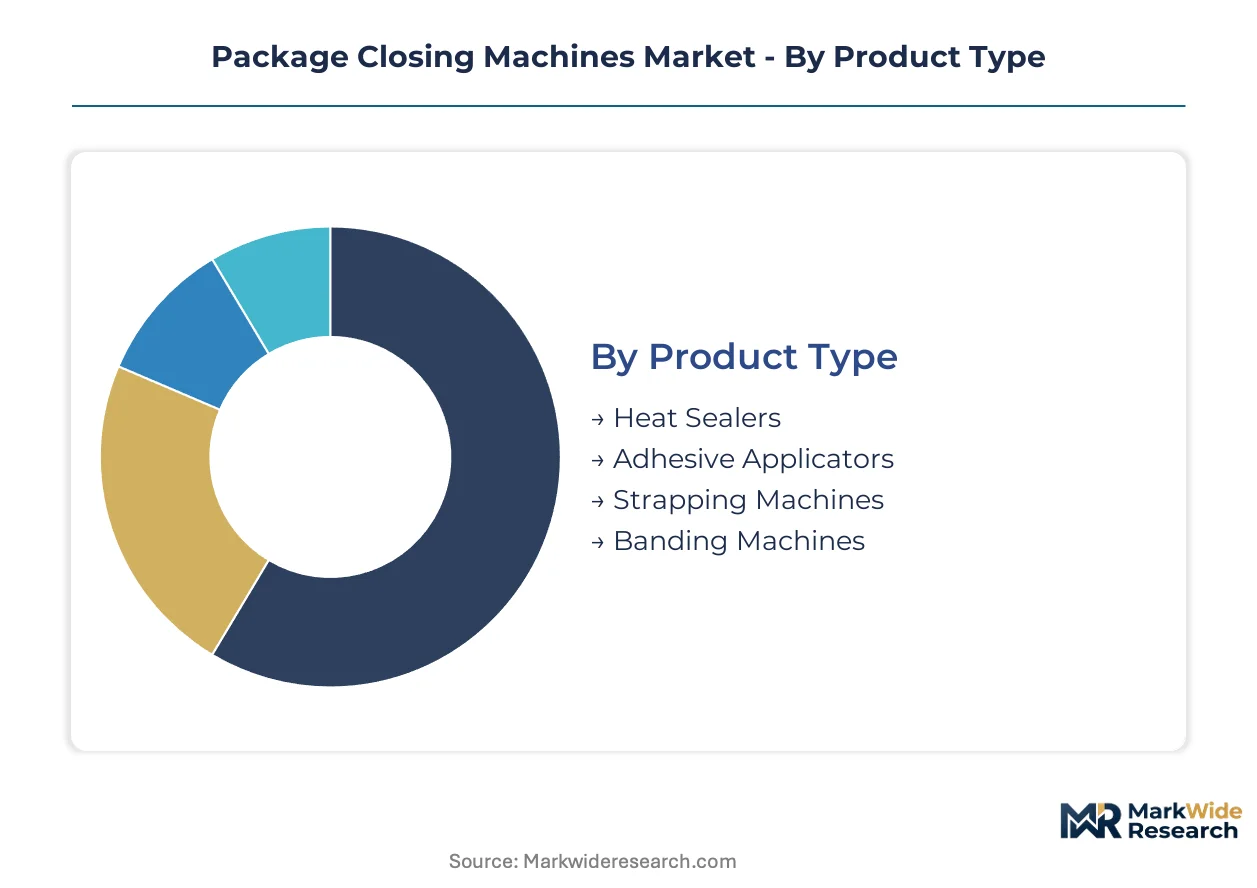
Segmentation in package closing machines reveals distinct service intensity patterns across equipment categories. Heat sealers demand intensive field engineering support for temperature calibration cycles, while strapping systems require more predictable consumables replenishment schedules.
Product Type:
After-sales-service intensity varies sharply across product categories, with heat sealers commanding the highest technician deployment rates due to thermal element degradation and seal-bar alignment protocols.
- Heat Sealers:Thermal impulse and continuous band systems bond films through controlled temperature and pressure cycles, achieving hermetic seals for medical trays and food pouches. German pharmaceutical packaging clusters in Baden-Württemberg drive premium demand for validated cleanroom-compatible units with IQ/OQ/PQ documentation packages.
- Adhesive Applicators:Hot-melt and cold-glue dispensing systems apply thermoplastic or water-based adhesives to corrugated cases and folding cartons. E-commerce fulfillment centers in the United Kingdom prioritize these for high-speed carton sealing where tape aesthetics matter less than throughput.
- Strapping Machines:Polypropylene and steel band tensioning systems secure palletized loads and heavy parcels for logistics networks.
- Banding Machines:Paper and film banding systems apply decorative or functional wraps around product bundles for retail presentation.
By volume, heat sealers lead. By growth pace, adhesive applicators are gaining share fastest in e-commerce corridors.
Technology:
Capital deployment thresholds stratify procurement patterns, with automatic systems requiring dedicated facility infrastructure and semi-automatic units accommodating flexible floor layouts.
- Automatic:Servo-driven systems with programmable logic controllers execute format changes without manual intervention, operating at 200-600 cycles per minute. Coca-Cola bottlers in Spain deploy these for rotary sealing applications where changeover speed directly impacts line utilization rates.
- Semi-Automatic:Operator-fed systems combine motorized sealing action with manual product loading, balancing throughput against capital constraints. Contract packagers in California's wine corridor favor these for seasonal volume spikes where full automation cannot be amortized.
- Manual:Foot-pedal or handheld systems serve micro-batch operations and prototype packaging lines.
- Low-Speed:Entry-level electric sealers target emerging market small manufacturers with basic tray sealing requirements.
Automatic technology commands the largest installed base. Semi-automatic systems are climbing the fastest in contract packaging applications.
End User:
Regulatory compliance burdens concentrate in pharmaceutical and food segments, where validation documentation and washdown specifications extend sales cycles.
- Food Packaging:Tray lidding, flow-wrap, and vacuum sealing systems preserve shelf stability for fresh and processed goods. French dairy processors under EU Green Deal extended producer responsibility mandates are retrofitting lines for paper-compatible heat profiles.
- Pharmaceuticals:Containment-grade sealing systems with isolator integration protect sterile fill-finish operations. FDA cGMP track-and-trace regulations drive validated equipment upgrades at United States sterile manufacturing facilities.
- E-Commerce:Carton sealing and void-fill integration systems reduce damage claims in last-mile logistics networks.
- Household Products:Detergent and cleaning supply packaging lines prioritize chemical resistance in sealing surfaces.
Food packaging leads by volume. E-commerce is expanding most quickly as parcel volumes force automation investments.
Material:
Material compatibility requirements are reshaping equipment specifications as sustainability mandates accelerate substrate transitions.
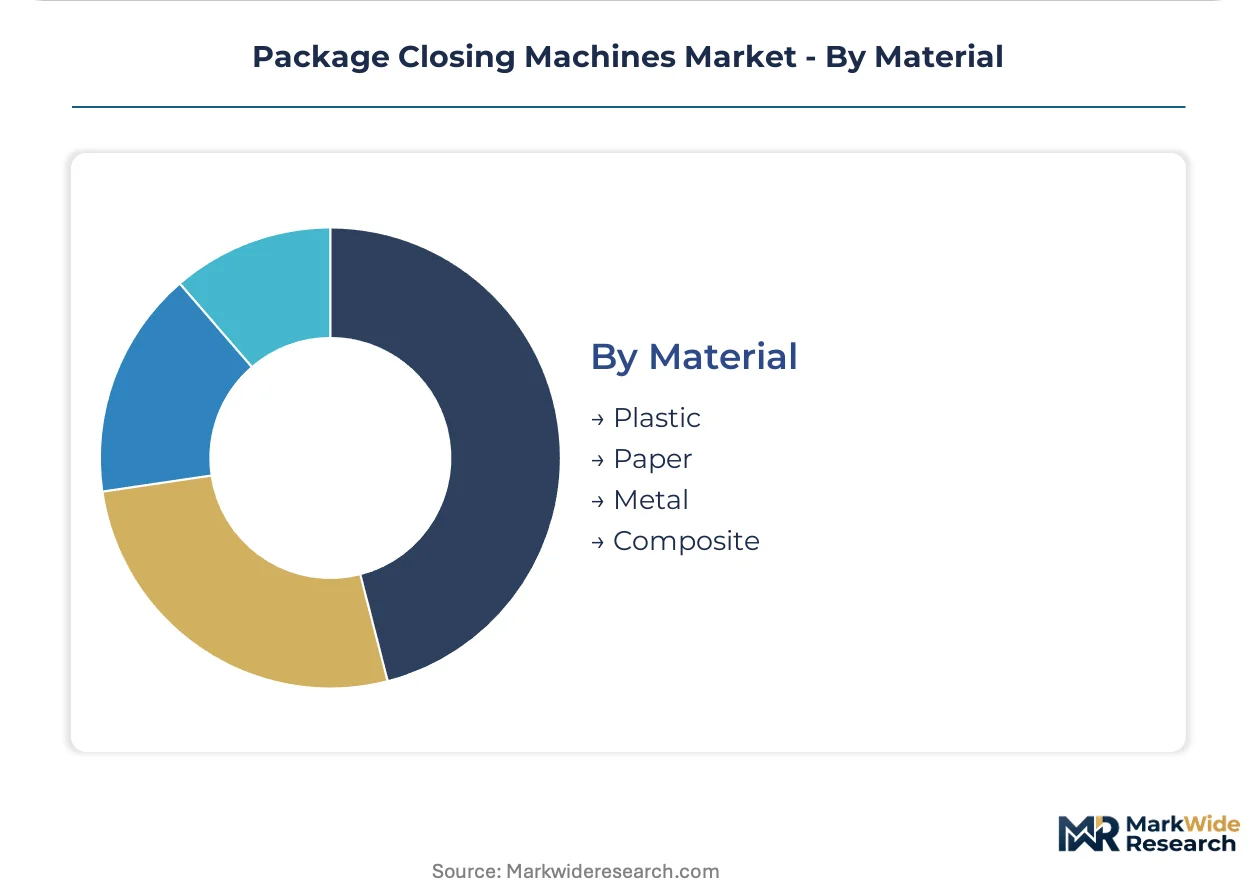
- Plastic:Polyethylene, polypropylene, and polyester films dominate flexible packaging applications with established heat-sealing protocols. Brazilian food processors anticipate ANVISA sustainable packaging guidelines by piloting PLA-compatible sealing profiles on existing equipment.
- Paper:Kraft and coated paper substrates require modified heat profiles and pressure dwell times for fiber-based sealing. German packaging machinery OEMs are engineering servo-controlled sealing heads with adjustable temperature ramps for paper tray lidding.
- Metal:Tinplate and aluminum can ends demand rotary seaming technology for beverage and food canning lines.
- Composite:Multi-layer barrier structures combining plastic, aluminum, and paper require precision sealing to maintain functional layer integrity.
Plastic leads by volume. Paper is climbing the fastest as EU packaging waste directives accelerate substrate transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract packagers and e-commerce fulfillment operators concentrate procurement authority across four national markets. Equipment specification power tilts toward German food machinery clusters and United States sterile manufacturing corridors.
Germany
Baden-Württemberg pharmaceutical packaging clusters drive premium demand for validated cleanroom-compatible heat sealers with IQ/OQ/PQ documentation. The EU Machinery Directive's 2023 software safety update forces control system revalidations across exported equipment. Bavarian dairy processors under extended producer responsibility mandates retrofit lines for paper-compatible sealing profiles.
United States
FDA cGMP track-and-trace regulations compel sterile fill-finish facilities to upgrade validated washdown machines. California wine and specialty food contract packagers favor equipment-as-a-service arrangements over capital purchases for seasonal flexibility. Third-party logistics providers deploy void-fill integrated closing stations to reduce damage claims in last-mile networks.
China
Dual carbon goals accelerate servo-driven motion control adoption to replace pneumatic systems in beverage canning operations. Yangtze River Delta packaging machinery OEMs engineer adjustable temperature ramp sealing heads for fiber-based tray lidding. The national pharmaceutical regulator enforces serialization requirements at sterile manufacturing sites.
India
CDSCO's phased manufacturing program attracts multinational pharma packaging investments to Ahmedabad and Hyderabad clusters. Contract packaging expansion in Maharashtra drives demand for semi-automatic systems balancing throughput against capital constraints. FSSAI food safety regulations extend equipment validation timelines for export-oriented processors.
Brazil
ANVISA advances sustainable packaging guidelines that create unserved demand for PLA and PHA-compatible heat profiles. São Paulo food processors pilot biodegradable film sealing on existing equipment to anticipate regulatory mandates. The country's agricultural export corridor drives tray lidding automation for protein packaging.
Package Closing Machines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Beverage packaging heritage firms leverage rotary sealing expertise against pharmaceutical-grade containment specialists. The structure rewards servo engineering capabilities and cleanroom validation documentation. Strategic moves concentrate on M&A for geographic footprint and technology licensing for motion control IP.
Within the heritage-tier, Tetra Pak and Krones AG occupy positions shaped by decades of liquid food and beverage packaging lineage. Syntegon Technology GmbH exemplifies the pharmaceutical-specialist archetype through its cleanroom-compatible design focus. Among diversified industrial conglomerates, GEA Group Aktiengesellschaft represents the scale-driven approach to packaging machinery portfolios.
| Leading Market Players |
|---|
| Tetra Pak |
| Krones AG |
| Coesia S.p.A. |
| Barry-Wehmiller |
| Syntegon Technology GmbH |
| Multivac Sepp Haggenmüller |
| ProMach, Inc. |
| Bosch Packaging Technology |
| GEA Group Aktiengesellschaft |
| Others |
Value Network & Pricing Analysis
Overcapacity in European stainless steel fabrication is compressing margin buffers for German and Italian OEMs while simultaneously accelerating equipment-as-a-service adoption among North American co-packers seeking to convert capital expenditure into operational flexibility.
Pricing Analysis
Cost-plus contracts indexed to nickel futures and 304-grade stainless steel spot markets dominate procurement between European fabricators and pharmaceutical packaging clusters. Three-tier pricing structure across premium, standard, and economy levels separates validated cleanroom-compatible units with IQ/OQ/PQ documentation from basic heat sealers and entry-level strapping systems. Cost compression in mid-tier automatic systems is intensifying because Japanese and German servo motor suppliers have extended lead times to 16 weeks. Contract packaging operators in California's wine corridor exhibit the highest price sensitivity due to seasonal volume spikes that prevent full automation amortization.
Supply Chain Analysis
Upstream feedstock for precision motion control components concentrates among Japanese and German suppliers, with servo motors and programmable logic controllers drawing from concentrated engineering bases in Nagoya and Stuttgart. Raw material dependencies span 304-grade stainless steel for washdown frames, nickel-copper alloys for thermal elements, and specialized polymers for conveyor belts. Single-source vulnerability in servo motor supply exposes OEMs to production line disruptions when semiconductor foundry capacity tightens. Distribution runs through direct sales forces for pharmaceutical-grade equipment and third-party machinery distributors for standard food packaging systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the package closing machines market creates multiple niche opportunities as EU Green Deal mandates force substrate transitions that incumbent vendors cannot serve uniformly from existing platforms.
For Market Incumbents: Entrench pharmaceutical-grade validation capabilities as the primary defensive moat against emerging Asian competitors. Deepen backward integration into servo engineering to reduce exposure to 16-week lead time extensions from Japanese suppliers. Acquire regional service networks in India to capture CDSCO-driven contract packaging expansion in Ahmedabad and Hyderabad. For New Entrants and Emerging Players: Build out biodegradable film sealing expertise to capture unserved demand as Brazil's ANVISA advances sustainable packaging guidelines. Target semi-automatic equipment segments in Maharashtra where multinational pharma packaging investments face capital constraints. Lead with equipment-as-a-service arrangements that bundle predictive maintenance and consumables to differentiate from incumbent capital-sales models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with installed base predictive maintenance platforms and per-unit sealing fee structures. Long-term viability hinges on servo engineering capabilities and cleanroom validation documentation that pharmaceutical serialization requirements make non-substitutable. Watch for inflection when extended producer responsibility laws in multiple jurisdictions trigger retrofit demand waves for paper-compatible sealing profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Engineering | In-house motion control development at Krones AG and Syntegon reduces lead time vulnerability from Japanese suppliers. |
| Equipment-as-a-Service Launch | Per-unit sealing fee models in California's wine corridor convert seasonal volume spikes into recurring revenue streams. |
| Paper-Compatible Sealing Platform Development | Adjustable temperature ramp heads engineered by German OEMs capture EU Green Deal-driven retrofit demand from French dairy processors. |
| Predictive Maintenance Platform Deployment | Vibration sensor and machine-learning integration creates aftermarket revenue from existing installed bases at pharmaceutical facilities. |
| Regional Service Network Acquisition | Local technician presence in Ahmedabad and Hyderabad captures CDSCO-driven multinational pharma packaging investments. |
Research Methodology
A standing panel of packaging line engineers, pharmaceutical manufacturing directors, contract packaging procurement leads, and aftermarket service technicians provided ongoing calibration across the study period. Primary interview data combined with secondary validation from FDA cGMP guidance documents, EU Machinery Directive regulatory filings, SEC 10-K disclosures from listed machinery OEMs, and customs trade data for packaging machinery imports. Bottom-up equipment shipment analysis triangulated against top-down pharmaceutical and food packaging capital expenditure surveys.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, automation technology level, end-use industry, and material compatibility requirements. CAGRs derived from installed base growth rates, replacement cycle analysis, and greenfield capacity announcements in e-commerce fulfillment corridors. Industry-specific forecast inputs included servo motor supply lead times and extended producer responsibility law implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese Yangtze River Delta OEMs or accelerated biodegradable film sealing adoption would shift outcomes beyond modeled ranges. Cross-checking against pharmaceutical capital expenditure surveys and food packaging machinery trade association shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Sack Filling Machine Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Tubular Form Fill and Seal Machines Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Pillow Packing Machine Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
North America Printing Machinery Market