
 Royal Jelly Market | 2026-2036
Royal Jelly Market Size, Share, and Industry Trends Forecast 2026-2036
Royal Jelly Market Analytics
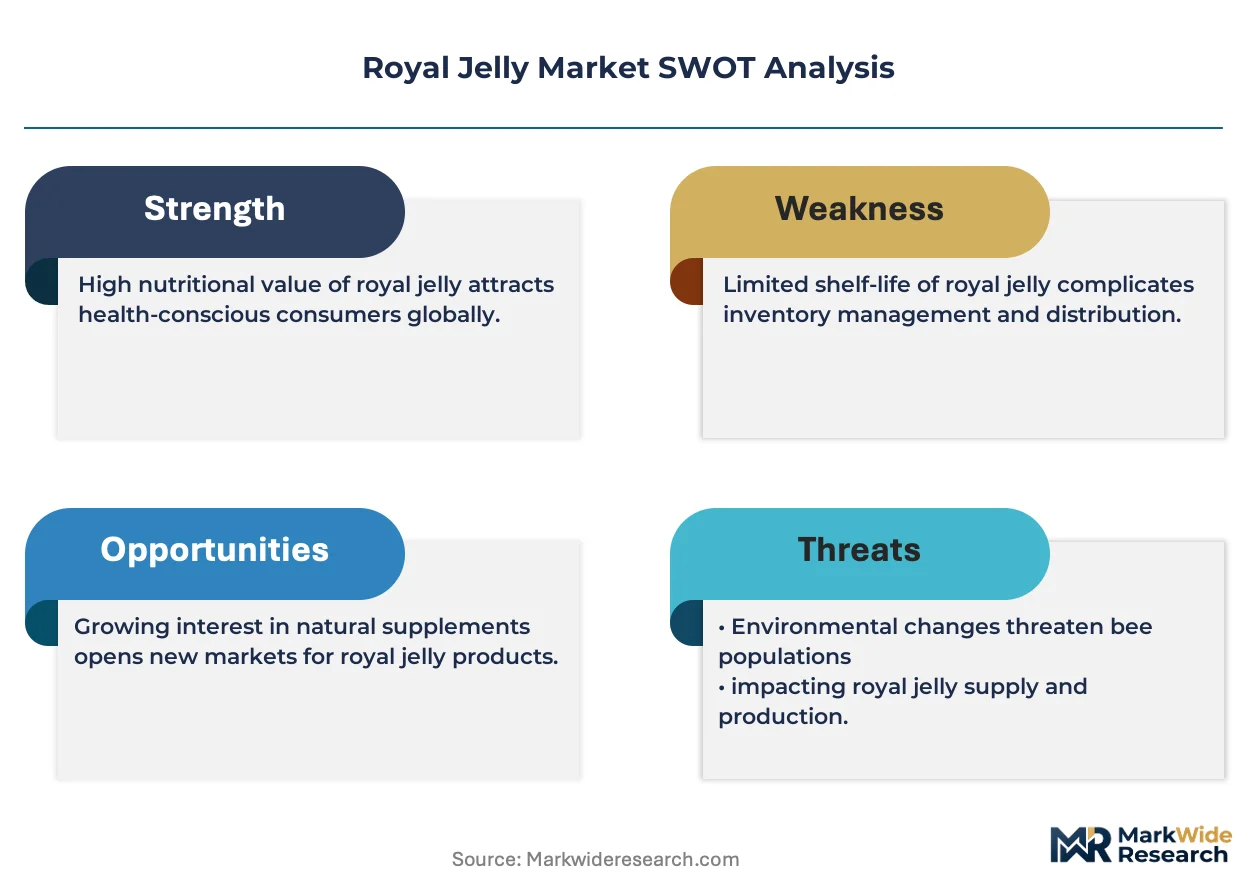
Specialty store distribution is narrowing as e-commerce platforms capture premium supplement buyers. Y.S. Organic Bee Farms leverages direct-to-consumer apiary sourcing to sustain margin control across North American markets. Durham's Bee Farm anchors its position through vertical integration from hive to capsule, while Yamada Bee Farm competes on freeze-drying technology leadership originating from Japan's Gunma Prefecture.
Royal jelly constitutes a secretion from the hypopharyngeal and mandibular glands of worker honeybees, containing 10-hydroxy-2-decenoic acid, proteins, and B-complex vitamins at concentrations that vary by larval feeding stage. This substance serves as exclusive nutrition for queen bees and now functions as a bioactive ingredient in human dietary supplements and cosmeceuticals. Organic royal jelly commands premium shelf positioning due to certification complexity and limited apiary scale, while liquid formulations retain volume leadership in East Asian traditional medicine channels. The nutraceutical end-user segment draws fastest growth from immune-modulation positioning, whereas cosmetics applications concentrate margin pools in Korean and Japanese skincare supply chains.
FDA dietary supplement cGMP enforcement and EU EFSA novel food assessments shape product standardization requirements for import eligibility. China's NMPA and GB standards for bee products impose residue limits that filter small-scale exporters from pharmaceutical-grade supply chains. Japan's Ministry of Health, Labour and Welfare maintains positive list systems for functional food claims that restrict marketing language around royal jelly's hormonal properties. Stakeholders must monitor evolving novel food classifications across jurisdictions to anticipate reformulation costs and market access barriers.
Market Dynamics
Regulatory fragmentation across FDA, EFSA, and NMPA jurisdictions is compressing formulation windows and forcing dual-track compliance investments from nutraceutical suppliers seeking multi-region shelf placement.
Growth Catalysts
- EFSA Novel Food Assessments:Harmonized safety benchmarks across EU member states reduce redundant testing costs for freeze-dried royal jelly exporters seeking pan-European distribution.
- Functional Gummy Formulation:Confectionery-grade encapsulation technologies mask royal jelly's bitter profile, expanding addressable demand beyond traditional capsule buyers into pediatric and geriatric segments.
- China:State-backed apiculture modernization programs consolidate fragmented hive operations, improving batch consistency for pharmaceutical-grade 10-HDA extraction.
Market Restraints
- Input Cost Volatility:Climate-induced nectar flow variability in Ukraine and Argentina elevates bee feed supplementation costs, compressing apiary margins upstream.
- Substitution Threat:Synthetic 10-HDA fermentation from engineered yeast strains offers cost-advantaged alternatives for cosmetic formulators less sensitive to natural-origin claims.
- Regulatory Friction:Japan's Ministry of Health, Labour and Welfare positive list systems restrict hormonal marketing claims, limiting premium positioning in functional food channels.
Strategic Opportunities
- Vietnam:Underpenetrated traditional medicine distribution networks present first-mover advantages for liquid royal jelly positioned alongside existing honey and propolis SKUs.
- Regulatory Tailwind:China's dual carbon goals incentivize organic certification adoption, creating margin premiums for apiaries achieving GB/T 19630 compliance.
- Direct-to-Consumer Subscription:Recurring revenue models bypass pharmacy retail slotting fees, capturing lifetime value from immune-conscious households in South Korea.
Industry Challenges
- Lyophilization Technician Scarcity:Specialized freeze-drying expertise for heat-sensitive protein preservation concentrates among Japanese and German equipment operators, elevating labor costs.
- Organic Certification Timelines:Three-year conversion periods for conventional apiaries block rapid capacity scaling to meet surging certified demand from German pharmacy chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Royal Jelly Market |
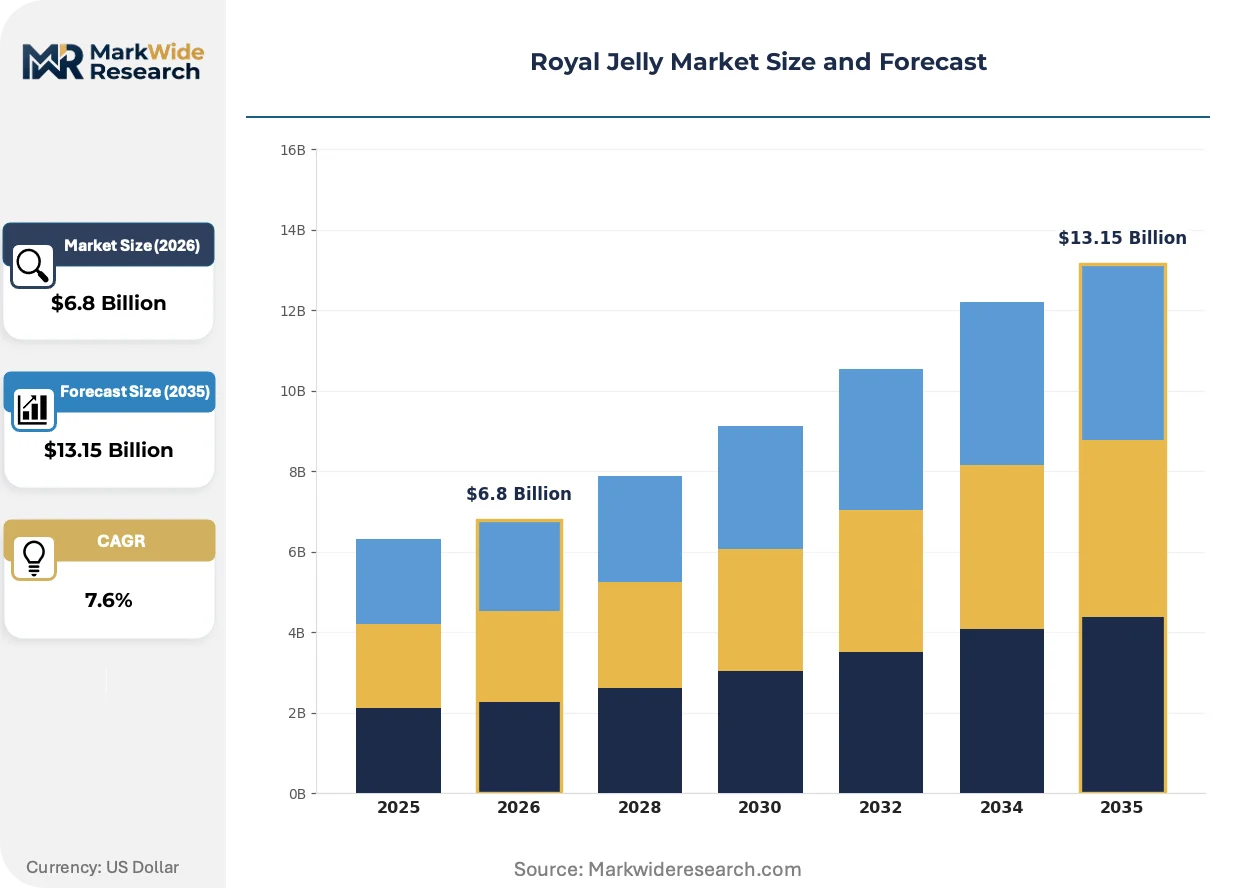
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Royal Jelly, Freeze-Dried Royal Jelly, Powdered Royal Jelly, Liquid Royal Jelly End User: Healthcare, Cosmetics, Nutraceuticals, Food & Beverage Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Form: Capsules, Tablets, Syrups, Smoothies |
| Companies Covered | Y.S. Organic Bee Farms, NOW Foods, Durham's Bee Farm, Nestlé S.A., Swanson Health Products, NaturaNectar, Golden Hive, Yamada Bee Farm, Source Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Royal Jelly Market Evolving Landscape
Processing technology convergence with blockchain traceability and AI-driven hive monitoring is compressing quality assurance cycles while opening new premium positioning vectors for origin-verified supply chains.
Blockchain-based apiary-to-capsule traceability platforms is digitizing provenance documentation for royal jelly batches, enabling real-time 10-HDA potency verification. Premium supplement buyers in Switzerland and Singapore now mandate this transparency layer. The technology is compressing audit cycles from quarterly to continuous, forcing mid-tier suppliers into compliance investments or private-label retreat.
EU EFSA novel food guidance updates are tightening residue limit documentation for imported bee products, requiring expanded chromatography testing from third-country exporters. Chinese suppliers face particular scrutiny on chloramphenicol and nitrofuran detection thresholds. Pharmaceutical-grade segments are responding by captive sourcing from EU-registered apiaries, bifurcating supply chains into compliant and commodity tiers.
Specialty store buyers are consolidating procurement authority into centralized category managers, displacing fragmented regional purchasing that previously accommodated smaller freeze-dry operators. This concentration favors suppliers with ISO 22000 certification and multi-language labeling capabilities. The shift is most visible in France and Italy, where pharmacy chains now demand single-SKU pan-European supply agreements.
Royal Jelly Market Segmentation
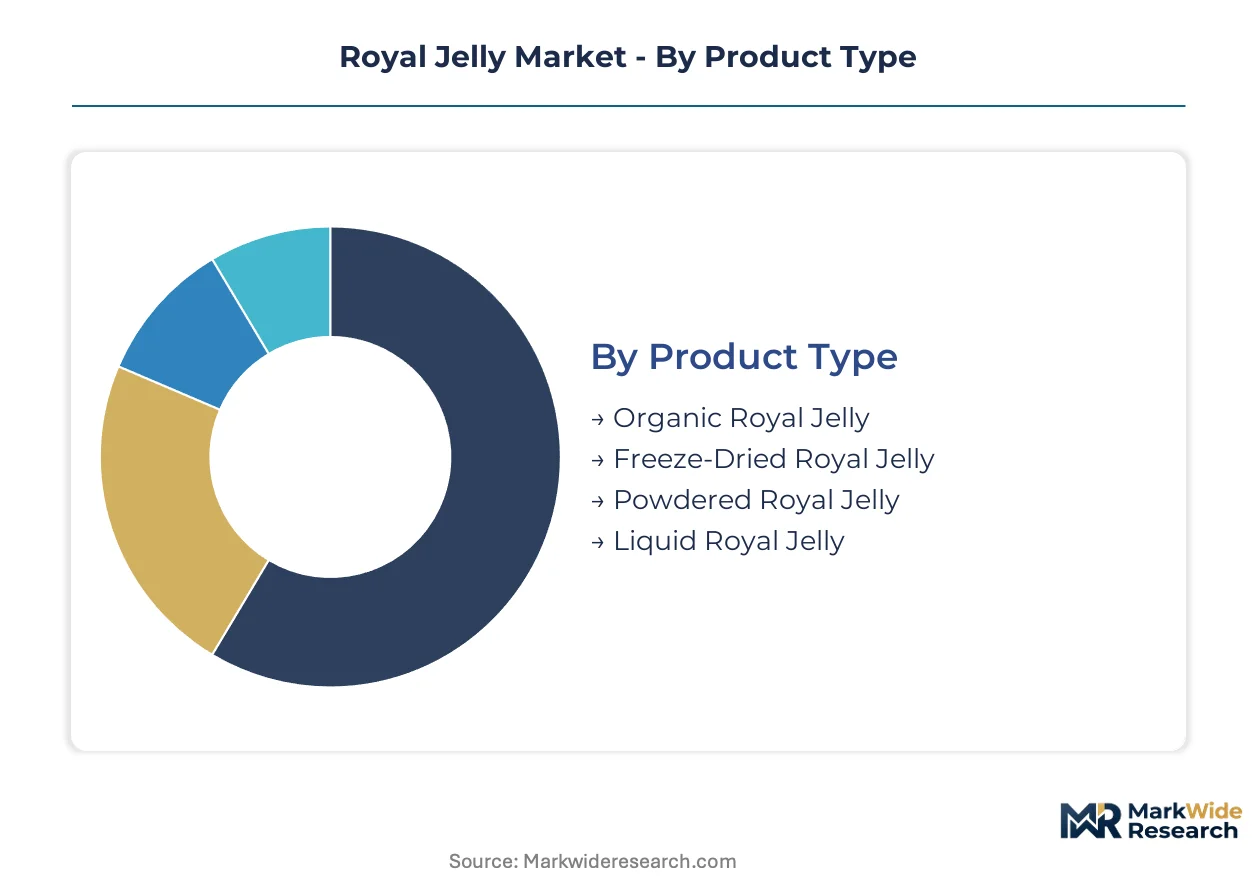
Royal jelly segmentation reflects divergent technical requirements across pharmaceutical extraction, cosmetic formulation, and traditional medicine channels. Each category carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning.
Product Type:
After-sales service intensity varies sharply across product types, with freeze-dried and organic variants demanding specialized storage guidance and potency verification protocols that liquid formulations rarely require.
- Organic Royal Jelly:Certification under EU Organic Regulation and China's GB/T 19630 standard requires three-year apiary conversion timelines and residue testing protocols. German pharmacy chains and Japanese department stores command premium shelf positioning for certified batches, though limited hive scale constrains volume expansion.
- Freeze-Dried Royal Jelly:Lyophilization preserves heat-sensitive 10-HDA and protein fractions at concentrations exceeding 6%. Japanese equipment manufacturers in Gunma Prefecture dominate technical supply, while Swiss and Singaporean buyers now mandate blockchain-verified potency documentation for pharmaceutical-grade procurement.
- Powdered Royal Jelly:Spray-dried variants suit mass-market capsule production with lower unit economics.
- Liquid Royal Jelly:Traditional medicine channels in China and Vietnam favor this format for direct consumption and compounding.
Freeze-dried royal jelly holds the largest share; momentum sits with organic certification as dual carbon goals reshape Chinese apiary investment.
End User:
Cost tier differentiation separates pharmaceutical-grade extraction from commodity cosmetic sourcing, with 10-HDA concentration thresholds determining qualification for each tier.
- Nutraceuticals:Functional gummy and immune-support formulations drive fastest expansion as encapsulation technologies mask bitterness for pediatric and geriatric segments. South Korean subscription models bypass pharmacy slotting fees.
- Cosmetics:Korean and Japanese skincare supply chains concentrate margin pools around anti-aging serums, with synthetic 10-HDA fermentation emerging as cost-advantaged alternative for natural-origin-insensitive formulators.
- Healthcare:TCM practitioners and integrative medicine clinics prescribe liquid royal jelly for fatigue and hormonal support protocols.
- Food & Beverage:Honey blends and functional beverages incorporate royal jelly at lower concentrations for accessibility positioning.
Nutraceuticals holds the largest share; cosmetics applications are climbing the fastest as Korean skincare exports expand.
Distribution Channel:
Volume concentration favors direct-to-consumer platforms that capture immune-conscious households, while specialty stores narrow procurement authority into centralized category managers.
- Online Retail:E-commerce platforms capture premium supplement buyers through subscription models and apiary-to-capsule traceability marketing. Y.S. Organic Bee Farms leverages direct sourcing to sustain margin control across North American markets.
- Direct Sales:Apiary-owned channels bypass distributor markups for pharmaceutical-grade batches, particularly in Japan's functional food sector where positive list restrictions limit conventional retail claims.
- Supermarkets:Mass-market penetration remains limited to honey-blend SKUs with lower royal jelly concentrations.
- Specialty Stores:Pharmacy chains in France and Italy now demand single-SKU pan-European supply agreements with ISO 22000 certification.
Online retail holds the largest share; direct sales channels are gaining share fastest as traceability premiums reshape buyer preferences.
Form:
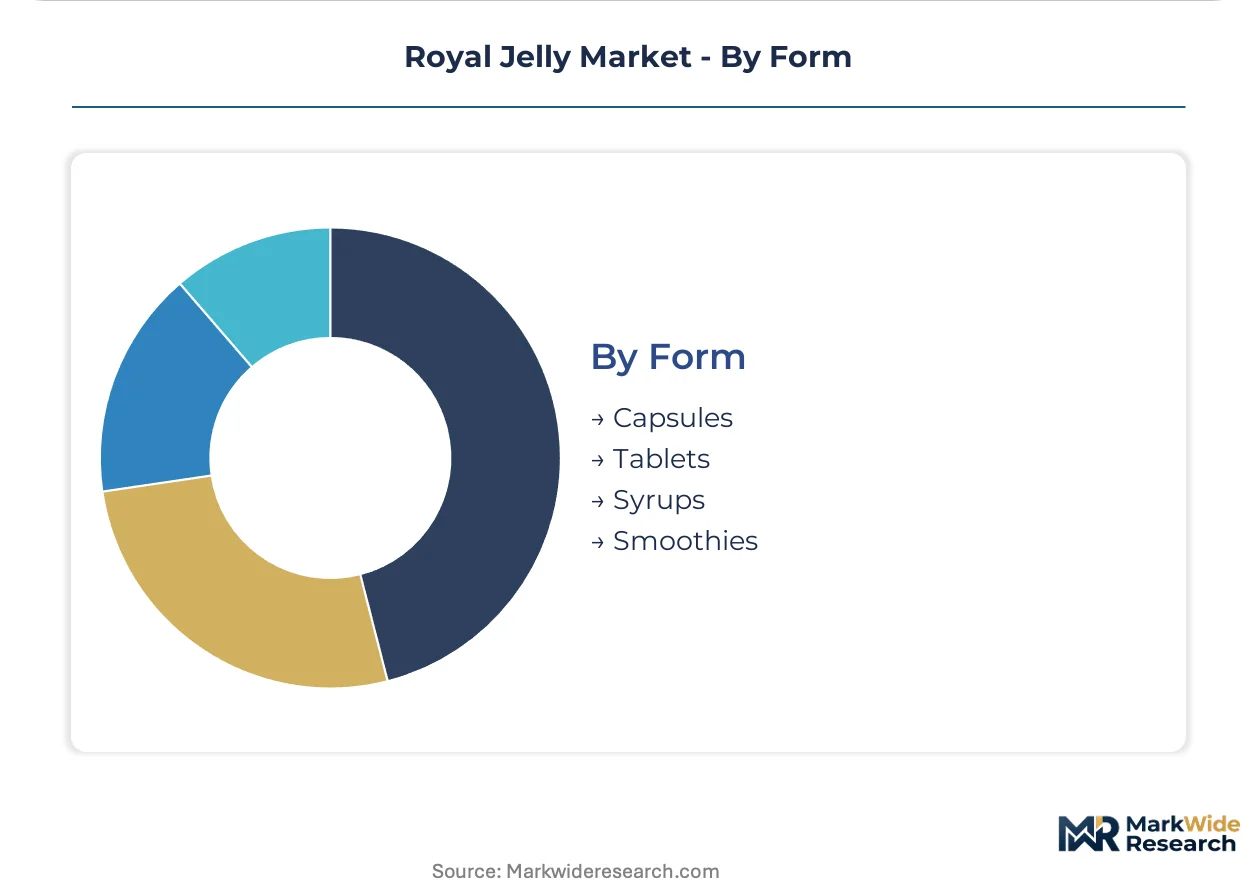
Application requirements dictate form selection, with capsule stability contrasting syrup preservation challenges in humid climates.
- Capsules:Enteric-coated variants protect gastric acid degradation for pharmaceutical-grade positioning. Durham's Bee Farm anchors supply through captive hive-to-capsule integration.
- Syrups:Traditional medicine channels in Vietnam and southern China favor this format for compounding flexibility and taste masking with honey bases.
- Tablets:Compressed formulations suit mass-market supplement positioning with extended shelf stability.
- Smoothies:Ready-to-drink functional beverages target convenience-oriented urban consumers in South Korea and Japan.
Capsules hold the largest share; syrups show steepest expansion trajectory as Vietnamese traditional medicine networks deepen penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium shelf positioning in Japanese pharmacy chains commands unit economics that Argentine apiaries cannot approach, creating a pricing-power asymmetry that reshapes investment flows across hemispheres.
China
State-backed apiculture modernization consolidates fragmented hive operations around Shandong and Zhejiang provinces for pharmaceutical-grade 10-HDA extraction. NMPA residue limits under GB standards filter small-scale exporters from premium supply chains. The Yangtze River Delta anchors captive sourcing investments by nutraceutical formulators seeking batch consistency.
Japan
Functional food positioning drives demand for freeze-dried variants with verified potency documentation. METI and the Ministry of Health, Labour and Welfare maintain positive list systems that restrict hormonal marketing claims, compressing formulation windows for immune-modulation products. Gunma Prefecture equipment manufacturers dominate lyophilization technical supply for regional processors.
Germany
Pharmacy chain procurement consolidation under centralized category managers demands ISO 22000 certification and multi-language labeling for pan-European supply agreements. EU Organic Regulation certification requirements impose three-year apiary conversion timelines that constrain rapid capacity scaling. Bavarian distributors now mandate blockchain traceability for origin-verified batches.
United States
Direct-to-consumer subscription models bypass pharmacy retail slotting fees to capture lifetime value from immune-conscious households. FDA dietary supplement cGMP enforcement tightens purity benchmarks for import eligibility, elevating compliance costs for third-country suppliers. Pacific Northwest apiary operations leverage direct sourcing to sustain margin control against mass-market competitors.
Vietnam
Underpenetrated traditional medicine distribution networks present first-mover positioning for liquid royal jelly alongside existing honey and propolis SKUs. The country's national food safety regulator imposes emerging residue documentation requirements that favor early entrants with established testing protocols. Ho Chi Minh City trading houses are consolidating procurement authority for export-grade batches.
Royal Jelly Market Competitive Landscape
Vertically integrated apiary operators and specialized freeze-dry technology providers split the market between margin-capture and technical-differentiation strategies. The vendor base concentrates among Japanese equipment-dependent processors, North American direct-to-consumer marketers, and Chinese state-consolidated suppliers. Three archetypes dominate: captive hive-to-capsule integrators, lyophilization technology licensors, and subscription-platform direct marketers. Competitive moves center on backward integration into apiary assets and geographic expansion through regulatory-compliant captive sourcing.
Among North American direct marketers, Y.S. Organic Bee Farms and Durham's Bee Farm exemplify the captive-sourcing archetype through apiary-owned channel strategies. Yamada Bee Farm occupies a position within the Japanese technology-tier, representing freeze-drying specialization originating from regional equipment clusters. These three anchors illustrate how geographic proximity to technical supply or consumer markets determines viable strategic positioning.
| Leading Market Players |
|---|
| Y.S. Organic Bee Farms |
| NOW Foods |
| Durham's Bee Farm |
| Nestlé S.A. |
| Swanson Health Products |
| NaturaNectar |
| Golden Hive |
| Yamada Bee Farm |
| Source Naturals |
| Others |
Value Network & Pricing Analysis
Gunma Prefecture's freeze-drying equipment cluster anchors pharmaceutical-grade lyophilization capacity, concentrating technical supply among Japanese processors who command premium pricing power over downstream nutraceutical formulators seeking verified 10-HDA potency documentation.
Pricing Analysis
The customization-premium spread separates blockchain-verified organic batches from commodity spray-dried powder. Three-tier pricing structure across premium freeze-dried, certified organic, and standard liquid formats reflects 10-HDA concentration thresholds and EU Organic Regulation compliance status. Cost compression in the standard tier is intensifying because Argentine apiaries face climate-induced nectar flow variability elevating bee feed supplementation costs. Pediatric gummy formulations show least price sensitivity due to encapsulation technology premiums, while mass-market honey-blend SKUs face greatest buyer resistance.
Supply Chain Analysis
Contract-manufacturing concentration sits with Gunma Prefecture lyophilization specialists and Shandong province state-consolidated apiaries. Geographic supply draws from China, Japan, and Argentina for raw royal jelly secretion, while freeze-drying equipment sources from German and Japanese precision manufacturers. Single-source vulnerability concentrates in 10-HDA testing chromatography supply chains facing EU EFSA novel food assessment documentation demands. Distribution runs through direct-to-consumer subscription platforms capturing immune-conscious households alongside consolidated pharmacy chain category managers in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as functional gummy encapsulation technologies mask royal jelly's bitter profile, unlocking pediatric and geriatric segments previously unreachable through traditional capsule formats.
For Market Incumbents:Pre-empt synthetic 10-HDA fermentation substitutes by accelerating captive apiary investments in China's Yangtze River Delta where state-backed modernization improves batch consistency. Secure ISO 22000 certification and blockchain traceability infrastructure before pharmacy chain procurement consolidation in Germany and Italy hardens entry barriers. Backward integration into hive assets remains the critical margin-defense lever against climate-induced input cost volatility.
For New Entrants and Emerging Players:Vietnam's underpenetrated traditional medicine distribution networks offer first-mover positioning for liquid royal jelly alongside existing honey and propolis SKUs. Target Ho Chi Minh City trading houses consolidating export-grade procurement authority before residue documentation requirements mature. A direct-sales model bypassing pharmacy slotting fees captures traceability premiums from immune-conscious households in South Korea.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with apiary-to-capsule traceability marketing, suggesting long-term viability across a 5-10 year window favors captive-sourcing archetypes over commodity traders. Acquisition targets should demonstrate GB/T 19630 organic certification progress or Gunma Prefecture lyophilization partnerships. The signal to monitor is EFSA novel food guidance tightening residue thresholds, which would accelerate bifurcation between compliant and commodity supply tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Implementation | Swiss and Singaporean buyers now mandate real-time 10-HDA potency verification for pharmaceutical-grade procurement. |
| Functional Gummy Formulation Launch | Confectionery-grade encapsulation technologies expand addressable demand beyond traditional capsule buyers into pediatric segments. |
| Captive Apiary Sourcing Investment | Y.S. Organic Bee Farms leverages direct-to-consumer apiary sourcing to sustain margin control across North American markets. |
| EU Organic Certification Pathway | German pharmacy chains command premium shelf positioning for EU Organic Regulation certified batches despite three-year conversion timelines. |
| Direct-to-Consumer Subscription Model | Recurring revenue platforms bypass pharmacy retail slotting fees to capture lifetime value from immune-conscious households in South Korea. |
Research Methodology
The analysis maps freeze-dried, organic, liquid, and powdered royal jelly sub-sectors, each validated through apiary operations managers, nutraceutical formulators, pharmacy chain category buyers, and lyophilization equipment technicians. Primary interviews combined with secondary validation from NMPA GB standards documentation, EU EFSA novel food assessments, FDA cGMP enforcement records, and Japanese Ministry of Health positive list systems. Bottom-up hive production estimates and top-down nutraceutical demand triangulation anchored market sizing.
Assumptions held fixed include regulatory classification stability across FDA, EFSA, and NMPA jurisdictions, while variables included climate-induced nectar flow variability and synthetic 10-HDA substitution rates. Segmentation dimensions modeled encompass product type, end-user application, distribution channel, and geographic regulatory cluster across the analysis window. CAGRs derived from compound growth trajectory analysis of immune-modulation positioning adoption and functional gummy penetration curves, with freeze-drying capacity expansion and organic certification timelines as industry-specific forecast inputs.
Practitioners should monitor EFSA novel food guidance updates, NMPA residue threshold revisions, and synthetic 10-HDA fermentation cost curves for early signals requiring forecast adjustment. Quarterly review of pharmacy chain procurement consolidation patterns and lyophilization technician labor market tightness is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Choline Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Natural Vitamin E Product Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market