
 Smart Lawn Robot Market | 2026-2036
Smart Lawn Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Lawn Robot Market Insights
Subscription-based leasing and robot-as-a-service models is fragmenting capital requirements across the competitive landscape. Husqvarna Group leverages its captive fleet-management platform to sustain recurring revenue streams. Deere & Company anchors its position through precision-agriculture technology spillover into residential turf management. Robert Bosch GmbH competes on sensor-integration density across its autonomous mower lineup.
Smart lawn robots are self-propelled outdoor automation systems integrating lithium-ion powertrains, perimeter-wire or GPS-based boundary mapping, and obstacle-avoidance arrays to execute turf cutting without human operation. Units typically operate at noise levels below 60 decibels and run on 18-40 volt battery architectures designed for sustained daily cycling across variable terrain. Autonomous mowers dominate installed base volumes while AI algorithm-enabled navigation systems capture disproportionate margin pools through software differentiation. Residential users anchor unit shipments, though commercial landscapers represent the fastest-growing end-user category as labor-cost pressures intensify across North American and European property-maintenance sectors.
The EU Machinery Directive and FCC Part 15 emissions standards in the United States constrain radio-frequency subsystem design and certification pathways for cross-border manufacturers. Japan's METI energy-efficiency labeling requirements shape battery-selection strategies for vendors targeting East Asian distribution. Stakeholders must monitor evolving battery-recycling mandates across multiple jurisdictions as these regulations will determine aftermarket service economics and product lifecycle obligations.
Market Dynamics
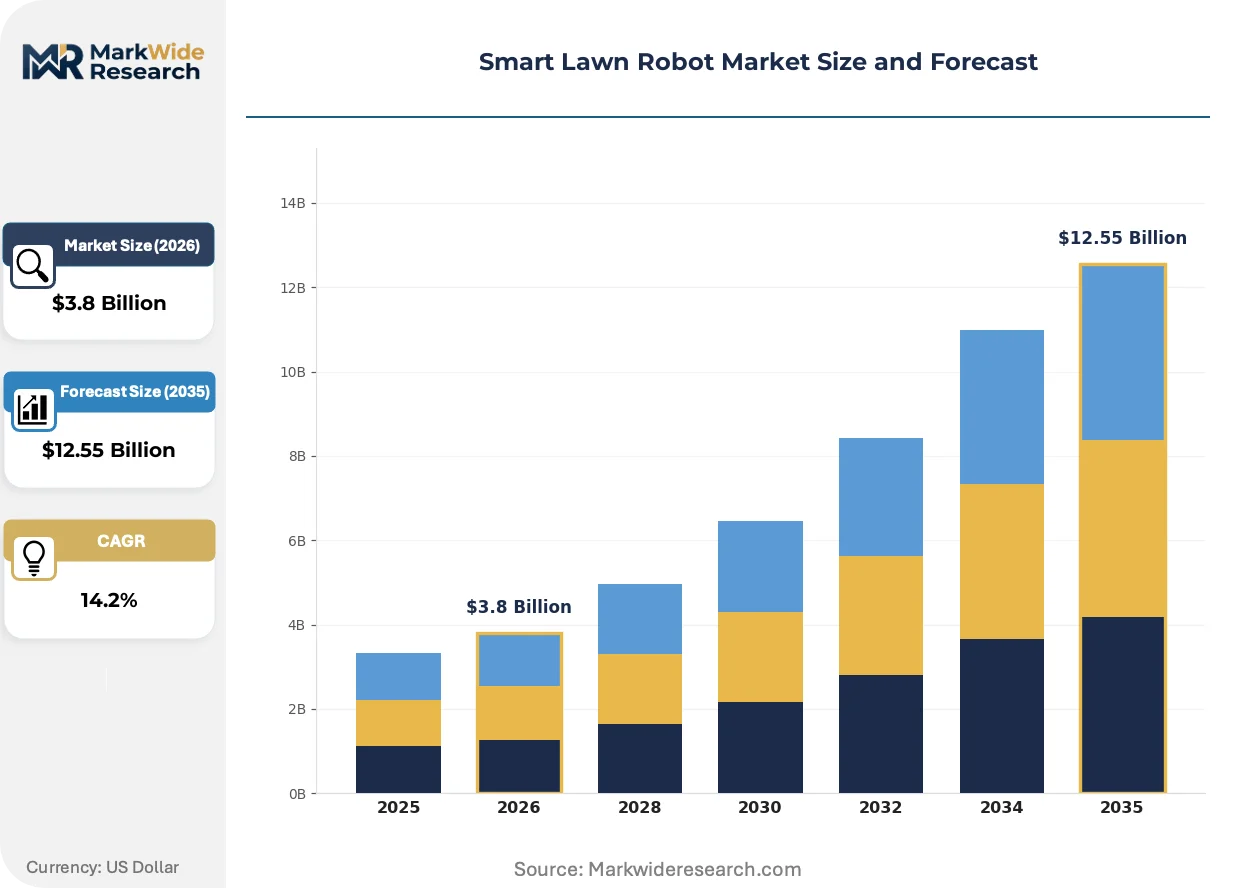
Subscription-based leasing models are fragmenting capital requirements across the competitive landscape, while the EU Green Deal's noise-reduction mandates accelerate battery-electric platform development and reshape vendor R&D priorities.
Growth Catalysts
- EU Machinery Directive compliance pathways:The directive's safety certification requirements for autonomous outdoor equipment create standardized entry barriers that favor established lithium-ion powertrain specialists with in-house testing facilities.
- Precision boundary mapping:GPS-RTK and vision-based navigation systems eliminate perimeter-wire installation costs, expanding addressable demand among rental property managers and estate maintenance contractors.
- Japan's suburban automation adoption:METI energy-efficiency labeling requirements shape battery-selection strategies, while aging demographics in Japanese prefectures drive residential outsourcing of turf maintenance to robotic systems.
Market Restraints
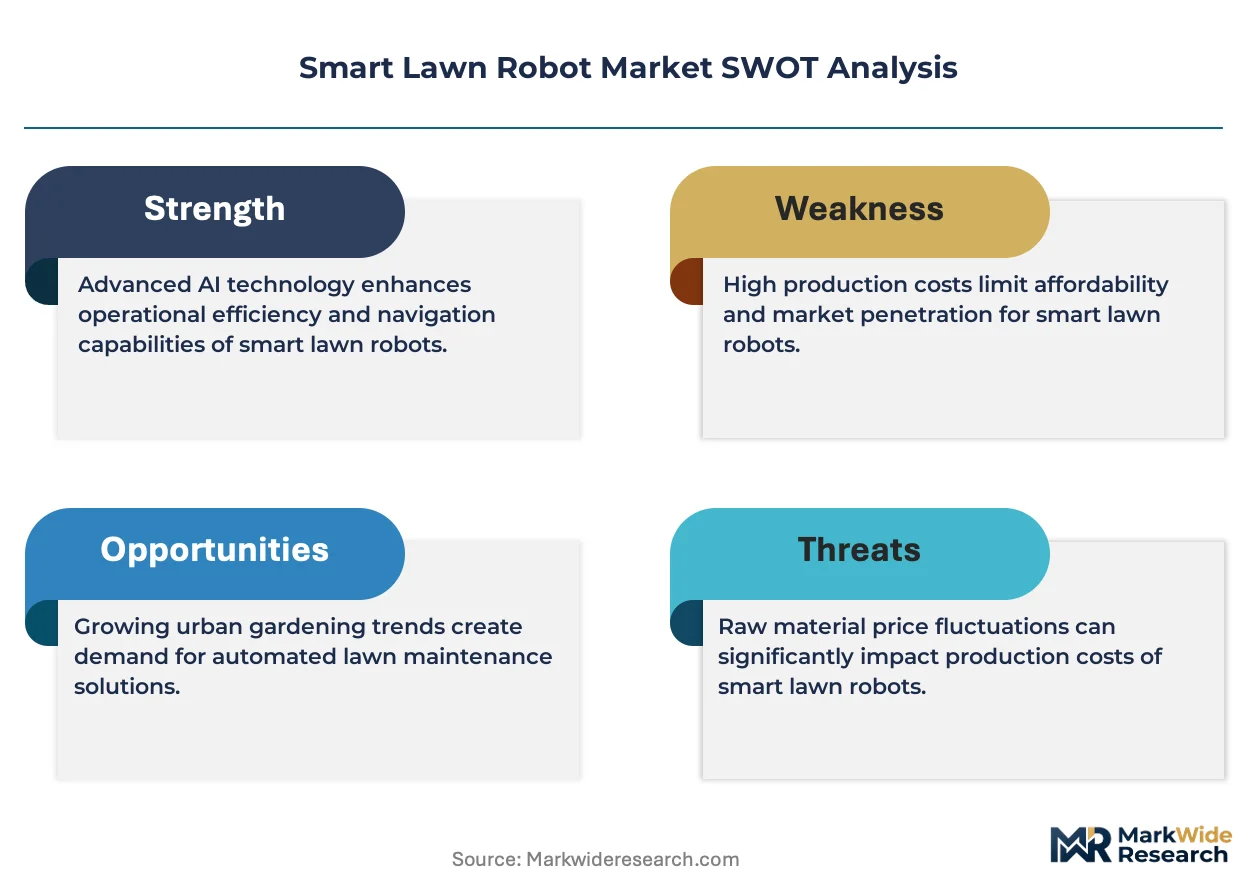
- Lithium-ion cell supply concentration:Cathode material processing and cell manufacturing cluster in East Asian supply chains, exposing vendors to freight cost volatility and geopolitical trade friction.
- Perimeter-wire legacy infrastructure:Existing installed bases of boundary-wire systems create switching costs for residential upgraders, slowing replacement cycles in mature European markets.
- FCC Part 15 emissions certification:Radio-frequency subsystem design constraints for cross-border manufacturers extend product development timelines and raise compliance expenditures for multi-jurisdiction launches.
Strategic Opportunities
- Commercial landscaper labor-cost pressures:North American property-maintenance sectors face wage inflation and seasonal workforce shortages, creating pull for fleet-scale autonomous mower deployments with centralized monitoring.
- Battery-recycling mandate preparation:Evolving extended producer responsibility frameworks across multiple jurisdictions will determine aftermarket service economics, rewarding vendors with closed-loop material recovery partnerships.
- Vision-LiDAR sensor fusion:Convergence of depth-sensing arrays with machine-learning obstacle classification enables operation in unstructured environments previously inaccessible to perimeter-dependent systems.
Industry Challenges
- Autonomy software talent scarcity:Robotics perception engineers and SLAM algorithm specialists command premium compensation, constraining mid-tier vendors' ability to match navigation performance of category leaders.
- Multi-jurisdiction certification timelines:Parallel FCC, CE marking, and METI approval processes delay product launches by 8-14 months, compressing effective sales windows within seasonal demand peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Lawn Robot Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Mowers, Robotic Trimmers, Hybrid Models, Solar-Powered Units Technology: GPS Navigation, Bluetooth Connectivity, AI Algorithms, Ultrasonic Sensors End User: Residential Users, Commercial Landscapers, Golf Courses, Parks Service Type: Installation Services, Maintenance Services, Warranty Support, Software Updates |
| Companies Covered | Husqvarna Group, Deere & Company, Robert Bosch GmbH, Honda Motor Co., Ltd., STIGA S.p.A., ANDREAS STIHL AG & Co. KG, The Toro Company, Stanley Black & Decker, Inc., Segway Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Lawn Robot Market Trends and Innovations
Navigation architectures are converging toward sensor-fusion approaches that reduce dependency on physical infrastructure, while regulatory pressure on noise and emissions accelerates platform electrification timelines.
RTK-GPS positioning systems are hybridizing with computer-vision boundary detection to eliminate perimeter-wire installation entirely. Estate managers and golf course operators are piloting these wire-free configurations during renovation cycles. The technology is hybridizing equipment procurement models by enabling seasonal rental deployments without permanent landscape modifications.
The EU Green Deal's push for emission-free outdoor equipment is compressing development timelines for battery-electric platforms. Manufacturers must now achieve sub-60-decibel operation and zero tailpipe emissions to access public procurement channels in German municipalities. Residential buyers in Benelux countries are responding by prioritizing certified low-noise models for suburban compliance.
Robot-as-a-service contracts are displacing capital purchase patterns among commercial landscaping fleets. Mid-sized property maintenance firms in the United States are subscribing to seasonal equipment access with bundled maintenance and software updates. This shift is most visible in Florida and Texas, where year-round mowing demand justifies continuous fleet utilization against fixed monthly fees.
Smart Lawn Robot Market Segmentation
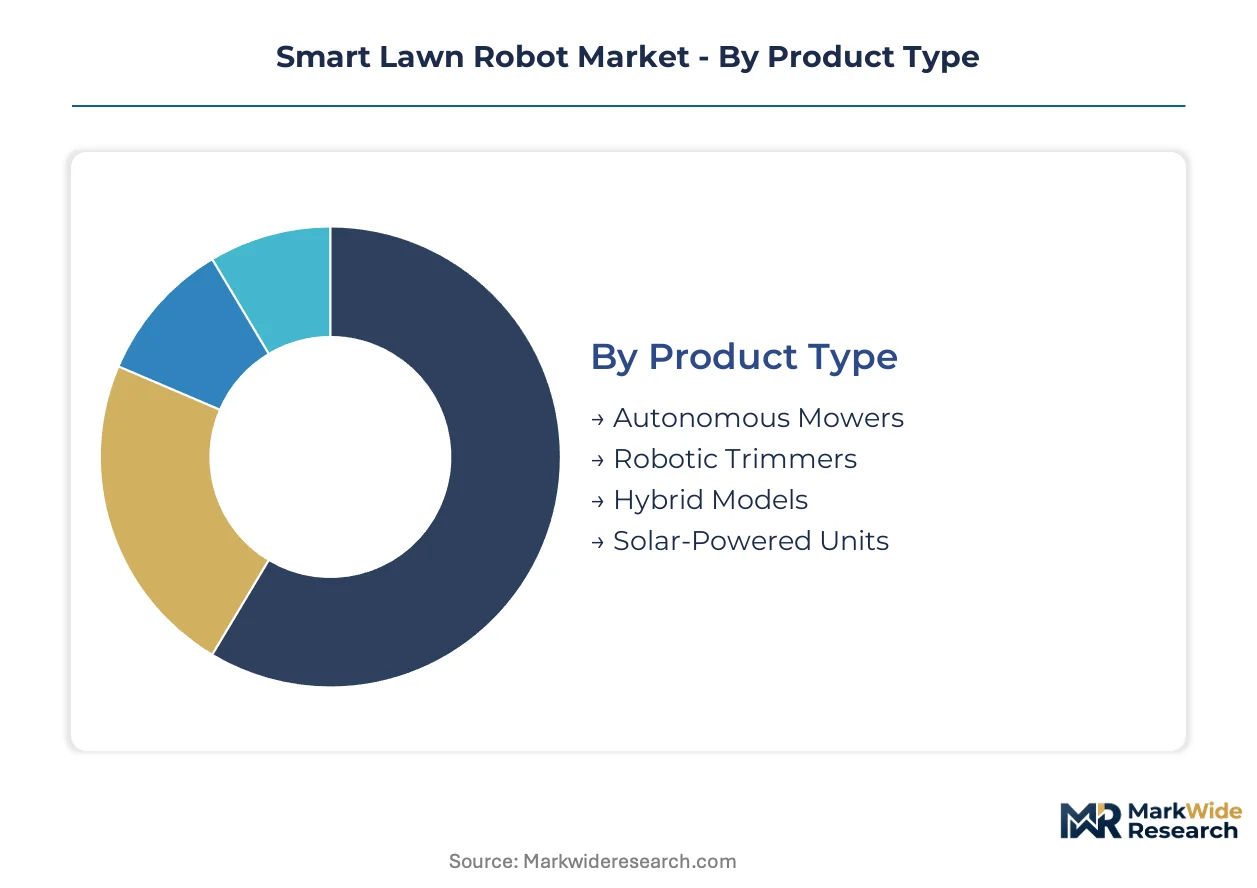
Segmentation reveals how capital deployment and replacement cycles vary across the smart lawn robot ecosystem. Product architecture determines hardware refresh rates while service attachment creates divergent revenue durability profiles among vendors.
Product Type:
Cycle times range from 3-5 years for battery-electric autonomous platforms to 7-10 years for solar-integrated mechanical systems with minimal electronic components.
- Autonomous Mowers:Self-propelled lithium-ion units with perimeter-wire or GPS-RTK navigation dominate current shipments. Residential estates in Germany and Japan drive replacement demand as first-generation wire-bound systems reach end-of-life.
- Robotic Trimmers:Edge-cutting and precision-trimming platforms address perimeter maintenance gaps left by standard mowers. Golf course superintendents in Florida and Texas are piloting these for bunker edge and collar maintenance where precision outweighs speed.
- Hybrid Models:Dual-powertrain systems combining battery storage with small combustion engines for extended runtime.
- Solar-Powered Units:Photovoltaic-integrated platforms targeting off-grid estates and sustainability-certified properties.
Autonomous mowers dominate installed base. Robotic trimmers are where expansion concentrates.
Technology:
Cost tiers separate navigation architectures, with sensor-fusion platforms commanding 40-60% price premiums over basic perimeter-wire systems.
- GPS Navigation:RTK-corrected positioning enables centimeter-accurate boundary mapping without physical wire installation. Commercial landscapers in the United States are adopting these for fleet-scale deployments across multiple properties.
- AI Algorithms:Machine-learning obstacle classification and terrain adaptation differentiate premium offerings. Japanese prefectures with aging demographics prioritize these systems for unsupervised residential operation.
- Bluetooth Connectivity:Short-range smartphone pairing for manual override and scheduling.
- Ultrasonic Sensors:Proximity detection arrays for basic obstacle avoidance in entry-level units.
GPS navigation anchors current revenue. AI algorithms represent the steepest expansion trajectory.
End User:
Application intensity varies sharply, with commercial operators running 2,000+ annual hours versus 300-500 hours for typical residential deployments.
- Residential Users:Single-family homeowners and estate managers purchasing 1-2 units for private turf maintenance. Suburban districts in Benelux countries are driving demand for sub-60-decibel certified models compliant with municipal noise ordinances.
- Commercial Landscapers:Fleet operators managing multiple properties under contract. Labor-cost pressures across North American property-maintenance sectors are accelerating robot-as-a-service adoption among mid-sized firms.
- Golf Courses:Precision turf management for fairways, collars, and rough areas.
- Parks:Municipal and regional green space maintenance operations.
Residential users dominate installed base. Commercial landscapers are gaining share fastest.
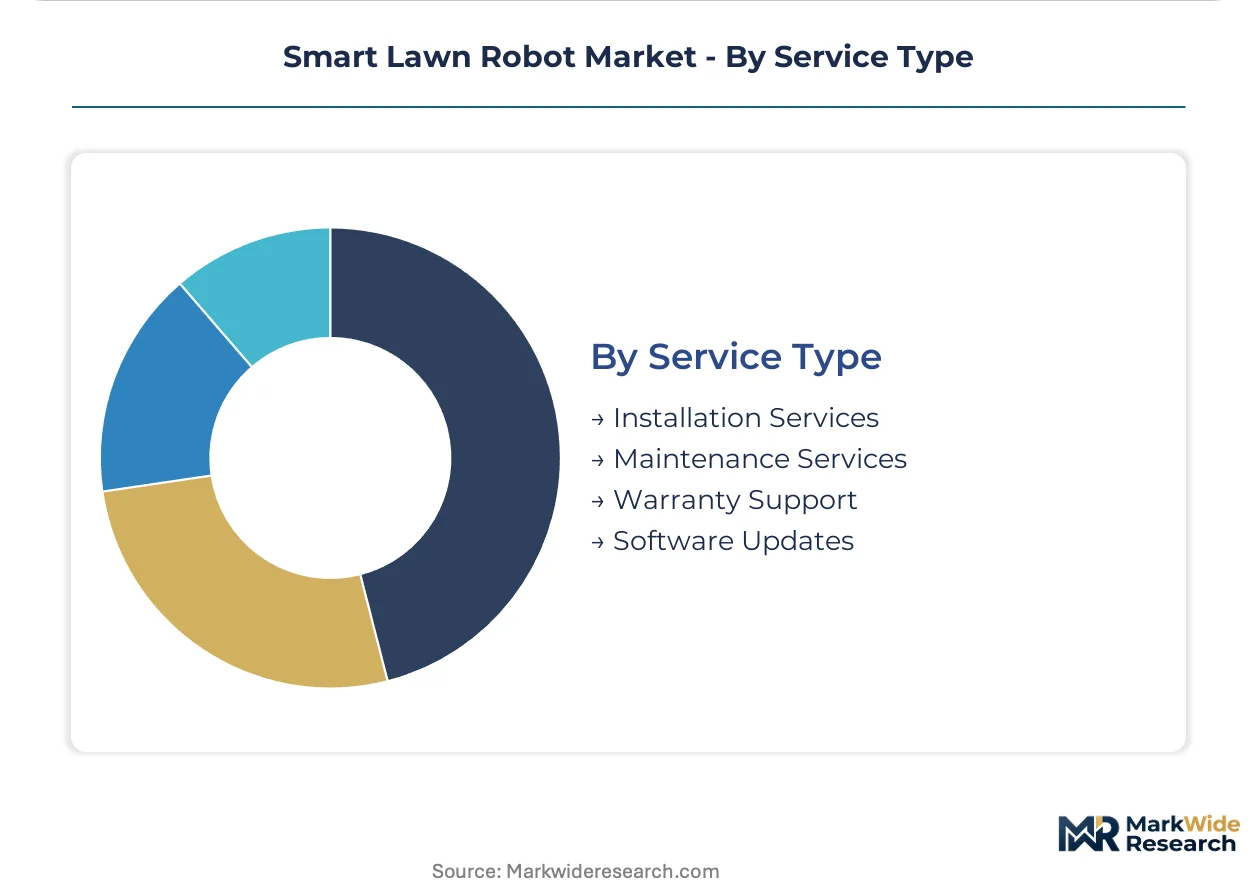
Service Type:
Margin structures diverge between one-time installation revenue and recurring maintenance contracts with 70-85% renewal rates.
- Installation Services:Perimeter-wire deployment, base station positioning, and boundary mapping for GPS-RTK systems. German municipalities require certified low-noise installation for public procurement eligibility.
- Maintenance Services:Scheduled blade replacement, battery health monitoring, and seasonal storage. Fleet operators in the United States are bundling these into fixed monthly robot-as-a-service fees.
- Warranty Support:Defect coverage and repair services during initial ownership period.
- Software Updates:Navigation algorithm improvements and feature expansion delivered over-the-air.
Installation services dominate one-time revenue capture. Maintenance services are where recurring margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipalities command premium pricing for certified low-noise equipment while US commercial landscapers absorb volume discounts through fleet-scale robot-as-a-service contracts. This pricing-power asymmetry reflects divergent regulatory enforcement intensity and labor-cost pressures across the Atlantic.
United States
Commercial landscapers in Florida and Texas drive fleet-scale adoption as seasonal workforce shortages intensify. FCC Part 15 emissions standards constrain radio-frequency subsystem design for cross-border manufacturers. The Southeast automation corridor, spanning Atlanta to Orlando, concentrates pilot deployments of wire-free GPS-RTK systems among property-management firms.
Germany
Municipal procurement channels require sub-60-decibel certification and zero tailpipe emissions under EU Green Deal implementation. The EU Machinery Directive's safety certification creates standardized entry barriers favoring established lithium-ion specialists. Stuttgart and Munich anchor development clusters where precision-agriculture technology spills into residential turf management.
Japan
Aging demographics in prefectures like Kanagawa and Saitama drive residential outsourcing of turf maintenance to unsupervised robotic systems. METI energy-efficiency labeling requirements shape battery-selection strategies for vendors targeting East Asian distribution. The Kanto region around Tokyo concentrates early adoption of AI-enabled navigation for elderly homeowners.
United Kingdom
Benelux-influenced suburban districts prioritize certified low-noise models for compliance with municipal noise ordinances in dense residential areas. Post-Brexit regulatory divergence from EU Machinery Directive creates parallel certification pathways for vendors. The Southeast England estate belt, spanning Surrey to Buckinghamshire, drives replacement demand as first-generation wire-bound systems reach end-of-life.
Netherlands
Suburban automation adoption widens among residential homeowners seeking emission-free outdoor equipment under strict municipal environmental standards. The country's national environmental regulator enforces noise-reduction mandates that accelerate battery-electric platform development. The Randstad conurbation, covering Amsterdam-Rotterdam-The Hague, concentrates demand for perimeter-wire-free configurations in canal-side properties.
Smart Lawn Robot Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor arrays, battery modules, and navigation chipsets. The vendor base organizes into three tiers: diversified outdoor power equipment conglomerates with captive distribution networks; pure-play autonomous mower specialists scaling through direct-to-consumer channels; and industrial automation firms leveraging precision-manufacturing expertise. Competitive dynamics center on M&A activity consolidating sensor-fusion capabilities and strategic partnerships securing lithium-ion cell supply.
Within the diversified conglomerate tier, Husqvarna Group, Deere & Company, and Robert Bosch GmbH exemplify scale-driven positioning through integrated fleet-management platforms and precision-agriculture technology spillover. These Sweden-based, US-based, and Germany-based entities respectively occupy archetypal roles: the captive software ecosystem builder, the agricultural technology cross-over, and the sensor-integration density leader. Their collective presence shapes R&D prioritization across battery-electric platform development and wire-free navigation architectures.
| Leading Market Players |
|---|
| Husqvarna Group |
| Deere & Company |
| Robert Bosch GmbH |
| Honda Motor Co., Ltd. |
| STIGA S.p.A. |
| ANDREAS STIHL AG & Co. KG |
| The Toro Company |
| Stanley Black & Decker, Inc. |
| Segway Inc. |
| Others |
Pricing and Supply Chain Analysis
East Asian lithium-ion cell manufacturing concentration funnels margin pools toward vendors with captive battery partnerships and long-term cathode material offtake agreements. German and Japanese buyers absorb premium pricing for certified low-noise configurations while US commercial fleets extract volume discounts through robot-as-a-service contracting.
Pricing Analysis
The customization-premium spread separates GPS-RTK wire-free configurations from perimeter-wire standard systems by substantial margins. Subscription-based robot-as-a-service models dominate commercial landscaping, while residential transactions favor per-unit purchase with bundled installation. Price differentiation hinges on noise-certification grade and navigation architecture sophistication. Cost compression in entry-tier perimeter-wire systems is intensifying because of component commoditization. Commercial landscapers exhibit highest price sensitivity due to fleet-scale procurement volumes; golf course operators show lowest sensitivity given precision requirements.
Supply Chain Analysis
Contract manufacturing capacity for autonomous mower final assembly concentrates with Taiwanese and Chinese electronics manufacturing services alongside German industrial automation specialists. Lithium-ion cell supply draws from South Korean and Japanese producers, with cathode material processing anchored in Chinese chemical complexes. Single-source vulnerability in RTK-GPS module supply creates exposure to semiconductor allocation constraints. Distribution runs through outdoor power equipment dealers, direct-to-consumer channels, and landscaping fleet procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart lawn robot market sits at a platform-economics inflection where fleet-management software ecosystems determine vendor switching costs and customer lifetime value. Interoperability between autonomous mowers and property-management systems is fragmenting competitive moats.
For Market Incumbents: Entrench fleet-management platform adoption through API integrations with commercial landscaping ERP systems. Deepen backward integration into lithium-ion cell supply by securing cathode material partnerships in South Korea. The emergence of pure-play navigation software vendors threatens to commoditize hardware margins; counter by embedding AI-enabled obstacle classification as a proprietary service layer. For New Entrants and Emerging Players: Establish a beachhead in robotic trimmer subsystems for golf course bunker edge maintenance, a segment where precision requirements justify premium pricing and incumbent presence remains thin. Target Japanese prefectures with aging demographics through unsupervised operation certification. Pursue direct-to-consumer channels with simplified GPS-RTK configurations that eliminate dealer markup. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor power equipment specialists seeking sensor-fusion capability tuck-ins. Five-to-ten year viability favors vendors with closed-loop battery recycling partnerships and software recurring revenue above hardware replacement cycles. Monitor METI energy-efficiency labeling revisions as inflection signal for East Asian market access.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Fusion Navigation Development | Wire-free GPS-RTK configurations unlock estate manager demand without perimeter installation costs. |
| Battery Supply Agreement | Long-term cathode material offtake secures cost position against East Asian supply volatility. |
| Fleet Management Platform Integration | API connectivity with landscaping ERP systems raises customer switching costs and retention. |
| Robot-as-a-Service Launch | Subscription contracting converts capital expenditure to recurring revenue in commercial segments. |
| Low-Noise Certification Investment | EU Green Deal compliance unlocks German municipal procurement channels at premium pricing. |
Research Methodology
Desk research of customs trade databases, EU Machinery Directive filings, and lithium-ion supply chain disclosures preceded structured interviews with commercial landscaping fleet managers, outdoor power equipment procurement directors, robotics perception engineers, and municipal grounds maintenance supervisors. Primary fieldwork validated secondary data on battery-electric platform adoption rates and GPS-RTK navigation penetration. Bottom-up unit shipment modeling triangulated against top-down market value reconstruction across product type, technology tier, and end-user segment dimensions.
Assumption sets held battery cell cost trajectories and regulatory noise-emission thresholds fixed while varying labor-cost inflation scenarios and seasonal workforce availability across North American property-maintenance sectors. Segmentation dimensions modeled include navigation architecture, powertrain configuration, end-user application intensity, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and first-time adoption elasticities. Forecast inputs incorporated METI energy-efficiency labeling revision timelines and EU extended producer responsibility framework evolution.
Stress conditions across lithium supply disruption severity, autonomous software talent wage inflation, and multi-jurisdiction certification delay lengths were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology cost reduction slopes and regulatory enforcement intensity. Quarterly review of German municipal procurement award volumes and Florida landscaping wage indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
France Cloud Robotics Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
US Cloud Robotics Market