
 High-Efficiency Laundry Liquid Detergent Market | 2026-2036
High-Efficiency Laundry Liquid Detergent Market Size, Share, and Industry Trends Forecast 2026-2036
High-Efficiency Laundry Liquid Detergent Market Intelligence
Commercial laundries and institutional buyers is reorganizing demand patterns for high-efficiency laundry liquid detergent as residential consumers face persistent price sensitivity. Procter & Gamble leverages its formulation science infrastructure to maintain shelf presence across concentrated and pod variants in North American retail channels. Henkel anchors European supply through specialized eco-friendly lines that comply with ECHA REACH surfactant restrictions. Kao Corporation dominates technical partnerships with Japanese appliance manufacturers to optimize enzyme stability in low-water wash cycles.
High-efficiency laundry liquid detergent comprises surfactant systems engineered for reduced water volumes, typically requiring lower foam profiles and faster rinsing kinetics than conventional formulations to prevent residue accumulation in front-loading drum mechanisms. The product category serves residential consumers, commercial linen services, and industrial textile processors seeking to minimize water heating energy and cycle duration without sacrificing soil removal performance. Concentrated formulations command margin pools due to reduced packaging and logistics costs, while eco-friendly variants attract regulatory preference and retailer slotting allowances in jurisdictions with extended producer responsibility laws. Pods and gel formats are gaining fastest in residential channels where dosing convenience offsets per-wash premiums, though bulk packaging sustains share in commercial and institutional procurement.
The EPA Safer Choice program and ECHA REACH framework restrict alkylphenol ethoxylates and phosphates in detergent chemistry, compelling reformulation investments that smaller suppliers struggle to absorb. Japan's Ministry of Economy, Trade and Industry (METI) promotes high-efficiency appliance standards that create bundled demand for compatible detergents through manufacturer certification programs. Stakeholders must monitor evolving state-level packaging mandates in California and New York alongside EU Green Deal circular economy requirements that will reshape refill infrastructure and concentrated dosing formats.
Market Dynamics
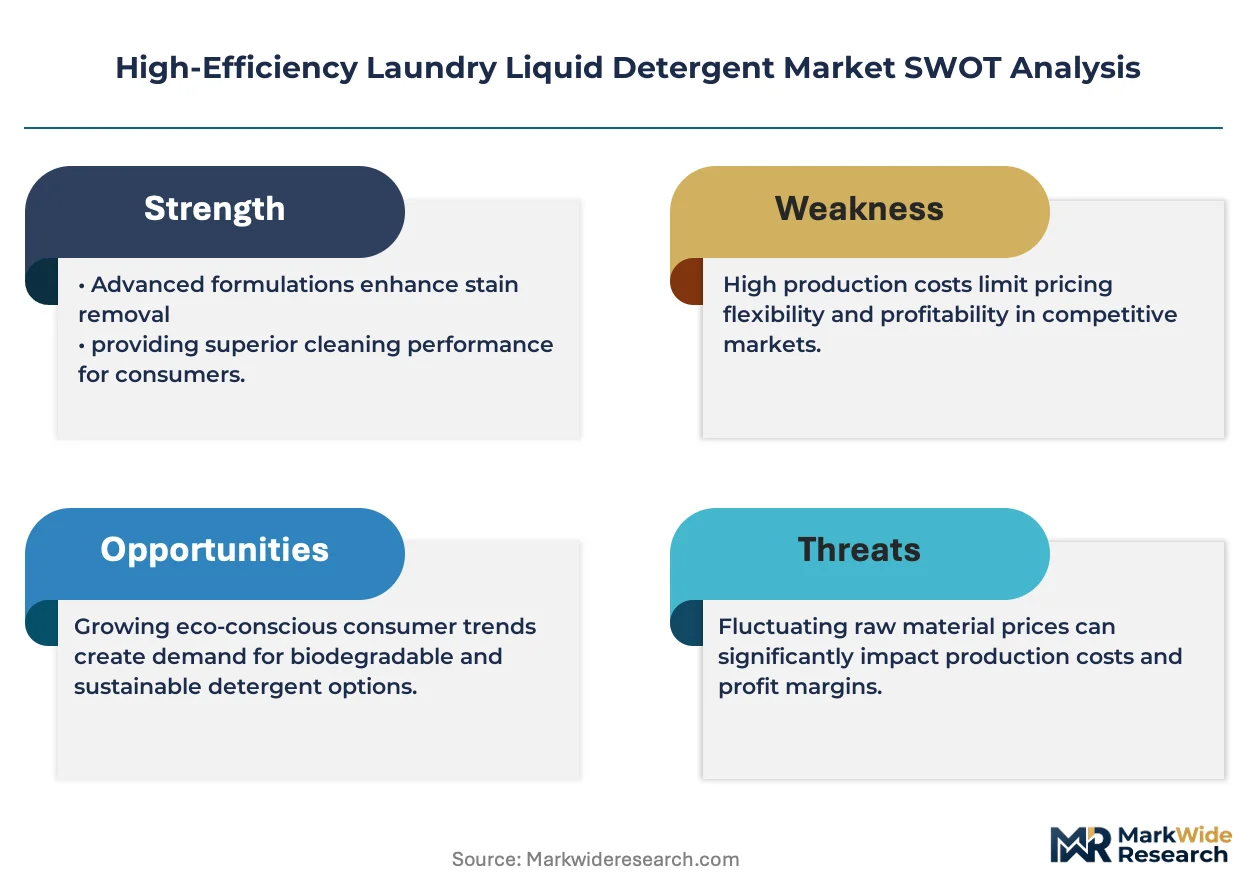
The EPA Safer Choice program and ECHA REACH surfactant restrictions are forcing simultaneous reformulation across all major production footprints, compressing margin structures for suppliers lacking captive enzyme development capabilities.
Growth Catalysts
- Water scarcity mandates:California and Arizona state-level conservation regulations now require high-efficiency detergent compatibility in commercial laundry equipment procurement, expanding institutional demand pools beyond voluntary adoption.
- Enzyme stabilization advances:Cold-water wash formulations with improved protease and amylase shelf stability are unlocking residential conversion from conventional detergents in metered-utility markets.
- EU Green Deal circular economy requirements:Extended producer responsibility laws for packaging are accelerating refill infrastructure investment by retailers seeking to preempt compliance costs.
Market Restraints
- Petrochemical feedstock volatility:Linear alkylbenzene sulfonate and alcohol ethoxylate input costs fluctuate with crude oil derivatives, constraining pricing flexibility for mid-tier suppliers without backward integration into surfactant production.
- Concentration in enzyme supply:Technical-grade protease and lipase manufacturing clusters in Denmark and the Netherlands create single-source vulnerability for formulators dependent on just-in-time delivery.
- Legacy equipment incompatibility:Top-loading agitator machines prevalent in rental housing and older residential stock cannot utilize low-foam HE formulations without residue accumulation and odor complaints.
Strategic Opportunities
- Subscription direct-to-consumer channels:Concentrated refill pouches delivered on automated replenishment cycles are capturing urban millennials in US coastal metros, bypassing slotting fee barriers at mass retail.
- Healthcare linen services:Thermal disinfection requirements in hospital central sterile supply departments create demand for enzyme-detergent hybrids that maintain efficacy at reduced wash temperatures.
- Japan METI appliance-certification bundling:Detergent manufacturers partnering with washing machine OEMs for co-certified wash programs gain preferred placement in appliance retail channels and replacement part ecosystems.
Industry Challenges
- Biodegradability certification timelines:OECD 301B ready biodegradability testing and EPA Safer Choice label approval processes extend product launch windows by 8-14 months, compressing first-mover advantage windows.
- Reformulation complexity for cold-water stability:Maintaining enzyme activity across variable municipal water hardness profiles requires region-specific variants, fragmenting production runs and inventory management.
- Interoperability with smart appliance ecosystems:Dosing algorithms in connected washing machines demand precise viscosity and conductivity specifications that vary by OEM, forcing multiple formulation SKUs for identical cleaning performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Efficiency Laundry Liquid Detergent Market |
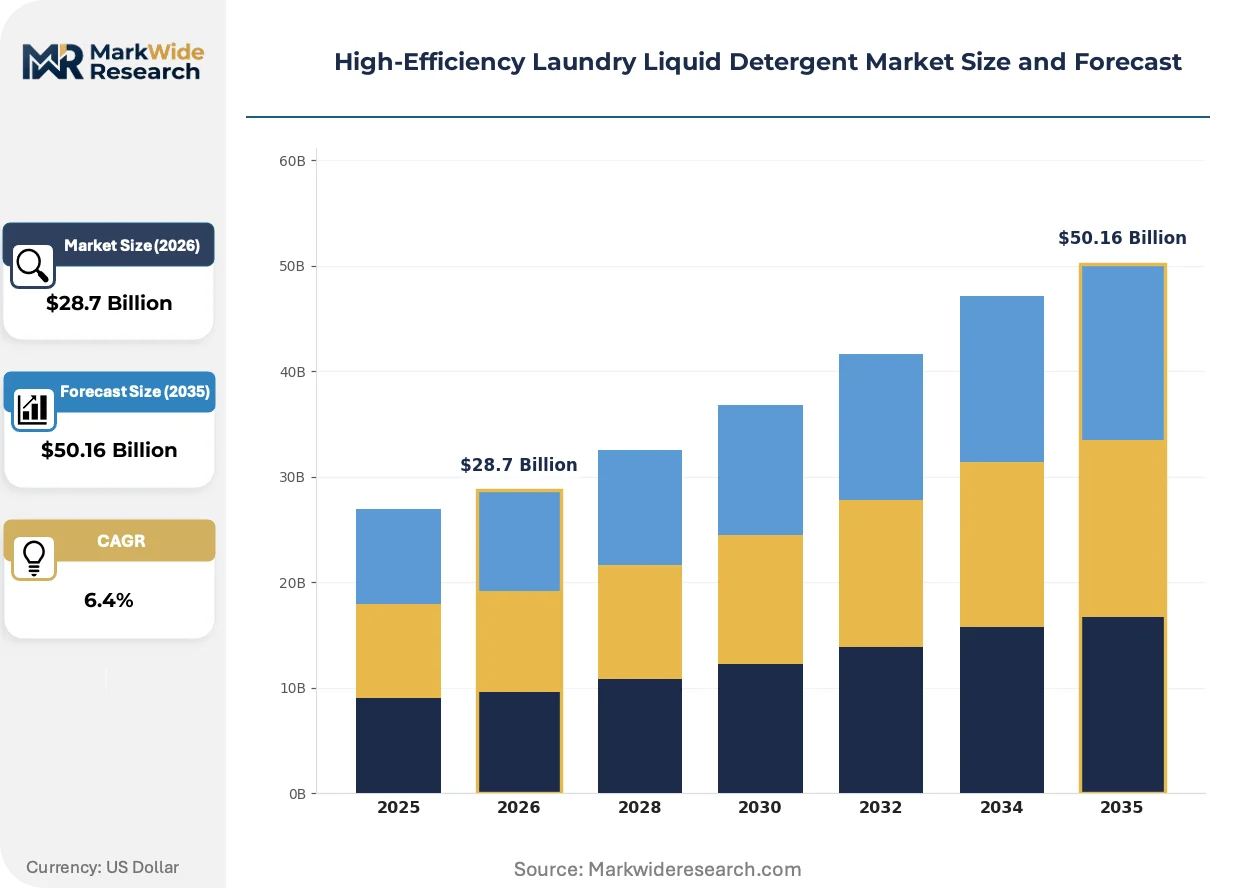
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Non-Concentrated, Sensitive Skin, Eco-Friendly Application: Residential, Commercial, Industrial, Institutional Formulation Type: Liquid, Gel, Powder, Pods Packaging Type: Bottle, Pouch, Refill, Bulk |
| Companies Covered | Procter & Gamble, Unilever, Henkel, Colgate-Palmolive, Church & Dwight, Reckitt Benckiser, SC Johnson, Clorox Company, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Efficiency Laundry Liquid Detergent Market Strategic Shifts & Innovations
Formulation chemistry and delivery mechanisms are converging around water reduction, with enzyme engineering and packaging innovation advancing in parallel rather than sequentially.
Single-dose pod formats with dissolvable film barriers are miniaturizing residential consumption patterns by eliminating overdosing waste and enabling precise enzyme concentration per wash cycle. Urban apartment dwellers in Tokyo, New York, and London are adopting these formats fastest due to storage constraints and premium positioning at convenience retail. This miniaturization is compressing bulk liquid volume share in residential channels while expanding margin pools for suppliers with film-sealing process expertise.
ECHA REACH restrictions on alkylphenol ethoxylates and phosphates are compelling surfactant system redesigns across European manufacturing footprints. Formulators are substituting alcohol ethoxylates and glucoside-based alternatives, increasing raw material costs by 15-25% for comparable foam profiles. Commercial laundry operators in Germany and France are absorbing these premiums to maintain eco-label eligibility for hospitality and municipal contracts.
Buying committees at hospital systems and hotel chains are consolidating detergent procurement into multi-year managed service agreements that bundle chemical supply, equipment maintenance, and wash program optimization. Distributor relationships are being disintermediated as manufacturers deploy direct technical sales teams with process engineering capabilities. This pattern is most visible in US Sun Belt markets where healthcare construction and hospitality expansion are concentrating new account formation.
High-Efficiency Laundry Liquid Detergent Market Segmentation
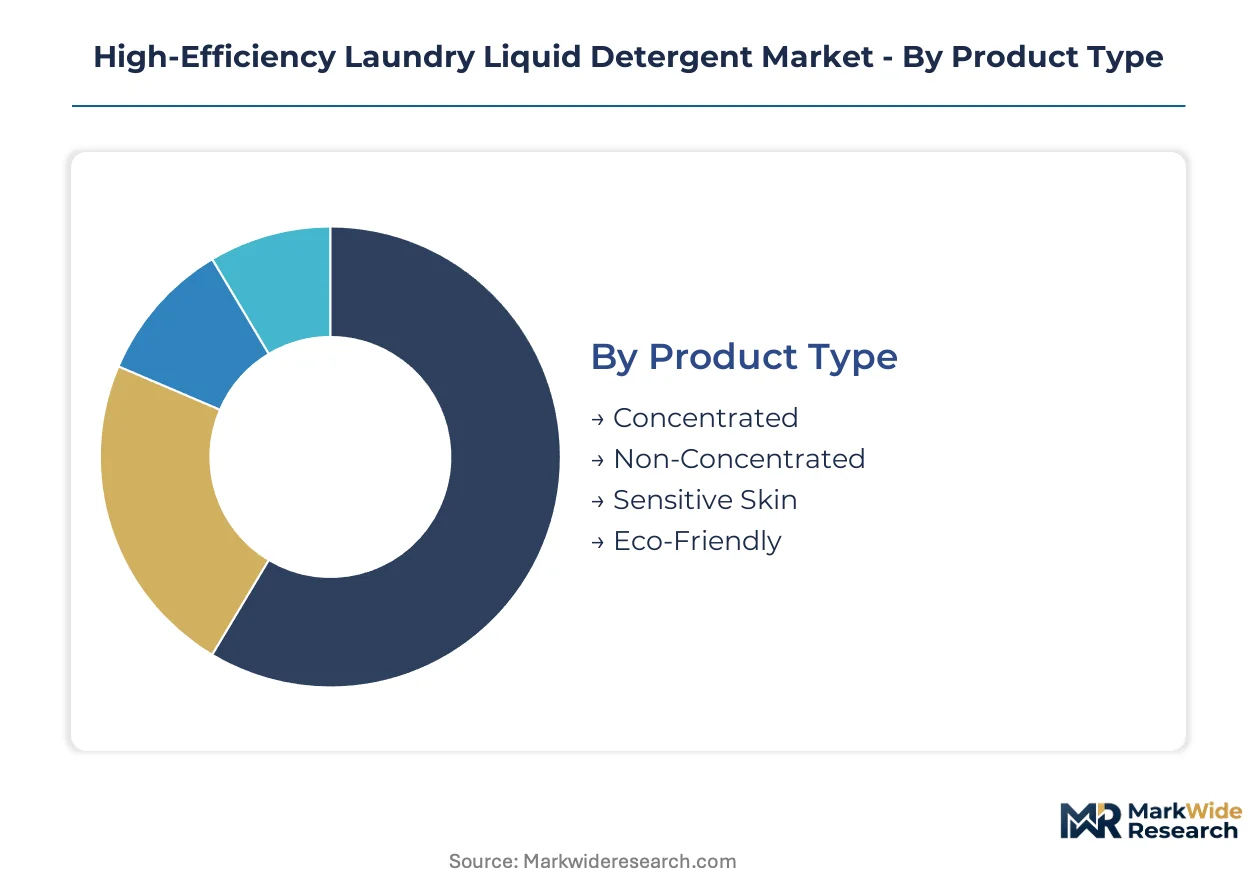
Segmentation in high-efficiency laundry liquid detergent reflects divergent channel economics and regulatory exposure across consumer and institutional procurement. Product format, concentration level, and packaging modality each dictate distinct margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Channel-mix dynamics concentrate premium formulations in specialty retail and direct-to-consumer platforms, while mass-market SKUs dominate club and grocery distribution.
- Concentrated:Reduced water content formulations require 50-70% less packaging volume than legacy equivalents. Demand concentrates in Germany and Japan where municipal water pricing and appliance efficiency standards create bundled purchasing incentives for residential and commercial buyers.
- Eco-Friendly:Biodegradable surfactant systems certified under EPA Safer Choice or EU Ecolabel frameworks command slotting premiums in European retail channels. Hospitality procurement in France and the Netherlands absorbs 15-25% raw material cost premiums to maintain contract eligibility under extended producer responsibility laws.
- Non-Concentrated:Legacy dilute formulations retain shelf presence in price-sensitive retail segments and rental housing markets with older top-loading equipment.
- Sensitive Skin:Fragrance-free and dye-reduced variants target pediatric and dermatology-recommended segments through pharmacy and healthcare retail channels.
Concentrated formulations dominate installed base in high-efficiency appliance markets. Eco-friendly variants are where expansion concentrates as ECHA REACH and EPA disclosure requirements tighten.
Application:
Volume scale and contract structure differentiate institutional procurement from fragmented residential purchasing patterns.
- Residential:Single-family and multi-unit dwelling consumption drives pod and gel adoption where dosing convenience offsets per-wash premiums. Urban millennials in US coastal metros and Tokyo apartment markets show fastest uptake of subscription refill models.
- Commercial:On-premise laundry operators in hospitality and healthcare sectors prioritize thermal disinfection compatibility and enzyme stability across variable water hardness profiles.
- Industrial:Textile processors and linen rental services demand bulk formulations with precise conductivity specifications for automated dosing systems.
- Institutional:Hospital central sterile supply departments and correctional facilities require managed service agreements bundling chemical supply with equipment maintenance and wash program optimization.
Commercial applications dominate contract value concentration. Residential channels are where format innovation and direct-to-consumer disruption accelerate most quickly.
Formulation Type:
Physical state determines compatibility with smart appliance ecosystems and automated dispensing infrastructure.
- Pods:Single-dose dissolvable film barriers eliminate overdosing waste and enable precise enzyme concentration per wash cycle. Tokyo, New York, and London apartment dwellers adopt these formats fastest due to storage constraints and convenience retail positioning.
- Liquid:Standard pour formulations retain flexibility across machine types and water hardness profiles, serving as the baseline for regional variant development.
- Gel:Viscosity-optimized alternatives target front-loading drum mechanisms with reduced residue accumulation risk in low-water cycles.
- Powder:Legacy format retains share in emerging markets and commercial bulk procurement where dissolution speed is less critical than unit economics.
Liquid formulations dominate installed base across all geographies. Pods are where residential volume expansion and margin pool migration concentrate.
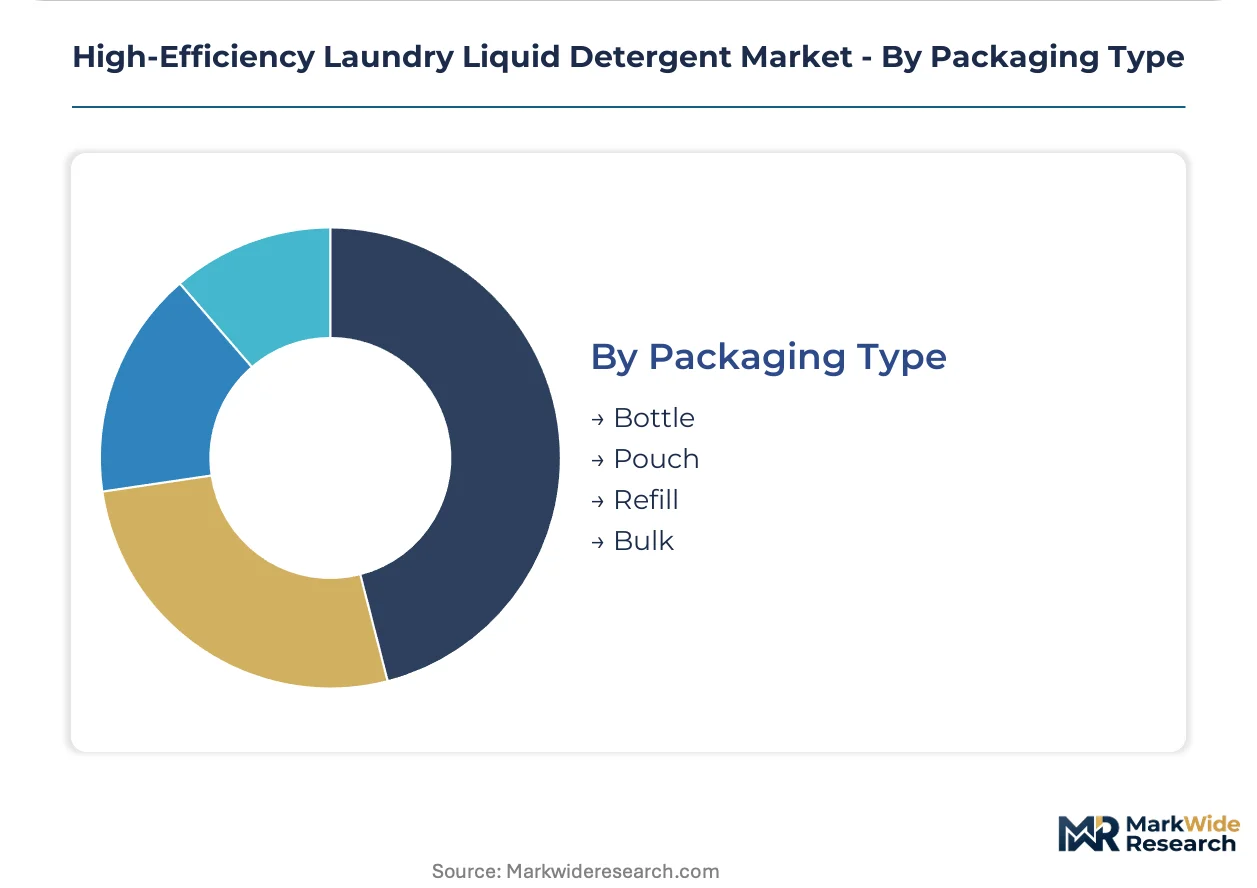
Packaging Type:
Extended producer responsibility laws and refill infrastructure investment reshape cost allocation between primary and secondary packaging.
- Pouch:Flexible refill formats reduce per-unit plastic consumption and enable subscription direct-to-consumer channels bypassing slotting fee barriers at mass retail.
- Bottle:Rigid primary packaging retains dominance in conventional grocery and club channels where shelf visibility and handling durability matter.
- Refill:Concentrated bulk supply for existing bottle reuse systems expands in EU markets ahead of Green Deal circular economy compliance deadlines.
- Bulk:Industrial drum and tote formats serve commercial linen services and textile processors with automated dosing equipment and high-throughput requirements.
Bottle formats dominate current retail shelf presence. Pouch and refill systems are where regulatory pressure and infrastructure investment concentrate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European supply chain reliability for surfactant imports and concentrated formulation distribution across the Rhine corridor.
United States
California and Arizona water scarcity mandates now require high-efficiency detergent compatibility in commercial laundry equipment procurement. The EPA Safer Choice program tightens surfactant disclosure requirements for institutional buyers. Hospital systems in the Sun Belt are consolidating procurement into multi-year managed service agreements bundling chemical supply with wash program optimization.
Germany
Municipal water pricing and appliance efficiency standards create bundled purchasing incentives for concentrated formulations across residential and commercial segments. ECHA REACH restrictions on alkylphenol ethoxylates compel surfactant system redesigns with 15-25% raw material cost premiums. The Rhine-Ruhr industrial corridor hosts reformulation facilities serving hospitality procurement in France and the Netherlands.
Japan
Tokyo apartment dwellers adopt single-dose pod formats fastest due to storage constraints and convenience retail positioning. METI appliance-certification programs create bundled demand for compatible detergents through manufacturer partnerships. Kansai region textile processors demand precise conductivity specifications for automated dosing systems in industrial applications.
France
Hospitality procurement absorbs eco-label premiums to maintain contract eligibility under extended producer responsibility laws. EU Green Deal circular economy requirements accelerate refill infrastructure investment by retailers. The Lyon chemical cluster supplies glucoside-based surfactant alternatives replacing restricted phosphate formulations.
United Kingdom
London's dense urban housing stock drives subscription refill pouch adoption among millennials bypassing mass retail slotting fees. Post-Brexit regulatory divergence creates parallel compliance tracks for surfactant disclosure versus EU Ecolabel frameworks. Manchester-based commercial linen services consolidate detergent procurement with equipment maintenance contracts.
High-Efficiency Laundry Liquid Detergent Market Key Industry Players
Concentration sits with multinational consumer goods conglomerates possessing captive formulation science infrastructure and retail channel scale. Three to five global players control shelf presence across concentrated, pod, and eco-friendly variants in developed markets. Strategic archetypes include vertically integrated surfactant producers, enzyme technology licensors, and regional specialists with appliance manufacturer partnerships. Capacity expansion in cold-water stable enzyme production and geographic licensing agreements represent dominant competitive moves.
Among US-based conglomerates, Procter & Gamble and Colgate-Palmolive exemplify scale-driven archetypes with retail channel breadth. Henkel AG represents European eco-specialization with ECHA REACH-compliant portfolio positioning. Kao Corporation anchors Japanese technical partnerships with appliance OEMs for wash program certification.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Henkel |
| Colgate-Palmolive |
| Church & Dwight |
| Reckitt Benckiser |
| SC Johnson |
| Clorox Company |
| Kao Corporation |
| Others |
Cost & Logistics Intelligence
Alcohol ethoxylate substitution for alkylphenol ethoxylates under ECHA REACH restrictions is simultaneously shifting surfactant sourcing toward Rotterdam-Antwerp chemical corridors and compressing margin structures for formulators lacking captive glucoside production capabilities.
Pricing Analysis
Volume-discount tiering separates eco-certified premium formulations from standard concentrated SKUs and legacy non-concentrated economy options. Price differentiation rests on EPA Safer Choice certification status and cold-water enzyme stability performance rather than brand heritage alone. Cost compression in the mid-tier is intensifying because Danish and Dutch enzyme suppliers command premium pricing for technical-grade protease with extended shelf stability. Hospital procurement committees show least price sensitivity due to bundled managed service agreements, while rental housing operators with legacy top-loading equipment remain most margin-constrained.
Supply Chain Analysis
Inventory lead times for technical-grade enzymes stretch disproportionately versus surfactant feedstocks due to single-source fermentation capacity in Denmark and the Netherlands. Manufacturing concentration in Germany, the United States, and Japan anchors formulation finishing, while linear alkylbenzene sulfonate precursors draw from petrochemical complexes in the US Gulf Coast and Rotterdam. Single-source vulnerability in cold-stable lipase supply creates exposure for formulators dependent on just-in-time delivery. Distribution runs through chemical distributors serving commercial laundries and direct-to-retail channels for residential pods and refill pouches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-efficiency laundry liquid detergent represents a high-growth disruption justified by Japan METI appliance-certification bundling that locks detergent OEMs into replacement part ecosystems and co-certified wash programs.
For Market Incumbents: Fortify enzyme stabilization capabilities through captive R&D or exclusive licensing arrangements with Danish fermentation specialists. Secure backward integration into glucoside surfactant production to absorb ECHA REACH compliance premiums without passing full cost to hospitality procurement committees. The priority lever sits with preemptive refill infrastructure investment ahead of EU Green Deal circular economy deadlines. For New Entrants and Emerging Players: Subscription direct-to-consumer refill pouches present the most penetrable white-space where Procter & Gamble and Henkel maintain underinvestment relative to mass retail slotting dominance. Target urban millennial households in London and New York where storage constraints and convenience positioning override brand loyalty. The optimal go-to-market angle pairs automated replenishment algorithms with EPA Safer Choice certification for regulatory preference in municipal procurement. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with appliance manufacturer partnerships in Japan and cold-water enzyme formulation expertise. Long-term viability favors acquisition targets possessing METI co-certification relationships and concentrated production footprints in high water-pricing markets. Watch for inflection signals in California state-level packaging mandate enforcement that would accelerate refill infrastructure returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Absorbs ECHA REACH reformulation premiums without margin erosion to hospitality buyers. |
| Appliance OEM Co-Certification Partnership | Locks in preferred placement through Japan METI wash program bundling. |
| Direct-to-Consumer Refill Channel Launch | Bypasses mass retail slotting fees while capturing urban millennial subscription lifetime value. |
| Cold-Water Enzyme Stability R&D Investment | Opens residential conversion from conventional detergents in metered-utility markets. |
| Extended Producer Responsibility Compliance Infrastructure | Preempts EU Green Deal circular economy costs through retailer refill system partnerships. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with commercial laundry procurement directors, hospital central sterile supply managers, detergent formulation chemists, and retail category buyers. Secondary validation drew from EPA Safer Choice certified product databases, ECHA REACH registration dossiers, Japan METI appliance efficiency standard filings, and customs trade records for surfactant feedstock flows. Bottom-up volume modeling across product formats and applications triangulated against top-down value estimates from disclosed chemical supply agreements.
Across the analysis window, the forecast framework modeled segmentation by concentration level, formulation type, packaging modality, and regional regulatory cluster to capture divergence between EPA Safer Choice markets and ECHA REACH jurisdictions. CAGRs were derived from elasticity-adjusted adoption curves for high-efficiency appliance penetration and institutional procurement contract renewal patterns. Key inputs included municipal water pricing trajectories in California and Arizona, enzyme stabilization patent filings, and hospitality construction permits in US Sun Belt markets.
Forecasts assume regulatory continuity in EPA Safer Choice disclosure requirements and ECHA REACH surfactant restrictions; material policy shifts in either regime would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
South Africa Cookware Market
Household Items
Consumerware Market
Household Items
Knife Market
Household Items
Sanitary Metal Ware Market
Household Items
US Digital Showers Market
Household Items
US Air Purifier Market
Household Items
Saudi Arabia Cookware Market
Household Items
Garbage Disposals Market
Household Items
Disposable Cutlery Market
Household Items
Smart Bathroom Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Toilet Rim Blocks Market
Household Items
Toilet Paper Market
Household Items
Tiki Torch Market
Household Items
Commercial Locker Market
Household Items
Steam Cleaners Market