
 Electric Mop Market | 2026-2036
Electric Mop Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Mop Market Analysis
IPX4 water-resistance certification is unwinding competitive access for smaller assemblers unable to fund third-party validation. Alfred Kärcher SE & Co. KG leverages in-house testing laboratories to accelerate compliance cycles. BISSELL anchors its North American position through captive injection-molding capacity for solution tanks. Xiaomi Corporation competes on connected-home stack integration, embedding robotic mops within its IoT ecosystem.
An electric mop is a mains- or battery-powered floor-cleaning appliance that uses motorized pad rotation, heated steam generation, or autonomous navigation to remove soil without manual wringing, typically operating at 1200–1500 watts for steam variants or 14.4–21.6 volts for cordless units. Its primary commercial purpose is reducing chemical dependency and labor time in hygiene-sensitive environments. Steam mops command the widest household penetration but face margin compression from commodity motor suppliers. Robotic mops represent the fastest-expanding value pool, tethered to LiDAR mapping and app-based scheduling subscriptions. UV-C sanitization models occupy a premium niche in hospitality procurement, where infection-control protocols justify unit costs three to four times above base spin configurations.
The EPA regulates antimicrobial claims on UV-C and steam-based sanitization devices, requiring substantiated kill-rate documentation before interstate marketing. Ecodesign requirements under the EU Green Deal are phasing out inefficient resistive heating elements in favor of optimized boiler designs. China's GB 4706 household appliance safety standards mandate automatic shut-off and cord-retraction mechanisms. Stakeholders must monitor whether emerging state-level chemical disclosure laws in the United States extend to cleaning solution cartridges sold as proprietary refills.
Market Dynamics
Steam boiler efficiency mandates under the EU Green Deal are forcing wholesale redesign of heating architectures, compressing margins for assemblers dependent on commodity resistive elements while rewarding integrated manufacturers with captive thermal engineering capabilities.
Growth Catalysts
- Healthcare procurement protocols:Infection-control standards in hospitals and long-term care facilities now specify UV-C sanitization cycles, creating specification pull for premium electric mop configurations.
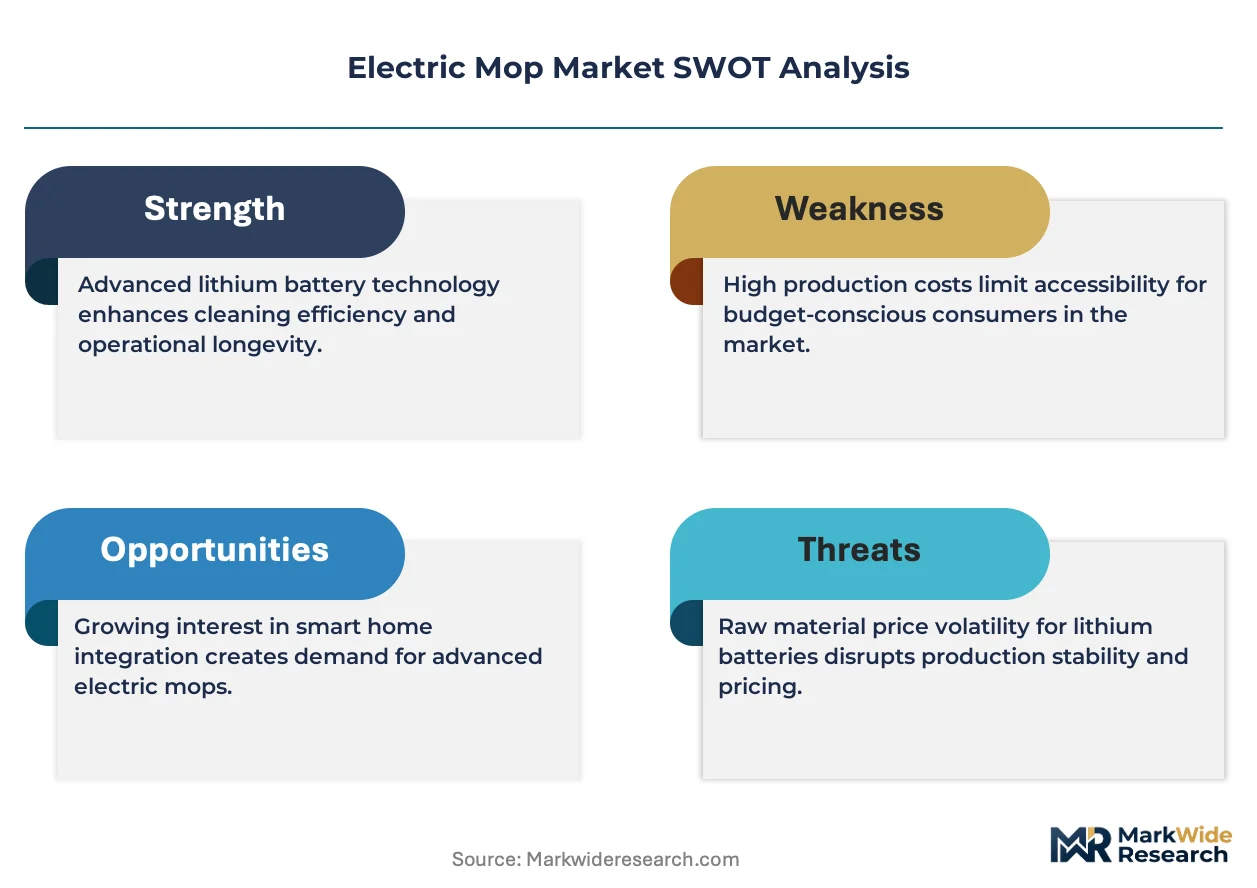
- China's dual carbon goals:Municipal subsidies for energy-efficient household appliances accelerate replacement cycles in tier-one and tier-two cities.
- LiDAR navigation modules:Falling component costs enable robotic mop penetration into mid-income segments previously served by manual alternatives.
Market Restraints
- Lithium-ion cell volatility:Battery raw material price swings compress margins on cordless units, particularly for distributors without forward-contracting relationships with cell suppliers.
- IPX4 certification concentration:Third-party validation capacity clusters with established testing houses in Germany and China, creating queue bottlenecks for new entrants.
- Steam mop substitution:Disposable wet-mop systems with antimicrobial claims capture price-sensitive household segments, limiting base-model volume expansion.
Strategic Opportunities
- India's urban sanitation infrastructure:Swachh Bharat Mission funding for commercial cleaning equipment creates procurement windows in municipal and educational institutions.
- IoT ecosystem convergence:Integration with smart home platforms enables subscription-based consumable replenishment and predictive maintenance revenue streams.
- EU Ecodesign compliance services:Technical consultancy and boiler redesign support represent high-margin adjacencies for engineering firms with thermal systems expertise.
Industry Challenges
- Embedded software talent scarcity:Robotic navigation and app development functions compete for engineers with automotive and consumer electronics sectors, inflating compensation costs.
- GB 4706.1 testing timelines:China's safety standard certification requires extended sample evaluation periods, delaying product launches by two to three quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Mop Market |
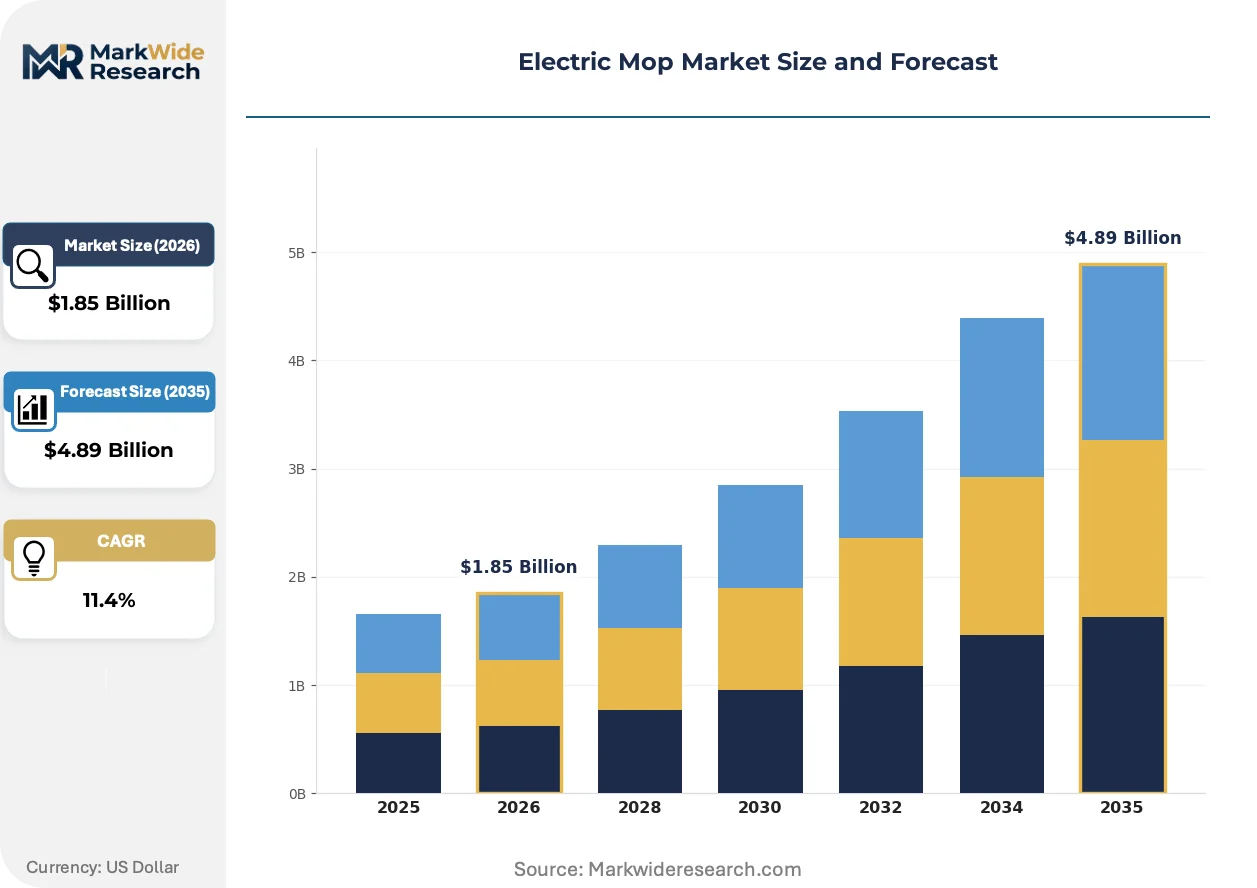
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin Mops, Steam Mops, Robotic Mops, Spray Mops End User: Households, Commercial Spaces, Industrial Settings, Hospitality Cleaning Technology: Dry Cleaning, Wet Cleaning, UV-C Sanitization, Hybrid Technology Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | SharkNinja Operating LLC, Alfred Kärcher SE & Co. KG, Procter & Gamble, Xiaomi Corporation, Stanley Black & Decker Inc., Ecovacs Robotics Co Ltd, BISSELL, HAAN Corporation, TTK Prestige Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Mop Market Emerging Trajectories
Product architectures are splitting between premium autonomous systems with mapping capabilities and simplified steam units optimized for cost, while regulatory pressure on energy efficiency accelerates thermal engineering differentiation.
Steam generation technology is bifurcating between legacy resistive heating elements and optimized boiler designs with rapid-cycle thermal management. Hospitality procurement teams specify the latter for continuous-duty applications in cruise ships and convention centers. This divide compresses margins for commodity motor suppliers while rewarding captive thermal engineering capabilities.
REACH restrictions on persistent organic pollutants are tightening material specifications for plastic housings and solution tank linings. Manufacturers must reformulate polymer compounds or source alternative resins, adding formulation validation costs. Cordless unit producers serving EU markets face the steepest compliance burden, accelerating supplier consolidation toward vertically integrated compounders.
Facility managers increasingly specify equipment through consolidated procurement platforms rather than traditional distributor relationships. Group purchasing organizations aggregate demand from hospital networks and university systems, compressing distributor margins and privileging manufacturers with direct fulfillment infrastructure. This pattern concentrates most visibly in the United States, where healthcare system consolidation has reduced the number of independent purchasing decision points by half over the past decade.
Electric Mop Market Segmentation
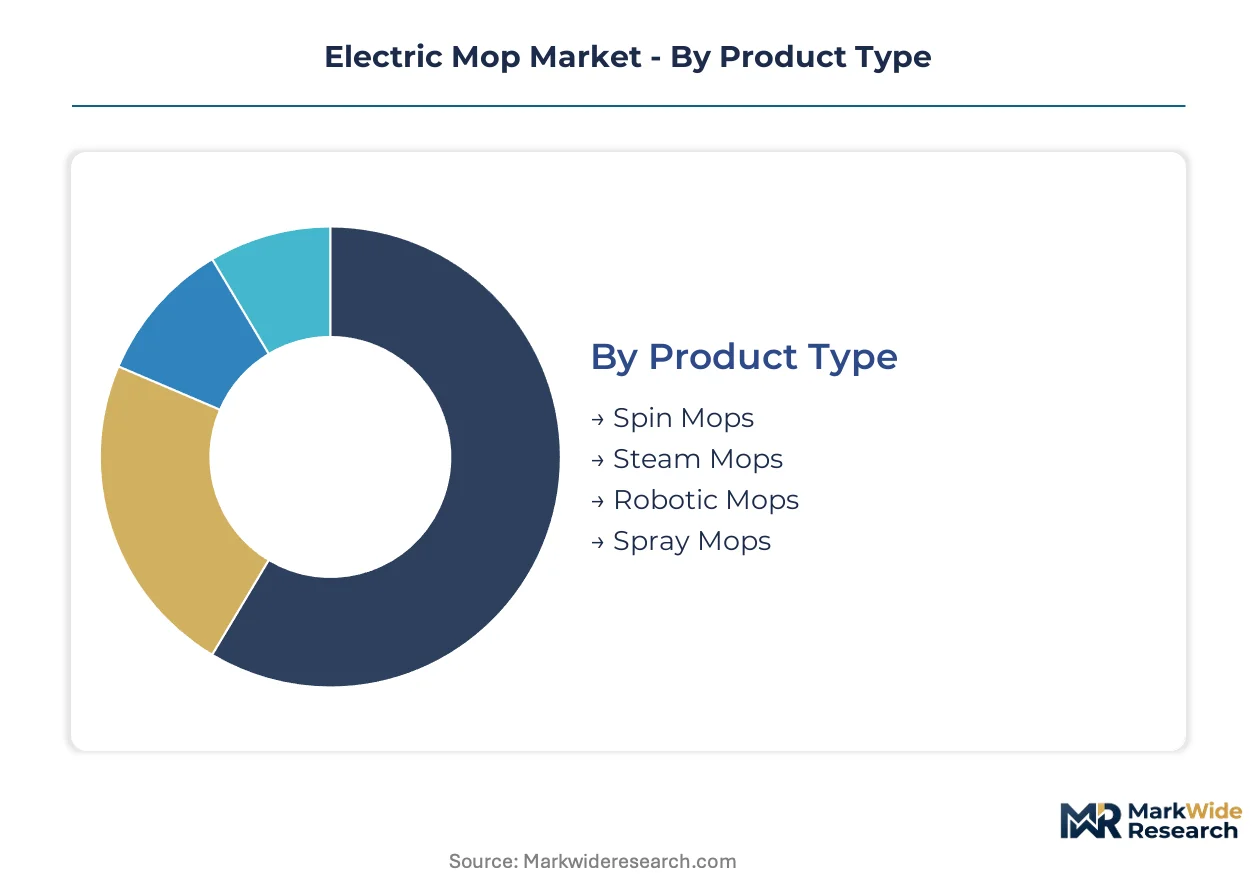
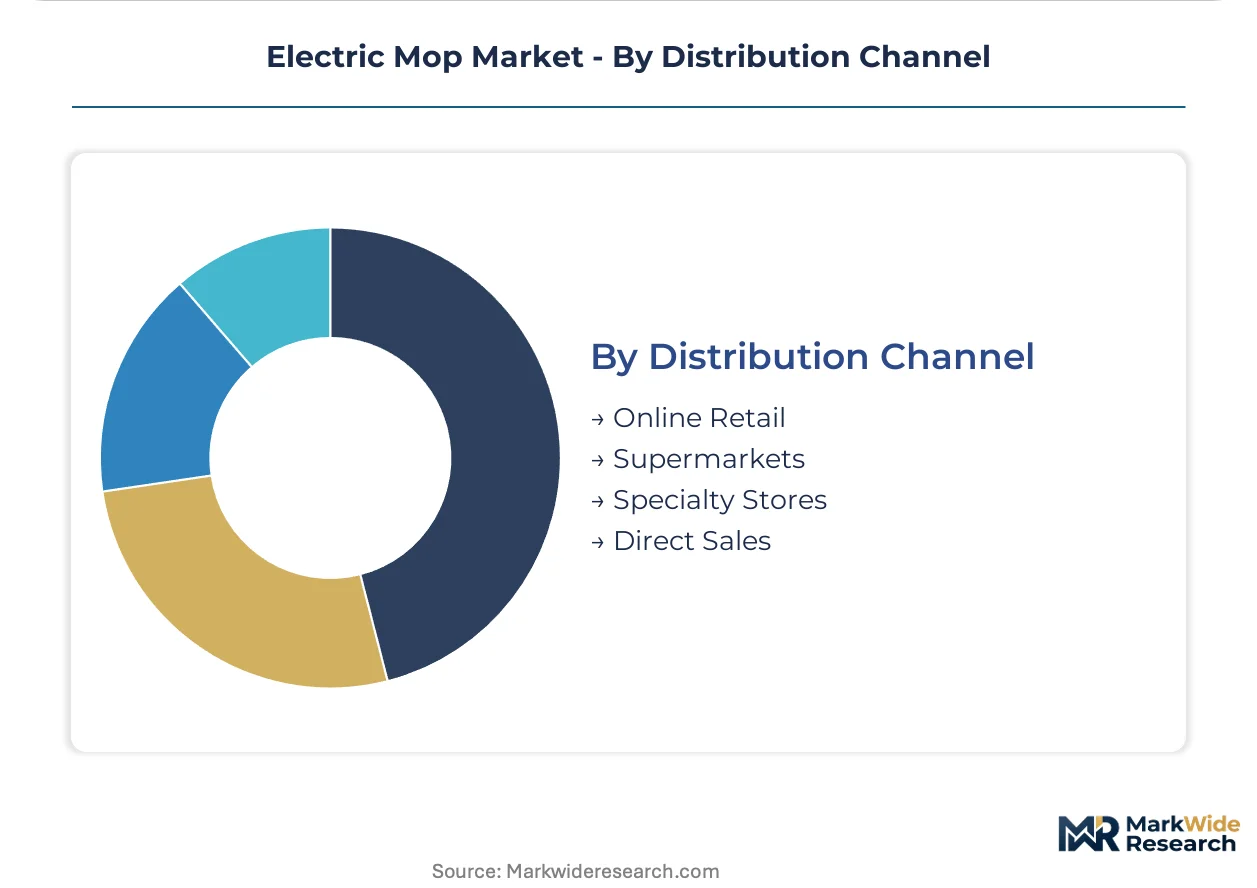
Electric mop procurement channels diverge sharply by buyer sophistication and purchase frequency. Household buyers favor self-service digital channels for replacement units, while institutional procurement teams route high-value sanitization equipment through specialized distributors with validation documentation.
Product Type:
Channel mix varies dramatically: spin and spray models dominate mass retail shelf space, while robotic and steam variants concentrate in direct-to-consumer and B2B specification channels.
- Spin Mops:Motorized pad rotation systems operating at 40–60 RPM with microfiber absorption cores. Demand clusters in North American big-box retail where replacement pad subscriptions drive recurring revenue. Walmart and Target allocate premium end-cap positioning to cordless lithium-ion variants.
- Steam Mops:Pressurized boiler systems generating 110–150°C saturated steam for chemical-free sanitization. Healthcare facilities in Germany and France specify these for patient room turnover protocols under EU Green Deal efficiency mandates. Resistive heating element redesigns are compressing margins for assemblers without captive thermal engineering.
- Robotic Mops:Autonomous navigation platforms with LiDAR mapping and app-based scheduling. Xiaomi and Roborock dominate through smart home ecosystem integration.
- Spray Mops:Manual-pump solution dispensers with disposable or reusable pads. Dollar-store and supermarket channels in India and Southeast Asia absorb volume.
By volume, spin mops lead. By growth pace, robotic mops are climbing the fastest.
End User:
Cost tier stratification separates premium specification buyers from price-sensitive mass market segments.
- Households:Individual consumers purchasing 1–2 units annually with replacement consumables. Chinese tier-one cities show fastest upgrade cycles to connected robotic systems.
- Commercial Spaces:Office complexes and educational institutions with centralized procurement. India's Swachh Bharat Mission funds municipal cleaning equipment purchases.
- Industrial Settings:Manufacturing floors and warehouse operations requiring continuous-duty equipment. IPX4 certification and OSHA compliance documentation gate entry.
- Hospitality:Hotels, cruise ships, and convention centers specifying UV-C sanitization cycles. Infection-control protocols justify unit costs three to four times above base configurations.
Households generate absolute volume. Hospitality commands the steepest per-unit pricing and fastest technology refresh cycles.
Cleaning Technology:
Application environment dictates technology selection: dry systems for dust-sensitive electronics manufacturing, wet and hybrid for general soil removal, UV-C for healthcare-grade sanitization.
- Dry Cleaning:Electrostatic and suction-based particulate removal without liquid application. Electronics cleanrooms and semiconductor fabrication facilities mandate these for static control.
- Wet Cleaning:Water-based soil suspension with detergent or plain water. Dominates residential replacement cycles across all geographies.
- UV-C Sanitization:254nm ultraviolet germicidal irradiation integrated with mechanical cleaning. EPA kill-rate documentation requirements restrict interstate marketing to substantiated claims. Hospital networks in the United States specify through group purchasing organizations.
- Hybrid Technology:Sequential or simultaneous application of wet cleaning and UV-C exposure. Cruise ship operators and airport terminals adopt for high-traffic surface protocols.
Wet cleaning holds installed base dominance. UV-C sanitization is gaining share fastest in specification-driven procurement.
Distribution Channel:
Supply concentration clusters with fulfillment infrastructure scale: Amazon and JD.com for online, Costco and Carrefour for mass retail, specialized distributors for institutional specification.
- Online Retail:E-commerce platforms with search-optimized listings and subscription replenishment. Robotic mop attachment rates for consumable subscriptions exceed 40% in China.
- Supermarkets:Mass merchandisers with seasonal promotional cycles and impulse placement. Spin and spray mop SKUs turn inventory fastest in this channel.
- Specialty Stores:Appliance retailers and cleaning equipment distributors with demonstration capacity. Steam mop conversion rates benefit from in-store boiler performance trials.
- Direct Sales:Manufacturer-owned channels for B2B specification and warranty service. Kärcher and BISSELL maintain field sales teams for healthcare and hospitality accounts.
Online retail leads volume contribution. Direct sales delivers the highest margin realization and longest contract tenure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal subsidy programs and building efficiency codes are redirecting procurement volumes toward certified electric mop configurations in urban centers across multiple continents.
China
Tier-one cities including Shanghai and Shenzhen are accelerating replacement cycles through dual carbon goal subsidies for energy-efficient household appliances. GB 4706 safety standards mandate automatic shut-off mechanisms, extending product development timelines. The Yangtze River Delta hosts the densest concentration of robotic mop assembly, where LiDAR module integration costs have fallen below mid-income price thresholds.
Germany
Healthcare facilities in Bavaria and North Rhine-Westphalia specify steam mops with optimized boiler designs under EU Green Deal efficiency mandates. Ecodesign regulations are phasing out resistive heating elements, compressing margins for assemblers without captive thermal engineering. Stuttgart's industrial testing cluster processes IPX4 certification queues, creating bottlenecks for new market entrants.
United States
Hospital networks route UV-C sanitization procurement through consolidated group purchasing organizations, reducing independent decision points by half over the past decade. EPA antimicrobial kill-rate documentation requirements restrict interstate marketing to substantiated claims. The Southeast corridor shows fastest hospitality sector refresh cycles for infection-control equipment.
India
Swachh Bharat Mission funding creates procurement windows for commercial cleaning equipment in municipal and educational institutions. BIS certification requirements for electrical safety extend product launch timelines. Maharashtra and Gujarat host expanding distribution infrastructure for mid-priced spin mop variants targeting urban middle-income households.
Japan
Metropolitan Tokyo and Osaka prefectures demonstrate highest robotic mop penetration rates outside China, driven by smart home platform integration. METI energy efficiency labeling programs differentiate premium from commodity configurations. Kansai region electronics retailers maintain demonstration capacity for steam boiler performance trials, supporting conversion rates.
Electric Mop Market Vendor Landscape
Player mix skews toward diversified appliance conglomerates with captive manufacturing infrastructure and specialized robotics firms with navigation software competencies. Market structure concentrates around three tiers: premium specification suppliers serving hospitality and healthcare procurement, mass-market assemblers competing on replacement consumable economics, and ecosystem-integrated robotics platforms. Dominant competitive moves include backward integration into injection-molding capacity for solution tanks and strategic partnerships with smart home platform operators.
Among diversified cleaning equipment specialists, Alfred Kärcher SE & Co. KG and BISSELL occupy positions defined by in-house testing laboratory infrastructure and captive manufacturing capabilities respectively. Xiaomi Corporation represents the ecosystem-integrated archetype, embedding robotic mop offerings within broader IoT platform strategies. These three exemplify how competitive positioning diverges between thermal engineering depth, manufacturing scale, and software stack integration.
| Leading Market Players |
|---|
| SharkNinja Operating LLC |
| Alfred Kärcher SE & Co. KG |
| Procter & Gamble |
| Xiaomi Corporation |
| Stanley Black & Decker Inc. |
| Ecovacs Robotics Co Ltd |
| BISSELL |
| HAAN Corporation |
| TTK Prestige Limited |
| Others |
Supply Flow & Price Mechanics
Ninety-day IPX4 certification queues in Stuttgart and Shenzhen compress margin recovery windows for assemblers without captive testing infrastructure, concentrating pricing power with integrated manufacturers who bypass third-party bottlenecks. This lead-time asymmetry stratifies procurement economics: healthcare systems absorb premium pricing for validated UV-C configurations while price-sensitive household segments defect to disposable wet-mop substitutes.
Pricing Analysis
Certification level creates the primary spread between hospitality-grade UV-C units and mass-market spin configurations. Three-tier pricing structure across premium, standard, and economy levels reflects IPX4 validation status, GB 4706 compliance depth, and smart home ecosystem bundling. Cost compression in steam mop tiers is intensifying because EU Ecodesign mandates force resistive heating element redesigns. Dollar-store channels in India and Southeast Asia exhibit highest price sensitivity; hospital group purchasing organizations in the United States show lowest elasticity.
Supply Chain Analysis
Strait of Malacca transit congestion amplifies lithium-ion cell delivery uncertainty for cordless unit assemblers without forward-contracting relationships. Manufacturing gravity centers on China for robotic mop final assembly, Germany for precision boiler components, and Vietnam for injection-molded solution tanks. Raw material dependencies span neodymium magnets for drive motors, polypropylene compounds for housings subject to REACH restrictions, and cobalt-nickel cathode formulations. Single-source vulnerability concentrates in LiDAR module supply. Distribution runs through Amazon and JD.com for household units, specialized healthcare distributors for institutional specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering talent scarcity constrains steam boiler redesign velocity under EU Green Deal mandates, privileging incumbents with captive R&D infrastructure while excluding pure-software robotics entrants from premium hospitality procurement.
For Market Incumbents: Secure captive injection-molding capacity for solution tanks to defend margin position against commodity polymer price swings. Deepen backward integration into boiler component manufacturing to accelerate Ecodesign compliance cycles before third-party testing queues extend further. Channel control through direct sales teams for healthcare accounts remains essential as group purchasing organizations consolidate decision points. For New Entrants and Emerging Players: BIS certification fast-track partnerships with Mumbai testing laboratories unlock Swachh Bharat Mission procurement windows before established competitors localize production. Mid-priced spin mop segments in tier-two Indian cities offer most penetrable white space, with municipal educational institution contracts providing referenceable accounts. Go-to-market through consolidated e-commerce platforms with search-optimized listings bypasses traditional distributor margin stacking. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance conglomerates with underutilized thermal engineering divisions and dormant healthcare sales relationships. Long-term viability favors integrated manufacturers with software stack optionality rather than pure-play hardware assemblers. Signal to monitor: GB 4706.1 testing timeline extensions that would advantage incumbents with established China regulatory affairs infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boiler Manufacturing | Captive thermal engineering accelerates EU Ecodesign compliance before third-party validation queues lengthen. |
| Smart Home Platform Partnership | Xiaomi's IoT ecosystem integration demonstrates subscription consumable replenishment economics in Chinese tier-one cities. |
| Healthcare Direct Sales Expansion | Kärcher's field sales teams for hospital accounts illustrate margin protection against group purchasing organization compression. |
| India BIS Certification Localization | Swachh Bharat Mission municipal funding creates procurement windows for validated commercial equipment. |
| IPX4 Testing Laboratory Investment | Alfred Kärcher's in-house Stuttgart facilities bypass German and Chinese third-party bottlenecks. |
Methodological Framework
Desk research of customs trade records, EU Ecodesign regulatory filings, and hospital procurement databases preceded structured interviews with plant engineers at boiler component manufacturers, category buyers at big-box retailers, regulatory affairs leads at appliance conglomerates, and maintenance directors at hospitality operators. Primary fieldwork validated secondary data on LiDAR module cost trajectories and GB 4706 testing timelines. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, cleaning technology, end-user segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price movements. Industry-specific forecast inputs included municipal subsidy program announcements in Chinese tier-one cities and group purchasing organization consolidation metrics in United States healthcare networks.
Decision-makers should treat outputs as directional under assumptions of sustained lithium-ion raw material price volatility and stable EU Green Deal implementation timelines; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as REACH restriction expansion and India BIS enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Manual Bottle Opener Market
Household Items
Electric Shoe Polisher Market
Household Items
North America Car Air Freshener Market
Household Items
Bristle Brush Market
Household Items
Commercial Locker Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Global Buddhist Supplies Market
Household Items
Laundry Detergent Sheets Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
North America Tankless Water Heater Market
Household Items
Wet Wipes and Toilet Paper Market
Household Items
US Air Purifier Market
Household Items
Smart Connected Water Purifier Market
Household Items
Global Sports Bottle Market
Household Items
Portable Air Humidifier and Dehumidifier Market