
 Smart Bathtub Market | 2026-2036
Smart Bathtub Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bathtub Market Insights
Plumbing-electrical crossover talent is redrawing competitive boundaries in the smart bathtub sector. Kohler Co. leverages its captive foundry network to control cast iron supply for premium connected tubs. TOTO Ltd. anchors its position through deep R&D integration between its ceramic and electronic control divisions. LIXIL Group Corporation competes by dominating Japanese distribution channels for intelligent bathroom systems.
A smart bathtub integrates electronically controlled water management, sensor-based temperature regulation, and network connectivity into a fixed sanitary vessel, typically manufactured through thermoformed acrylic shell bonding or enameled cast iron pouring with embedded heating elements. Its primary purpose is to deliver personalized hydrotherapy, automated fill-and-drain cycles, and energy-optimized bathing for residential and commercial wellness environments. Freestanding units command the highest margin pools due to their sculptural positioning in luxury interiors, while hydrotherapy technology leads volume growth as aging populations seek home-based therapeutic alternatives. Acrylic dominates material selection for mid-market expansion because of its thermal retention properties and moldability for integrated jet housings.
The US EPA WaterSense program and the EU Ecodesign Directive jointly constrain flow-rate specifications for electronically controlled bathing fixtures, forcing manufacturers to redesign pump and valve architectures for compliance across both jurisdictions. Japan's METI energy-labeling standards add a third certification layer for products targeting its high-end residential segment. Stakeholders must monitor divergence between regional connectivity protocols as Matter, KNX, and proprietary home automation standards fragment the addressable installed base.
Market Dynamics
Plumbing-electrical crossover talent scarcity is compressing product development cycles across the smart bathtub sector. Manufacturers now compete primarily on integrated system architecture rather than standalone fixture quality.
Growth Catalysts
- EU Ecodesign Directive:Tightening water-efficiency thresholds for electronically controlled sanitary fixtures are accelerating pump and valve redesign investments across European manufacturing bases.
- Aging demographics:Home-based therapeutic alternatives are displacing clinical hydrotherapy visits in Japan, Germany, and the United States, expanding residential installation rates.
- Rhine-Ruhr metropolitan cluster:Premium bathroom renovation activity in this German hub outpaces broader European averages, concentrating demand for connected bathing systems.
Market Restraints
- Cast iron supply concentration:Captive foundry networks controlled by vertically integrated incumbents limit material access for mid-market entrants seeking premium positioning.
- Connectivity protocol fragmentation:Divergence between Matter, KNX, and proprietary home automation standards fragments the addressable installed base and inflates SKU complexity.
- Acrylic resin price volatility:Petrochemical feedstock fluctuations directly impact thermoformed shell production costs for mid-market acrylic units.
Strategic Opportunities
- Saudi Arabia luxury residential:Riyadh and Jeddah developers are specifying connected bathing systems at rates unmatched elsewhere in the Middle East, creating white space for system integrators.
- Preventive health integration:Convergence of biometric sensors and hydrotherapy controls enables physician-prescribed home wellness protocols, opening reimbursement-adjacent revenue streams.
- WaterSense certification leverage:US EPA program compliance creates differentiated positioning in California and Arizona markets facing municipal usage restrictions.
Industry Challenges
- Mechatronics talent pipeline:Combined plumbing-electrical-electronic skill sets remain scarce in vocational training systems across all major manufacturing geographies.
- Triple certification burden:Simultaneous compliance with EU Ecodesign, US WaterSense, and Japan METI energy-labeling extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bathtub Market |
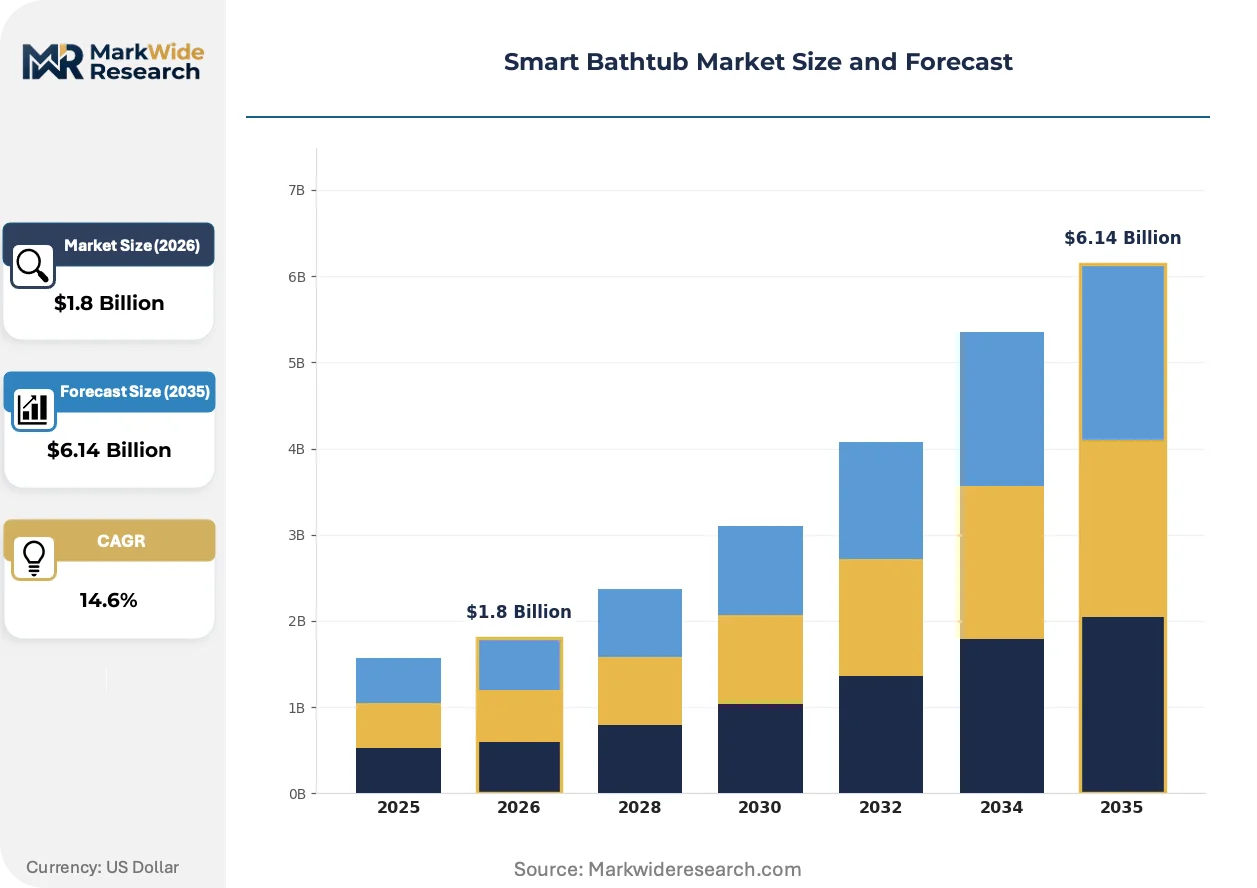
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Undermount, Drop-in, Corner Technology: Smart Controls, Automated Filling, Hydrotherapy, LED Lighting Material: Acrylic, Fiberglass, Cast Iron, Stone End User: Residential, Hotels, Spas, Wellness Centers |
| Companies Covered | Kohler Co., TOTO Ltd., LIXIL Group Corporation, Roca Sanitario S.A., Duravit AG, Grohe AG, American Standard Brands, Villeroy & Boch AG, Moen Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bathtub Market Trends and Innovations
Sensor fusion and embedded intelligence are redefining what constitutes a bathing fixture. The competitive frontier has shifted from water containment to data-driven personalization and predictive maintenance capabilities.
Solid-state heating elements are miniaturizing thermal management systems within freestanding and built-in tub architectures. Luxury residential developers in Dubai and Miami are specifying these systems for their reduced footprint and faster temperature response curves. The technology is miniaturizing control enclosures, enabling sculptural shell designs previously incompatible with conventional heating hardware.
The EU Ecodesign Directive's 2027 water-efficiency thresholds are forcing pump architecture redesigns across all electronically controlled bathing fixtures. Manufacturers serving both European and North American markets must engineer dual-compliance valve systems, adding engineering overhead but creating regulatory moats against single-market competitors. German and Italian producers are responding fastest, leveraging existing appliance-sector compliance infrastructure.
Wellness-oriented buyers now demand outcome documentation rather than feature checklists. This behavioral pivot pressures traditional showroom channels and favors direct-to-consumer configurators with integrated telehealth partnerships. The shift is most visible in Japan's senior housing sector, where facility operators select suppliers based on fall-risk reduction data rather than jet count or finish options.
Smart Bathtub Market Segmentation
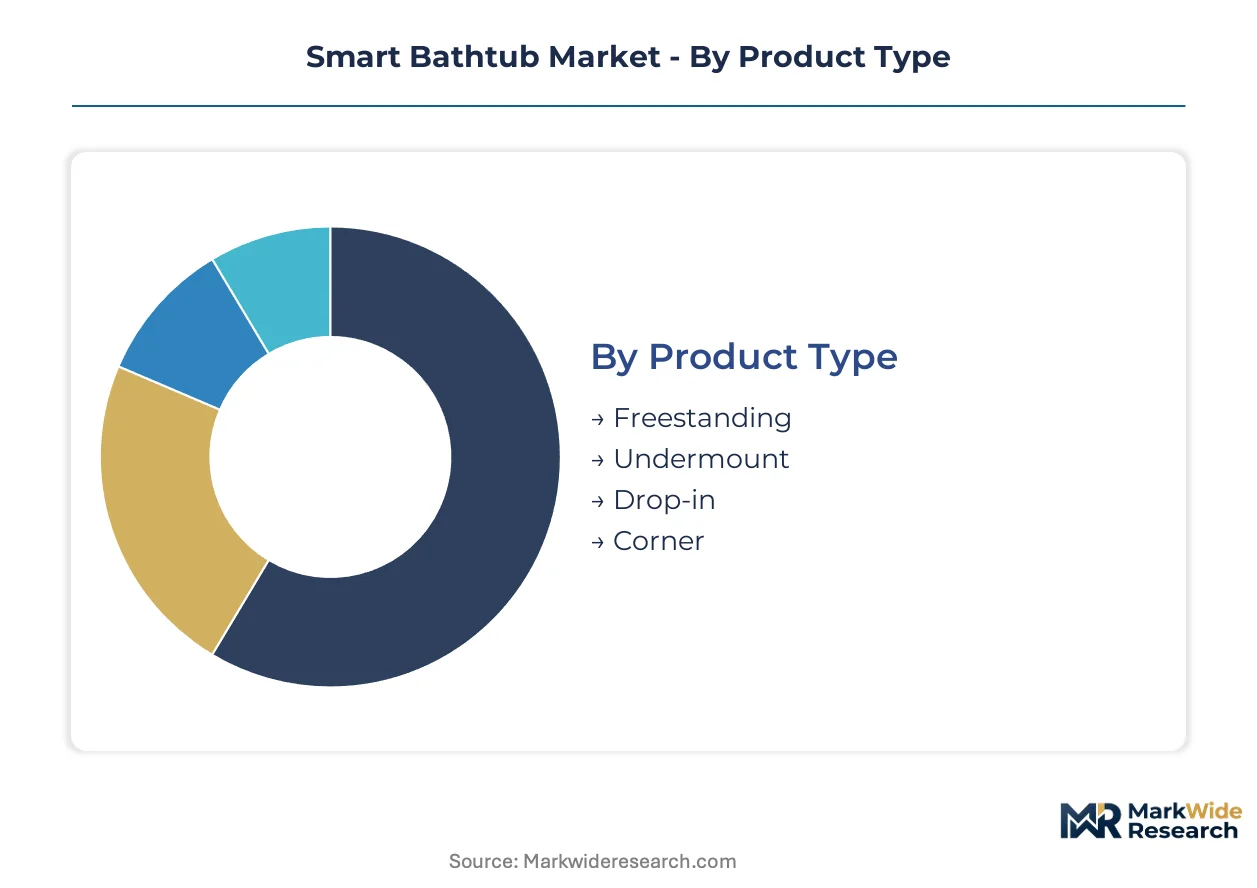
Smart bathtub segmentation reveals how regulatory compliance costs, installation constraints, and end-user wellness requirements fragment addressable demand. Manufacturers must align product architectures with specific certification burdens and channel economics rather than pursuing universal platform strategies.
Product Type:
EU Ecodesign water-efficiency thresholds apply unevenly across installation configurations, with freestanding units facing distinct testing protocols for electronically controlled fill-and-drain systems compared to built-in alternatives.
- Freestanding:Sculptural shell designs with embedded solid-state heating elements command premium positioning in luxury residential developments. Dubai and Riyadh developers specify these units at unmatched rates, driven by architectural visibility and reduced footprint requirements.
- Undermount:Deck-integrated installations dominate premium bathroom renovation activity in Germany's Rhine-Ruhr cluster, where seamless countertop continuity outweighs freestanding aesthetic preferences.
- Drop-in:Alcove-compatible units serve mid-market replacement cycles with lower installation complexity.
- Corner:Spatially optimized configurations address compact urban residential footprints in Japanese and Korean markets.
Freestanding handles the majority of throughput; Corner is gaining share fastest among space-constrained metropolitan installations.
Technology:
Cost tier stratification separates physician-prescribed therapeutic systems from convenience-oriented automation features, with reimbursement eligibility determining engineering investment levels.
- Hydrotherapy:Jet-integrated systems with sensor-based temperature regulation serve aging populations seeking home-based alternatives to clinical visits. Japan's senior housing operators select suppliers based on fall-risk reduction data rather than jet specifications.
- Smart Controls:Network-connected water management interfaces face protocol fragmentation between Matter, KNX, and proprietary standards, inflating SKU complexity for multi-market manufacturers.
- Automated Filling:Preset fill-and-drain cycles reduce water waste for EPA WaterSense compliance in California and Arizona markets facing municipal restrictions.
- LED Lighting:Chromotherapy integration adds marginal cost with limited regulatory differentiation.
Hydrotherapy handles the majority of throughput; Smart Controls is expanding most quickly as connectivity standardization efforts progress.
Material:
Supply concentration in captive foundry networks and petrochemical feedstock chains creates divergent margin structures across material categories.
- Acrylic:Thermoformed shells with integrated jet housings dominate mid-market expansion due to thermal retention properties and moldability. Resin price volatility directly impacts production costs for volume manufacturers.
- Cast Iron:Enameled vessels with embedded heating elements remain supply-constrained by vertically integrated incumbents controlling foundry access.
- Fiberglass:Lower-cost alternative for price-sensitive renovation segments with reduced thermal mass.
- Stone:Solid-surface and natural stone variants serve ultra-premium custom installations with extended lead times.
Acrylic handles the majority of throughput; Cast Iron is climbing the fastest on share despite supply constraints.
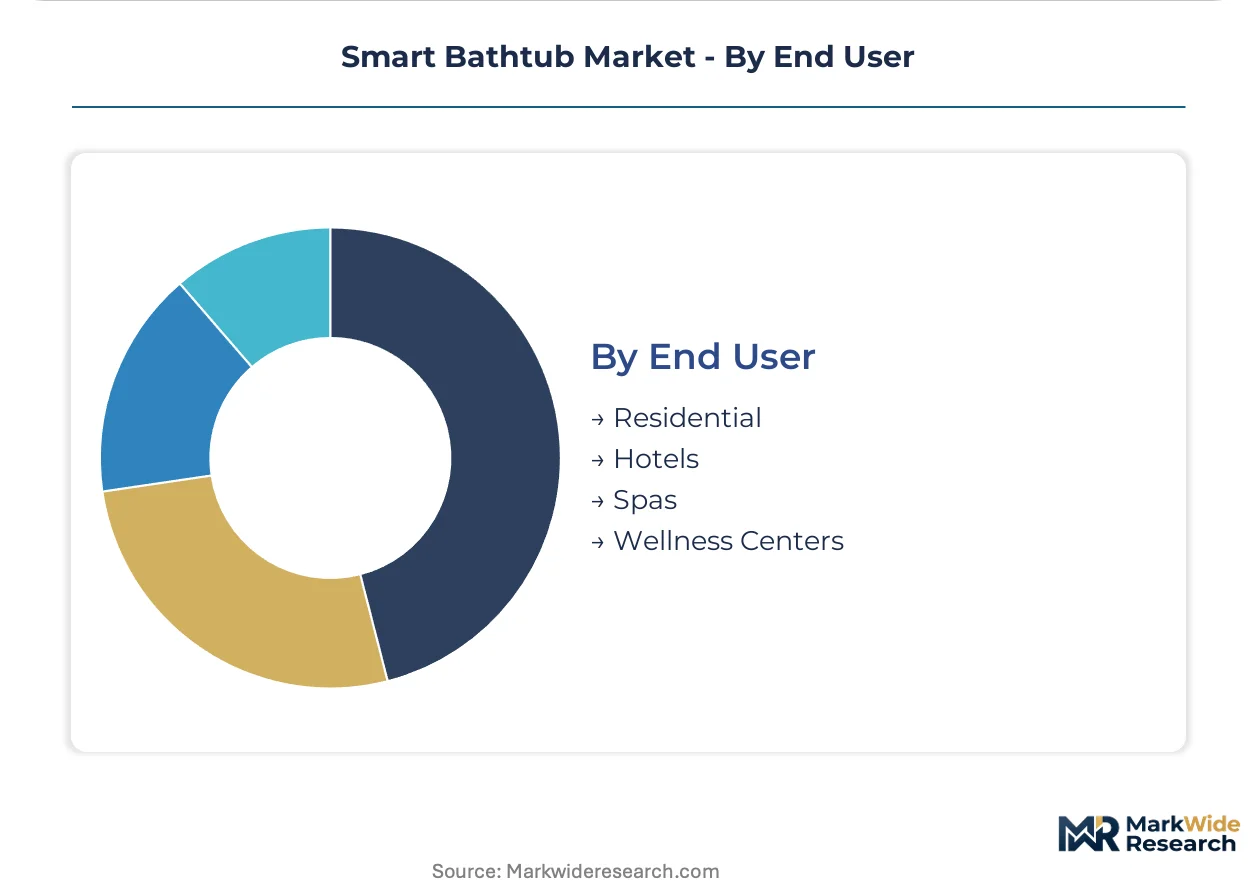
End User:
Application maturity separates established residential replacement demand from emerging wellness-center procurement patterns with distinct specification requirements.
- Residential:Personalized hydrotherapy and energy-optimized bathing drive replacement cycles in Germany, Japan, and the United States. Aging demographics expand installation rates for therapeutic home alternatives.
- Hotels:Luxury hospitality specifications in Dubai and Miami prioritize solid-state heating for faster temperature response and reduced mechanical footprint.
- Spas:Commercial hydrotherapy operations demand outcome documentation and predictive maintenance capabilities over feature checklists.
- Wellness Centers:Preventive health integration with biometric sensors enables physician-prescribed protocols and reimbursement-adjacent revenue streams.
Residential handles the majority of throughput; Wellness Centers is showing the steepest expansion trajectory as health system cost pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between wellness-integrated markets and infrastructure-driven installations. Japan and Germany prioritize therapeutic outcomes and energy efficiency. The United States and Gulf states emphasize luxury positioning and architectural visibility.
United States
California and Arizona municipalities enforce municipal usage restrictions that elevate EPA WaterSense-certified fixtures. The EPA program creates differentiated positioning for compliant manufacturers. Los Angeles and Phoenix metropolitan clusters drive premium replacement cycles.
Germany
The Rhine-Ruhr metropolitan cluster concentrates premium bathroom renovation activity above broader European averages. The EU Ecodesign Directive tightens water-efficiency thresholds for electronically controlled sanitary fixtures. Stuttgart and Munich engineering bases accelerate pump and valve redesign investments.
Japan
Aging demographics displace clinical hydrotherapy visits with home-based therapeutic alternatives. METI energy-labeling standards add certification requirements for high-end residential segments. Tokyo and Osaka senior housing operators select suppliers based on fall-risk reduction data.
Saudi Arabia
Riyadh and Jeddah luxury residential developers specify connected bathing systems at unmatched Middle Eastern rates. The country's national building regulator aligns with Gulf standardization initiatives. NEOM and Red Sea Project developments anchor demand concentration.
United Arab Emirates
Dubai developers prioritize solid-state heating elements for reduced mechanical footprint and faster temperature response. MOHAP facility standards influence wellness-center procurement patterns. Downtown Dubai and Palm Jumeirah residential towers concentrate high-value installations.
Smart Bathtub Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the smart bathtub sector. Vertically integrated incumbents control captive foundry networks for cast iron supply, compressing material access for mid-market entrants. Plumbing-electrical crossover specialists and ceramic-electronic integrators represent the dominant strategic archetypes. Competitive moves center on R&D integration between material and control divisions and distribution channel dominance for intelligent bathroom systems.
Within the integrated leader tier, Kohler Co. and TOTO Ltd. exemplify divergent pathway dominance. Kohler's North American positioning reflects captive supply chain control over premium vessel materials. TOTO anchors Japanese market architecture through deep operational integration between ceramic fabrication and electronic control development. LIXIL Group Corporation occupies a distribution-focused position, channeling intelligent bathroom systems through concentrated domestic retail networks.
| Leading Market Players |
|---|
| Kohler Co. |
| TOTO Ltd. |
| LIXIL Group Corporation |
| Roca Sanitario S.A. |
| Duravit AG |
| Grohe AG |
| American Standard Brands |
| Villeroy & Boch AG |
| Moen Incorporated |
| Others |
Pricing and Supply Chain Analysis
Captive foundry utilization rates at vertically integrated incumbents set price floors for enameled cast iron vessels, compressing margin headroom for mid-market acrylic producers facing simultaneous petrochemical feedstock volatility. Scale advantages in thermoformed shell production concentrate among German and Chinese manufacturers, while EU Ecodesign compliance investments add fixed-cost layers that stratify competitive tiers.
Pricing Analysis
Long-term offtake contracts dominate premium cast iron procurement, locking in material access for incumbents while spot-market acrylic resin exposure leaves mid-tier manufacturers vulnerable to price swings. Three-tier pricing structure across premium, standard, and economy levels separates WaterSense-certified systems from basic automated filling units and luxury biometric-integrated installations. Cost compression in the acrylic segment is intensifying because resin suppliers pass through naphtha-indexed adjustments quarterly. Budget-conscious renovation buyers in Germany's Rhine-Ruhr cluster exhibit highest price sensitivity, whereas wellness-center procurement committees in Dubai prioritize outcome documentation over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites petrochemical feedstock flows for Asian acrylic resin producers, exposing shell manufacturers to geopolitical logistics disruption. Manufacturing concentrates in Germany, China, and Japan for electronically controlled valve assemblies and solid-state heating elements. Supply chains draw from South Korean pump motor specialists, Italian ceramic foundries, and Taiwanese sensor fabricators. Single-source vulnerability concentrates in enameled cast iron pouring capacity controlled by Kohler's captive network. Distribution runs through specialist bathroom retailers in Japan, luxury developer specification channels in the Gulf, and direct-to-consumer configurators in North American wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics talent scarcity across plumbing-electrical-electronic disciplines constrains product development velocity, rewarding firms that internalize cross-functional capabilities or lock in vocational pipeline partnerships.
For Market Incumbents: Compound captive foundry advantages by expanding enameled cast iron capacity for the premium connected tub segment before mid-market entrants secure alternative vessel suppliers. Deepen backward integration into solid-state heating element sourcing to offset Korean component lead time variability. Prioritize EU Ecodesign pre-compliance engineering to capture Rhine-Ruhr renovation demand ahead of regulatory deadlines. For New Entrants and Emerging Players: Differentiate on preventive health integration by partnering with telehealth platforms to deliver physician-prescribed hydrotherapy protocols reimbursable through Japanese senior housing operators. Target Saudi Arabia's NEOM and Red Sea Project developments where luxury residential specifications for connected bathing systems outpace installed supplier capacity. Pursue direct-to-consumer configurators with integrated biometric sensor partnerships to bypass showroom channel gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic-electronic integrators with proven R&D handoffs between material and control divisions over pure-play plumbing fixture manufacturers. Acquisition candidates with METI energy-labeling approvals and existing Japanese distribution relationships offer strongest long-term viability as home-based therapeutic alternatives displace clinical visits. Watch for convergence between Matter protocol standardization progress and SKU complexity reduction as inflection signal for multi-market manufacturer margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Mechatronics Talent Pipeline Development | Cross-functional skill acquisition compresses product development cycles for integrated system architectures. |
| EU Ecodesign Pre-Compliance Engineering | Early pump and valve redesign investments capture Rhine-Ruhr renovation demand concentration. |
| Telehealth Platform Partnership | Physician-prescribed protocol integration opens reimbursement-adjacent revenue streams in Japanese senior housing. |
| Solid-State Heating Vertical Integration | In-house thermal element production reduces Korean component dependency for Dubai luxury specifications. |
| Matter Protocol Certification | Connectivity standardization lowers SKU complexity across fragmented North American home automation installed base. |
Research Methodology
Operator-level perspectives from plumbing-electrical contractors, luxury residential developers, senior housing facility operators, wellness-center procurement committees, and ceramic foundry managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed bathroom fixture manufacturers, EU Ecodesign directive implementation guidance, METI energy-labeling standard documentation, and trade flow data for acrylic resin and cast iron feedstocks. Bottom-up unit economics modeling triangulated against top-down market sizing across installation type, technology tier, material category, and end-use application.
Sensitivity analysis tested forecast outputs against variable regulatory enforcement timelines, petrochemical price trajectory assumptions, and connectivity protocol adoption curves across the projection horizon. Segmentation dimensions modeled include product installation configuration, hydrotherapy versus automation technology tier, vessel material category, and regional certification cluster. CAGRs derived from fitted growth curves applied to replacement cycle frequencies, new construction permit flows, and wellness-center capital expenditure patterns. Industry-specific inputs incorporated EPA WaterSense compliance rates and Japanese senior housing operator specification surveys.
Material uncertainties — regulatory divergence between EU, US, and Japanese certification regimes, acrylic resin price volatility, and Matter protocol adoption timing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding demographic aging trajectories and luxury residential development pipelines. Practitioners should keep alternative scenarios live as Gulf state building regulator alignment with international standardization initiatives evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Dosage Spoon Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Oman Gas Hobs Market
Household Items
Liquid Hand Soap Market
Household Items
Global Sports Bottle Market
Household Items
Toilet Hygiene Products Market
Household Items
Memory Foam Market
Household Items
Porcelain Tableware Market
Household Items
Portable Iron Market
Household Items
Fine Mist Sprayer Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Party Balloon Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Cutlery Market