
 Aviation Transaction Blockchain Market | 2026-2036
Aviation Transaction Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Transaction Blockchain Market Analysis
Project finance tied to aircraft operating lease securitization is narrowing the competitive field for blockchain infrastructure providers, as lessors demand immutable title-transfer records and automated covenant monitoring. IBM Corporation leverages its enterprise blockchain stack to anchor compliance workflows for lessor portfolios across multiple jurisdictions. Winding Tree specializes in decentralized distribution protocols that compete with legacy global distribution systems, while Honeywell Aerospace extends its avionics data pedigree into engine-hour verification on distributed ledgers.
Aviation transaction blockchain denotes cryptographically linked distributed databases engineered to record, validate, and settle aerospace-related exchanges without centralized intermediaries, typically employing consensus mechanisms with sub-second finality thresholds for high-frequency payment corridors. Its primary commercial purpose centers on eliminating reconciliation lag between airlines, lessors, MRO providers, and financiers while creating tamper-evident audit trails for regulatory examination. Smart contracts within the technology segment automate escrow release and penalty calculation, capturing margin pools from manual legal review; payment processing applications are expanding fastest as carriers seek to disintermediate card networks and foreign exchange markups on international route revenue. Private blockchain deployments dominate among financial institutions requiring permissioned participant lists and configurable privacy tiers for sensitive lease terms.
The FAA mandates airworthiness documentation standards that increasingly reference immutable record-keeping, while the EU's DORA framework imposes operational resilience testing on financial infrastructure serving European carriers. ISO 27001 and SOC 2 Type II certifications function as de facto market access prerequisites for blockchain vendors targeting airline IT procurement committees. Stakeholders must evaluate whether their consensus architecture can satisfy divergent data-sovereignty requirements across the transatlantic corridor without fragmenting network effects.
Market Dynamics
Immutable audit mandates from the EU's DORA framework and FAA documentation standards are compressing settlement cycles between airlines, lessors, and MRO providers while forcing infrastructure providers to architect cross-jurisdictional compliance layers.
Growth Catalysts
- Loyalty Program Interoperability:Airlines are deploying blockchain rails to enable point redemption across carrier networks, eliminating manual reconciliation between disparate legacy systems.
- DORA Compliance Mandates:The EU's Digital Operational Resilience Act requires immutable transaction logs for financial infrastructure serving European carriers, directly elevating distributed ledger procurement priorities.
- Cross-Border Payment Disintermediation:Carriers are routing international route revenue through blockchain corridors to bypass card network fees and foreign exchange markups on high-frequency payment corridors.
Market Restraints
- Data Sovereignty Fragmentation:Divergent storage requirements across the transatlantic corridor force network architects to maintain jurisdiction-specific node configurations, eroding economies of scale.
- Consensus Latency Thresholds:Sub-second finality requirements for high-frequency aviation payment corridors strain permissioned blockchain architectures during peak transaction windows.
- Legacy System Integration Costs:SAP and Oracle ERP environments dominant in airline IT stacks require expensive middleware layers to interface with distributed ledger backends.
Strategic Opportunities
- Engine-Hour Verification Markets:MRO providers and lessors are piloting distributed ledger protocols for tamper-evident flight cycle logging, creating new revenue pools from maintenance forecasting data.
- Automated Covenant Monitoring:Smart contract escrow release and penalty calculation is capturing margin pools previously allocated to manual legal review in aircraft operating lease structures.
- Sustainable Aviation Fuel Tracking:Blockchain-based provenance systems for SAF certificates are emerging as carriers face Scope 3 emissions disclosure requirements under CSRD.
Industry Challenges
- Distributed Systems Talent Scarcity:Airlines and lessors face acute shortages of engineers capable of architecting Byzantine fault-tolerant consensus mechanisms for financial-grade workloads.
- Multi-Jurisdictional Certification Timelines:ISO 27001 and SOC 2 Type II audits for aviation blockchain vendors stretch 12-18 months, delaying procurement committee approvals.
- Interoperability Standard Delays:Absence of unified protocols between private permissioned networks and public settlement rails fragments liquidity and complicates counterparty onboarding.
Report Scope
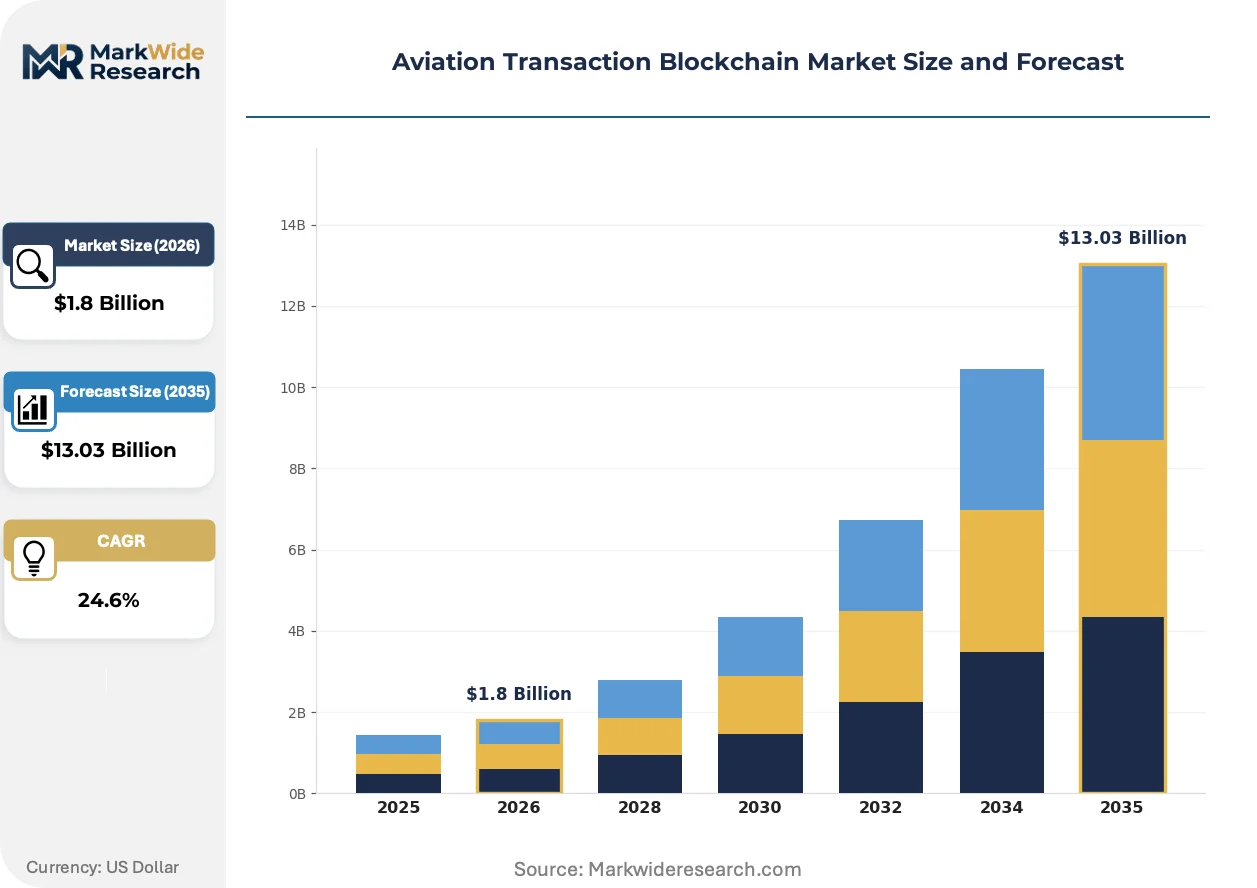
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Transaction Blockchain Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Contracts, Distributed Ledger, Public Blockchain, Private Blockchain Application: Supply Chain Management, Asset Tracking, Payment Processing, Regulatory Compliance End User: Airlines, Maintenance Providers, Aircraft Manufacturers, Financial Institutions Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Managed Services |
| Companies Covered | IBM Corporation, Microsoft Corporation, Infosys Limited, Zamna Technologies, Aeron Labs, Winding Tree, LeewayHertz Technologies, Moog Inc., Honeywell Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Transaction Blockchain Market Emerging Trajectories
Settlement infrastructure is migrating from batch-processed reconciliation to continuous finality, compressing working capital cycles and rewiring competitive advantage toward real-time data fidelity rather than relationship-based trust.
Zero-knowledge proof architectures are virtualizing privacy-preserving verification for sensitive lease terms, enabling lessors to share portfolio performance data with financiers without exposing counterparty identities. Major operating lessors in Dublin and Singapore are piloting these circuits for securitization due diligence. The technology is virtualizing the due diligence bottleneck that previously constrained portfolio aggregation speed.
REACH and EU AI Act compliance requirements are mandating algorithmic transparency for automated decision systems in aviation finance, forcing blockchain vendors to embed explainable smart contract modules. Industrial consequence includes elevated R&D allocation toward auditable oracle networks. European carriers and their lessor counterparts are most affected, responding through consortium-led standardization working groups.
Buyer concentration among top-twenty global lessors is compressing vendor evaluation cycles and privileging incumbents with existing FAA and EASA certification relationships. Procurement committees now require live pilot demonstrations rather than white-paper assessments, shifting vendor selection criteria toward operational resilience testing. This pattern is most visible in the United States, where FAA modernization initiatives have accelerated enterprise-grade procurement timelines.
Aviation Transaction Blockchain Market Segmentation
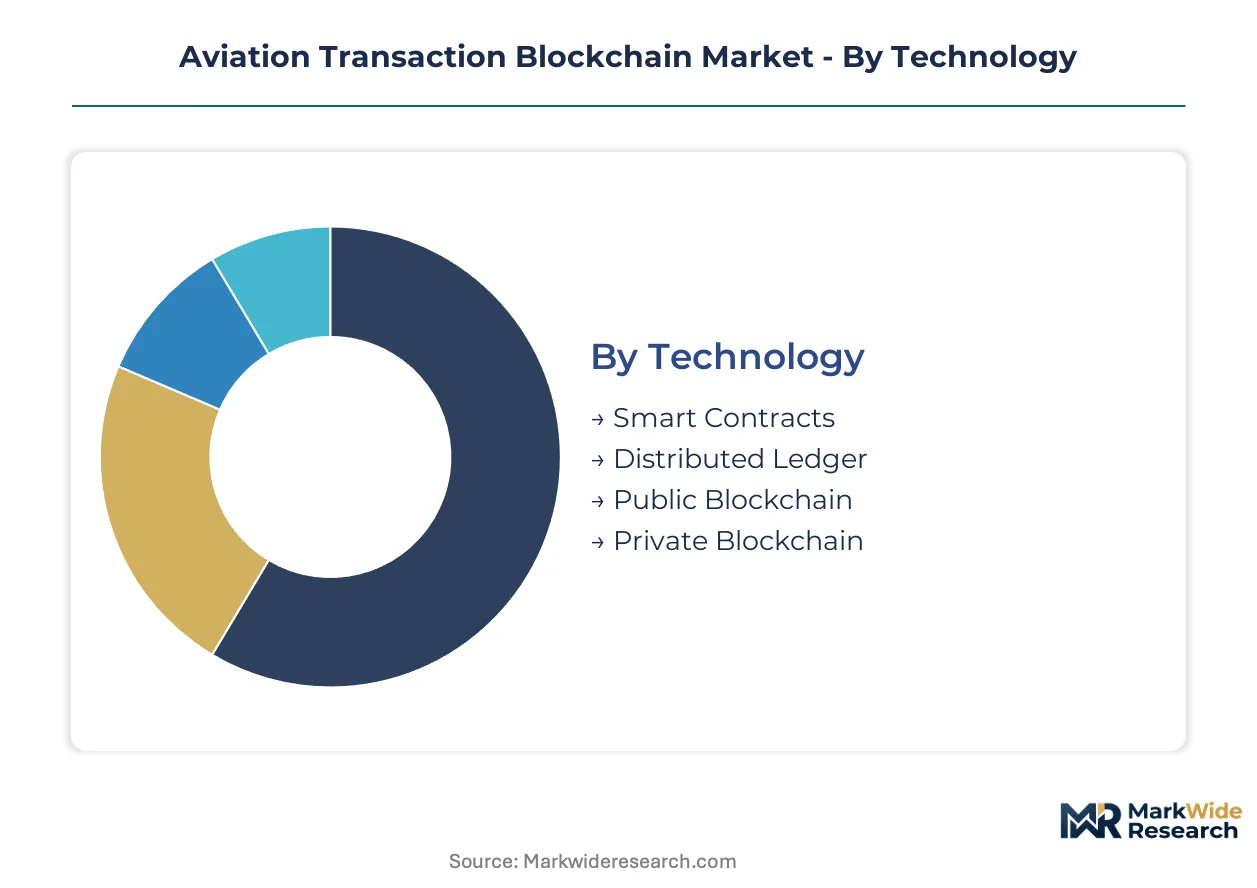
Segmentation in aviation blockchain reveals divergent commercial rhythms across technology layers and operational contexts. Smart contract automation compresses settlement cycles to sub-second finality, while regulatory compliance applications move through extended certification timelines. Understanding these velocity differentials shapes vendor resource allocation and partnership prioritization.
Technology:
Cycle times vary dramatically across technology segments, with some achieving production deployment in months while others require multi-year standardization efforts.
- Smart Contracts:Self-executing code modules automate escrow release, penalty calculation, and covenant monitoring without intermediary legal review. Airlines and lessors in the United States deploy these for lease securitization workflows, driven by FAA documentation standards that increasingly reference immutable record-keeping.
- Private Blockchain:Permissioned networks with configurable privacy tiers dominate financial institution procurement, enabling sensitive lease term protection while maintaining regulatory audit access. EU carriers favor these deployments under DORA's operational resilience mandates, which require immutable transaction logs for financial infrastructure.
- Distributed Ledger:Cryptographically linked databases provide the foundational architecture for cross-carrier settlement reconciliation and loyalty program interoperability.
- Public Blockchain:Open settlement rails attract payment processing innovators seeking to disintermediate card networks on international route revenue.
Private blockchain anchors the volume base while smart contracts gain share at the steepest rate.
Application:
Cost tiers stratify sharply, with infrastructure-heavy deployments commanding premium pricing against lightweight compliance modules.
- Payment Processing:Blockchain corridors route high-frequency aviation payments to bypass foreign exchange markups and card network fees. Carriers across transatlantic routes concentrate procurement here, compelled by working capital compression targets and real-time settlement finality requirements.
- Supply Chain Management:End-to-end visibility systems track components from manufacturer through MRO provider to airframe installation. The EU's CSRD disclosure requirements for Scope 3 emissions accelerate adoption, particularly for sustainable aviation fuel certificate provenance tracking.
- Asset Tracking:Tamper-evident logging of flight cycles and engine hours supports predictive maintenance forecasting for lessor portfolios.
- Regulatory Compliance:Automated audit trail generation satisfies FAA documentation standards and DORA immutable log mandates with minimal manual intervention.
Supply chain management captures the largest implementation spend while payment processing expands most quickly.
End User:
Customer type determines procurement authority cycles, with financial institutions running longest evaluation timelines against airline operational urgency.
- Airlines:Primary demand centers for loyalty interoperability, cross-border payment disintermediation, and real-time settlement infrastructure. US carriers lead enterprise-grade adoption through FAA modernization initiative participation and private consortium engagement.
- Financial Institutions:Lessors and aviation financiers require immutable title-transfer records and automated covenant monitoring for operating lease securitization. These stakeholders command the most stringent certification requirements, stretching vendor approval timelines.
- Maintenance Providers:MRO operators pilot engine-hour verification protocols to monetize maintenance forecasting data.
- Aircraft Manufacturers:OEMs explore distributed ledger integration for component provenance and airworthiness documentation.
Financial institutions anchor the volume base while airlines gain share at the steepest rate.
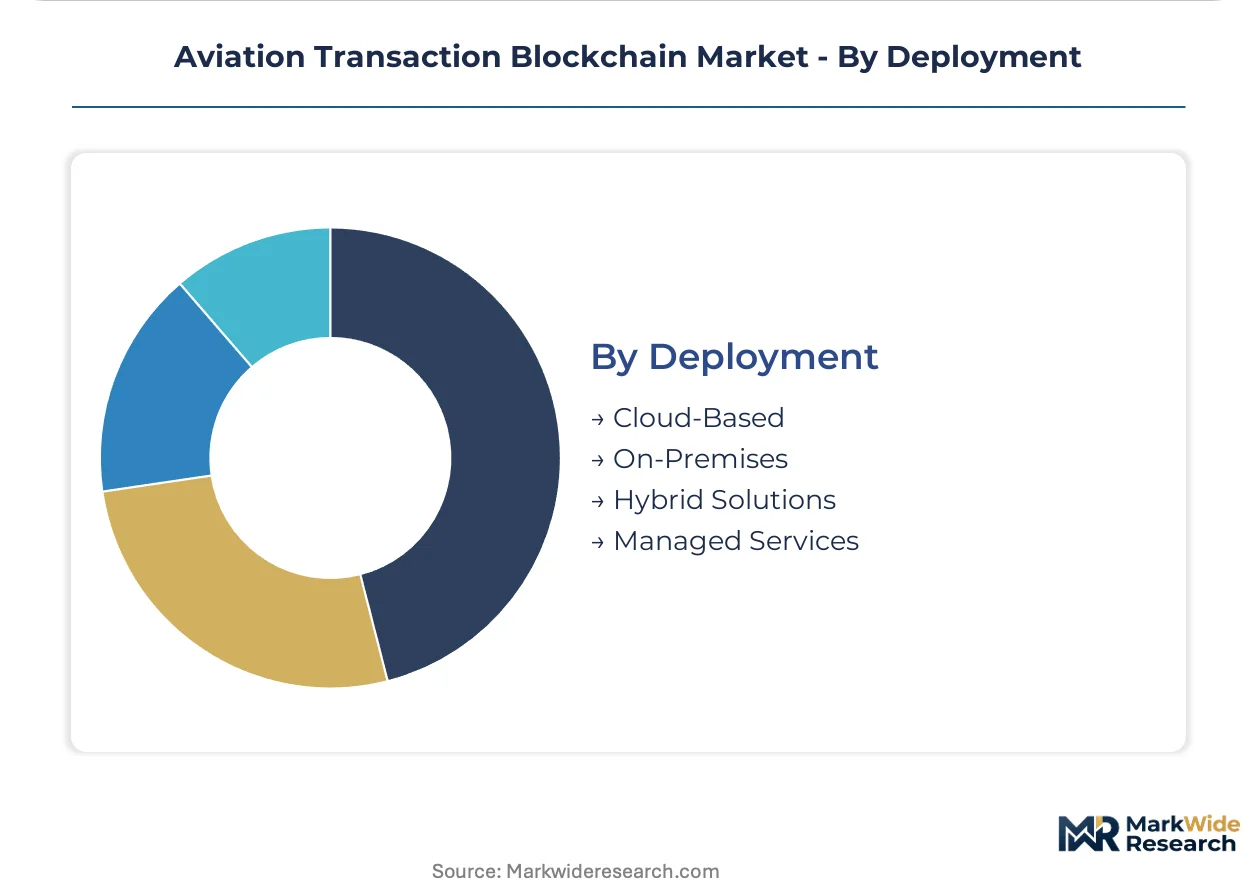
Deployment:
Maturity levels diverge, with cloud-native solutions achieving production scale against on-premises installations constrained by legacy ERP integration complexity.
- Cloud-Based:Scalable infrastructure enables rapid network expansion without capital-intensive hardware deployment. Mid-size carriers and regional lessors favor this model for loyalty program interoperability pilots, constrained by data sovereignty requirements that force jurisdiction-specific node configurations.
- Hybrid Solutions:Split architectures balance sensitive data on-premises with settlement logic in cloud environments. Major US lessors pursuing cross-jurisdictional compliance layers concentrate procurement here, managing divergent transatlantic storage mandates.
- On-Premises:Fully captive infrastructure serves carriers with strict data residency requirements or classified operational needs.
- Managed Services:Outsourced node operation and consensus management reduce internal distributed systems talent requirements.
Cloud-based deployment anchors the volume base while hybrid solutions gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation blockchain infrastructure flows disproportionately toward jurisdictions with dense lessor populations and stringent documentation mandates. Trade surplus in aviation financial services concentrates demand in specific regulatory environments.
United States
FAA modernization initiatives and private carrier consortiums accelerate enterprise-grade procurement. The FAA mandates airworthiness documentation standards that increasingly reference immutable record-keeping. Dallas and Miami host dense clusters of operating lessors piloting smart contract escrow for lease securitization workflows.
Ireland
Dublin's aircraft leasing hub generates concentrated demand for cross-jurisdictional compliance layers. EU DORA frameworks impose operational resilience testing on financial infrastructure serving European carriers. The city's lessor community pilots zero-knowledge proof architectures for portfolio performance data sharing with financiers.
Singapore
The city-state's aviation finance sector drives demand for real-time settlement finality across Asian route networks. Monetary Authority of Singapore guidelines on digital asset infrastructure influence procurement specifications. Changi Aviation Park clusters MRO providers testing engine-hour verification protocols on distributed ledgers.
Germany
Lufthansa Group carriers and Frankfurt-based financiers anchor continental European adoption. REACH and EU AI Act compliance requirements mandate algorithmic transparency for automated decision systems in aviation finance. Munich's industrial corridor hosts consortium-led standardization working groups for explainable smart contract modules.
United Arab Emirates
Dubai International Financial Centre regulations attract aviation blockchain vendors targeting Middle Eastern carrier networks. The country's national aviation regulator emphasizes operational resilience testing for financial infrastructure. Dubai South's aviation district clusters lessors exploring hybrid cloud deployments for sensitive lease term protection.
Aviation Transaction Blockchain Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in consensus architecture and cryptographic verification. The vendor base stratifies between enterprise technology conglomerates with existing FAA certification relationships and specialized distributed ledger developers. Three archetypes dominate: enterprise platform providers, decentralized distribution protocol developers, and avionics-to-blockchain extenders. Competitive moves concentrate on consortium participation for standard-setting and middleware development for legacy ERP integration.
Among enterprise platform providers, IBM Corporation and Microsoft Corporation occupy positions anchored by enterprise blockchain stacks and cloud infrastructure scale. Winding Tree exemplifies the decentralized distribution protocol archetype, sitting within the challenger tier competing with legacy global distribution systems. Honeywell Aerospace represents avionics-to-blockchain extension, leveraging pedigree in engine data logging for distributed ledger verification markets.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Infosys Limited |
| Zamna Technologies |
| Aeron Labs |
| Winding Tree |
| LeewayHertz Technologies |
| Moog Inc. |
| Honeywell Aerospace |
| Others |
Supply Flow & Price Mechanics
Regulatory chokepoint exposure through divergent transatlantic data-sovereignty mandates determines both three-tier pricing spreads across certification levels and supply chain fragmentation into jurisdiction-specific node configurations. FAA and EU DORA compliance layers force infrastructure vendors to maintain parallel hardware deployments, compressing margin pools at the standard tier while premium-certified deployments capture scarcity rents.
Pricing Analysis
Industrial OEM buyers anchor a subscription-SaaS tiered structure with premium-mid-economy pricing differentiation across ISO 27001 and SOC 2 Type II certification levels. Price differentiation stems from audit trail granularity and cross-jurisdictional compliance coverage breadth. Cost compression in the standard tier is intensifying because mid-size carriers demand cloud-native deployments without captive infrastructure overhead. Regional lessors exhibit highest price sensitivity due to working capital constraints, while top-twenty global lessors show lowest sensitivity given securitization timeline pressures.
Supply Chain Analysis
Export-control restrictions on cryptographic hardware and consensus acceleration chips limit flows from United States, Taiwan, and Netherlands suppliers into aviation blockchain infrastructure. Component dependencies center on HSM modules, zero-knowledge proof ASICs, and fault-tolerant networking gear. Single-source vulnerability concentrates in FAA-certified firmware providers. Distribution runs through managed service providers and hyperscaler marketplaces serving airline IT procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation transaction blockchain functions as a service-attach play where recurring compliance-as-a-service revenue layers expand faster than initial infrastructure licensing. Smart contract automation and continuous audit trail generation now outpace hardware node deployment in annual contract value growth.
For Market Incumbents: Entrench consortium leadership positions through exclusive middleware development for SAP and Oracle ERP integration, the dominant chokepoint for competitor displacement. Capture automated covenant monitoring revenue pools before decentralized distribution protocols erode legacy global distribution system relationships. Prioritize FAA and EASA certification maintenance as competitive moats against challenger-tier vendors lacking audit relationships.
For New Entrants and Emerging Players: Build out zero-knowledge proof verification services for Dublin and Singapore lessor clusters, the most penetrable segment given pilot program openness and securitization data-sharing pain points. Target engine-hour verification protocols for MRO providers at Changi Aviation Park. Lead with API-first integration to bypass ERP middleware bottlenecks that stall incumbent deployments.
For Investors and Strategic Acquirers: Distributed systems engineering boutiques with existing aviation certification relationships represent the highest-conviction acquisition archetype for platform consolidation plays. Long-term viability hinges on cross-jurisdictional compliance automation becoming table-stakes rather than premium-tier differentiation. Watch for DORA enforcement action timelines as inflection indicators for European carrier procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Consortium-Led Standardization | DORA and FAA alignment on immutable audit formats reduces vendor fragmentation across transatlantic corridors. |
| ERP Middleware Development | SAP and Oracle integration layers capture sticky revenue from airline IT procurement committees. |
| Zero-Knowledge Proof Deployment | Privacy-preserving verification unlocks lessor portfolio aggregation speed for securitization workflows. |
| Cloud-Native Node Architecture | Scalable infrastructure serves mid-size carriers without capital-intensive hardware deployment. |
| Compliance-as-a-Service Expansion | Automated DORA and CSRD reporting layers generate recurring revenue beyond initial system sales. |
Methodological Framework
Desk research of regulatory filings from FAA and EU DORA frameworks, aviation finance trade publications, and lessor securitization disclosures preceded structured interviews with airline IT procurement directors, aircraft operating lease portfolio managers, MRO maintenance forecasting leads, and blockchain infrastructure vendor sales engineers. Secondary validation drew from EASA safety directives, ISO certification registries, and aviation consortium technical specifications. Bottom-up deployment estimates across carrier and lessor fleets were triangulated against top-down market sizing from infrastructure spending disclosures.
Assumptions held fixed across the modeling period include continued DORA enforcement timelines, FAA documentation standard evolution toward immutable record-keeping, and stable transatlantic data-sovereignty divergence. Segmentation dimensions modeled encompass technology layer, application function, end-user type, and deployment architecture. CAGRs were derived from logistic adoption curves fitted to enterprise procurement cycle data. Forecast inputs incorporated smart contract automation penetration rates and cross-border payment corridor volumes.
Stress conditions across regulatory enforcement intensity, ERP integration timeline delays, and distributed systems talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor calibrations. Material shifts in DORA penalty structures or FAA certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain Identity Management Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Global Blockchain IoT Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Bitcoin Technology Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Blockchain in Pharmaceutics Market