
 Decentralized Identity Market | 2026-2036
Decentralized Identity Market Size, Share, and Industry Trends Forecast 2026-2036
Decentralized Identity Market Intelligence
GDPR Article 25 data-protection-by-design mandates is decoupling identity verification from centralized credential storage, forcing vendors to architect systems around user-controlled data vaults. ConsenSys leverages its Ethereum infrastructure dominance to anchor enterprise-grade decentralized identifier issuance. Microsoft Entra Verified ID competes through deep Azure Active Directory integration, sustaining channel control across Fortune 500 IAM procurement. Spruce Systems specializes in wallet-native authentication protocols, positioning its Sign-In with Ethereum stack as a Web3-native alternative to OAuth.
Decentralized identity denotes a technical architecture where cryptographic key pairs, verifiable credentials, and distributed ledger anchoring replace hierarchical certificate authorities for identity proofing. Self-sovereign identity frameworks employ W3C-standard decentralized identifiers and JSON-LD verifiable credentials to enable peer-to-peer trust establishment without intermediary validation. Blockchain technology leads current deployment value due to immutable audit trails for credential revocation, while distributed ledger technology variants capture growing interest where energy-efficient consensus mechanisms prove critical. Identity attestation applications command widening enterprise budgets as supply-chain verification and workforce credentialing migrate from paper-based workflows to cryptographically signed digital proofs.
The EU eIDAS 2.0 framework, the US NIST Digital Identity Guidelines, and the W3C Verifiable Credentials Data Model collectively establish interoperability baselines that determine which vendor stacks qualify for government and regulated-industry procurement. EMA and FDA pharmacovigilance reporting requirements are extending into clinical trial participant identity verification, creating compliance-driven demand for tamper-proof credentialing. Stakeholders must monitor which national digital identity wallets achieve cross-border mutual recognition, as this regulatory alignment will determine addressable market boundaries faster than technology differentiation alone.
Market Dynamics
EU eIDAS 2.0 mandates are forcing enterprises to abandon centralized identity databases in favor of user-controlled cryptographic credentialing, compressing procurement timelines for compliant architectures.
Growth Catalysts
- Pharmaceutical traceability mandates:EMA and FDA pharmacovigilance rules now require tamper-proof participant identity verification for clinical trials, driving demand for verifiable credential systems.
- Financial sector KYC modernization:Banks are replacing document-based identity proofing with W3C-standard decentralized identifiers to reduce fraud exposure and compliance costs.
- Germany's digital wallet acceleration:The country's eIDAS 2.0 implementation timeline is compressing enterprise procurement cycles for interoperable identity infrastructure.
Market Restraints
- Energy-intensive consensus mechanisms:Proof-of-work blockchain anchoring for credential revocation creates sustainability liabilities incompatible with corporate ESG commitments.
- Legacy IAM vendor concentration:Microsoft's Azure Active Directory dominance in Fortune 500 enterprises creates channel lock-in that slows vendor diversification.
- Cross-border recognition gaps:Absence of mutual recognition between national digital identity wallets fragments addressable markets and raises integration costs.
Strategic Opportunities
- Supply-chain credentialing white space:Workforce certification and supplier verification workflows remain paper-dependent, creating openings for cryptographically signed digital proof systems.
- GDPR Article 25 compliance services:Data-protection-by-design mandates are decoupling verification from storage, creating demand for user-controlled data vault architectures.
- Web3-native authentication convergence:Wallet-native protocols are capturing developer mindshare as alternatives to OAuth, opening enterprise sales channels through bottom-up adoption.
Industry Challenges
- Cryptographic talent scarcity:Shortage of engineers proficient in zero-knowledge proofs and JSON-LD verifiable credential implementation is throttling deployment velocity.
- Legacy system integration friction:Enterprises face complex middleware requirements to connect decentralized identifier stacks with existing Active Directory and SAML infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decentralized Identity Market |
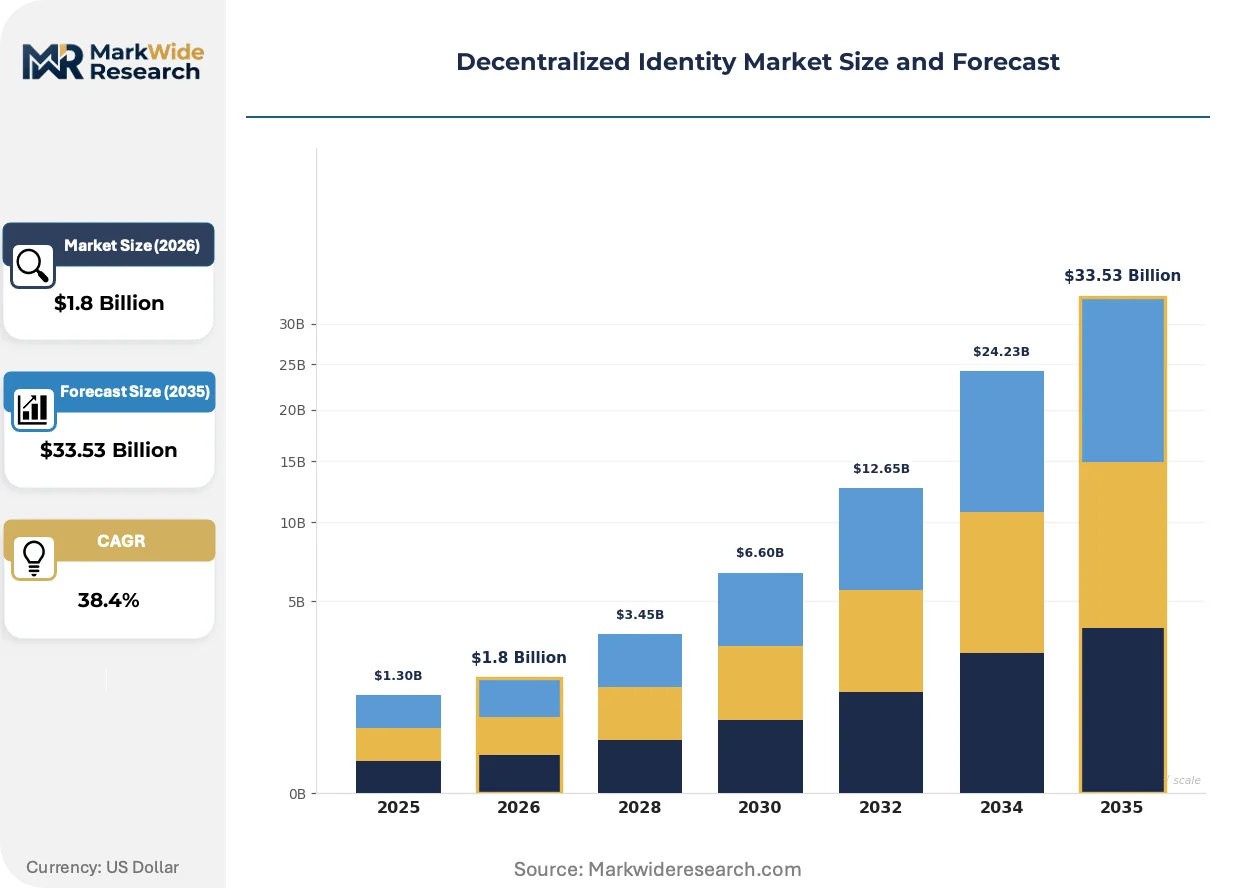
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.53 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, Self-Sovereign Identity, Distributed Ledger Technology, Cryptography Application: Digital Identity Verification, Online Authentication, Secure Access Management, Identity Attestation End User: Individuals, Enterprises, Government Agencies, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Hu-manity.co, ConsenSys, Evernym, IBM Verify Credentials, Microsoft Entra Verified ID, Civic Technologies, Dock Labs, Spruce Systems, 1Kosmos Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decentralized Identity Market Strategic Shifts & Innovations
Zero-knowledge proof architectures are compressing the trade-off between identity verification and data minimization, enabling selective disclosure without credential exposure.
Zero-knowledge credentialing is rewriting how enterprises handle sensitive attribute verification. Financial institutions are piloting zk-SNARK-based age and income proofs at scale. This compression of disclosure scope is eliminating the honeypot risk of centralized attribute repositories.
EU AI Act risk classification rules are extending into identity verification systems, categorizing biometric inference engines as high-risk applications. Vendors must now maintain conformity assessment documentation and human oversight protocols. German procurement officers are prioritizing certified systems ahead of enforcement deadlines.
Enterprise buyers are unbundling identity verification from workforce management suites, creating direct procurement relationships with specialized decentralized identity vendors. Systems integrators are losing their historical role as authentication gatekeepers. This disintermediation is most visible in Netherlands and Scandinavian enterprise IT budgets.
Decentralized Identity Market Segmentation
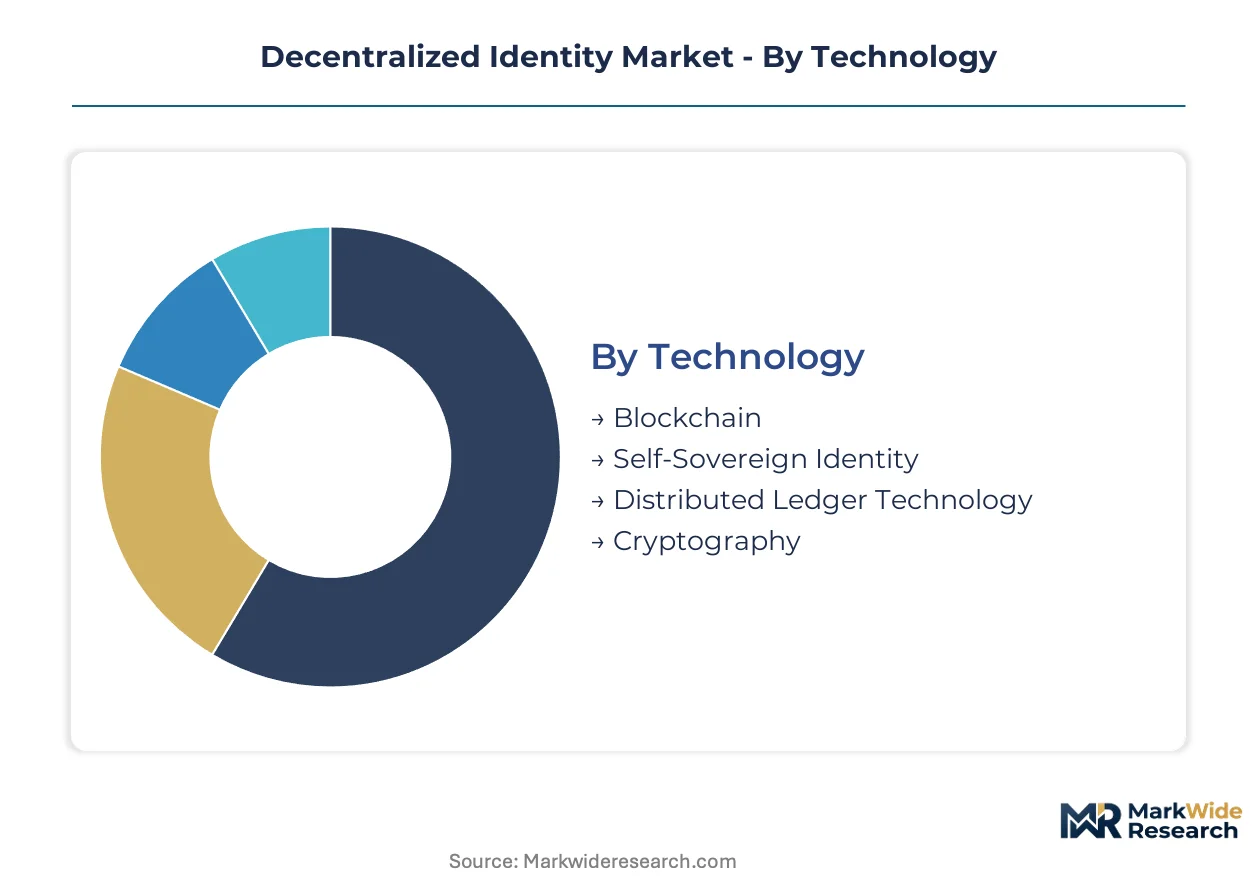
Decentralized identity architectures fragment across technology stacks, deployment models, and credentialing workflows that demand distinct procurement criteria. Each segmentation dimension carries unique capital requirements, compliance burdens, and integration complexity that shape vendor selection and implementation timelines.
Technology:
Blockchain infrastructure demands the heaviest upfront investment in consensus node deployment, cryptographic hardware security modules, and energy provisioning for proof-of-stake validation networks.
- Blockchain:Immutable distributed ledgers anchor credential revocation registries with tamper-proof audit trails. Financial institutions in Germany are deploying Ethereum-compatible networks for KYC credential lifecycle management under eIDAS 2.0 timelines.
- Self-Sovereign Identity:User-controlled identifier frameworks employ W3C-standard decentralized identifiers and verifiable credentials without intermediary validation. Enterprise procurement in Netherlands and Scandinavian markets is accelerating as organizations disintermediate systems integrators from authentication workflows.
- Distributed Ledger Technology:Permissioned consensus variants reduce energy consumption versus public blockchains while maintaining cryptographic integrity. Supply-chain verification pilots favor Hyperledger Fabric deployments for supplier credentialing.
- Cryptography:Zero-knowledge proof implementations enable selective attribute disclosure without credential exposure. zk-SNARK libraries require specialized engineering talent that throttles deployment velocity.
Blockchain absorbs the bulk of installed capacity; Self-Sovereign Identity is expanding most quickly.
Application:
Application segments diverge by regulatory touchpoint density, with identity attestation commanding the highest compliance documentation burden across EMA pharmacovigilance and FDA clinical trial mandates.
- Digital Identity Verification:Cryptographic proofing replaces document-based KYC workflows with W3C verifiable credentials. Banks are eliminating photocopy retention and manual review steps through automated credential validation.
- Online Authentication:Wallet-native protocols displace OAuth and SAML for Web3-native user journeys. Developer adoption of Sign-In with Ethereum patterns is opening enterprise sales channels through bottom-up procurement.
- Secure Access Management:Decentralized identifiers integrate with existing Active Directory infrastructures through middleware bridges. Fortune 500 IAM procurement cycles favor Azure-compatible stacks despite vendor lock-in risks.
- Identity Attestation:Tamper-proof credentialing for clinical trial participants satisfies EMA and FDA pharmacovigilance requirements. Pharmaceutical sponsors are mandating cryptographically signed participant proofs for regulatory submission packages.
Digital Identity Verification captures the dominant share of current deployment; Identity Attestation follows the steepest expansion trajectory.
End User:
End user segments separate by procurement authority concentration, with government agencies consolidating demand through national digital wallet mandates while individual adoption remains fragmented.
- Individuals:Citizen-controlled identity wallets store government-issued credentials and private attestations. EU Digital Identity Wallet regulation is forcing wallet interoperability standards that determine vendor qualification.
- Enterprises:Workforce credentialing and supplier verification workflows migrate from paper-based systems to cryptographically signed digital proofs. Supply-chain white space remains substantial in manufacturing and logistics sectors.
- Government Agencies:National digital identity programs establish procurement baselines that cascade to regulated industries. Cross-border mutual recognition gaps fragment addressable markets and raise integration costs.
- Educational Institutions:Verifiable diploma and transcript issuance reduces credential fraud in international admissions. University procurement lags financial and pharmaceutical sectors by several implementation cycles.
Enterprises deploy the majority of production systems; Government Agencies are scaling fastest through regulatory mandate.
Deployment:
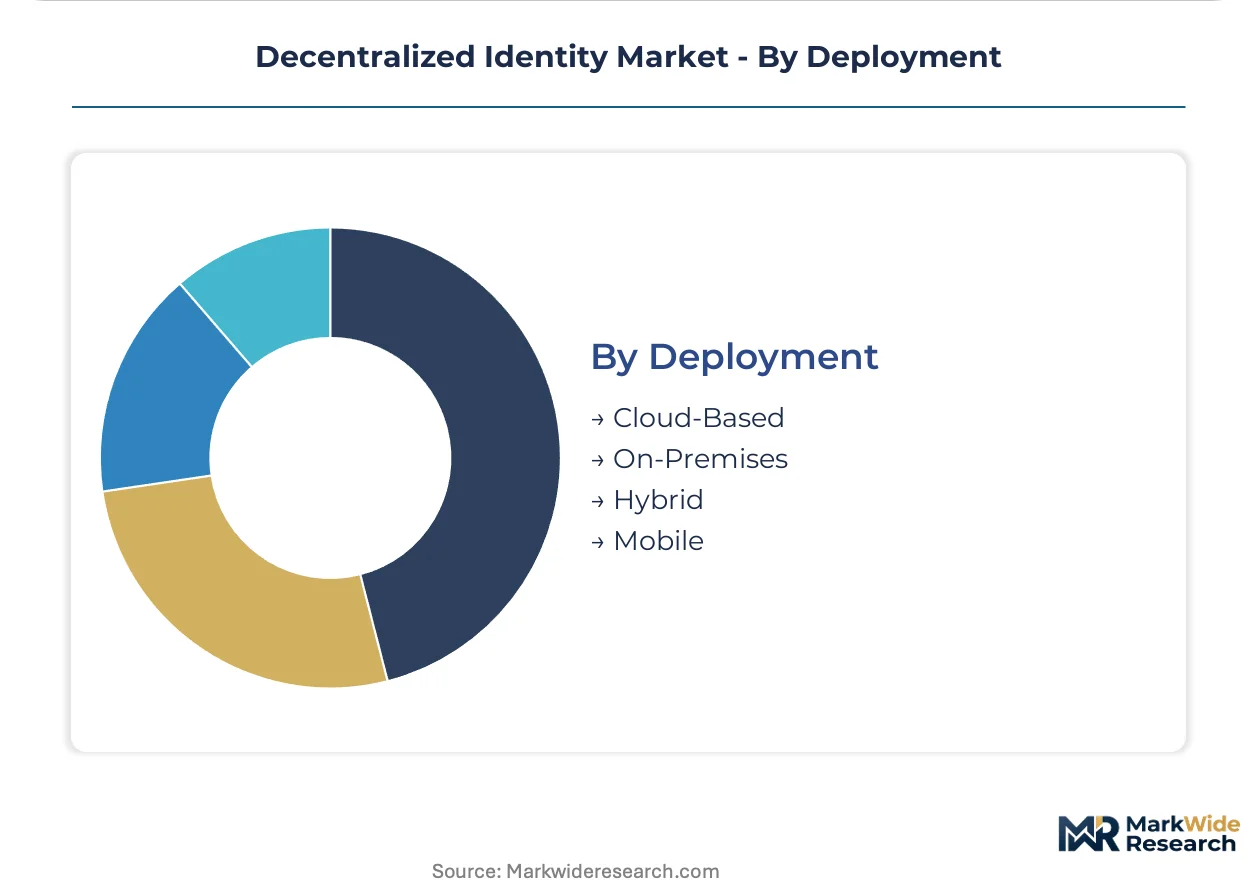
Deployment models distribute across control sensitivity and operational burden, with hybrid architectures splitting credential storage from verification logic to satisfy GDPR Article 25 data-protection-by-design mandates.
- Cloud-Based:Managed identity services reduce infrastructure overhead for mid-market enterprises. Microsoft Entra Verified ID leverages Azure dominance to sustain channel control.
- On-Premises:Air-gapped credential vaults serve defense and intelligence community requirements. High capital expenditure and specialized staffing limit adoption outside regulated sectors.
- Hybrid:Split architectures anchor revocation registries on-chain while retaining personal data in user-controlled off-chain vaults. GDPR compliance services are driving procurement of decoupled verification-storage systems.
- Mobile:Wallet-native credential presentation enables selective disclosure at point of service. German eIDAS 2.0 implementation is accelerating mobile-first procurement specifications.
Cloud-Based deployments hold the largest installed base; Hybrid configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German procurement officers are compressing enterprise identity infrastructure timelines under eIDAS 2.0 mandates, while US financial institutions and Dutch disintermediation patterns concentrate demand across three distinct regulatory environments.
Germany
Banks and pharmaceutical sponsors are accelerating verifiable credential procurement for KYC modernization and clinical trial participant verification. The country's eIDAS 2.0 implementation timeline forces abandonment of centralized identity databases by regulated enterprises. Berlin and Frankfurt clusters anchor enterprise deployment of Ethereum-compatible credential revocation registries.
United States
Financial sector KYC modernization and FDA pharmacovigilance requirements drive verifiable credential adoption across banking and clinical research sectors. NIST Digital Identity Guidelines establish interoperability baselines for vendor qualification in regulated procurement. Boston and San Francisco metropolitan areas concentrate developer talent for zero-knowledge proof implementation.
Netherlands
Enterprise IT budgets are disintermediating systems integrators from authentication workflows through direct decentralized identity vendor procurement. GDPR Article 25 data-protection-by-design mandates accelerate hybrid deployment architectures splitting verification from storage. Amsterdam and Rotterdam corporate headquarters lead wallet-native protocol adoption for workforce credentialing.
United Kingdom
Financial services firms are replacing document-based identity proofing with W3C-standard decentralized identifiers to reduce fraud exposure. The UK Digital Identity and Attributes Trust Framework creates procurement baselines cascading to regulated industries. London's fintech concentration drives pilot programs for zk-SNARK-based selective disclosure at scale.
India
Educational institutions and workforce certification bodies are migrating from paper-based credential workflows to cryptographically signed digital proofs. The country's national digital identity infrastructure creates interoperability expectations for private-sector wallet providers. Bangalore and Hyderabad technology corridors anchor engineering talent pools for JSON-LD verifiable credential implementation.
Decentralized Identity Market Key Industry Players
US-based infrastructure providers anchor one tier; European specialists hold compliance-driven positioning. The vendor set fragments across blockchain infrastructure, enterprise IAM integration, and wallet-native protocol specialization. Three archetypes dominate: Ethereum-anchored credential issuers, Azure-integrated identity suites, and Web3-native authentication stacks. Competitive moves concentrate on middleware bridge development for Active Directory interoperability and zero-knowledge proof capability acquisition.
Within the blockchain infrastructure tier, ConsenSys leverages its Ethereum positioning for enterprise-grade decentralized identifier issuance. Microsoft Entra Verified ID exemplifies the enterprise IAM integration archetype through Azure channel dominance. Spruce Systems occupies a position among wallet-native specialists with its Sign-In with Ethereum stack capturing developer adoption as an OAuth alternative.
| Leading Market Players |
|---|
| Hu-manity.co |
| ConsenSys |
| Evernym |
| IBM Verify Credentials |
| Microsoft Entra Verified ID |
| Civic Technologies |
| Dock Labs |
| Spruce Systems |
| 1Kosmos Inc. |
| Others |
Cost & Logistics Intelligence
Zero-knowledge proof engineering talent scarcity in Berlin and Boston clusters compresses labor-cost differentials between premium-tier credentialing suites and economy-grade authentication modules. This workforce concentration shapes pricing spreads as vendors compete for cryptographic specialists capable of implementing zk-SNARK libraries.
Pricing Analysis
High-volume cloud-based deployments sacrifice margin for scale while on-premise air-gapped vaults capture premium pricing. Three-tier pricing structure across enterprise-grade, mid-market SaaS, and developer-tier API access separates buyers by integration complexity and compliance burden. Pricing pressure stems from open-source credentialing libraries commoditizing basic verifiable credential issuance. Mid-market enterprises exhibit highest price sensitivity as they lack procurement scale for volume discounts yet face budget constraints against legacy IAM renewal cycles.
Supply Chain Analysis
Cryptographic engineering workforce availability in Germany, Netherlands, and United States determines vendor delivery capacity and implementation timelines. Supply chains draw from hardware security module manufacturers in Switzerland and Taiwan, cloud infrastructure hyperscalers, and specialized zero-knowledge proof research labs. Single-source vulnerability concentrates in HSM firmware providers serving regulated financial and pharmaceutical credentialing deployments. Distribution runs through direct enterprise sales teams and systems integrator partnerships, with channel conflict intensifying as vendors disintermediate traditional IAM gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cryptographic engineering talent scarcity props pricing for vendors capable of delivering zero-knowledge proof implementations at scale. Capacity constraints in qualified implementation teams create defendable margin positions for incumbents with established training pipelines.
For Market Incumbents: Lock in channel control through middleware bridge investments that embed decentralized identifier stacks within existing Azure Active Directory and SAML infrastructures. Acquire zero-knowledge proof engineering teams in Berlin and Boston to defend against talent poaching by emerging wallet-native protocol vendors. Certification investment under EU AI Act high-risk system conformity assessment protocols creates switching costs that protect installed base revenue. For New Entrants and Emerging Players: The mid-market pricing gap between Microsoft Entra Verified ID enterprise contracts and open-source credentialing tools offers entry space for compliant SaaS-tier offerings. Target supply-chain credentialing workflows in manufacturing and logistics sectors where paper-based supplier verification remains dominant. Developer adoption of Sign-In with Ethereum patterns enables bottom-up enterprise sales channel construction without direct incumbent confrontation. For Investors and Strategic Acquirers: Re-rating potential sits with wallet-native protocol specialists given Web3-native authentication convergence as a demand catalyst. Five-to-ten year viability hinges on cross-border mutual recognition between national digital identity wallets achieving regulatory alignment. Watch German eIDAS 2.0 implementation procurement awards as inflection indicator for enterprise adoption velocity across European regulated industries.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Proof Capability Acquisition | zk-SNARK engineering teams in Berlin and Boston anchor selective disclosure product differentiation. |
| Middleware Bridge Development | Active Directory integration sustains channel control across Fortune 500 IAM procurement cycles. |
| EU AI Act Conformity Certification | High-risk system documentation requirements create compliance moats against unverified competitors. |
| Supply-Chain Credentialing Platform Launch | Workforce certification and supplier verification white space opens manufacturing sector revenue. |
| Cross-Border Wallet Interoperability Partnership | Mutual recognition agreements between German and Dutch national wallets expand addressable market boundaries. |
Research Approach
Independent corroboration across primary interviews with IAM procurement officers, cryptographic engineering leads, regulatory compliance directors, and systems integrator partners underwrites the qualitative findings. Secondary validation draws from eIDAS 2.0 implementation timelines, FDA pharmacovigilance guidance documents, W3C Verifiable Credentials specification releases, and hyperscaler identity service capex disclosures. Bottom-up deployment tracking across technology stacks and end-user segments triangulates against top-down regulatory mandate analysis.
Rate-of-change decomposition separates volume expansion from value-per-credential evolution across the projection horizon. Segmentation dimensions modeled include technology infrastructure, application workflow, end-user procurement authority, and deployment architecture complexity. CAGRs were derived from regression analysis of historical procurement cycle compression and forward regulatory deadline alignment. Forecast inputs incorporate eIDAS 2.0 implementation timeline acceleration and zero-knowledge proof pilot program scaling patterns.
Inputs from enterprise procurement databases and government digital wallet program disclosures were available through the study window; gaps in real-time credential transaction volumes introduce uncertainty bands around adoption velocity assumptions. Forecasts reflect documented assumptions regarding cross-border mutual recognition timeline achievement and cryptographic talent pipeline expansion. A small set of regulatory enforcement triggers and national wallet interoperability announcements warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Blockchain Technology Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Global Blockchain Software Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Global Blockchain IoT Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Global Blockchain in Energy Market