
 Global Blockchain in Agriculture and Food Supply Chain Market | 2026-2036
Global Blockchain in Agriculture and Food Supply Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Agriculture and Food Supply Chain Market Foresight
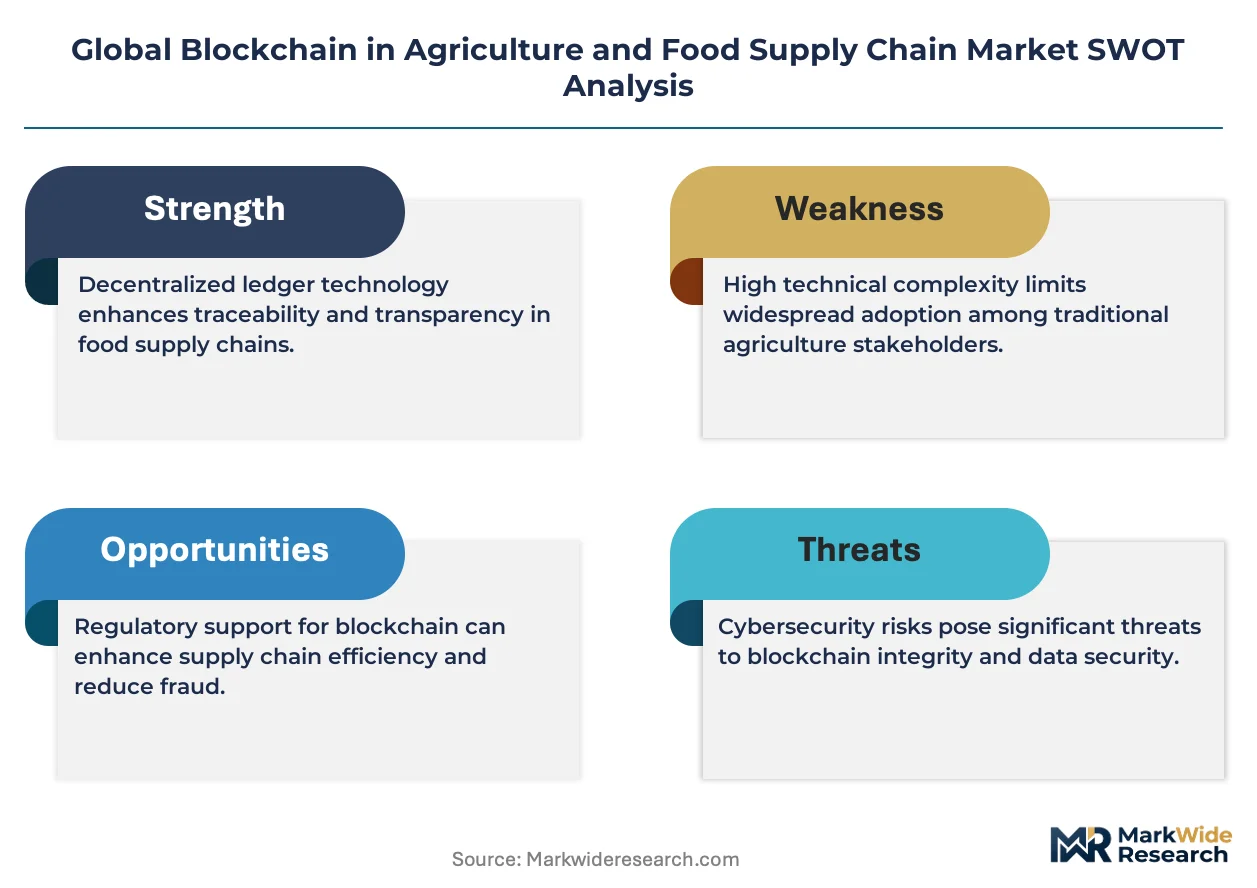
Subscription-based software platforms is consolidating around recurring revenue models that embed compliance automation and real-time sensor integration. IBM leverages its Hyperledger Fabric deployments to anchor enterprise-grade traceability networks across North American protein supply chains. SAP SE competes through pre-integrated ERP modules that extend blockchain functionality into existing agricultural procurement workflows. OriginTrail specializes in decentralized knowledge graphs that differentiate its interoperability approach from siloed ledger implementations.
Blockchain in agriculture and food supply chain refers to cryptographically linked distributed databases that record immutable transaction hashes across multiple nodes, typically employing consensus mechanisms such as proof-of-authority or Byzantine fault tolerance to validate batch movements from farm to retail shelf. These systems serve the primary commercial purpose of eliminating information asymmetry between producers, handlers, and consumers by creating auditable provenance trails for perishable goods. Traceability and transparency applications dominate current deployment value, while smart contracts represent the fastest-expanding technology layer as automated payment triggers and quality escrow mechanisms gain traction among commodity traders. Software platforms capture the deepest margin pools due to recurring licensing structures, though hardware devices including IoT-enabled edge nodes are gaining share in cold-chain monitoring segments.
The FDA's Food Safety Modernization Act traceability requirements and the EU's General Food Law Regulation, alongside China's SAMR food safety digitization mandates, are collectively elevating compliance-grade ledger adoption as a market access prerequisite rather than a discretionary investment. ISO 22000 food safety management standards and the GS1 EPCIS 2.0 event-sharing protocol are further hardening technical specifications that blockchain implementations must satisfy for cross-border shipment acceptance. Stakeholders must monitor which consensus governance models achieve regulatory recognition as the default compliance substrate for multi-jurisdictional agricultural trade.
Market Dynamics
Regulatory mandates for farm-to-fork traceability are compressing adoption timelines across agricultural supply chains, transforming blockchain from pilot projects into compliance infrastructure.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory supply chain accountability requirements across member states are forcing food handlers to deploy distributed ledger systems for batch provenance documentation.
- China SAMR digitization mandates:The national food safety regulator's prioritization of digital ledger integration for pork and grain tracking creates concentrated demand from protein processors and grain elevators.
- Sensor-ledger convergence:Real-time IoT integration with blockchain nodes enables automated cold-chain verification, reducing manual audit overhead for perishable logistics operators.
Market Restraints
- Interoperability fragmentation:Competing consensus protocols and proprietary data formats prevent seamless cross-platform data exchange between supply chain participants.
- Energy-intensive validation:Proof-of-work mechanisms face operational cost pressures and sustainability scrutiny from ESG-conscious agricultural conglomerates.
- Smallholder exclusion:Hardware and connectivity requirements for on-farm node participation marginalize subsistence producers across Sub-Saharan Africa and South Asia.
Strategic Opportunities
- Carbon credit verification:Blockchain-enabled measurement, reporting, and verification protocols for regenerative agriculture practices unlock access to voluntary carbon markets for commodity crop farmers.
- India FSSAI integration:The food safety authority's emerging digital infrastructure roadmap presents white space for compliance-grade traceability platforms in spice and dairy supply chains.
- Smart contract automation:Programmable payment triggers tied to quality escrow mechanisms reduce settlement friction between commodity traders and grain elevators.
Industry Challenges
- Distributed systems expertise scarcity:Agricultural enterprises struggle to recruit cryptographers and consensus engineers capable of maintaining private network deployments.
- Legacy ERP integration complexity:Synchronization between decades-old procurement databases and immutable ledger architectures requires expensive middleware development.
- GS1 EPCIS 2.0 certification timelines:Event-sharing protocol compliance for cross-border shipment acceptance demands extended technical validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Agriculture and Food Supply Chain Market |
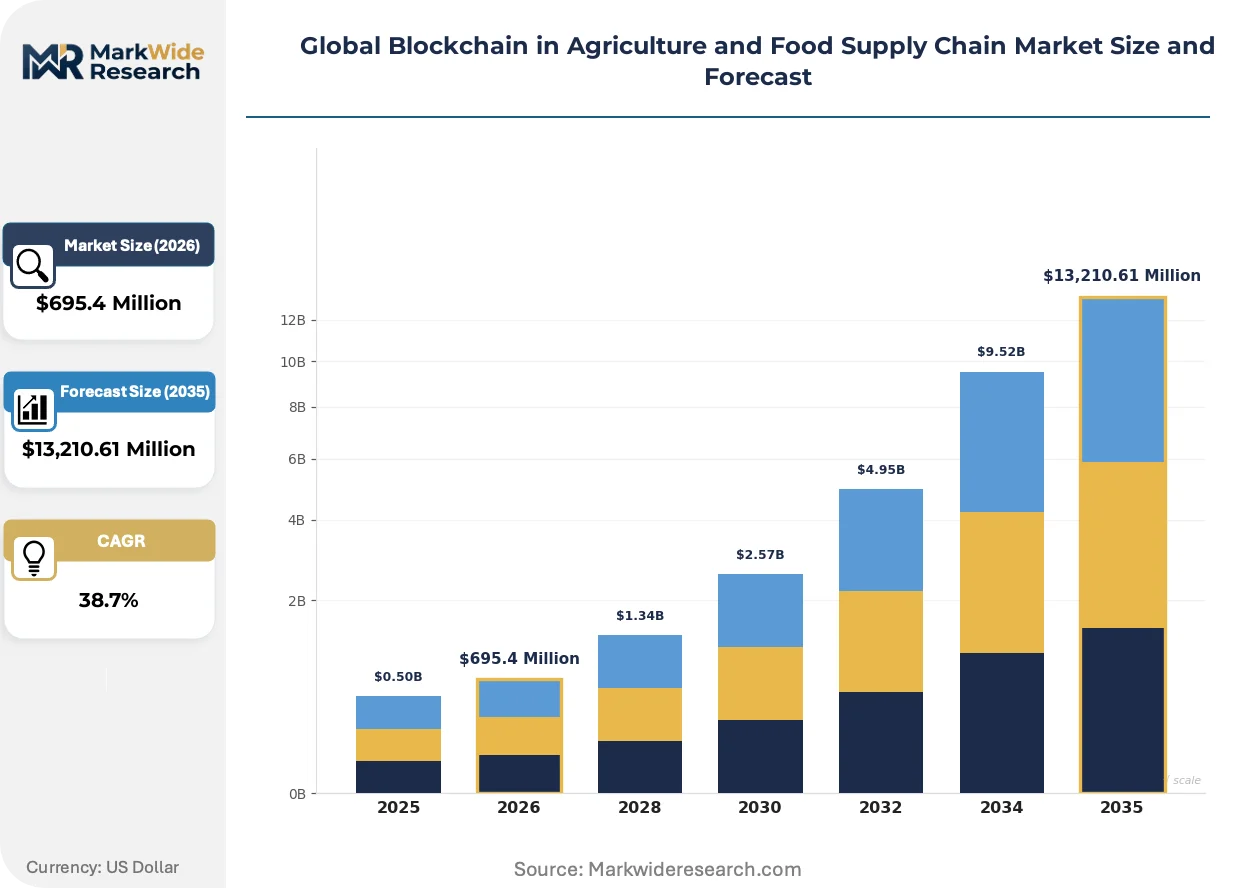
| Market Size in 2026 | $695.4 Million |
| Market Size in 2035 | $13,210.61 Million |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Traceability & Transparency, Quality Assurance, Farm Management, Supply Chain Financing, Food Safety, Logistics Optimization Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain, Smart Contracts, Distributed Ledger End User: Farmers, Food Processors, Logistics Providers, Retailers, Regulatory Authorities, Agricultural Consultants Product Type: Software Platforms, Middleware Solutions, Hardware Devices, Consulting Services, Integration Services, Analytics Tools |
| Companies Covered | IBM, Microsoft, SAP SE, OriginTrail, VeChain, AgriDigital, Ambrosus, TE-FOOD, Ripe.io, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Agriculture and Food Supply Chain Market Shifts & Advancements
Smart contract layers are automating commercial terms across agricultural commodity trading, compressing settlement cycles from weeks to hours while embedding quality-based payment triggers directly into transaction logic.
Automated execution protocols are automating payment disbursement upon IoT-verified delivery confirmation. Grain cooperatives in the US Midwest and protein processors in Brazil are deploying these systems for soybean and beef exports. The technology is automating trust intermediation previously handled by documentary letters of credit, reducing banking fees and counterparty risk exposure for international agricultural traders.
REACH chemical traceability extensions and the EU AI Act's risk classification framework are hardening data governance requirements for agricultural biotechnology supply chains. Seed manufacturers must now document genetic modification histories through auditable ledgers to maintain market access. German and Dutch agritech clusters are responding by pre-integrating compliance modules into their blockchain deployments.
Retail procurement teams now demand batch-level provenance data as a standard contract term, displacing commodity-grade anonymous sourcing. French and UK supermarket chains are rejecting suppliers unable to provide cryptographic origin certificates for fresh produce. This specification compression is most visible in the berry and leafy green categories, where food safety incidents have amplified buyer liability concerns.
Global Blockchain in Agriculture and Food Supply Chain Market Segmentation
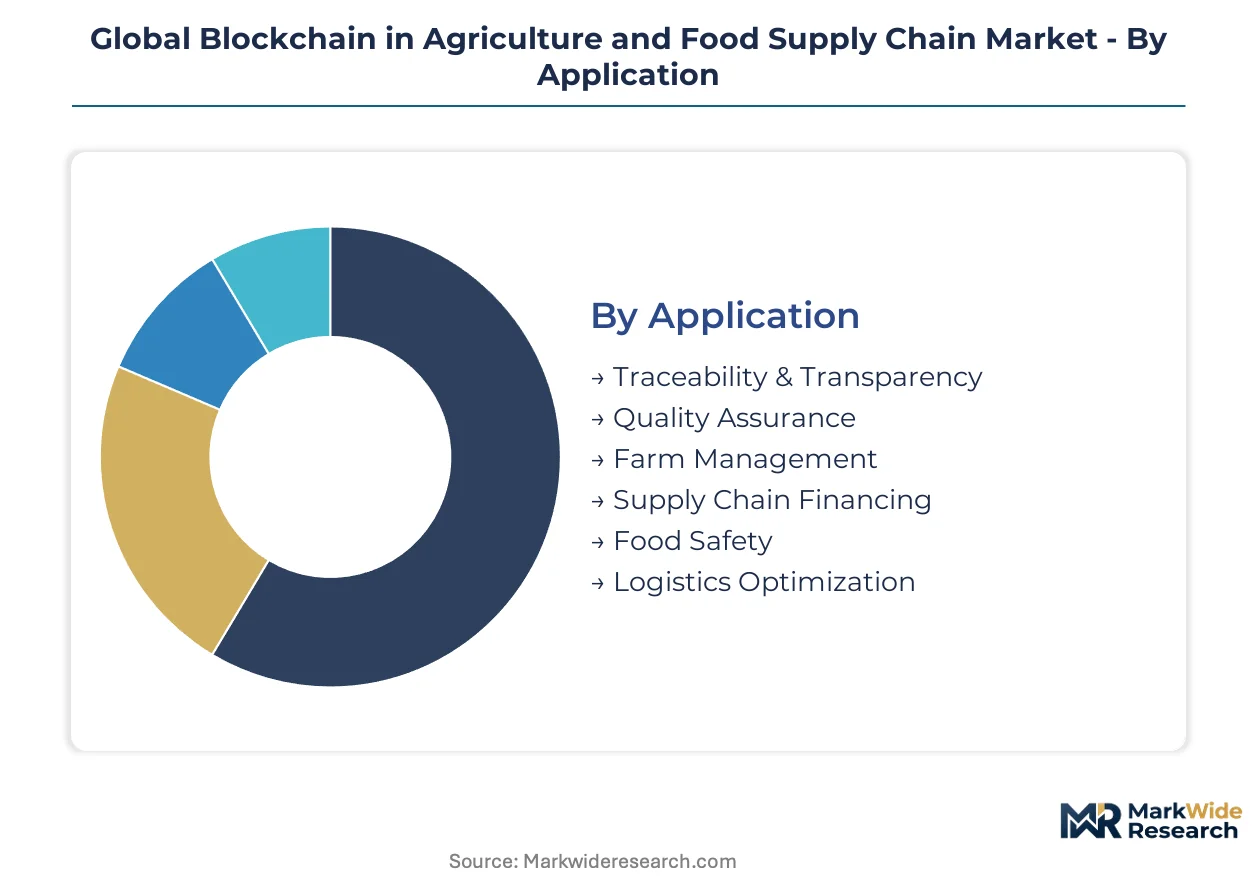
Blockchain deployments in agriculture fragment across integration depths, from standalone traceability tools to embedded ERP modules. Segmentation reveals where margin pools concentrate and which technology layers command pricing power across farm-to-fork value chains.
Application:
Standalone traceability applications dominate current deployment spend, while embedded quality and financing modules represent deeper integration trajectories.
- Traceability & Transparency:Immutable batch provenance tracking from farm gate to retail shelf anchors most enterprise deployments. Walmart's leafy green mandates and Carrefour's blockchain labeling programs concentrate demand in North American and European retail procurement specifications.
- Quality Assurance:Sensor-validated quality metrics trigger automated acceptance protocols at grain elevators and protein processing facilities. Cold-chain operators in Brazil and Australia embed these modules to reduce manual inspection overhead.
- Farm Management:Decentralized record-keeping for seed certification, input tracking, and harvest documentation.
- Supply Chain Financing:Cryptographic verification of inventory and receivables unlocks working capital for commodity traders.
- Food Safety:Real-time contamination alert propagation across distributed networks.
- Logistics Optimization:Route verification and carrier performance scoring through immutable delivery records.
Volume placements concentrate in Traceability & Transparency; the faster expansion belongs to Supply Chain Financing.
Technology:
Cost tiering separates permissionless infrastructure from enterprise-grade deployments with defined governance and predictable validation economics.
- Private Blockchain:Permissioned networks with proof-of-authority consensus dominate protein processor and grain trader deployments. SAP and IBM anchor these implementations for North American agricultural conglomerates requiring sub-second finality.
- Smart Contracts:Programmable payment triggers and quality escrow mechanisms automate commodity settlement. Brazilian soybean exporters and US Midwest grain cooperatives deploy these to compress cash cycles from weeks to hours.
- Public Blockchain:Open, permissionless networks for carbon credit verification and voluntary sustainability claims.
- Consortium Blockchain:Multi-party governance shared across competing supply chain participants.
- Hybrid Blockchain:Selective disclosure architectures balancing transparency with competitive confidentiality.
- Distributed Ledger:Broader architectural category encompassing non-blockchain directed acyclic graph implementations.
Enterprise procurement favors Private Blockchain for compliance-grade deployments; Smart Contracts gain share fastest in commodity trading automation.
End User:
Customer type determines integration complexity, from single-node farm implementations to multi-enterprise network orchestration.
- Retailers:Supermarket chains mandate cryptographic provenance certificates as standard contract terms. French and UK grocery chains reject berry and leafy green suppliers lacking batch-level origin documentation.
- Food Processors:Protein packers and grain millers operate the densest node concentrations. China's SAMR digitization mandates for pork tracking concentrate demand among domestic protein processors.
- Farmers:Primary production node operators with varying connectivity and technical capacity.
- Logistics Providers:Cold-chain and bulk commodity carriers with IoT-enabled edge verification requirements.
- Regulatory Authorities:Compliance auditors and certification bodies accessing read-only network views.
- Agricultural Consultants:Advisory firms deploying blockchain as a service for smallholder collectives.
Procurement leverage concentrates with Retailers; Food Processors represent the steepest expansion trajectory as regulatory mandates harden.
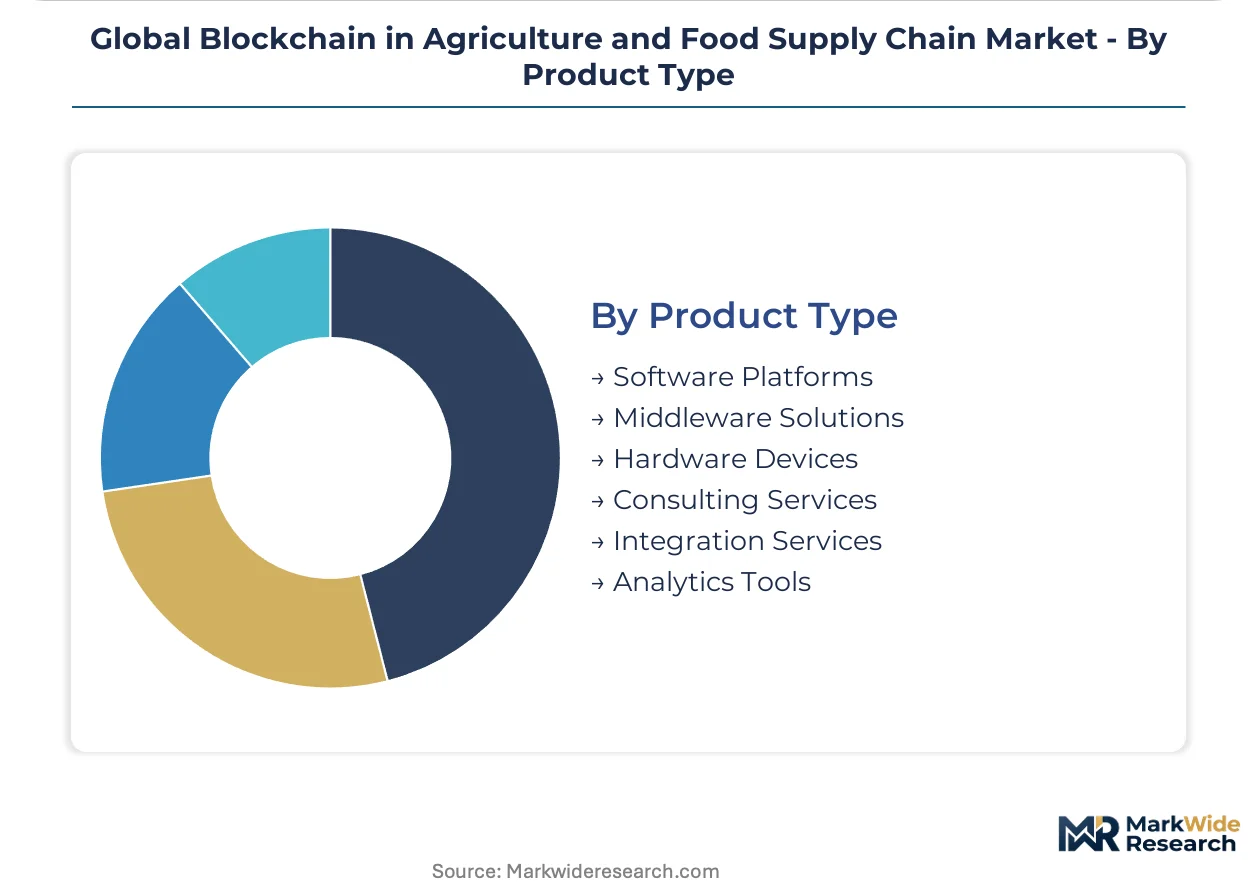
Product Type:
Margin structure separates recurring software revenue from one-time hardware and services engagements.
- Software Platforms:Subscription-based traceability networks with embedded compliance automation capture the deepest margin pools. Hyperledger Fabric and OriginTrail deployments anchor recurring licensing structures across enterprise agricultural networks.
- Hardware Devices:IoT-enabled edge nodes for cold-chain monitoring gain share as sensor-ledger convergence accelerates. Temperature loggers and GPS trackers with embedded cryptographic signing proliferate in perishable logistics.
- Middleware Solutions:ERP synchronization layers bridging legacy procurement databases with immutable ledgers.
- Consulting Services:Network design and governance architecture for multi-party implementations.
- Integration Services:Custom development for legacy system connectivity.
- Analytics Tools:Provenance-derived insights for yield optimization and risk scoring.
Revenue concentration sits with Software Platforms; Hardware Devices climb fastest as edge verification becomes standard in cold-chain specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blockchain deployment for agricultural traceability concentrates where regulatory pressure intersects with export-dependent food systems. Production-heavy economies deploy ledger infrastructure to secure foreign market access, while import-reliant nations mandate transparency to manage consumer liability.
United States
The FDA's Food Safety Modernization Act traceability rules compress adoption timelines for leafy green handlers and protein processors. Retail procurement teams at Walmart and Kroger now require cryptographic batch certificates as standard contract terms. California's Central Valley vegetable cooperatives deploy Hyperledger-based networks to satisfy buyer specifications.
China
SAMR digitization mandates for pork and grain tracking create concentrated demand from domestic protein processors and grain elevators. The national food safety regulator prioritizes digital ledger integration for livestock disease containment and inventory verification. Sichuan and Henan provinces host the densest node concentrations for hog supply chain monitoring.
Germany
The EU Green Deal Farm to Fork Strategy forces food handlers to document batch provenance across member state borders. REACH chemical traceability extensions harden data governance requirements for seed manufacturers documenting genetic modification histories. Bavarian agritech clusters pre-integrate compliance modules into blockchain deployments for export certification.
Brazil
Soybean exporters and beef processors deploy smart contract automation to compress settlement cycles from weeks to hours. The national agricultural regulator aligns with GS1 EPCIS 2.0 protocols for cross-border shipment acceptance. Mato Grosso and São Paulo state grain cooperatives anchor the densest smart contract deployments for commodity trading.
India
FSSAI's emerging digital infrastructure roadmap presents white space for compliance-grade traceability platforms in spice and dairy supply chains. The food safety authority's digitization push targets export-oriented agricultural segments facing EU and US buyer requirements. Gujarat and Maharashtra dairy cooperatives pilot sensor-ledger convergence for cold-chain verification.
Global Blockchain in Agriculture and Food Supply Chain Market Competitive Landscape
Top-tier vendors anchor enterprise-grade deployments, while mid-tier specialists compete on interoperability and sector-specific customization. The vendor base stratifies across three tiers: multinational technology conglomerates with pre-integrated ERP modules, blockchain-native platforms with decentralized knowledge graph architectures, and agritech specialists with embedded sensor hardware. Strategic archetypes include compliance automation providers, commodity trading automation specialists, and cold-chain verification integrators. Dominant competitive moves center on ERP synchronization partnerships and sensor-ledger convergence for perishable logistics.
Within the enterprise technology tier, IBM, SAP SE, and Microsoft occupy positions as infrastructure anchors for North American and European agricultural conglomerates. IBM leverages Hyperledger Fabric deployments for protein supply chain traceability. SAP SE competes through pre-integrated modules extending blockchain functionality into existing procurement workflows. Microsoft provides cloud substrate for distributed ledger implementations across farm management and supply chain financing applications.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| SAP SE |
| OriginTrail |
| VeChain |
| AgriDigital |
| Ambrosus |
| TE-FOOD |
| Ripe.io |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up agritech specialists dominate software platform ownership, concentrating pricing power with recurring-revenue vendors while compressing margins for hardware-integrated deployments across North American protein supply chains.
Pricing Analysis
Margin tightening in enterprise SaaS tiers reflects hyperscaler cloud substrate costs and ISO 22000 certification overhead. Three-tier pricing structure across premium compliance-grade, standard traceability, and economy sensor-only levels separates Walmart-mandated deployments from small cooperative pilots. Price differentiation hinges on GS1 EPCIS 2.0 certification status and embedded ERP synchronization depth. Smallholder-facing agricultural consultants exhibit highest price sensitivity; multinational food processors absorb premium tiers without volume negotiation.
Supply Chain Analysis
Domestic-content mandates in China's SAMR pork-tracking programs and India's FSSAI dairy pilots are reshaping sourcing toward local node manufacturers. Hardware componentry concentrates in China, Taiwan, and South Korea; consensus protocol development clusters in the United States and Germany. Silicon foundry capacity for IoT edge devices and cryptographic security modules feeds from semiconductor supply chains vulnerable to single-source lithography equipment restrictions. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams serving agricultural conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified consensus engineers and cryptographers capable of maintaining private Hyperledger deployments represent the binding capacity constraint, propping vendor pricing power and extending implementation timelines for enterprise agricultural networks.
For Market Incumbents: Cement network effects by pre-integrating compliance modules for EU Green Deal Farm to Fork mandates and China's SAMR digitization requirements. Defend against interoperability specialists like OriginTrail by deepening ERP synchronization partnerships with SAP and Microsoft. Prioritize sensor-ledger convergence R&D to capture cold-chain verification expansion. For New Entrants and Emerging Players: Launch via blockchain-as-a-service models targeting Indian FSSAI spice supply chains and Brazilian grain cooperative smart contract automation. India's emerging digital infrastructure roadmap presents the most penetrable white space. Target carbon credit verification protocols for regenerative agriculture as the fastest-expanding application layer. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier agritech specialists with embedded sensor hardware and existing GS1 EPCIS 2.0 certification in Germany and the Netherlands. Long-term viability rests on regulatory recognition of consensus governance models as default compliance substrates. Watch for FDA Food Safety Modernization Act enforcement acceleration as the inflection signal for North American deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Pre-Integration | Accelerates EU Green Deal Farm to Fork certification timelines for protein processors. |
| Sensor-Ledger Convergence R&D | Captures cold-chain verification demand from Brazilian beef and Australian perishable exporters. |
| ERP Synchronization Partnership | Reduces middleware development friction for North American agricultural conglomerates. |
| Smart Contract Platform Launch | Compresses settlement cycles for US Midwest grain cooperatives and Brazilian soybean traders. |
| Carbon Credit Verification Protocol | Unlocks voluntary carbon market access for commodity crop farmers under emerging MRV standards. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with blockchain platform engineers, agricultural procurement directors at food processors, cold-chain logistics operators, and compliance officers at retail chains. FDA Food Safety Modernization Act documentation, EU Green Deal strategy papers, SAMR digitization circulars, and GS1 EPCIS 2.0 technical specifications supplemented bottom-up deployment tracking with top-down regulatory impact assessment.
Reconciliation of software licensing volumes, hardware shipment manifests, and services contract values against regulatory mandate implementation timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled encompass application depth, consensus protocol type, end-user scale tier, and regional regulatory cluster. CAGRs derived from deployment velocity curves weighted by compliance deadline proximity and buyer procurement specification hardening.
Regulatory enforcement delays, interoperability standard fragmentation, and smallholder connectivity infrastructure gaps are the dominant revision risks to deployment assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Industrial Blockchain Technology Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Global Blockchain Supply Chain Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Bitcoin Technology Market