
 Blockchain in Mining Market | 2026-2036
Blockchain in Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Mining Market Insights
ISO 14001 environmental management certification is collapsing as the baseline qualifier for blockchain-enabled mining operations seeking institutional offtake agreements. Core Scientific leverages its vertically integrated data center footprint to anchor energy-intensive proof-of-work validation in North American jurisdictions with stranded power assets. CleanSpark competes through aggressive geographic expansion into underutilized grid zones. Bitdeer Technologies Group differentiates via proprietary immersion-cooling architectures that sustain hash-rate density in thermally constrained environments.
Blockchain in mining denotes cryptographically linked distributed ledger architectures deployed to immutably record mineral provenance, carbon intensity metrics, and chain-of-custody events across extraction-to-refinement workflows; systems typically achieve finality through consensus mechanisms consuming 50–150 kWh per transaction depending on protocol selection. Supply Chain Transparency applications dominate current deployment value, as smelters and original equipment manufacturers face downstream audit requirements from automotive and electronics sectors. Asset Tracking segments are accelerating fastest, driven by tokenization of unrefined ore inventories to collateralize trade finance. Private Blockchain deployments occupy the deepest margin pools, since consortium configurations let incumbents retain governance control while excluding public network congestion and fee volatility.
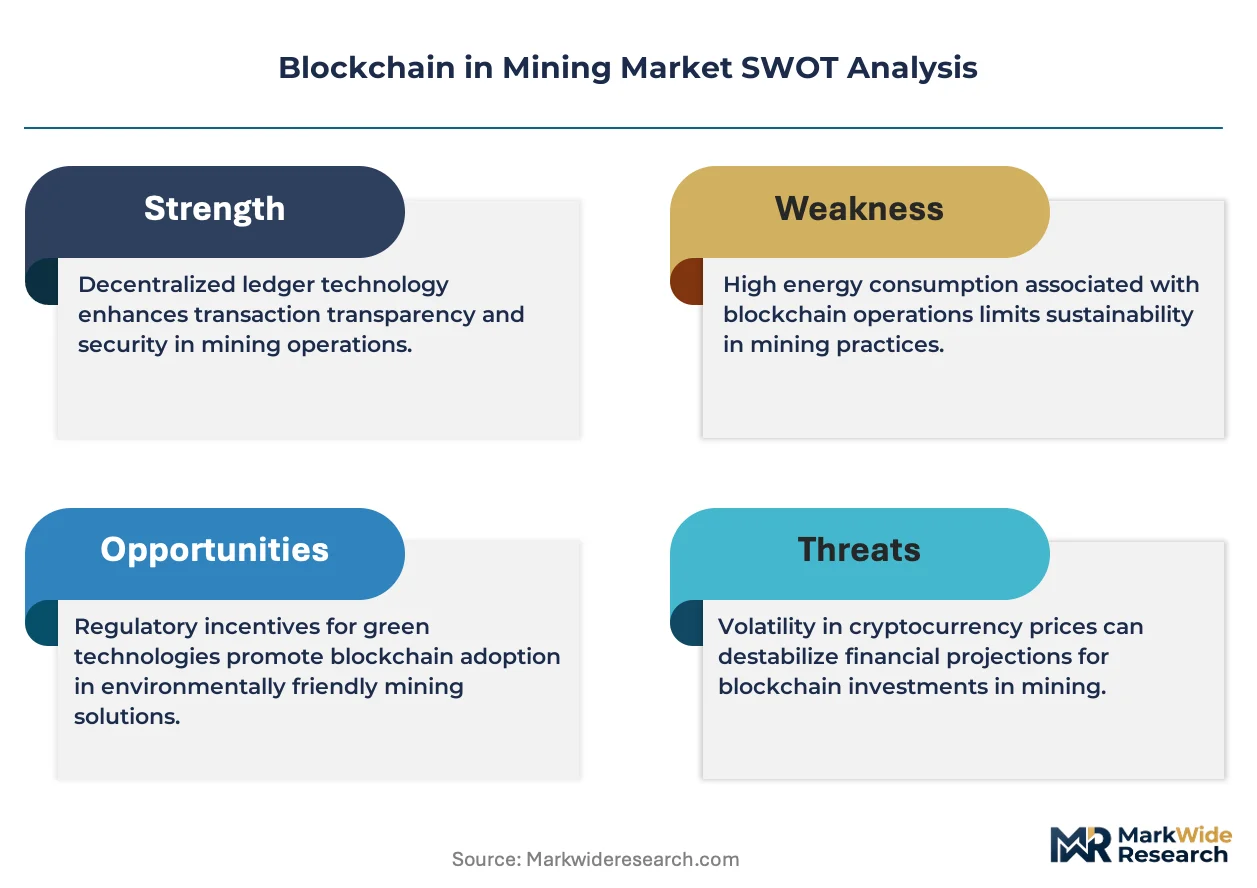
The SEC's climate disclosure rules and the EU CSRD mandate granular emissions traceability, forcing extraction companies to adopt tamper-proof reporting infrastructure or risk capital market exclusion. China's SAMR maintains parallel GB standards for blockchain data security that constrain cross-border ledger interoperability for mineral shipments originating from state-controlled concessions. Stakeholders must decide whether to build captive validation networks or subscribe to third-party consortium platforms before downstream customers harden supplier qualification criteria.
Market Dynamics
Downstream battery manufacturers are hardening supplier qualification criteria, forcing extraction operators to deploy immutable ledger infrastructure or face contract exclusion from automotive and electronics supply chains.
Growth Catalysts
- EU CSRD Mandate:Granular emissions traceability requirements compel mineral processors to adopt tamper-proof reporting infrastructure for capital market access.
- Lithium Provenance Verification:Electric vehicle OEMs now require cryptographic chain-of-custody documentation from Australian hard-rock and brine operations.
- Tokenized Ore Collateralization:Trade finance platforms are accelerating Asset Tracking segment adoption through blockchain-secured inventory monetization.
Market Restraints
- Validation Energy Costs:Proof-of-work consensus mechanisms consume 50–150 kWh per transaction, stranding operations in jurisdictions with expensive grid power.
- Cross-Border Ledger Friction:China's SAMR GB standards constrain interoperability for mineral shipments from state-controlled concessions.
- Consortium Governance Lock-In:Private blockchain configurations let incumbents exclude competitors, limiting network effects and interoperability.
Strategic Opportunities
- Underpenetrated African Copperbelt:DRC and Zambian cobalt-copper operations lack ESG disclosure infrastructure, creating first-mover advantage for ledger providers.
- AI-Blockchain Convergence:Machine learning models layered on immutable provenance data enable predictive carbon intensity scoring for smelter procurement.
- EU Green Deal Tailwind:Supply chain due diligence rules create regulatory pull for consortium platforms serving European mineral refiners.
Industry Challenges
- Distributed Systems Expertise Gap:Mining operations lack cryptographers and consensus mechanism engineers to architect secure validation networks.
- Legacy ERP Integration Complexity:SAP and Oracle installations require custom middleware to write tamper-proof records without disrupting batch processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Mining Market |
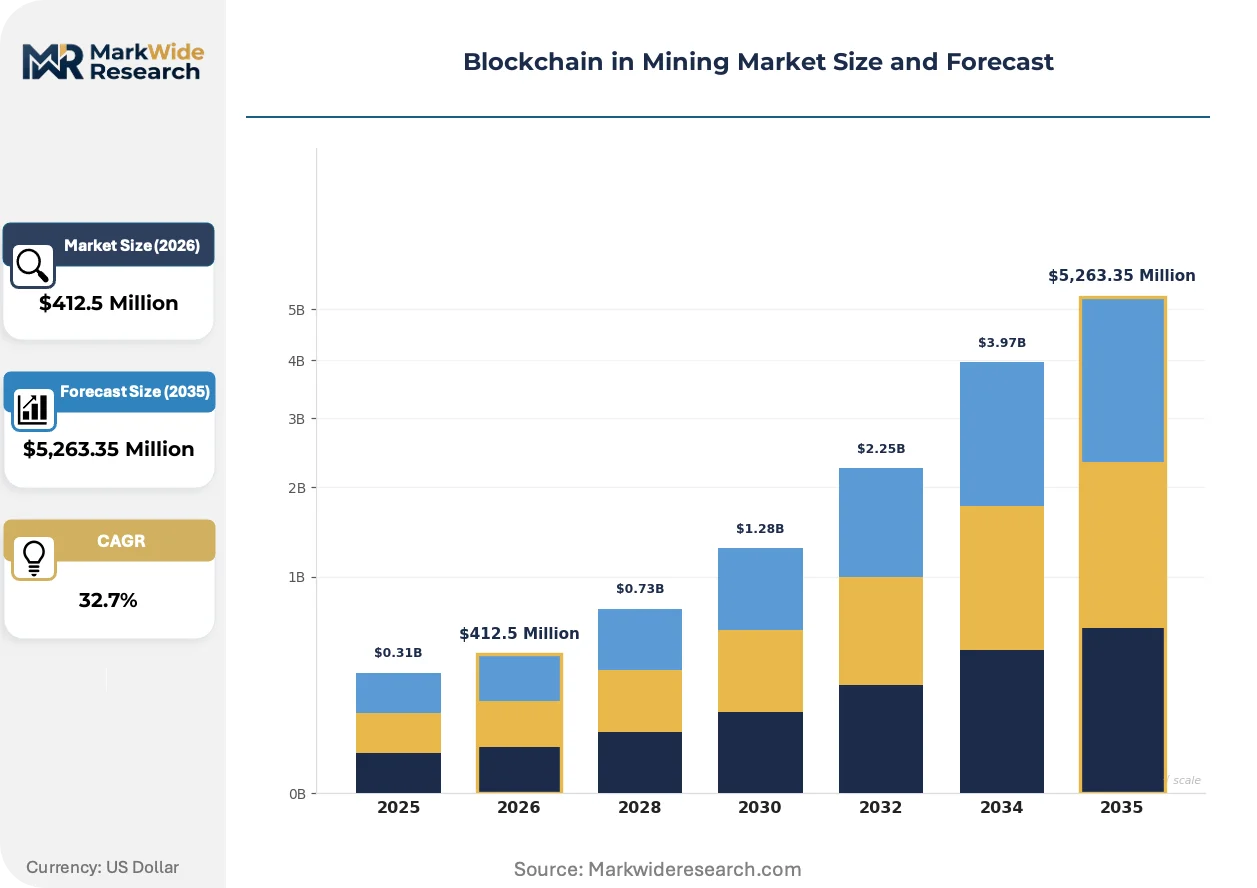
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $5,263.35 Million |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Transparency, Asset Tracking, Contract Management, Safety Compliance, Energy Usage Monitoring Technology: Private Blockchain, Public Blockchain, Consortium Blockchain, Hybrid Blockchain, Distributed Ledger Technology End User: Extraction Companies, Processing Entities, Equipment Manufacturers, Regulatory Bodies, Technology Providers Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Edge Computing |
| Companies Covered | Iris Energy, TeraWulf, Hut 8, Riot Platforms, Cipher Mining, Core Scientific, MARA Holdings, CleanSpark, Bitdeer Technologies Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Mining Market Trends and Innovations
Immutable ledger architectures are bifurcating into energy-intensive validation networks and lightweight permissioned systems, with deployment decisions increasingly tied to power cost arbitrage rather than cryptographic security alone.
Zero-knowledge proof protocols are fragmenting the identity layer of mineral provenance systems, allowing smelters to verify ESG compliance without exposing supplier pricing or concession terms to competitors. Automotive battery procurement teams in Germany and South Korea are piloting these privacy-preserving verification flows. The structural consequence is compressing information asymmetry between upstream miners and downstream manufacturers without dismantling commercial confidentiality.
The SEC's climate disclosure rules now require registrants to obtain third-party attestation of Scope 3 emissions data, pushing extraction companies toward blockchain-anchored measurement systems that resist retrospective manipulation. Mining CFOs face audit trail deficiencies that threaten 10-K filing timelines. North American copper and nickel operations are responding by pre-positioning sensor networks that stream directly to immutable ledgers before the 2025 attestation deadlines.
Automotive OEMs now mandate cryptographic provenance documentation as a condition of supplier qualification, displacing paper-based chain-of-custody records that dominated mineral purchasing through 2023. Tier-1 battery manufacturers in Japan and South Korea are transmitting these requirements upstream to Australian lithium and Indonesian nickel processors. The qualification burden falls heaviest on mid-scale concentrate traders lacking technical resources to deploy validation infrastructure independently.
Blockchain in Mining Market Segmentation
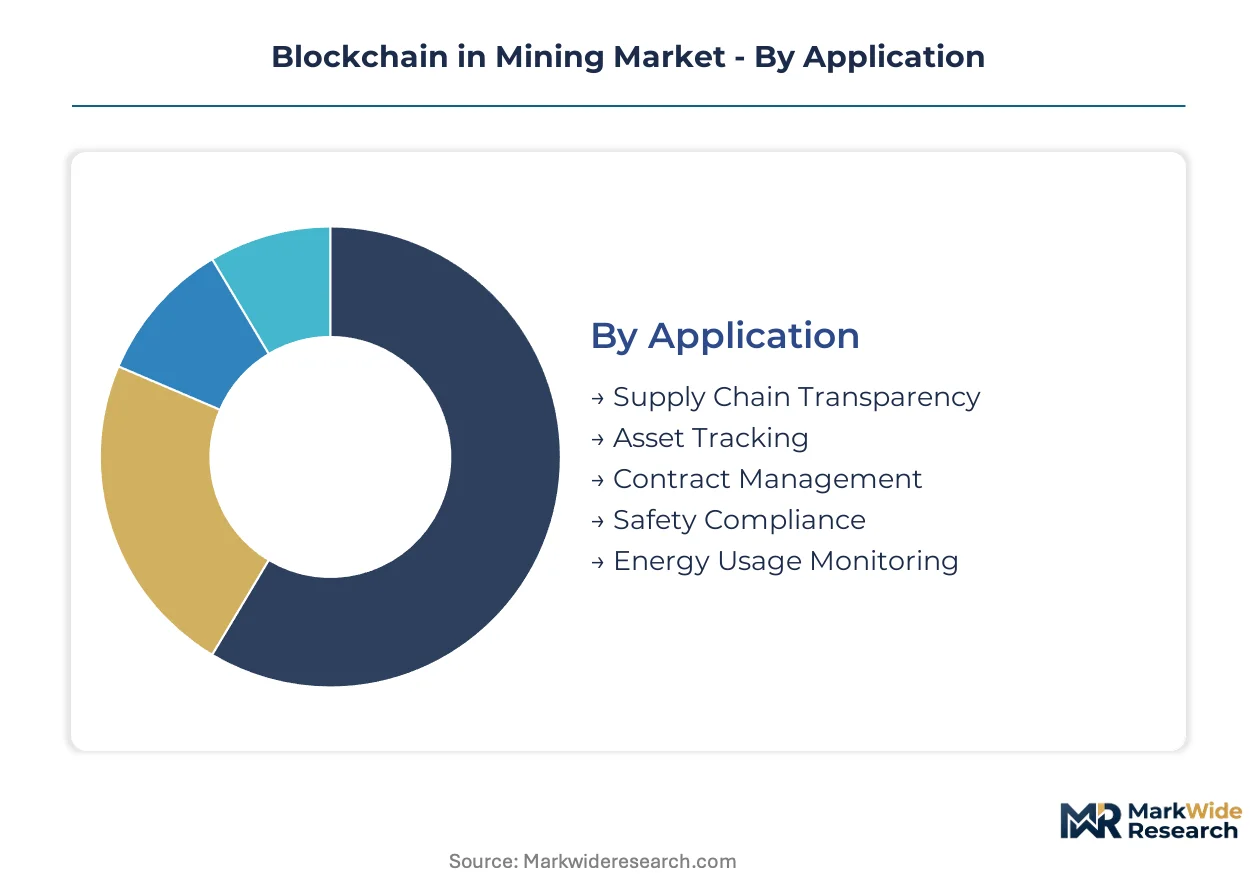
Segmentation in blockchain mining deployments reveals where ledger infrastructure commands premium pricing versus commodity substitution. Deployment choices across application type, consensus architecture, and operational model determine whether operators capture margin from ESG compliance or face cost-driven displacement by traditional audit systems.
Application:
Supply Chain Transparency faces acute substitution pressure from legacy paper-based chain-of-custody systems that remain entrenched in artisanal mineral corridors.
- Supply Chain Transparency:Cryptographic provenance documentation tracks mineral origin through extraction-to-refinement workflows. Australian lithium and Indonesian nickel processors deploy these systems to satisfy German and South Korean automotive OEM qualification requirements. Downstream battery manufacturers now mandate immutable records as a contractual condition.
- Asset Tracking:Tokenization of unrefined ore inventories enables blockchain-secured collateralization for trade finance platforms. DRC and Zambian cobalt-copper operations lacking ESG disclosure infrastructure present first-mover expansion opportunities for ledger providers.
- Contract Management:Smart contract automation enforces royalty payments and offtake terms without intermediary escrow.
- Safety Compliance:Immutable incident logging satisfies OSHA and national mining regulator audit requirements.
- Energy Usage Monitoring:Real-time carbon intensity streaming supports SEC climate disclosure attestation.
Supply Chain Transparency anchors the volume base while Asset Tracking gains share at the steepest rate.
Technology:
Cost tier stratification separates energy-intensive validation networks from lightweight permissioned systems, with power cost arbitrage increasingly outweighing cryptographic security in deployment decisions.
- Private Blockchain:Consortium configurations let incumbents retain governance control while excluding public network congestion and fee volatility. Mining CFOs favor these deployments for Scope 3 emissions data that resists retrospective manipulation ahead of third-party attestation deadlines.
- Public Blockchain:Decentralized consensus achieves finality through proof-of-work mechanisms consuming 50–150 kWh per transaction. Operations strand in jurisdictions with expensive grid power, limiting viable deployment to North American sites with stranded power assets.
- Consortium Blockchain:Multi-party governance structures balance transparency with commercial confidentiality for smelter procurement teams.
- Hybrid Blockchain:Selective data exposure combines public verification with private transaction details.
- Distributed Ledger Technology:Protocol-agnostic architectures accommodate future consensus mechanism migration.
Private Blockchain dominates current margin pools while Public Blockchain contracts under energy cost pressure.
End User:
Customer type determines whether blockchain deployments serve regulatory compliance, operational efficiency, or commercial differentiation objectives.
- Extraction Companies:Hard-rock and brine operators face mounting ESG disclosure pressure from downstream battery manufacturers. Australian lithium producers deploy sensor networks streaming directly to immutable ledgers to meet EU CSRD granular emissions traceability mandates.
- Processing Entities:Smelters and refiners require tamper-proof reporting infrastructure for capital market access under SEC climate disclosure rules. Zero-knowledge proof protocols allow ESG compliance verification without exposing supplier pricing to competitors.
- Equipment Manufacturers:Mining machinery OEMs track component provenance for warranty and recall management.
- Regulatory Bodies:National mining regulators audit immutable incident logs for enforcement actions.
- Technology Providers:Consortium platform operators monetize network infrastructure subscriptions.
Extraction Companies generate the largest deployment volumes while Processing Entities drive the steepest adoption acceleration.
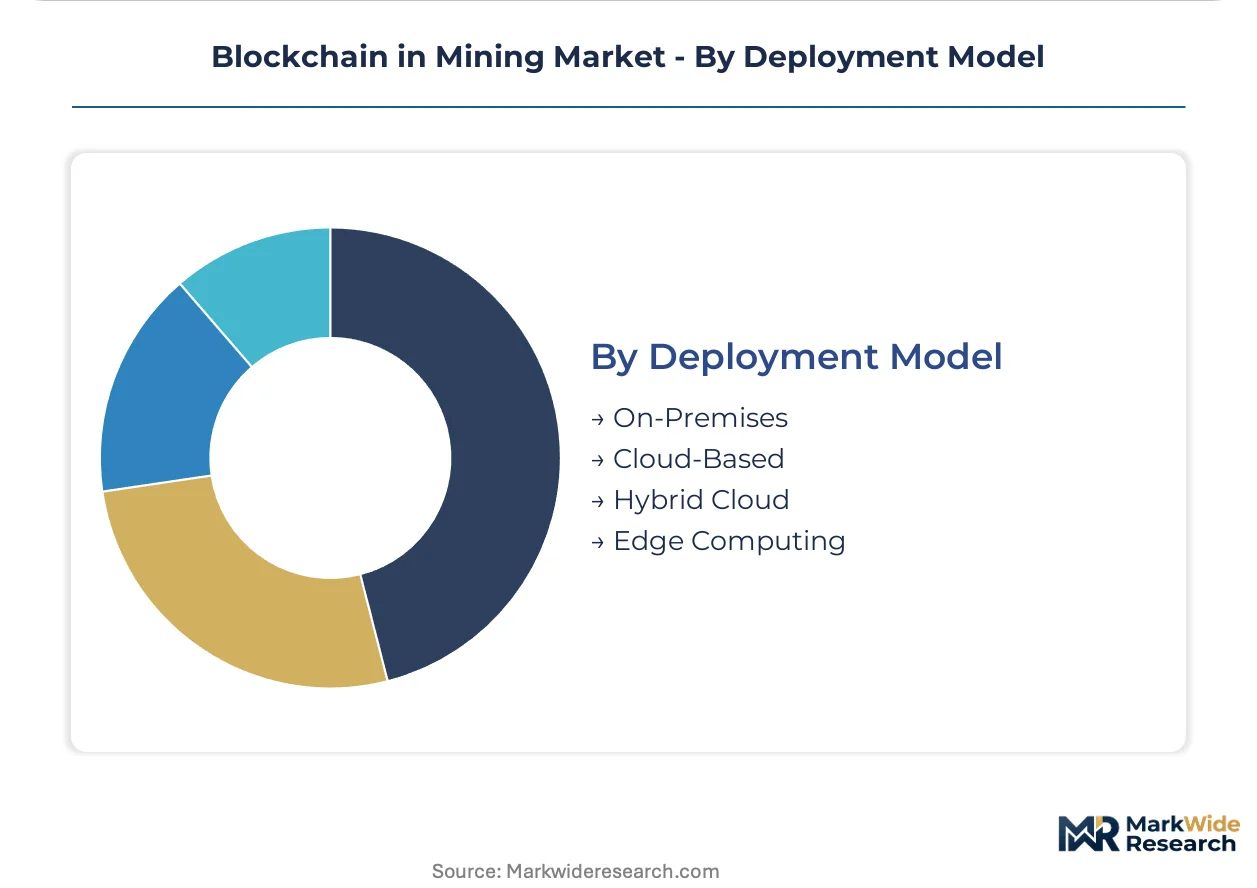
Deployment Model:
Volume concentration favors cloud architectures where mid-scale concentrate traders lack technical resources for independent validation infrastructure.
- Cloud-Based:Third-party hosted infrastructure eliminates capital expenditure for distributed systems expertise. Mid-scale traders subscribe to consortium platforms rather than architecting secure validation networks independently.
- On-Premises:Captive data centers anchor energy-intensive proof-of-work validation in jurisdictions with stranded power assets. Core Scientific leverages vertically integrated infrastructure for this deployment model.
- Hybrid Cloud:Sensitive provenance data resides on-premises while analytics workloads shift to public cloud.
- Edge Computing:Sensor-ledger integration at extraction sites minimizes latency for real-time carbon intensity monitoring.
Cloud-Based deployment captures the broadest adoption while Edge Computing climbs fastest among greenfield operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams in Germany and South Korea are transmitting cryptographic provenance requirements upstream to mineral processors. Extraction operators in lithium-rich jurisdictions face the steepest compliance burden as downstream battery manufacturers harden supplier qualification criteria.
Australia
Pilbara hard-rock lithium and Greenbushes operations deploy sensor networks streaming directly to immutable ledgers. The TGA oversees data integrity standards for mineral export certification. Perth-based technology providers are consolidating consortium platform subscriptions for mid-scale concentrate traders lacking independent validation infrastructure.
China
State-controlled rare earth concessions in Inner Mongolia and Jiangxi face SAMR GB standards constraining cross-border ledger interoperability. The MIIT promotes domestic blockchain architectures for mineral traceability. Ganzhou rare earth processing clusters are piloting captive validation networks to satisfy downstream electronics manufacturer audit requirements.
United States
Nevada lithium brine and Arizona copper operations pre-position sensor networks ahead of SEC climate disclosure attestation deadlines. The SEC mandates third-party verification of Scope 3 emissions data for registrants. Texas stranded power assets anchor energy-intensive proof-of-work validation for vertically integrated data center operators.
Indonesia
Nickel laterite processors in Sulawesi and Halmahera face cryptographic documentation requirements from South Korean battery manufacturers. The national mining regulator audits immutable incident logs for environmental compliance. Morowali Industrial Park operators subscribe to third-party consortium platforms rather than architecting independent ledger infrastructure.
Democratic Republic of Congo
Artisanal cobalt-copper corridors in Lualaba and Haut-Katanga lack ESG disclosure infrastructure, creating first-mover expansion opportunities for ledger providers. The country's national mining regulator struggles with chain-of-custody verification in informal extraction zones. Kolwezi trading hubs represent underpenetrated territory for blockchain-secured inventory monetization platforms.
Blockchain in Mining Market Competitive Landscape
Player mix skews toward vertically integrated data center operators and geographic expansion specialists. The vendor base concentrates around North American jurisdictions with stranded power assets and thermally optimized validation architectures. Two strategic archetypes dominate: captive infrastructure deployers leveraging proprietary energy arrangements, and immersion-cooling specialists sustaining hash-rate density in constrained environments. Competitive moves center on power cost arbitrage positioning and consortium platform subscriptions for mid-scale operators lacking technical resources.
Among North American infrastructure operators, Core Scientific, CleanSpark, and Bitdeer Technologies Group exemplify distinct positioning vectors. Core Scientific represents the vertically integrated archetype with captive data center footprints anchoring proof-of-work validation. CleanSpark occupies the geographic expansion specialist tier, targeting underutilized grid zones for operational deployment. Bitdeer Technologies Group sits within the thermal optimization segment, with nomenclature suggesting proprietary cooling architectures for density-constrained environments. These three entities collectively illustrate how power economics and thermal engineering differentiate competitive positioning in energy-intensive validation markets.
| Leading Market Players |
|---|
| Iris Energy |
| TeraWulf |
| Hut 8 |
| Riot Platforms |
| Cipher Mining |
| Core Scientific |
| MARA Holdings |
| CleanSpark |
| Bitdeer Technologies Group |
| Others |
Pricing and Supply Chain Analysis
Ninety-day sensor-deployment lead times for immutable ledger infrastructure concentrate pricing power with vertically integrated platform operators serving Australian lithium and Indonesian nickel processors under EU CSRD compliance deadlines. Consortium subscription models capture margin from mid-scale traders lacking captive validation expertise while energy-intensive proof-of-work deployments strand in high-cost grid jurisdictions.
Pricing Analysis
Cost-plus contracts indexed to stranded power asset availability dominate validation network pricing, with tariffs scaling to kWh consumption bands. Pricing stratifies across premium consortium governance tiers, standard cloud-hosted subscriptions, and economy sensor-only telemetry packages. Cost compression in public blockchain tiers intensifies because proof-of-work energy economics disqualify expensive grid zones. Mid-scale concentrate traders exhibit highest price sensitivity, while Tier-1 battery manufacturers prioritize tamper-proof attestation over subscription cost.
Supply Chain Analysis
Container availability constraints on the Australia-East Asia lithium concentrate lane inflate inbound logistics costs for sensor hardware deployments. Supply concentrates in Australia, Indonesia, and the Democratic Republic of Congo for hard-rock lithium, nickel laterite, and artisanal cobalt respectively. Hardware components draw from Taiwanese semiconductor foundries, German industrial sensor manufacturers, and Chinese rare earth magnet suppliers. Single-source vulnerability sits with ASIC chip fabrication for proof-of-work validation equipment. Distribution runs through Perth-based technology providers consolidating consortium platform subscriptions for regional mining operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as interoperability standards fragment between China's SAMR GB architectures and EU Green Deal-aligned consortium configurations, forcing stakeholders to commit to governance ecosystems before downstream qualification criteria harden.
For Market Incumbents: Consolidate consortium platform subscriptions through exclusive partnerships with Australian lithium processors facing German automotive OEM deadlines. Deepen backward integration into stranded power assets across Texas and Arizona to anchor energy-intensive validation cost structures. Zero-knowledge proof protocol development represents the priority capability investment against emerging privacy-preserving entrants. For New Entrants and Emerging Players: Anchor in underpenetrated African Copperbelt operations lacking ESG disclosure infrastructure, specifically DRC and Zambian cobalt-copper corridors where first-mover ledger deployment captures trade finance collateralization flows. Target cloud-hosted subscription models for mid-scale concentrate traders in Kolwezi trading hubs unable to architect independent validation networks. Go-to-market positioning should emphasize rapid sensor-deployment timelines against incumbent ninety-day implementation cycles. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because SEC climate disclosure attestation requirements and EU CSRD mandates create durable demand for tamper-proof reporting systems resistant to retrospective manipulation. Acquisition targets should display vertical integration into thermally optimized data center assets or proprietary immersion-cooling IP. The signal to watch is third-party attestation deadline acceleration by securities regulators, which compresses implementation timelines and favors incumbent platform operators with proven deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Platform Subscription | Captures recurring revenue from Australian lithium processors under EU CSRD compliance pressure. |
| Backward Integration into Power Assets | Secures stranded energy cost arbitrage for proof-of-work validation in Texas grid zones. |
| Zero-Knowledge Proof Development | Enables South Korean battery manufacturers to verify ESG compliance without exposing supplier pricing. |
| Edge Computing Sensor Deployment | Minimizes latency for real-time carbon intensity monitoring at Indonesian nickel laterite sites. |
| Trade Finance Platform Integration | Tokenizes DRC cobalt inventories to collateralize working capital for artisanal mining cooperatives. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with mining technology officers, consortium platform architects, and ESG compliance leads at Australian and Indonesian extraction operations; and secondary validation against SEC climate disclosure filings, EU CSRD implementation guidance, SAMR GB standard documentation, and customs records for blockchain hardware imports. Bottom-up deployment sizing triangulated against top-down regulatory mandate coverage estimates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning application type, consensus architecture, deployment model, and end-user category with regional regulatory cluster overlays. CAGRs derived from installed base growth curves weighted by attestation deadline proximity. Forecast inputs incorporated sensor hardware cost decline trajectories and stranded power asset availability by North American grid zone.
Material uncertainties — regulatory deadline extensions, cross-border ledger interoperability breakthroughs, and proof-of-stake protocol migration at scale — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU Green Deal enforcement continuity and SEC climate rule litigation outcomes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Tokenization Market