
 Global Blockchain Market | 2026-2036
Global Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain Market Analysis
Singapore is tilting toward blockchain infrastructure dominance through its regulatory sandbox programs and central bank digital currency pilots. IBM leverages enterprise-grade permissioned networks to anchor institutional trust in supply chain and trade finance workflows. Amazon Web Services sustains cloud-native blockchain services that reduce deployment friction for developers building on Ethereum and Hyperledger Fabric.
Blockchain denotes a cryptographically linked distributed ledger where consensus mechanisms validate sequential blocks of timestamped transactions without centralized intermediaries. Hash functions, Merkle trees, and Byzantine fault tolerance protocols ensure data immutability across permissionless or permissioned network topologies. Public blockchain networks capture speculative liquidity and developer attention, while private blockchain deployments generate recurring enterprise revenue through subscription licensing and managed infrastructure. Smart contract applications are expanding fastest in trade finance and insurance automation, though identity verification segments face margin pressure from commoditized biometric APIs.
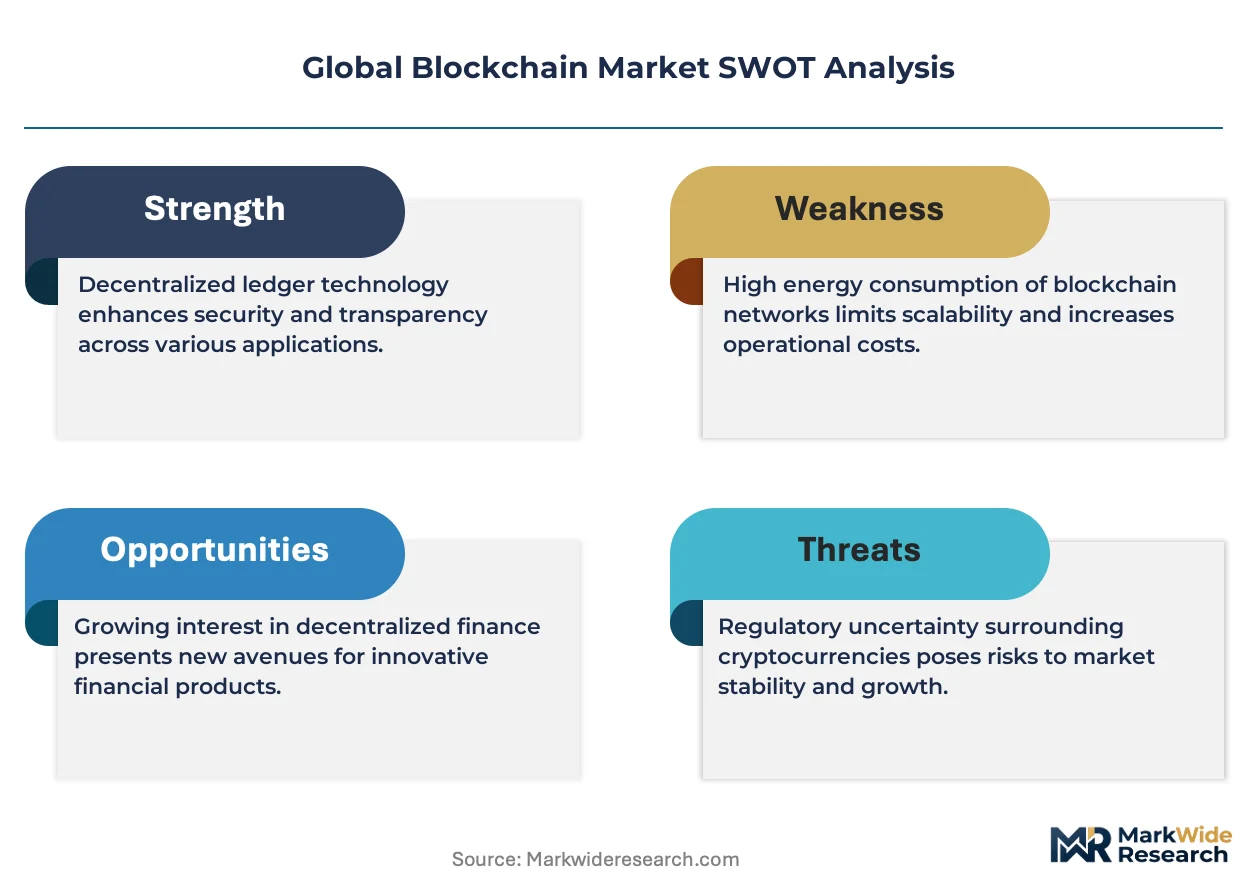
The US SEC, EU MiCA framework, and Singapore MAS shape market access through divergent token classification regimes and custody rules that fragment cross-border product design. ISO 23447 blockchain reference architecture standards are pressuring vendors toward interoperability certifications that reduce client switching costs. Stakeholders must monitor jurisdictional arbitrage risks as enforcement intensity diverges between asset-friendly hubs and restrictive regimes.
Market Dynamics
The divergence between permissionless public networks and permissioned enterprise deployments is fracturing vendor business models and forcing specialization bets. Financial institutions now demand ISO 23447 interoperability certifications before procurement, while energy-intensive consensus mechanisms face mounting environmental compliance costs.
Growth Catalysts
- EU MiCA framework:The Markets in Crypto-Assets regulation provides legal certainty for tokenized securities, prompting institutional custody infrastructure investment across Frankfurt and Paris.
- Trade finance digitization:Letter-of-credit automation through smart contracts reduces documentary processing time for commodity traders operating through Singapore's TradeTrust framework.
- Layer-2 scaling solutions:Rollup architectures compress transaction costs sufficiently for micropayment viability in emerging-market remittance corridors.
Market Restraints
- Energy input volatility:Proof-of-work validation remains tethered to electricity price swings, exposing mining operations in Kazakhstan and Texas to margin compression during peak demand periods.
- Validator concentration:Staking pools on major public networks exhibit geographic clustering, creating systemic resilience risks if jurisdictional enforcement actions target specific hosting jurisdictions.
- Cross-chain interoperability gaps:Bridge protocols suffer from smart contract exploit vulnerabilities that deter institutional treasury allocation despite yield advantages.
Strategic Opportunities
- Brazilian agribusiness tokenization:Soybean and cattle supply chains present underpenetrated use cases for provenance tracking, with B3 exchange infrastructure enabling commodity-linked digital assets.
- AI-oracle convergence:Machine-learning attestation mechanisms paired with decentralized verification create new service layers for parametric insurance automation.
- UAE regulatory sandbox expansion:Dubai's VARA framework permits experimental custody and exchange licensing that accelerates product iteration cycles unavailable in restrictive jurisdictions.
Industry Challenges
- Cryptographic talent scarcity:Zero-knowledge proof engineering and formal verification skills command premium compensation, constraining protocol development velocity for mid-tier projects.
- Legacy system integration friction:Core banking infrastructure at major financial institutions requires extensive API middleware development to interface with distributed ledger networks, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain Market |
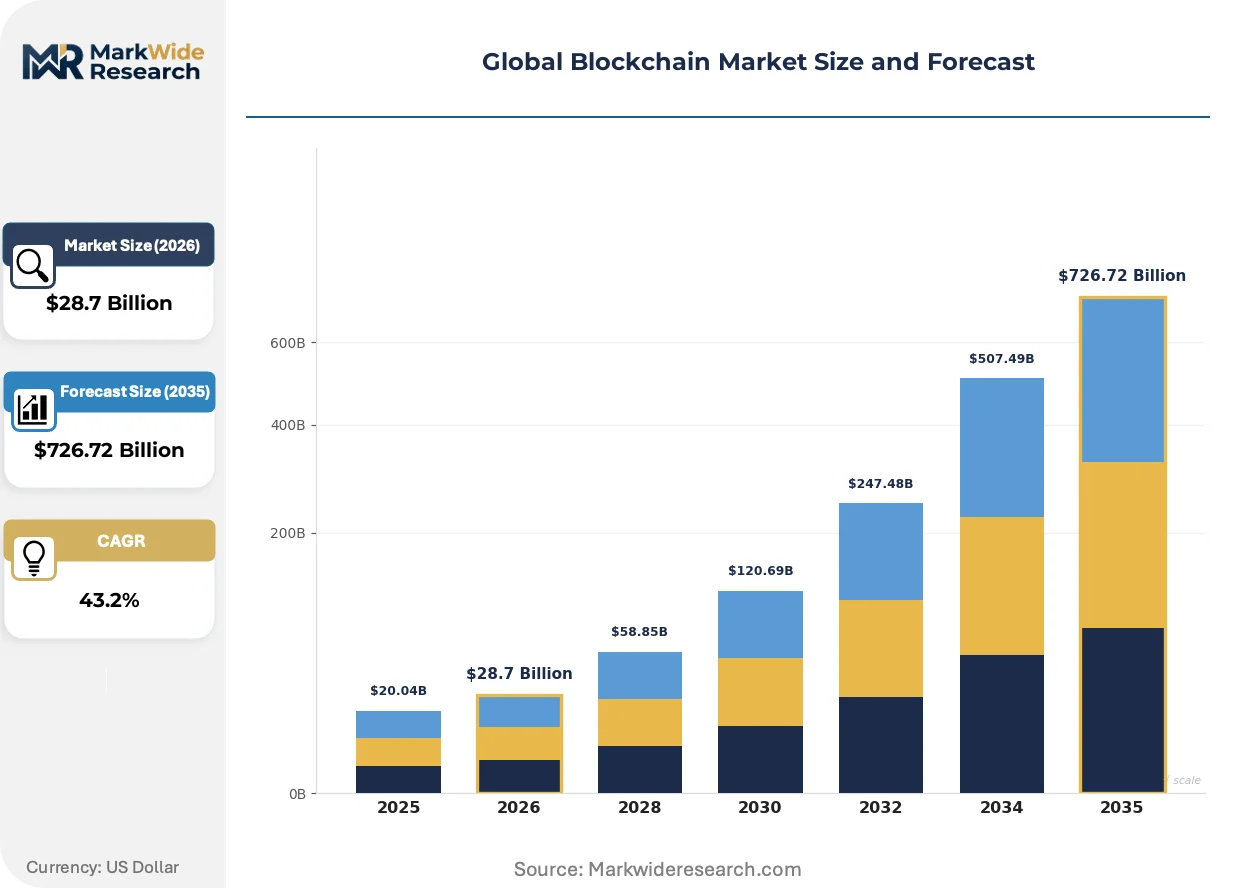
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $726.72 Billion |
| CAGR (2026 – 2036) | 43.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Application: Cryptocurrency, Supply Chain Management, Smart Contracts, Identity Verification End User: Financial Services, Healthcare, Retail, Government Deployment: On-Premises, Cloud, Hybrid, Others |
| Companies Covered | IBM, Amazon Web Services, Oracle, Accenture, Microsoft, SAP, Huawei, Intel, R3, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain Market Emerging Trajectories
Zero-knowledge proof architectures are migrating from academic cryptography into production financial infrastructure, compressing verification costs while expanding privacy-preserving transaction throughput. This shift is redrawing competitive boundaries between specialized infrastructure providers and generalist cloud platforms.
Account abstraction standards are rendering obsolete conventional externally-owned wallet architectures that require native token holdings for gas fee payment. Institutional custody providers including Anchorage and Fireblocks have accelerated ERC-4337 implementation timelines, enabling corporate treasury departments to sponsor transaction fees on behalf of end-users. The structural consequence is collapsing onboarding friction for consumer-facing applications previously gated by cryptocurrency acquisition complexity.
The EU AI Act's risk-classification framework is imposing algorithmic audit requirements on smart contract systems deployed within European Economic Area jurisdiction. Automated decision-making protocols now face conformity assessment obligations previously reserved for medical device software, compelling protocol developers to embed explainability features. Decentralized finance applications with leveraged lending automation represent the most affected segment, with several protocols withdrawing European IP geofencing rather than compliance investment.
Corporate procurement of blockchain infrastructure is consolidating around annual enterprise licensing contracts with embedded service-level agreements, displacing consumption-based node access models. Manufacturing conglomerates in Germany and Switzerland now mandate dedicated technical account management and guaranteed response times for production network outages. This behavioral pivot favors established systems integrators with existing C-suite relationships over native protocol foundations lacking enterprise sales infrastructure.
Global Blockchain Market Segmentation
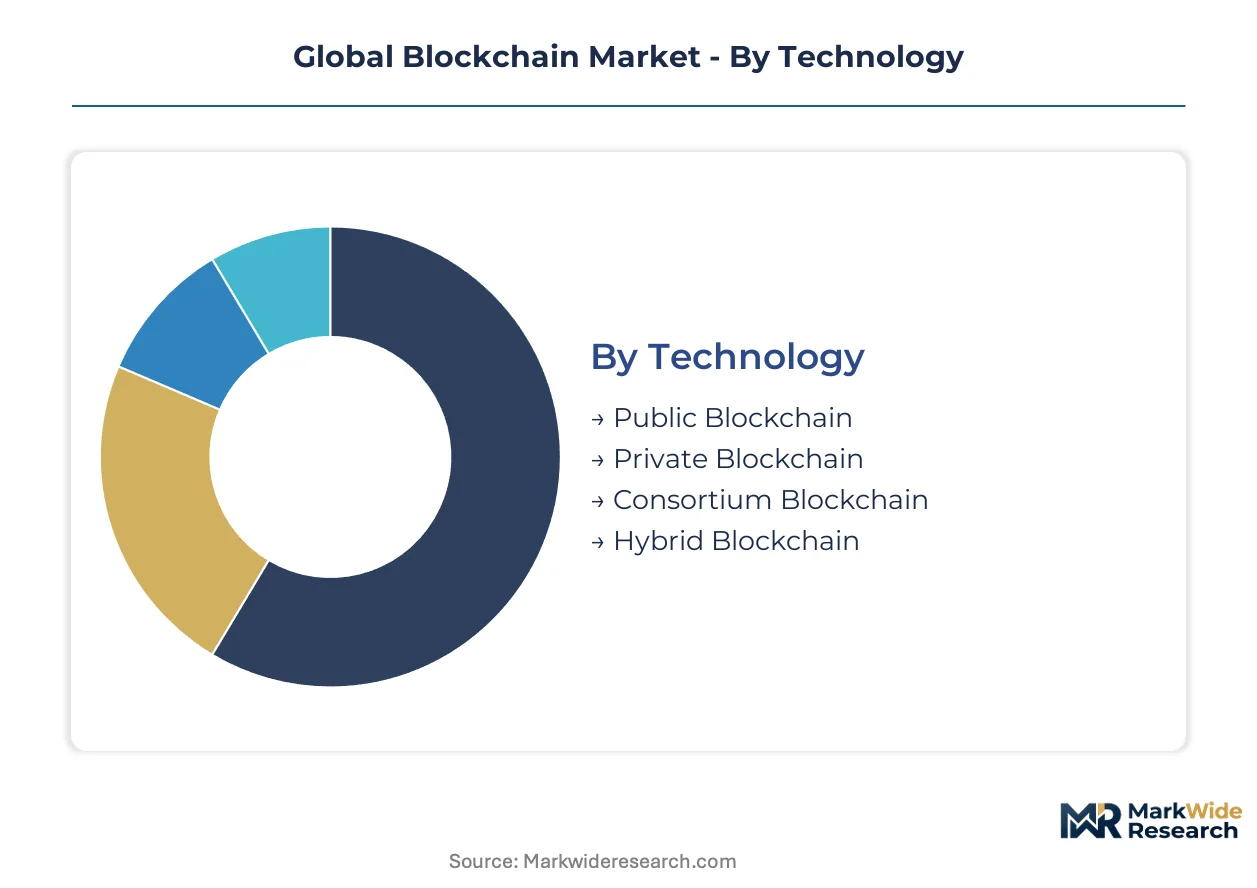
Blockchain market segmentation reveals divergent commercial rhythms across network architectures and deployment modes. Technology choices determine validation economics and regulatory exposure, while application segments show starkly different procurement cycles and margin structures.
Technology:
Public blockchain infrastructure turns over fastest as speculative liquidity and developer attention shift between layer-1 networks quarterly. Private blockchain deployments exhibit multi-year enterprise sales cycles with subscription renewal concentration. Consortium formations require extended governance negotiations among competing institutions. Hybrid architectures face the slowest adoption as integration complexity prolongs pilot phases.
- Public Blockchain:Permissionless networks rely on cryptographic consensus mechanisms like proof-of-stake or proof-of-work to validate transactions without centralized gatekeepers. Ethereum and Solana capture developer mindshare in Singapore and the UAE, where regulatory sandboxes permit experimental token issuance without securities classification. Validator economics remain tethered to cryptocurrency price volatility.
- Private Blockchain:Permissioned ledgers restrict node participation to pre-approved entities, enabling throughput optimization and data confidentiality for enterprise workflows. Hyperledger Fabric and R3 Corda dominate procurement at Frankfurt trade finance consortia, where ISO 23447 interoperability certifications have become mandatory pre-qualification criteria. Procurement committees prioritize vendor stability over feature velocity.
- Consortium Blockchain:Multi-party governance structures distribute infrastructure costs among industry competitors with shared operational interests. Maritime shipping alliances and diamond provenance networks favor this model for mutualizing platform development expenses.
- Hybrid Blockchain:Architectures partition sensitive data on private subnets while anchoring integrity proofs to public chains for external verification. Pharmaceutical supply chains in Switzerland deploy hybrid models to satisfy both patient privacy requirements and regulatory audit mandates.
Private blockchain dominates installed base through recurring enterprise licensing. Public blockchain is where expansion concentrates as account abstraction standards collapse consumer onboarding friction.
Application:
Cost tier differentiation separates capital-intensive infrastructure deployments from lightweight protocol integrations. Smart contract automation commands premium implementation fees due to formal verification requirements, while identity verification faces commoditization pressure from biometric API competition.
- Cryptocurrency:Native token issuance and exchange infrastructure anchor speculative liquidity flows and cross-border settlement rails. Dubai's VARA framework permits experimental custody licensing that accelerates product iteration unavailable in restrictive jurisdictions. Regulatory arbitrage between Singapore, Switzerland, and the UAE shapes exchange domicile decisions.
- Supply Chain Management:Distributed provenance tracking replaces paper-based documentation with immutable shipment records and automated compliance attestation. Brazilian agribusiness tokenization of soybean and cattle supply chains presents underpenetrated expansion opportunities through B3 exchange infrastructure.
- Smart Contracts:Self-executing protocols automate conditional value transfer without intermediary intervention. Trade finance digitization through letter-of-credit automation reduces documentary processing time for commodity traders operating through Singapore's TradeTrust framework.
- Identity Verification:Decentralized credential systems enable selective disclosure of personal attributes without centralized identity providers. Margin compression from commoditized biometric APIs constrains pricing power in this segment.
Supply chain management dominates installed base through manufacturing conglomerate procurement. Smart contracts are where expansion concentrates as the EU MiCA framework prompts institutional custody infrastructure investment.
End User:
Customer type segmentation separates regulated financial institutions with extended compliance review cycles from retail adopters with compressed decision timelines. Healthcare procurement exhibits the slowest adoption due to patient data protection requirements and legacy system integration friction.
- Financial Services:Banks, asset managers, and payment processors deploy distributed ledgers for cross-border settlements, trade finance, and tokenized securities custody. Frankfurt and Paris institutions are expanding infrastructure investment following EU MiCA legal certainty for tokenized instruments. The US SEC enforcement actions continue fragmenting product design.
- Healthcare:Providers and insurers pilot credential verification and claims automation while navigating patient data protection requirements. HIPAA compliance constraints and legacy EHR integration friction extend deployment timelines beyond other sectors.
- Retail:Merchants and consumer brands explore loyalty program tokenization and provenance marketing. Account abstraction standards enable corporate treasury departments to sponsor transaction fees on behalf of end-users.
- Government:Central banks and regulatory authorities pilot central bank digital currencies and sandbox frameworks. Singapore MAS and UAE VARA lead sandbox program development.
Financial services dominates installed base through enterprise licensing concentration. Government is where expansion concentrates as central bank digital currency pilots proliferate.
Deployment:
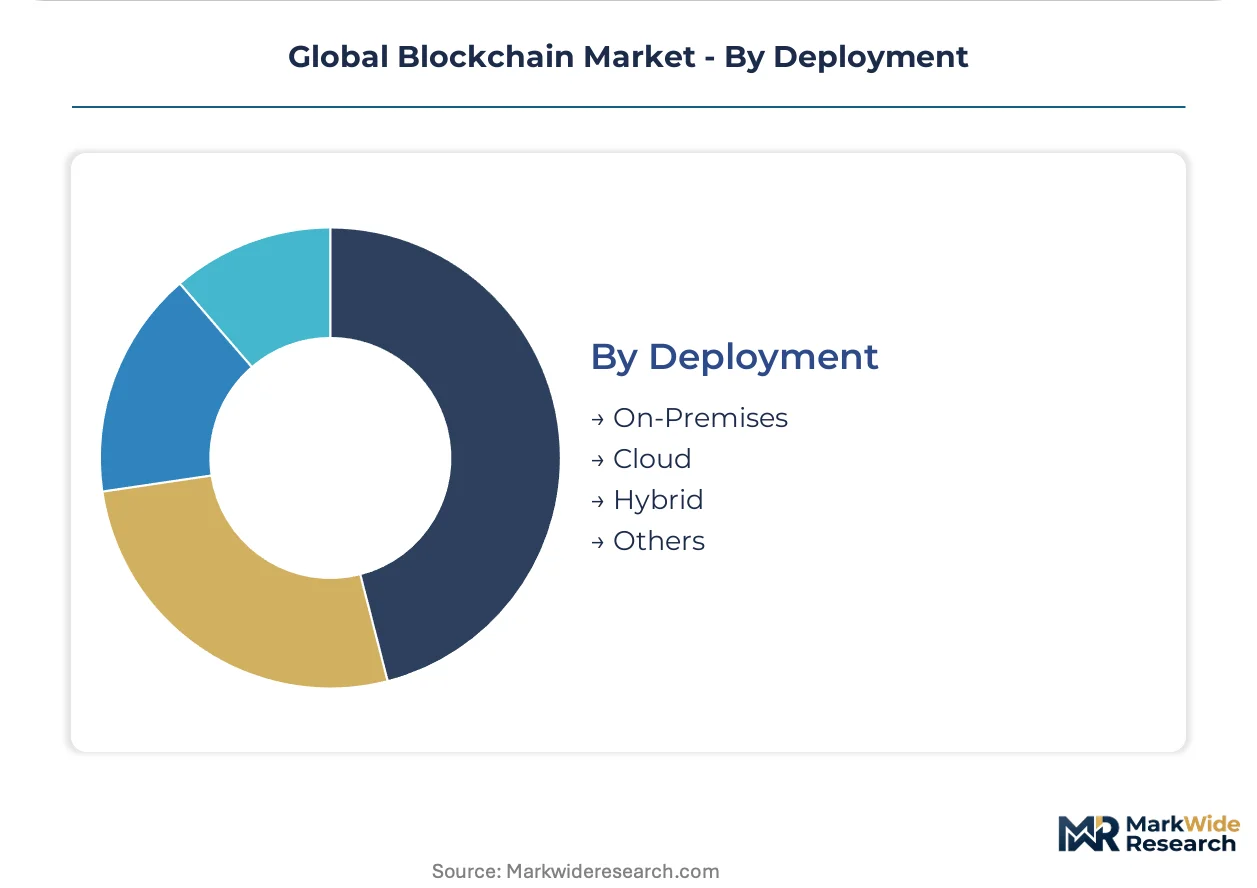
Volume concentration favors cloud-native deployments that reduce node provisioning friction for developers, while on-premises installations retain preference among financial institutions with data sovereignty requirements.
- On-Premises:Self-hosted infrastructure provides maximum data control and customization latitude for institutions with strict residency requirements. German manufacturing conglomerates mandate dedicated technical account management and guaranteed response times for production network outages.
- Cloud:Managed node services and blockchain-as-a-service platforms compress deployment timelines and operational overhead. Amazon Web Services sustains cloud-native services reducing friction for Ethereum and Hyperledger Fabric developers.
- Hybrid:Workload partitioning across private infrastructure and public cloud optimizes cost and control tradeoffs. Swiss pharmaceutical networks deploy hybrid models for patient privacy compliance.
- Others:Edge computing and specialized hardware deployments serve latency-sensitive applications and energy-intensive validation operations.
Cloud dominates installed base through developer accessibility and operational simplicity. Hybrid is where expansion concentrates as data sovereignty requirements intensify across European and Asian jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Singapore-Johor Bahru digital corridor anchors blockchain infrastructure development across Southeast Asia, with submarine cable landing stations and data center clusters underwriting the city-state's role as a custody and exchange hub.
United States
Texas energy markets and Wyoming's special purpose depository institution framework attract mining operations and custody providers seeking jurisdictional clarity. The US SEC enforcement actions fragment product design between registered securities offerings and decentralized protocol architectures. Miami and Austin metropolitan clusters concentrate venture funding for layer-1 network development.
Singapore
TradeTrust framework digitization and central bank digital currency pilots drive institutional adoption among commodity traders and correspondent banks. The Monetary Authority of Singapore sandbox programs permit experimental token issuance without immediate securities classification. Marina Bay financial district hosts the densest concentration of institutional custody infrastructure in Asia-Pacific.
Germany
Frankfurt trade finance consortia and BaFin crypto custody licensing create procurement concentration among regulated financial institutions. The EU MiCA framework provides legal certainty for tokenized securities, prompting infrastructure investment across the Rhine-Main metropolitan region. Stuttgart and Munich automotive clusters pilot supply chain provenance networks for battery mineral tracking.
United Arab Emirates
Dubai's VARA framework permits experimental custody and exchange licensing unavailable in restrictive jurisdictions, accelerating product iteration cycles. Abu Dhabi Global Market regulatory infrastructure attracts institutional treasury allocation to digital asset products. Dubai International Financial Centre concentrates blockchain service provider headquarters for Middle East and Africa market access.
Switzerland
Zug Crypto Valley governance frameworks and FINMA token classification guidance anchor private banking integration of digital assets. Swiss pharmaceutical supply chains deploy hybrid blockchain architectures to satisfy patient privacy requirements and regulatory audit mandates. Geneva and Zurich private banking clusters drive demand for institutional-grade custody and tokenized security infrastructure.
Global Blockchain Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with consensus mechanism and cryptographic tooling offerings. The vendor base concentrates around cloud hyperscalers with managed blockchain services and enterprise software incumbents with permissioned network deployments. Three strategic archetypes dominate: infrastructure providers with data center footprints, systems integrators with financial services relationships, and protocol foundations with developer ecosystem leverage. Competitive moves center on ISO 23447 interoperability certification acquisition and vertical integration into managed custody operations.
Within the enterprise platform tier, IBM and Amazon Web Services exemplify divergent positioning strategies. IBM leverages permissioned network expertise and trade finance workflow integration to anchor institutional trust. Amazon Web Services sustains cloud-native service breadth that reduces deployment friction for Ethereum and Hyperledger Fabric developers. SAP occupies a position bridging ERP system integration with distributed ledger middleware for manufacturing conglomerates in Germany and Switzerland.
| Leading Market Players |
|---|
| IBM |
| Amazon Web Services |
| Oracle |
| Accenture |
| Microsoft |
| SAP |
| Huawei |
| Intel |
| R3 |
| Others |
Supply Flow & Price Mechanics
Singapore's Marina Bay data center cluster concentrates enterprise blockchain infrastructure capacity, with hyperscaler node provisioning density translating directly into subscription pricing leverage for managed ledger services across Asia-Pacific financial institutions.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with three-tier pricing separating ISO 23447-certified infrastructure from standard cloud-native deployments and economy-grade developer sandbox access. Certification premiums command substantial markups as Frankfurt trade finance consortia mandate interoperability compliance. Pricing pressure stems from cloud hyperscaler entry into managed blockchain services, compressing margins for independent node operators. Financial institutions exhibit lowest price sensitivity due to compliance-driven procurement, while retail-facing application developers negotiate aggressively on per-transaction fees.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor hardware procurement for validation infrastructure, with Taiwanese semiconductor foundries and South Korean memory manufacturers providing critical components for enterprise-grade node deployments. Specialized ASIC manufacturing concentrates in China and the United States, while cooling and power distribution systems source primarily from German industrial suppliers. Single-source vulnerability in zero-knowledge proof accelerator chips creates systemic risk for privacy-preserving protocol developers. Distribution runs through systems integrators with existing financial services relationships rather than direct vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-knowledge proof engineering talent scarcity constrains protocol development velocity, with formal verification skills commanding compensation premiums that fragment competitive capacity across mid-tier projects.
For Market Incumbents: Build switching-cost moats through ISO 23447 interoperability certification depth and embedded technical account management. Deepen backward integration into specialized hardware accelerators for zero-knowledge computation. Anchor institutional relationships through guaranteed service-level agreements that match German manufacturing conglomerate procurement requirements. Counter cloud hyperscaler price competition with compliance expertise and vertical workflow integration. For New Entrants and Emerging Players: Establish a beachhead in Brazilian agribusiness tokenization, where B3 exchange infrastructure enables commodity-linked digital assets with limited incumbent presence. Target UAE regulatory sandbox participation through Dubai VARA experimental licensing frameworks. Pursue AI-oracle convergence for parametric insurance automation as the fastest-penetrating smart contract application segment. Differentiate through machine-learning attestation mechanisms rather than infrastructure scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among private blockchain infrastructure providers with multi-year enterprise licensing concentration. Long-term viability hinges on jurisdictional diversification across Singapore, Switzerland, and UAE regulatory frameworks. Prioritize acquisition targets with established central bank digital currency pilot relationships and embedded trade finance workflow integration. Watch staking pool geographic concentration as an inflection indicator for systemic resilience risk.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 23447 Certification Acquisition | Frankfurt consortia now mandate interoperability compliance as mandatory procurement pre-qualification. |
| Central Bank Digital Currency Partnership | Singapore MAS pilots provide institutional credibility anchoring for custody infrastructure providers. |
| Zero-Knowledge Proof Hardware Integration | Specialized accelerator chips reduce verification costs for privacy-preserving financial infrastructure. |
| UAE Regulatory Sandbox Entry | Dubai VARA experimental licensing accelerates product iteration unavailable in restrictive jurisdictions. |
| Trade Finance Workflow Embedding | Letter-of-credit automation through Singapore TradeTrust reduces documentary processing friction. |
Methodological Framework
A standing panel of protocol engineering leads, enterprise CTOs, regulatory sandbox administrators, and trade finance operations directors provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC enforcement action filings, EU MiCA regulatory texts, MAS sandbox program disclosures, and ISO standards documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across public and private deployment modes.
Scenario-bracketing framed analytical boundaries across permissionless and permissioned network adoption trajectories, with segmentation modeled by technology architecture, application vertical, end-user industry, and deployment topology. CAGRs derived from historical infrastructure investment patterns and regulatory milestone probability weighting. Forecast inputs incorporated energy price volatility for proof-of-work operations and cloud hyperscaler capex disclosure trends for managed service expansion.
Stress conditions across electricity input costs, jurisdictional enforcement intensity, and cross-chain bridge security incidents were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory sandbox program continuity and institutional custody infrastructure buildout. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Blockchain in Mining Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Industrial Blockchain Technology Market
Blockchain Technology
Smart Contracts on Blockchain Market