
 North America Business Process-As-A-Service (Bpaas) Market | 2026-2036
North America Business Process-As-A-Service (Bpaas) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Business Process-As-A-Service (Bpaas) Market Insights
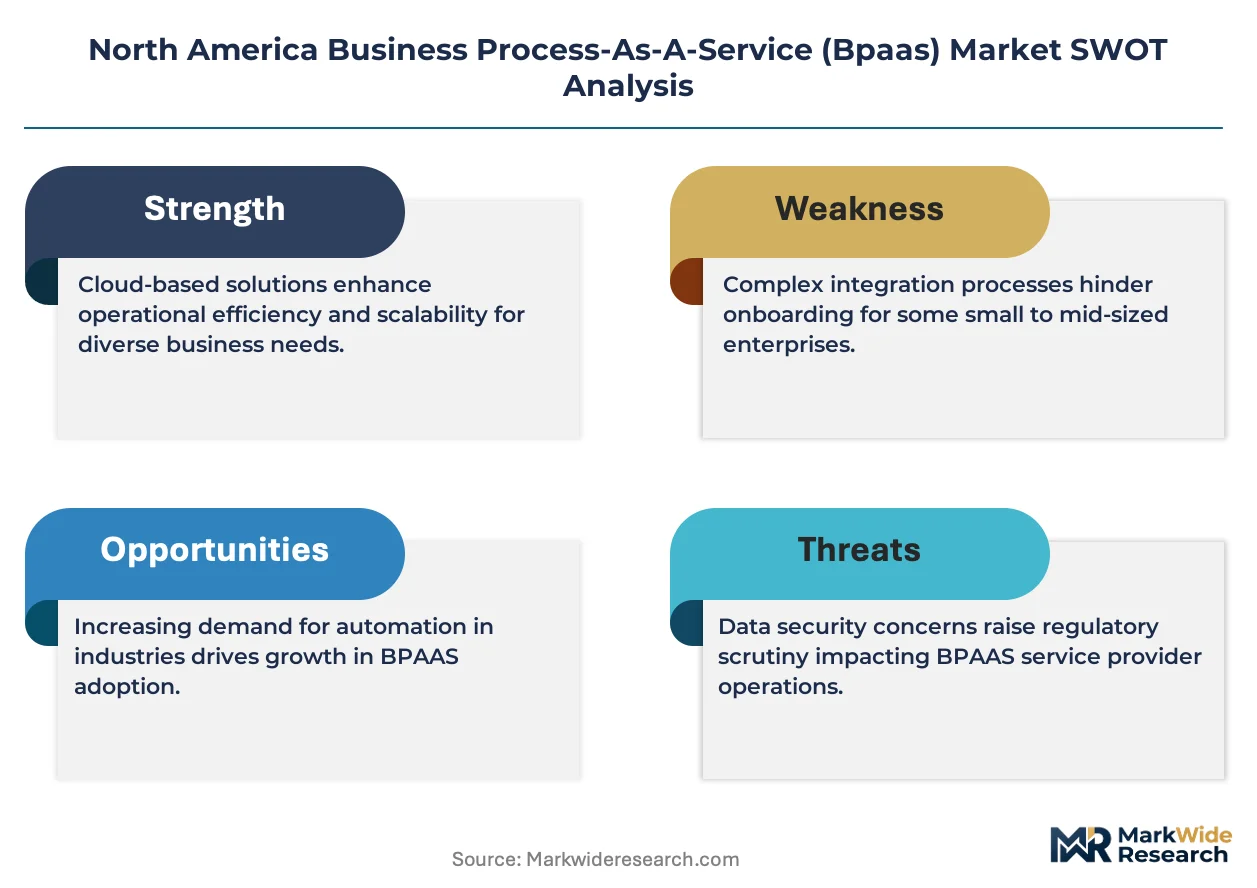
Enterprise-grade service tiering is rotating toward higher-assurance BPaaS contracts as buyers demand SOC 2 Type II and ISO 27001-aligned process outsourcing. Accenture leverages its multi-industry delivery footprint to capture complex finance and accounting mandates. IBM Corporation sustains technology leadership through AI-embedded workflow automation platforms. Cognizant Technology Solutions specializes in healthcare payer BPaaS, anchoring its North American position through vertical depth.
Business Process-As-A-Service denotes the third-party delivery of standardized business functions—finance, human resources, customer operations—via cloud-native platforms with defined SLAs, API orchestration, and multi-tenant architecture. Its primary purpose is to convert fixed process costs into variable, outcome-measured expenditures while embedding compliance and analytics. The service type dimension shows finance and accounting commanding the largest contract values, though customer support segments are expanding fastest as AI-augmented resolution layers reduce per-interaction costs. Deployment model insights reveal hybrid cloud architectures capturing disproportionate growth as regulated industries balance data sovereignty with elasticity needs.
The US SEC, HIPAA, and Canada's PIPEDA framework collectively shape BPaaS demand by mandating audit trails, data residency controls, and breach notification protocols that favor specialized providers over generic cloud platforms. US state-level privacy laws in California and Virginia add compliance fragmentation that drives buyers toward managed governance wrappers. Stakeholders must monitor how generative AI integration into core processes triggers fresh regulatory scrutiny around algorithmic accountability and vendor liability.
Market Dynamics
US SEC cybersecurity disclosure mandates are compressing procurement cycles as public companies race to embed compliant, auditable process workflows before enforcement deadlines crystallize.
Growth Catalysts
- HIPAA-aligned automation:Healthcare payers across the US Northeast corridor are migrating claims processing to SOC 2 Type II-certified platforms to satisfy federal audit requirements.
- Canada's PIPEDA data residency controls:Provincial health authorities in Ontario and British Columbia now mandate domestic cloud infrastructure for patient financial records.
- Generative AI resolution layers:Customer support segments are absorbing large language model tooling to compress per-interaction costs below human-only benchmarks.
Market Restraints
- Specialized talent scarcity:Cloud-native workflow architects command premium compensation in Boston and New York financial centers, inflating implementation costs.
- Hybrid cloud complexity:Regulated industries face integration friction between on-premise legacy systems and elastic public infrastructure.
- State-level privacy fragmentation:California's CCPA and Virginia's CDPA create conflicting data handling protocols that increase compliance overhead.
Strategic Opportunities
- Mid-market penetration:US healthcare providers below $500M revenue remain underserved by current enterprise-focused BPaaS tiers.
- API orchestration convergence:Workflow automation platforms are absorbing embedded analytics to create closed-loop process intelligence.
- Federal procurement reform:The US General Services Administration's cloud-first mandates accelerate civilian agency adoption of standardized finance and accounting workflows.
Industry Challenges
- Algorithmic accountability gaps:Generative AI integration into credit decisions and claims adjudication triggers unresolved liability questions under existing consumer protection frameworks.
- Multi-tenant isolation certification:ISO 27001 auditors are extending review timelines for providers serving both healthcare and financial services clients simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Business Process-As-A-Service (Bpaas) Market |
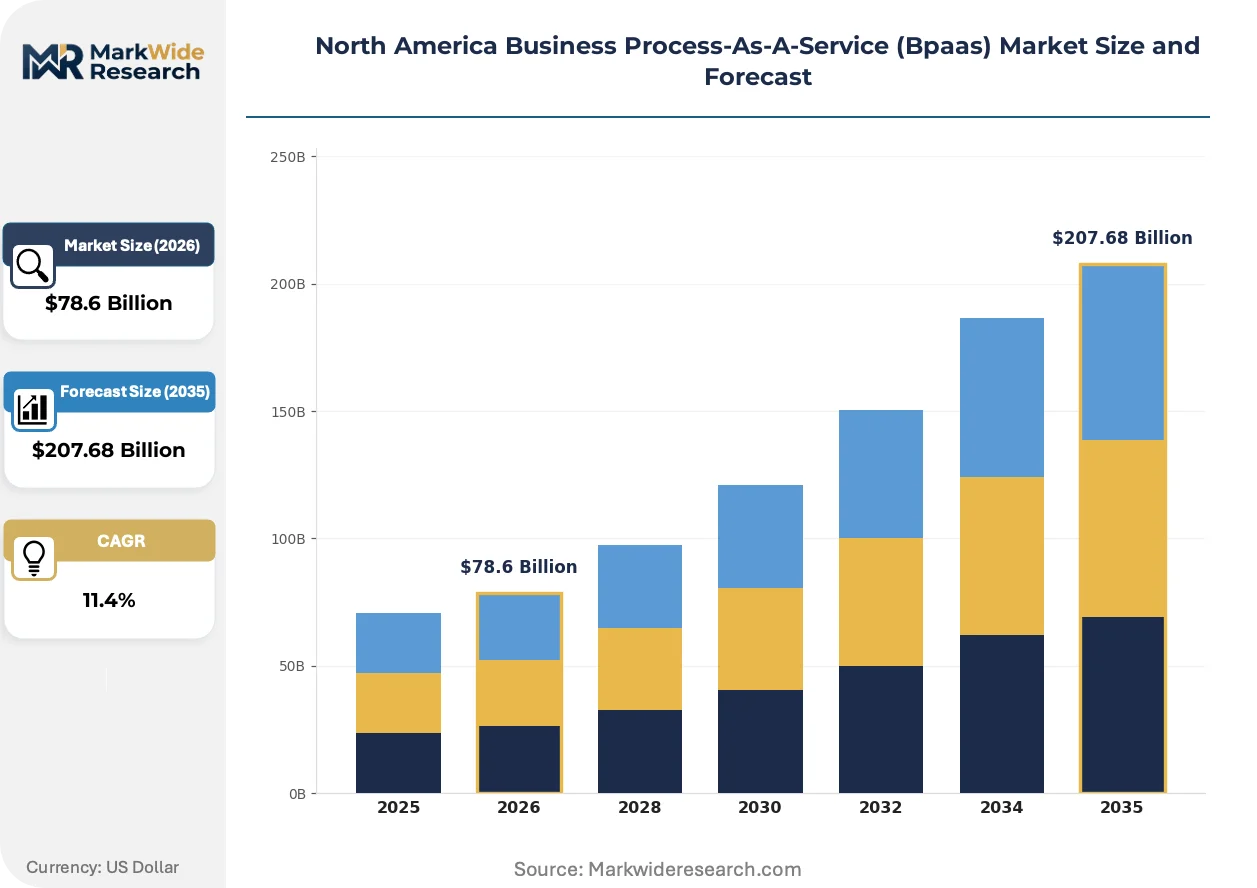
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $207.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Finance & Accounting, HR Management, Customer Support, Procurement Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Government Entities, Non-Profit Organizations Industry Vertical: Retail, Healthcare, Manufacturing, Telecommunications |
| Companies Covered | Accenture, IBM Corporation, Cognizant Technology Solutions, Tata Consultancy Services, Wipro Limited, Capgemini SE, Infosys Limited, HCL Technologies Ltd., NTT Data Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Business Process-As-A-Service (Bpaas) Market Trends and Innovations
Intelligent automation is compressing the boundary between transactional processing and predictive decision support across North American finance and healthcare operations.
Agentic AI workflow orchestration is supplanting rules-based robotic process automation in high-volume accounts payable operations. US Northeast financial services firms are piloting autonomous exception-handling systems that reduce manual intervention rates. This capability is compressing the cost structure of mid-tier providers who lack capital to deploy equivalent tooling.
HIPAA's Security Rule enforcement priorities are hardening data encryption standards for cloud-based patient financial management. The Office for Civil Rights has signaled intensified audit activity around business associate agreements. US hospital systems are responding by consolidating vendor relationships toward integrated platforms with pre-certified compliance architectures.
Subscription-to-outcome contract structures are displacing seat-based pricing in customer support BPaaS engagements. Enterprise buyers in Canadian banking and US insurance verticals now demand resolution-rate guarantees tied to variable fee schedules. This pattern concentrates most visibly among Fortune 500 companies with established vendor management offices in Toronto and Chicago.
North America Business Process-As-A-Service (Bpaas) Market Segmentation
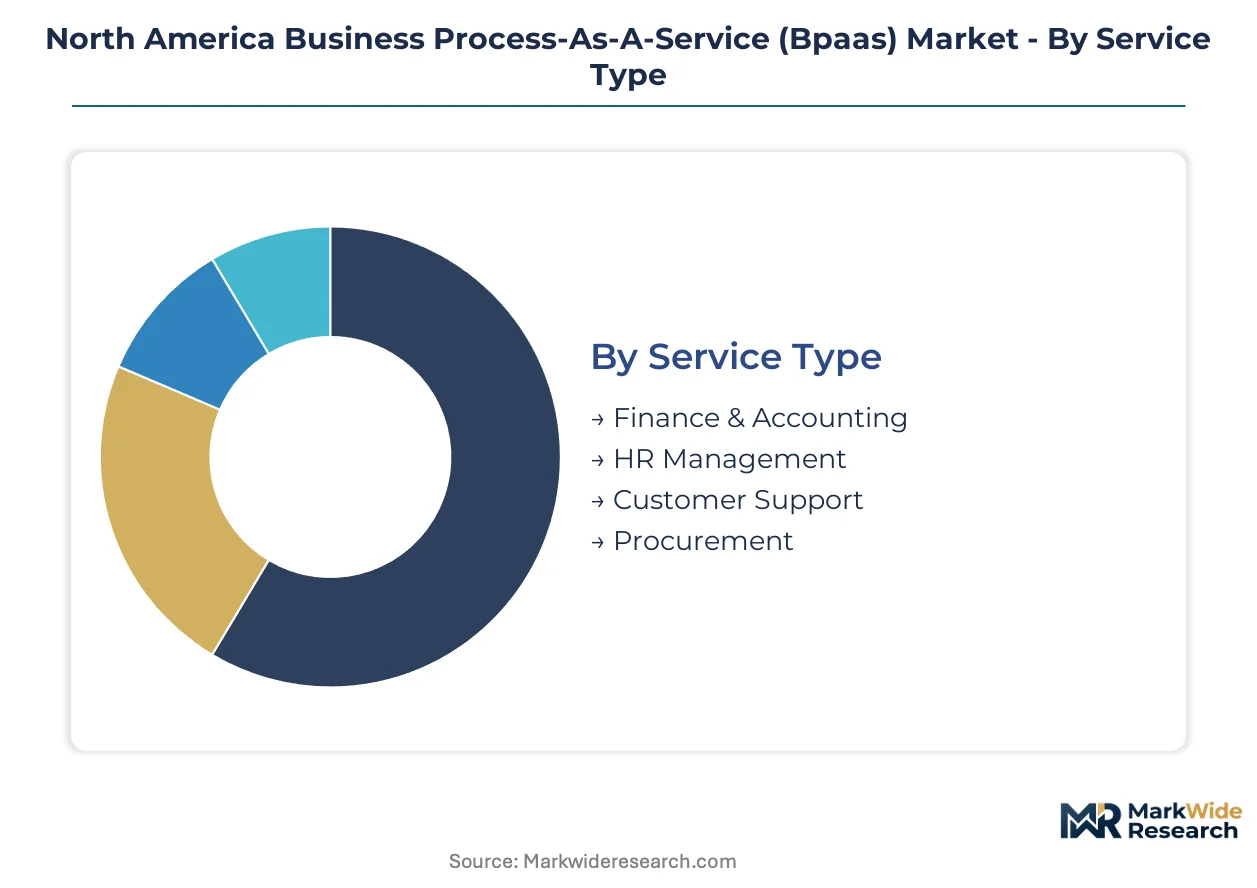
BPaaS procurement patterns diverge sharply across service types and deployment models, with compliance requirements and data sovereignty concerns dictating channel selection. Understanding these segment boundaries reveals where vendor specialization creates pricing power versus where standardization drives margin compression.
Service Type:
Channel mix varies by workflow complexity, with finance and accounting flowing through direct enterprise sales while customer support segments increasingly route through API-first platform marketplaces.
- Finance & Accounting:Encompasses accounts payable/receivable automation, general ledger management, and regulatory reporting workflows delivered through multi-tenant cloud platforms. Demand concentrates among US Northeast financial services firms seeking SOC 2 Type II-certified processing for SEC disclosure compliance.
- HR Management:Covers payroll processing, benefits administration, and talent acquisition workflows with embedded compliance engines. Canadian provincial health authorities and US hospital systems drive procurement for HIPAA-aligned personnel record management.
- Customer Support:AI-augmented resolution layers and omnichannel ticketing systems delivered via subscription-to-outcome contracts. US insurance verticals in Chicago and Toronto banking clusters prioritize resolution-rate guarantees over seat-based pricing.
- Procurement:Source-to-pay automation and supplier risk management workflows. Federal civilian agencies under GSA cloud-first mandates represent emerging demand concentration.
By volume, Finance & Accounting leads. By growth pace, Customer Support is climbing the fastest.
Deployment Model:
Cost tier stratification separates premium hybrid deployments from economy-grade public cloud offerings, with compliance certification grade determining pricing bands.
- Public Cloud:Multi-tenant infrastructure with shared security boundaries and elastic compute scaling. Mid-market US healthcare providers below $500M revenue default here for cost containment.
- Private Cloud:Dedicated single-tenant environments with custom encryption key management. Ontario and British Columbia health authorities mandate this tier for PIPEDA data residency compliance.
- Hybrid Cloud:Orchestrated workloads spanning on-premise legacy systems and elastic public infrastructure. Regulated industries across the US Northeast corridor absorb integration friction for sovereignty-elasticity balance.
- On-Premises:Legacy-hosted workflows with managed service overlays. Government entities with classified processing requirements maintain this tier despite cloud migration pressure.
By contract value concentration, Hybrid Cloud dominates. By expansion trajectory, Public Cloud is gaining share fastest among cost-constrained mid-market buyers.
End User:
Customer maturity and procurement sophistication create distinct engagement models, from self-service API onboarding for SMEs to bespoke statement-of-work negotiations with large enterprises.
- SMEs:Organizations with streamlined vendor management functions seeking standardized, quick-deploy workflow automation. US healthcare providers below $500M revenue remain underserved by current enterprise-focused tiering.
- Large Enterprises:Fortune 500 companies with established vendor management offices in Toronto and Chicago demanding outcome-based contracts with resolution-rate guarantees.
- Government Entities:Federal, state, and provincial agencies with mandated procurement compliance and audit trail requirements. US GSA cloud-first mandates accelerate civilian agency adoption.
- Non-Profit Organizations:Mission-constrained entities prioritizing cost predictability over advanced analytics capabilities.
By revenue contribution, Large Enterprises anchor the market. By untapped penetration potential, SMEs show the steepest expansion trajectory.
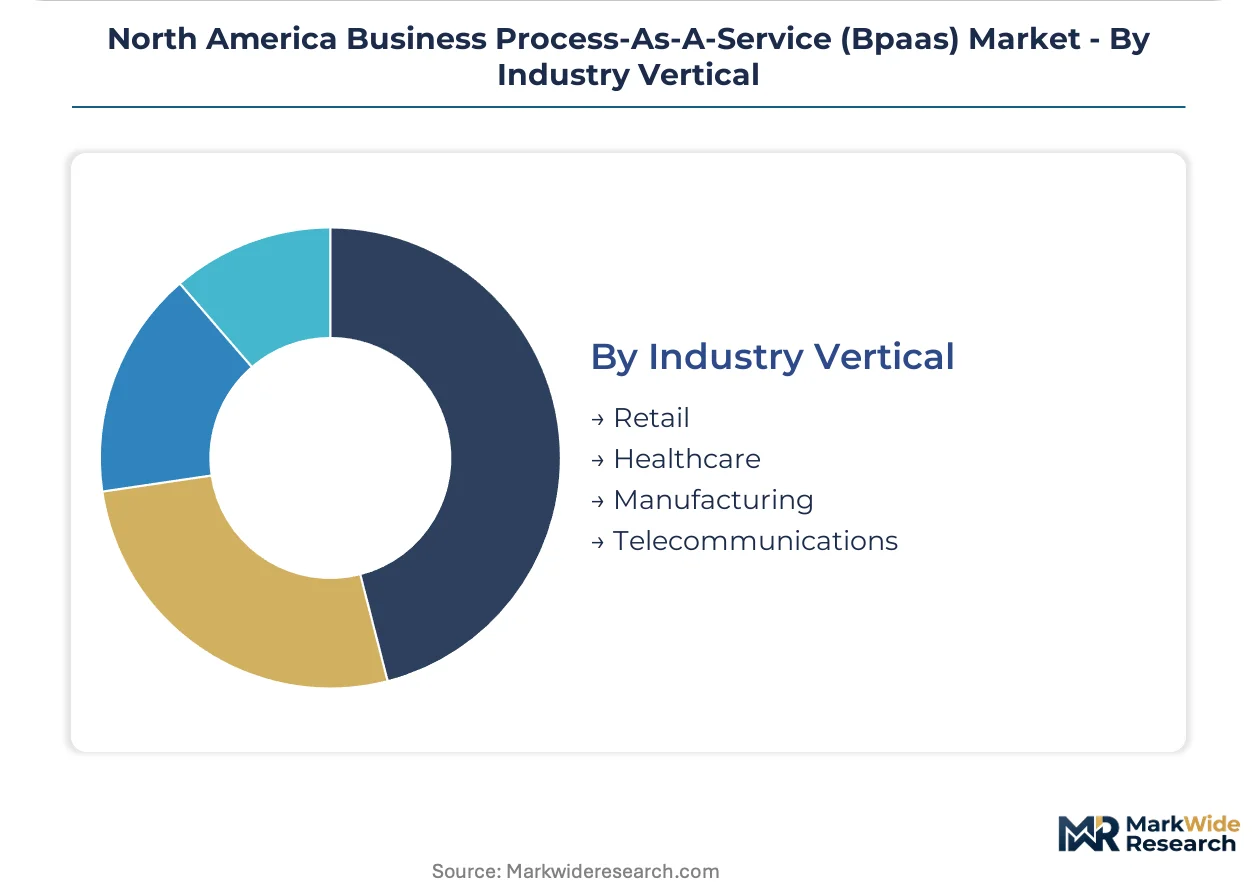
Industry Vertical:
Application-specific compliance burdens and workflow complexity create vertical specialization incentives, with healthcare and financial services demanding certified architectures unavailable to generic providers.
- Retail:Seasonal demand volatility and omnichannel order management drive need for elastic customer support scaling. US Northeast corridor retailers pilot agentic AI exception handling.
- Healthcare:HIPAA Security Rule enforcement and business associate agreement consolidation push hospital systems toward integrated, pre-certified platforms. OCR audit activity intensifies around patient financial management.
- Manufacturing:Supply chain finance and procurement automation with supplier risk analytics. Chicago-based industrial clusters seek closed-loop process intelligence.
- Telecommunications:High-volume customer support with generative AI resolution layers compressing per-interaction costs below human-only benchmarks.
By contract sophistication, Healthcare sets the standard. By AI adoption velocity, Telecommunications is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market buyers in the US Southeast demonstrate acute price sensitivity, while Fortune 500 buyers in the Northeast corridor absorb premium pricing for compliance-grade service tiers. Canadian provincial authorities impose strict data residency mandates that eliminate low-cost offshore alternatives. Mexican manufacturing clusters are emerging as cost-sensitive adopters of standardized finance automation.
United States
Healthcare payers and SEC-registered public companies dominate contract volumes. The SEC's cybersecurity disclosure rules compress procurement cycles as firms race toward compliance deadlines. Boston-to-New York financial centers concentrate demand for SOC 2 Type II-certified finance and accounting workflows.
Canada
Provincial health authorities in Ontario and British Columbia mandate domestic cloud infrastructure for patient financial records. PIPEDA data residency controls eliminate offshore processing options for sensitive healthcare data. Toronto's banking cluster drives outcome-based contract structures with resolution-rate guarantees.
Mexico
Manufacturing exporters in Nuevo León and the Bajío Region adopt standardized accounts payable automation to align with US customer compliance requirements. Nearshoring incentives from Mexico's federal economic development programs accelerate cloud migration among mid-tier suppliers. Mexico City anchors professional services demand for bilingual customer support operations.
North America Business Process-As-A-Service (Bpaas) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. Large multinational consultancies anchor the premium segment through integrated compliance and AI capabilities. Mid-tier specialists compete on vertical depth and regional proximity. Dominant competitive moves include strategic partnerships for technology access and portfolio diversification into adjacent automation services.
Among diversified technology conglomerates, IBM Corporation and Accenture occupy positions at the technology leadership frontier, while Cognizant Technology Solutions exemplifies vertical specialists anchoring healthcare payer segments. These three represent contrasting archetypes: platform-integrated capability stacks, multi-industry delivery footprints, and deep single-vertical expertise respectively.
| Leading Market Players |
|---|
| Accenture |
| IBM Corporation |
| Cognizant Technology Solutions |
| Tata Consultancy Services |
| Wipro Limited |
| Capgemini SE |
| Infosys Limited |
| HCL Technologies Ltd. |
| NTT Data Corporation |
| Others |
Pricing and Supply Chain Analysis
Multi-tenant cloud infrastructure scale economies in the US Northeast corridor compress unit delivery costs for SOC 2 Type II-certified platforms while simultaneously elevating price floors for hybrid deployments that must reconcile on-premise legacy systems with elastic public capacity. This dynamic concentrates pricing power among providers serving Fortune 500 financial services firms in Boston and New York, while mid-market healthcare providers below $500M revenue face persistent cost-to-serve disadvantages.
Pricing Analysis
SEC cybersecurity disclosure mandates dictate the pricing tier structure across North American BPaaS procurement, with compliance-grade service tiers commanding substantial premiums over baseline cloud offerings. Pricing stratifies across premium hybrid architectures, standard multi-tenant public cloud, and economy-grade shared infrastructure tiers. Cost compression in the mid-market segment is intensifying because generic platform providers lack certification depth to compete for regulated workloads. Fortune 500 buyers in Toronto and Chicago absorb premium pricing for resolution-rate guarantees, while US Southeast mid-market buyers demonstrate acute price sensitivity.
Supply Chain Analysis
Talent pipeline chokepoints in Boston and New York financial centers constrain cloud-native workflow architect availability, inflating implementation timelines for complex finance and accounting migrations. Service delivery draws from concentrated talent pools in the United States, Canada, and India, with Canadian operations tethered to PIPEDA-mandated domestic infrastructure investments. Single-source vulnerability persists for specialized HIPAA compliance auditors extending ISO 27001 review timelines. Distribution runs through direct enterprise sales for finance and accounting workflows, while customer support segments increasingly route through API-first platform marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native workflow architecture expertise functions as the binding constraint across North American BPaaS expansion, with certified talent scarcity limiting provider capacity to absorb surging demand from SEC-registered public companies facing compressed compliance deadlines.
For Market Incumbents: Fortify multi-tenant isolation certification depth to extend ISO 27001 audit efficiency advantages over competitors serving concurrent healthcare and financial services clients. Invest in captive supply of cloud-native workflow architects through targeted acquisition of boutique automation consultancies in Boston and New York. This counters margin erosion from generative AI tooling commoditization in transactional processing segments. For New Entrants and Emerging Players: Mid-market healthcare providers below $500M revenue represent the most penetrable white-space segment, as current enterprise-focused tiering leaves this cohort underserved by compliance-grade offerings. API-first platform marketplaces for customer support segments offer lower-friction go-to-market pathways than direct enterprise sales channels dominated by established consultancies. Target Ontario and British Columbia provincial health authorities with PIPEDA-aligned private cloud infrastructure as an entry wedge into regulated healthcare verticals. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical specialists with pre-certified healthcare payer platforms and established business associate agreement frameworks. Long-term viability across the analysis window favors providers with demonstrated HIPAA Security Rule audit survival and integrated compliance architectures over generic cloud platform resellers. Monitor Office for Civil Rights enforcement priority shifts around patient financial management as the critical inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates vendor relationships for US hospital systems responding to OCR audit intensification. |
| Geographic Expansion | Captures mid-market healthcare providers in the US Southeast corridor through cost-contained public cloud tiers. |
| Strategic Partnership | Accelerates AI-embedded workflow access for providers lacking capital to deploy autonomous exception-handling systems. |
| Acquisition of Specialist Firm | Addresses cloud-native architect scarcity in Boston and New York financial centers through talent consolidation. |
| Product Launch | Introduces subscription-to-outcome contract structures displacing seat-based pricing in Chicago insurance verticals. |
Research Methodology
Operator-level perspectives from BPaaS procurement officers at Fortune 500 financial services firms, HIPAA compliance leads at US hospital systems, cloud infrastructure architects at major consultancies, and vendor management office directors in Toronto and Chicago anchored the qualitative base. These primary insights combined with secondary validation from SEC cybersecurity disclosure filings, CMS Medicare administrative data, GSA procurement databases, and provincial health authority cloud migration records. Bottom-up contract value aggregation and top-down market sizing triangulation ensured cross-verification.
Sensitivity analysis across deployment model adoption curves, generative AI integration rates, and regulatory enforcement intensity variations shaped the analytical framework. Segmentation dimensions modeled encompass service type, deployment architecture, organization size tier, vertical industry, and regional regulatory cluster. CAGRs were derived through trend extrapolation anchored to disclosed contract values and validated against macroeconomic drivers. Industry-specific forecast inputs included HIPAA audit frequency projections and GSA cloud-first mandate implementation pacing.
Forecasts assume regulatory continuity in SEC cybersecurity disclosure regimes, HIPAA Security Rule enforcement priorities, and PIPEDA data residency controls; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as algorithmic accountability frameworks and state-level privacy fragmentation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
Technical Support Outsourcing Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Digitalization in Bpo Market