
 Plastic-Eating Bacteria Market | 2026-2036
Plastic-Eating Bacteria Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic-Eating Bacteria Market Analytics
Buyer concentration is realigning as multinational waste management firms consolidate procurement contracts while municipal buyers fragment across regional pilot programs. Carbios leverages enzymatic PET depolymerization to anchor technology leadership in polyester-specific biodegradation. Novozymes competes through fermentation-scale enzyme production that sustains cost advantages in industrial bioplastic processing.
Plastic-eating bacteria comprise engineered or naturally occurring microbial strains—primarily Ideonella sakaiensis and modified Pseudomonas species—that secrete PETase and MHETase enzymes to hydrolyze polyethylene terephthalate and polyurethane polymers at 30–40°C operating temperatures, converting waste plastics into terephthalic acid and ethylene glycol for repolymerization. Enzyme-based systems lead commercial deployment due to faster reaction kinetics and simpler downstream processing compared to whole-cell fermentation. Genetic engineering approaches attract R&D investment as CRISPR-modified strains expand substrate range beyond PET to polypropylene and mixed-plastic streams.
The EPA regulates genetically modified organisms under TSCA while the EU Green Deal mandates extended producer responsibility frameworks that directly create procurement budgets for bacterial remediation systems. ISO 14855 biodegradation testing standards govern product certification and market access for commercial microbial formulations. Stakeholders must monitor regulatory divergence between jurisdictions on GMO release protocols and synthetic biology oversight to anticipate compliance costs and commercialization timelines.
Market Dynamics
The plastic-eating bacteria sector is restructuring around enzymatic PET depolymerization as waste management firms replace mechanical recycling with microbial hydrolysis systems that operate at lower temperatures and energy inputs than thermal alternatives.
Growth Catalysts
- EU Green Deal extended producer responsibility:Municipal procurement budgets across Germany, France, and the Netherlands now explicitly fund engineered bacterial strain deployment for industrial composting infrastructure.
- Enzymatic reaction kinetics:PETase and MHETase secretion at 30–40°C enables faster polymer breakdown than whole-cell fermentation, accelerating commercial adoption by industrial bioplastic processors.
- Genetic engineering R&D pipelines:CRISPR-modified strains are expanding substrate compatibility beyond polyethylene terephthalate into polypropylene and mixed-plastic waste streams.
Market Restraints
- Fermentation-scale enzyme production costs:Industrial-grade enzyme purification requires specialized bioreactor infrastructure that constrains margin expansion for mid-scale processors.
- GMO release protocol divergence:The EPA regulates genetically modified organisms under TSCA with containment requirements that clash with EU open-field testing permissions, fragmenting deployment timelines.
- Mechanical recycling substitution:Established PET mechanical reprocessing retains cost advantages for clean, single-stream feedstocks in established collection zones.
Strategic Opportunities
- Polyurethane waste streams:Modified Pseudomonas species capable of degrading PU foams from furniture and automotive sectors represent an untapped substrate category.
- ISO 14855 certification arbitrage:Early movers securing biodegradation testing credentials gain preferential access to municipal tender processes in jurisdictions mandating certified microbial formulations.
- Synthetic biology oversight harmonization:Anticipated OECD guidance convergence on contained-use GMO standards would streamline multi-jurisdictional product registration for strain developers.
Industry Challenges
- Downstream processing integration:Terephthalic acid and ethylene glycol recovery from hydrolyzed PET requires capital-intensive separation equipment that legacy recycling facilities lack.
- CRISPR IP licensing complexity:Patent thickets around guide RNA designs and base-editing architectures create royalty stacking risks for engineered strain commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic-Eating Bacteria Market |
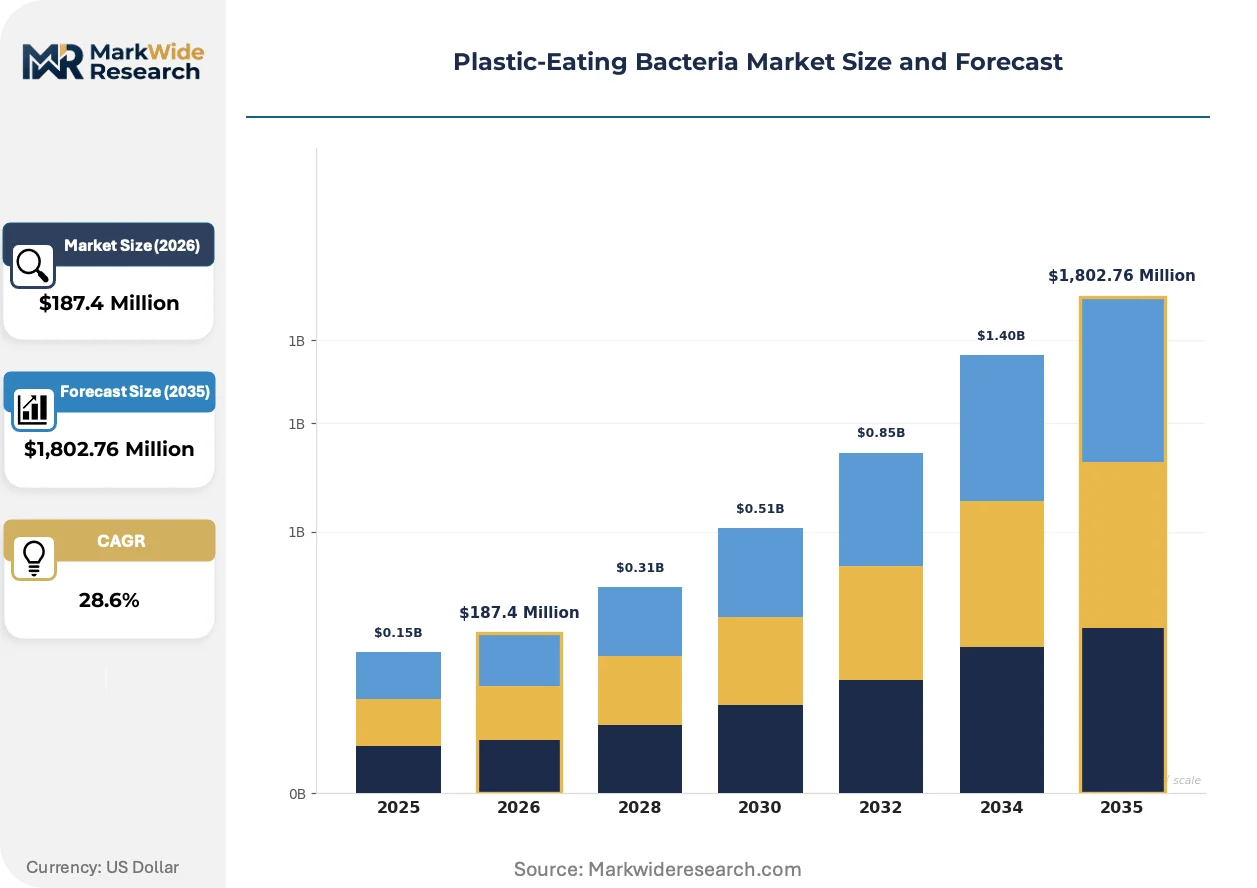
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioplastic, Enzyme-Based, Microbial Strain, Biofilm Application: Waste Management, Environmental Remediation, Wastewater Treatment, Biodegradation Technology: Genetic Engineering, Synthetic Biology, Natural Selection, Fermentation End User: Municipalities, Waste Management Companies, Research Institutions, Environmental NGOs |
| Companies Covered | Carbios, Pyrowave, EREMA, Sidel Group, Novozymes, Danimer Scientific, BioLogiQ, Tianjin GreenBio Materials, Full Cycle Bioplastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic-Eating Bacteria Market Evolving Landscape
Microbial biodegradation is absorbing capital and talent from adjacent biotech sectors as enzyme engineering platforms mature and regulatory frameworks stabilize across major jurisdictions.
Directed evolution of PETase variants is absorbing research investment from pharmaceutical biotech as protein engineering toolkits migrate to industrial enzyme applications. Waste management firms in the Netherlands and Japan are piloting these enhanced strains at demonstration scale. The technology is absorbing technical risk that previously blocked whole-cell system deployment.
REACH authorization requirements for polymer additives are forcing brand owners to validate biodegradation pathways for packaging materials placed on the European market. Industrial composting operators must now document microbial degradation kinetics to maintain facility permits. German municipalities are responding by specifying engineered bacterial strain inclusion in organic waste processing contracts.
Buyer concentration among consolidated waste management multinationals is compressing supplier negotiation leverage for microbial formulation providers. Regional pilot programs operated by fragmented municipal buyers are proliferating alternative procurement channels. France exhibits the most pronounced bifurcation, with Suez and Veolia dominating volume contracts while smaller cities tender experimental biodegradation services.
Plastic-Eating Bacteria Market Segmentation
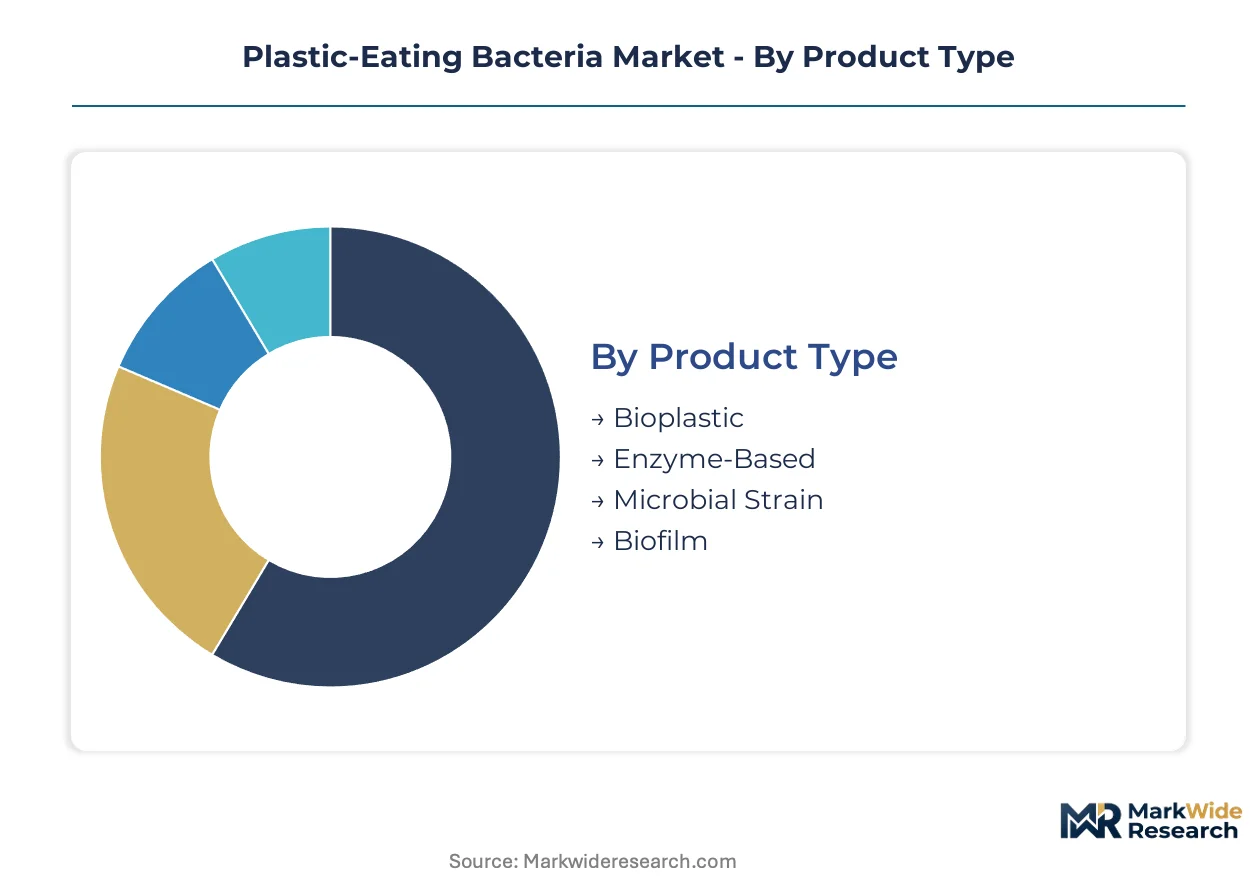
Segmentation in the plastic-eating bacteria market reflects divergent commercial readiness across biological platforms. Product architecture determines capital intensity, regulatory pathway, and integration complexity for waste management infrastructure.
Product Type:
Volume deployment concentrates in lower-cost biological inputs, while premium pricing attaches to engineered enzymatic systems with validated degradation kinetics.
- Enzyme-Based:Purified PETase and MHETase formulations enable direct hydrolysis of polyethylene terephthalate at 30–40°C without whole-cell bioreactor infrastructure. Demand clusters with German and Dutch industrial composting operators seeking drop-in replacements for thermal depolymerization under EU Green Deal procurement mandates.
- Microbial Strain:Engineered Ideonella sakaiensis and modified Pseudomonas species secrete depolymerizing enzymes through fermentation-based cultivation. Japanese demonstration facilities and French municipal pilots are scaling contained-use deployments ahead of broader GMO release authorizations.
- Bioplastic:Bacterial polyhydroxyalkanoate production from waste feedstocks integrates upstream degradation with material synthesis.
- Biofilm:Immobilized consortia on carrier matrices enable continuous-flow reactor configurations with reduced downstream separation burden.
Mature deployment sits with Enzyme-Based systems. Newer deployment is concentrated in Microbial Strain applications as genetic engineering pipelines advance.
Application:
Commercial traction splits between established waste handling operations and emerging environmental liability management use cases.
- Waste Management:Industrial-scale PET depolymerization at mechanical recycling facilities converts contaminated feedstocks into terephthalic acid and ethylene glycol for repolymerization. Suez and Veolia in France have integrated enzymatic systems into existing sorting infrastructure to capture volumes excluded from mechanical reprocessing.
- Environmental Remediation:In-situ soil and marine degradation targets legacy plastic accumulation in unmanaged environments. Netherlands-funded research consortia are piloting contained bioaugmentation for harbor sediment cleanup ahead of regulatory framework development.
- Wastewater Treatment:Microplastic capture and degradation within activated sludge systems addresses synthetic fiber fragmentation from textile processing.
- Biodegradation:Certification-driven validation services support ISO 14855 compliance for packaging material claims.
Revenue concentration favors Waste Management. Steepest expansion trajectory belongs to Environmental Remediation as liability frameworks mature.
Technology:
Intellectual property positioning and capital requirements stratify across biological innovation approaches.
- Genetic Engineering:CRISPR-modified strains expand substrate range beyond PET into polypropylene and mixed-plastic streams. Carbios anchors technology leadership through patent-protected PETase variants, while Novozymes leverages fermentation-scale production infrastructure for cost-positioned enzyme supply.
- Fermentation:Bioreactor-based cultivation of engineered or natural strains enables controlled enzyme secretion with standardized downstream processing. Industrial bioplastic processors in Germany prefer this route for batch reproducibility under REACH authorization requirements.
- Synthetic Biology:De novo pathway construction and modular genetic circuits enable multi-enzyme cascade design for complex polymer degradation.
- Natural Selection:Directed evolution of environmental isolates without recombinant DNA techniques navigates simplified regulatory pathways in GMO-restrictive jurisdictions.
Commercial maturity centers on Fermentation. Capability investment flows toward Genetic Engineering as CRISPR IP licensing structures stabilize.
End User:
Procurement authority and technical sophistication create distinct buying center dynamics across institutional categories.
- Waste Management Companies:Consolidated multinationals negotiate volume contracts with standardized performance specifications. Buyer concentration in France, Germany, and the Netherlands compresses supplier margins while demanding documented biodegradation kinetics for facility permit maintenance.
- Municipalities:Fragmented regional pilot programs proliferate alternative procurement channels with heterogeneous technical requirements. Smaller French cities tender experimental biodegradation services outside Suez and Veolia volume frameworks.
- Research Institutions:Academic and national laboratory partnerships advance strain characterization and environmental risk assessment for regulatory submission packages.
- Environmental NGOs:Advocacy-driven project finance supports demonstration deployments with public visibility objectives.
Established procurement sits with Waste Management Companies. Emerging demand generation concentrates in Municipalities as extended producer responsibility frameworks activate local budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineered bacterial strain development clusters near established biotech corridors and municipal waste infrastructure in Western Europe, East Asia, and North America. Feedstock proximity to PET manufacturing residues and industrial composting sites dictates deployment sequencing.
Germany
Industrial composting operators in North Rhine-Westphalia and Bavaria procure enzymatic PET depolymerization systems under extended producer responsibility frameworks. The Federal Environment Agency enforces containment protocols for genetically modified organisms under the Genetic Engineering Act. Stuttgart's biotech corridor hosts fermentation-scale enzyme production facilities serving Dutch and French municipal contracts.
France
Suez and Veolia negotiate volume contracts for enzymatic hydrolysis integration into existing sorting infrastructure. The country's national environmental regulator validates biodegradation kinetics for facility permit maintenance under EU Green Deal implementation. Lyon and Marseille municipalities tender experimental biodegradation services outside consolidated multinational frameworks.
Netherlands
Harbor sediment cleanup pilots in Rotterdam apply contained bioaugmentation techniques ahead of regulatory framework development. The Human Environment and Transport Inspectorate oversees contained-use GMO standards aligned with anticipated OECD guidance convergence. Wageningen University research consortia advance strain characterization for multi-jurisdictional product registration.
Japan
Demonstration facilities in Osaka and Nagoya scale contained-use deployments of engineered Ideonella sakaiensis strains. The Ministry of Economy, Trade and Industry funds directed evolution research migrating pharmaceutical protein engineering toolkits to industrial enzyme applications. Tokyo Bay marine plastic accumulation sites attract pilot funding for environmental remediation liability frameworks.
United States
Mechanical recycling facilities in Texas and California evaluate enzymatic systems for contaminated feedstock capture. The Environmental Protection Agency regulates genetically modified organisms under the Toxic Substances Control Act with containment requirements that fragment deployment timelines compared to European permissions. Boston-area synthetic biology startups pursue CRISPR-modified strain development under stricter release protocols.
Plastic-Eating Bacteria Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue enzymatic specialization and synthetic biology toolkits. The market structure stratifies between consolidated multinational enzyme suppliers and fragmented strain developers. Three archetypes dominate: fermentation-scale enzyme producers, CRISPR-modified strain engineers, and integrated bioplastic manufacturers. Capacity expansion and technology licensing constitute the primary competitive moves as players navigate divergent GMO release protocols.
Within the enzymatic technology tier, Carbios and Novozymes represent distinct positioning approaches. Carbios anchors patent-protected PETase variant development. Novozymes exemplifies fermentation-scale production infrastructure leverage. Danimer Scientific occupies a position bridging engineered strain deployment with integrated bioplastic synthesis.
| Leading Market Players |
|---|
| Carbios |
| Pyrowave |
| EREMA |
| Sidel Group |
| Novozymes |
| Danimer Scientific |
| BioLogiQ |
| Tianjin GreenBio Materials |
| Full Cycle Bioplastics |
| Others |
Value Network & Pricing Analysis
Fermentation-grade glucose price indices cascade through bioreactor operating costs into three distinct pricing tiers for microbial formulation buyers. Industrial composting operators in Germany and the Netherlands absorb enzyme purification premiums under EU Green Deal procurement mandates while municipal pilot programs negotiate unbundled service rates.
Pricing Analysis
Warranty coverage for strain performance and biodegradation kinetics validation separates premium enzyme formulations from standard microbial strain supply. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 14855 certification status, fermentation scale, and after-sales technical support inclusion. Cost compression in standard-tier enzyme supply is intensifying because Novozymes and Carbios expand fermentation capacity in Stuttgart's biotech corridor. Municipal buyers in fragmented French pilot programs exhibit highest price sensitivity; consolidated waste management multinationals in Germany accept premium tiering for documented performance guarantees.
Supply Chain Analysis
ISO 14855 certification and EU contained-use GMO permits gate supplier qualification for municipal procurement channels. Manufacturing concentrates in Germany, the Netherlands, and Japan where bioreactor infrastructure clusters near industrial composting feedstock sources. Production draws from fermentation-grade glucose, specialized bioreactor vessels, and CRISPR guide RNA synthesis inputs. Single-source vulnerability sits with German fermentation equipment suppliers serving Dutch and French facility expansions. Distribution runs through waste management company procurement divisions and municipal tender platforms with heterogeneous technical specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic PET depolymerization is displacing mechanical recycling for contaminated feedstock streams, creating technology-transition investment windows across procurement and supply infrastructure.
For Market Incumbents: Deepen backward integration into fermentation-grade glucose supply to defend margin position against commodity input volatility. Expand CRISPR-modified strain R&D pipelines to preempt substrate-range competition from synthetic biology startups. Carbios and Novozymes should lock exclusive bioreactor capacity in Stuttgart before Dutch facility expansions absorb regional equipment lead times.
For New Entrants and Emerging Players: Fragmented French municipalities outside Suez and Veolia volume frameworks represent the most penetrable buyer archetype for experimental biodegradation service contracts. Polyurethane waste streams from automotive dismantlers in Japan offer white-space substrate specialization with simplified regulatory pathways. Pursue ISO 14855 certification arbitrage to bypass consolidated procurement gatekeeping in German industrial composting.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-scale enzyme producers with REACH authorization credentials in the Netherlands ahead of OECD guidance convergence on GMO standards. Long-term viability centers on multi-jurisdictional product registration capabilities across EPA TSCA and EU contained-use frameworks. Watch for CRISPR IP licensing structure stabilization as the inflection signal for engineered strain commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Development Partnership | Expands substrate compatibility beyond PET into polypropylene and mixed-plastic streams for Carbios. |
| Fermentation Capacity Expansion | Novozymes secures cost advantages in industrial bioplastic processing through Stuttgart bioreactor scale-up. |
| ISO 14855 Certification Investment | Unlocks preferential municipal tender access in France and Germany under EU Green Deal mandates. |
| Backward Integration into Glucose Supply | Reduces input cost volatility for enzyme purification operations in Dutch industrial composting facilities. |
| Contained-Use GMO Regulatory Harmonization | Anticipated OECD guidance convergence streamlines multi-jurisdictional product registration for strain developers. |
Research Methodology
Multi-period observation of enzymatic PET depolymerization deployment rates and municipal procurement budget allocations anchored the trend analysis, supplemented by interviews with fermentation plant managers, waste management procurement leads, EU regulatory affairs specialists, and industrial composting operators. Secondary validation drew from EPA TSCA filings, ECHA REACH authorization databases, EU Green Deal implementation reports, and ISO 14855 certification registries. Bottom-up strain deployment tracking across German, French, and Dutch facilities triangulated against top-down extended producer responsibility budget analysis.
Input-output matrices mapped fermentation-scale enzyme production capacity against municipal tender volumes and contaminated feedstock availability across the projection horizon. Segmentation dimensions modeled include product architecture, application category, biological innovation approach, and institutional buyer type. CAGRs were derived from logistic diffusion curves fitted to demonstration-scale deployment trajectories. Industry-specific forecast inputs incorporated CRISPR-modified strain pipeline advancement rates and GMO release protocol divergence timelines between EPA and EU frameworks.
Revisions become necessary when EPA TSCA containment requirements tighten, EU open-field testing permissions expand, or CRISPR IP licensing structures destabilize royalty stacking assumptions. A model refresh is warranted upon material change in OECD guidance convergence timelines for contained-use GMO standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
North America Biosolids Market
Environmental Biotechnology
Bioremediation Market
Environmental Biotechnology
Global Bio Decontamination Market
Environmental Biotechnology
Global Anaerobic Digestion Market
Environmental Biotechnology
Blue Biotechnology Market
Environmental Biotechnology
Europe Anaerobic Digestion Market
Environmental Biotechnology
Bio-Detection Market
Environmental Biotechnology
Enzymatic Cleaning Market