
 Global Biometric Technology Market | 2026-2036
Global Biometric Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biometric Technology Market Foresight
Government procurement channels is tilting toward multimodal biometric suites that combine facial and iris recognition for border checkpoints. NEC Corporation leverages its longstanding relationship with immigration authorities across Japan and multiple other countries to sustain large-scale deployment contracts. Thales competes through integrated digital identity platforms that extend beyond hardware into software analytics. IDEMIA anchors its position in civil identification programs where it controls enrollment and credential issuance infrastructure.
Biometric technology encompasses automated systems that measure and analyze unique physiological or behavioral characteristics—fingerprint minutiae, iris patterns, facial geometry, voiceprints, or vascular structures—for identity verification against stored templates, typically operating with false acceptance rates below 0.001% in high-security configurations. Its primary commercial purpose is to bind digital or physical access privileges to an irrefutable biological identity, eliminating credential sharing and reducing fraud in financial transactions, border crossings, and workforce management. Facial recognition occupies the fastest-expanding margin pool as cloud-based APIs and mobile integration lower deployment barriers for mid-sized enterprises. Fingerprint recognition remains the most mature segment with commoditized sensor costs, while voice recognition is gaining traction in call center fraud detection and telebanking authentication where remote verification is essential.
The EU AI Act classifies many biometric identification systems as high-risk, mandating conformity assessments and human oversight that reshape product development roadmaps for vendors serving European public sector clients. The FDA regulates certain biometric devices used in healthcare settings under 21 CFR Part 820 quality system requirements, while India's BIS certification and UIDAI standards govern Aadhaar-linked authentication hardware deployed across financial and welfare programs. Stakeholders must monitor the divergence between permissive national identity frameworks and restrictive privacy regimes to determine where R&D investment and localization of data processing architectures will yield sustainable market access.
Market Dynamics
EU AI Act high-risk classification of biometric identification systems is forcing vendors to rearchitect product roadmaps around human-in-the-loop oversight and conformity assessments, compressing margins for European public sector deployments.
Growth Catalysts
- GDPR Article 9 Exemptions:EU member states are carving out lawful grounds for biometric processing in national security and border contexts, opening procurement channels for multimodal authentication suites at major airports and seaports.
- Aadhaar-Linked Financial Inclusion:India's UIDAI mandates biometric authentication for welfare distribution and bank account opening, sustaining hardware refresh cycles across rural banking networks and micro-ATM deployments.
- Contactless Fingerprint Sensors:Optical-on-glass and ultrasonic technologies are eliminating hygiene friction in healthcare and food service access control, replacing legacy capacitive pads in high-throughput environments.
Market Restraints
- Silicon Supply Concentration:Advanced image signal processors and neural accelerators for edge biometric devices concentrate in Taiwan and South Korea foundries, exposing OEMs to geopolitical disruption and allocation constraints.
- Template Storage Liability:Centralized biometric databases create catastrophic breach exposure under GDPR and state-level privacy laws, chilling enterprise adoption for workforce management applications.
- Presentation Attack Vulnerability:Deepfake-synthesized facial imagery and high-fidelity fingerprint molds are outpacing liveness detection algorithms, eroding trust in unsupervised authentication scenarios.
Strategic Opportunities
- Edge AI Biometric Modules:On-device template matching and federated learning architectures are opening privacy-compliant deployment in German and French enterprise settings where data residency is non-negotiable.
- Behavioral Biometrics Convergence:Keystroke dynamics and gait analysis layered with physiological traits are creating continuous authentication protocols for zero-trust security frameworks in financial services.
- Digital Identity Wallets:EU Digital Identity Regulation is mandating interoperable biometric credentials, positioning vendors to capture recurring verification revenue beyond one-time hardware sales.
Industry Challenges
- Algorithmic Bias Certification:NIST FRTE and ISO/IEC 19795-1 testing for demographic performance parity is extending product validation timelines and requiring costly retraining on geographically diverse datasets.
- Interoperability Fragmentation:Proprietary template formats across IDEMIA, Thales, and NEC systems are forcing integrators to maintain multiple SDKs and translation layers, inflating deployment complexity for multi-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biometric Technology Market |
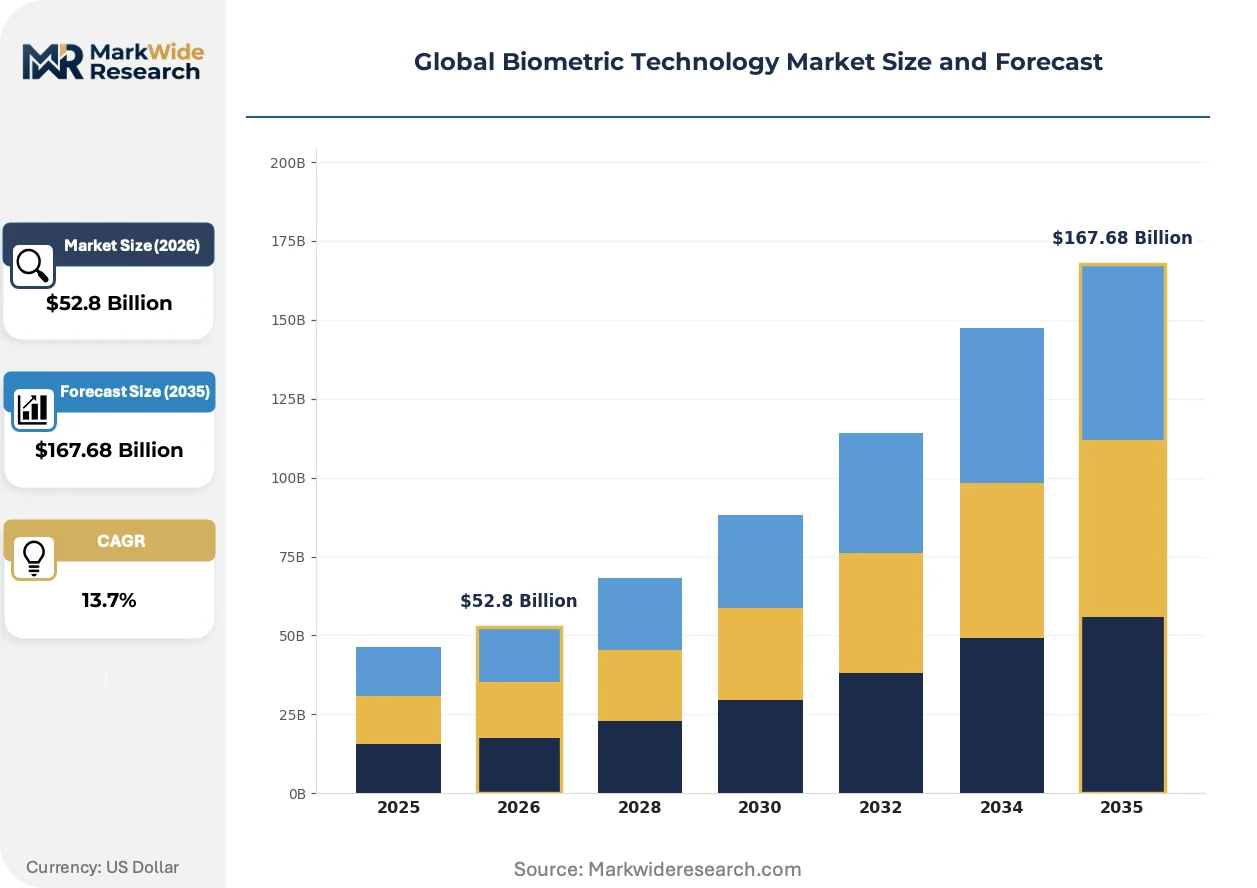
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $167.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biometric Type: Fingerprint Recognition, Iris Recognition, Facial Recognition, Voice Recognition, Vein Recognition, Signature Verification Application: Access Control, Border Security, Employee Attendance, Fraud Detection, Payment Authorization, Identity Management End User Industry: Government Agencies, Financial Institutions, Telecommunications, Education Institutes, Hospitality Sector, Public Safety Organizations Deployment Model: On-Premises, Cloud-Based, Hybrid Deployment, Mobile Integration, Edge Computing, SaaS Solutions |
| Companies Covered | NEC Corporation, Socure, Thales, Alcatraz AI, HYPR Corp, IDEMIA, Fujitsu, Paravision, ASSA ABLOY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biometric Technology Market Shifts & Advancements
Cloud-native biometric APIs and on-device neural processing are collapsing traditional hardware-software boundaries, enabling mid-sized enterprises to deploy enterprise-grade authentication without capital-intensive infrastructure.
Contactless fingerprint-on-display technology is collapsing the distinction between mobile device security and physical access control. Smartphone OEMs are licensing ultrasonic sensor stacks to building automation vendors, compressing the addressable market for standalone fingerprint terminals. The technology is collapsing legacy capacitive sensor margins while expanding biometric touchpoints into elevator panels and vehicle entry systems.
EU AI Act high-risk system classifications are reshaping vendor liability structures for biometric identification deployed in public spaces. Conformity assessment bodies in Germany and France are backlogged with certification requests, delaying product launches. European police forces and border agencies are accelerating procurement of human-in-the-loop architectures to preempt compliance failures.
Subscription-based biometric-as-a-service models are displacing perpetual license sales in mid-market workforce management. HR software platforms in the United States and United Kingdom are bundling facial recognition time clocks with cloud payroll systems, capturing recurring revenue from franchises and distributed retail chains. The shift concentrates buyer power with platform aggregators and commoditizes standalone hardware vendors.
Global Biometric Technology Market Segmentation
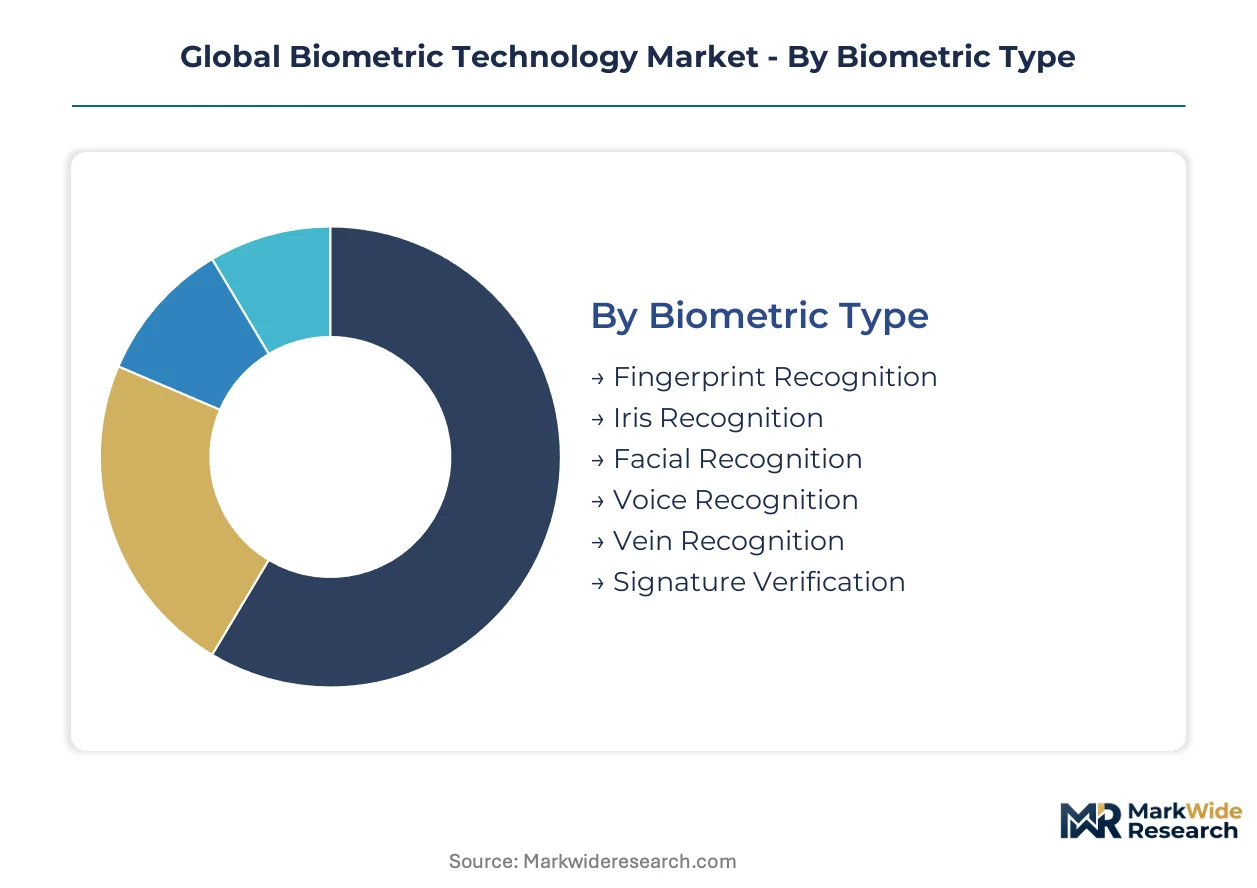
Biometric technology deployment varies sharply across authentication modalities, operational contexts, and infrastructure architectures. Vendors must align product roadmaps with specific compliance regimes and integration requirements that differ by segment.
Biometric Type:
Use cases span high-security border checkpoints requiring multimodal fusion to consumer mobile unlock with single-factor convenience.
- Facial Recognition:Cloud-based APIs and neural processing units in smartphones have collapsed deployment costs for mid-sized enterprises. Demand concentrates in United States retail banking and Chinese smart city surveillance where contactless verification reduces throughput friction.
- Fingerprint Recognition:Ultrasonic and optical-on-glass sensors now operate through display glass, eliminating dedicated hardware buttons. India's UIDAI-mandated Aadhaar authentication sustains massive sensor procurement across rural banking networks and micro-ATM infrastructure.
- Iris Recognition:NIST-tested algorithms achieve false acceptance rates below 0.0001% in border checkpoint configurations.
- Voice Recognition:Telebanking fraud detection and call center authentication drive adoption where remote verification is essential.
- Vein Recognition:Palm-vein patterns resist spoofing through presentation attacks in Japanese ATM networks.
- Signature Verification:Behavioral dynamics analysis persists in document-heavy European insurance workflows.
The dominant share belongs to fingerprint recognition, while facial recognition is closing the gap fastest.
Application:
Cost tiers separate capital-intensive government infrastructure from recurring-revenue SaaS models in commercial workforce management.
- Border Security:Multimodal suites combining facial and iris matching operate at throughput rates exceeding 60 travelers per minute in Dubai International Airport and Singapore Changi. EU AI Act high-risk classification mandates human-in-the-loop oversight, extending procurement cycles.
- Payment Authorization:EMVCo-certified fingerprint and facial templates enable card-not-present transaction verification. Mastercard and Visa biometric card pilots in South Africa and Brazil test embedded sensor form factors.
- Access Control:Enterprise campus deployments favor contactless fingerprint-on-display for hygiene-sensitive healthcare and food service environments.
- Employee Attendance:Cloud payroll bundling commoditizes standalone time-clock hardware in United States franchise networks.
- Fraud Detection:Behavioral biometrics layer keystroke dynamics atop physiological traits in zero-trust financial architectures.
- Identity Management:EU Digital Identity Regulation mandates interoperable biometric credentials for cross-border recognition.
Border security commands the highest per-unit pricing, yet payment authorization is expanding most quickly through mobile wallet integration.
End User Industry:
Customer procurement sophistication ranges from centralized government tenders to fragmented hospitality deployments.
- Government Agencies:National identity programs in India, Nigeria, and the Philippines drive enrollment and credential issuance infrastructure at scale. BIS certification and UIDAI standards govern Aadhaar-linked hardware specifications.
- Financial Institutions:PSD2 strong customer authentication mandates in European Union member states accelerate biometric card and mobile app deployment. RBI guidelines shape Indian bank authentication protocols.
- Telecommunications:SIM registration regulations across Pakistan, Bangladesh, and Ghana mandate biometric subscriber verification.
- Public Safety Organizations:Police forces in France and Germany backlog conformity assessments for EU AI Act compliance.
- Education Institutes:Campus access and examination proctoring applications grow in South Korean and Turkish universities.
- Hospitality Sector:Cruise lines and casino operators deploy facial recognition for passenger embarkation and VIP identification.
Government agencies anchor procurement volume, while financial institutions are gaining share fastest through regulatory mandate expansion.
Deployment Model:
Margin structures diverge between hardware-intensive edge installations and recurring SaaS revenue with minimal capital requirements.
- Cloud-Based:API-first architectures enable mid-market enterprises to deploy enterprise-grade facial recognition without infrastructure investment. AWS, Azure, and Google Cloud biometric services compete on inference latency and data residency guarantees.
- Edge Computing:On-device template matching satisfies GDPR data minimization requirements in German manufacturing and French healthcare settings where cloud transmission is prohibited.
- On-Premises:Air-gapped installations persist in defense and intelligence agency facilities with classified network requirements.
- Mobile Integration:Smartphone secure enclaves store FIDO2-compliant credentials for passwordless enterprise authentication.
- Hybrid Deployment:Template enrollment in cloud with matching at edge balances convenience and privacy in distributed retail chains.
- SaaS Solutions:Subscription-based workforce management bundles facial time clocks with payroll platforms in United Kingdom and Australian franchise networks.
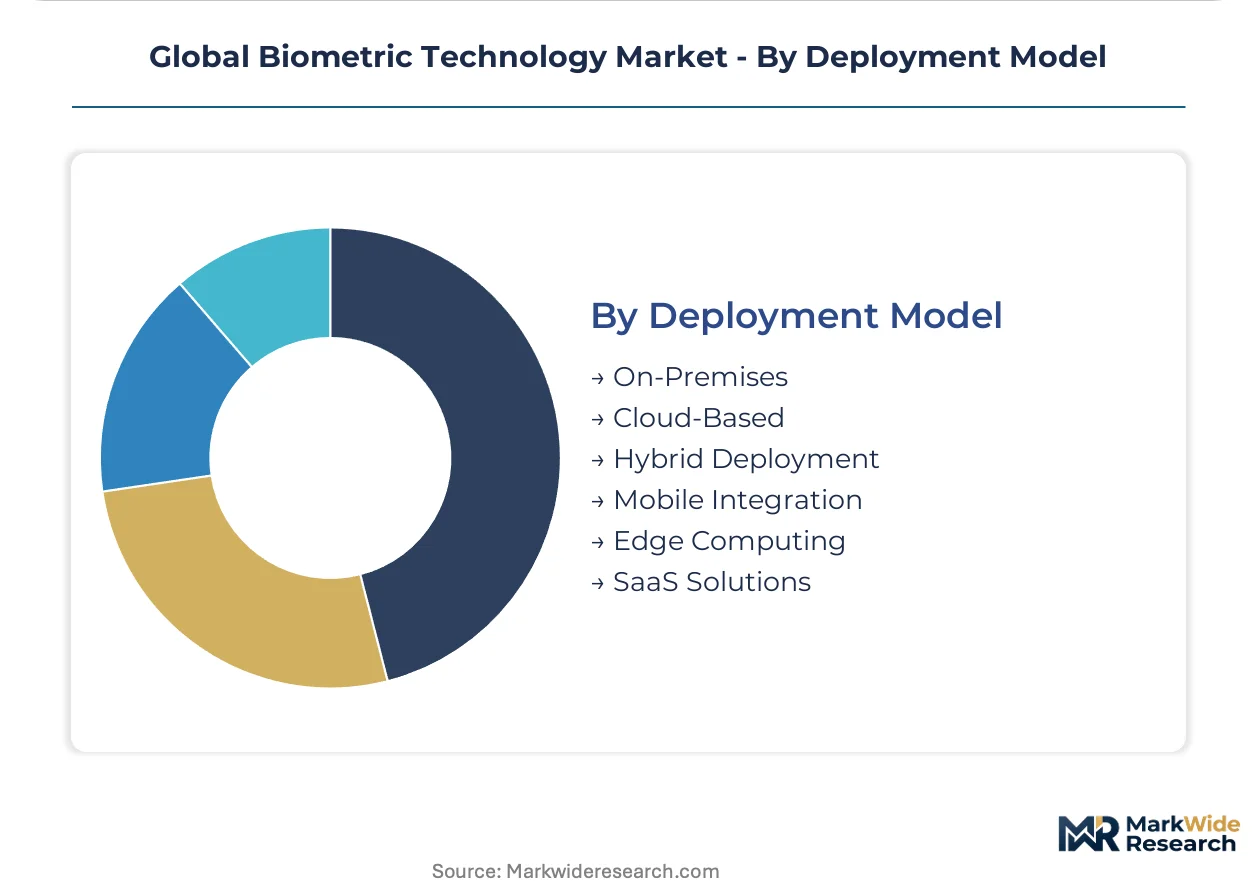
Cloud-based deployment holds the dominant share, though edge computing is climbing the fastest as privacy regulations harden data residency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Aadhaar biometric backbone underwrites India's dominance in national identity infrastructure, while the EU's Digital Identity Regulation and China's Smart City Initiative each anchor distinct procurement architectures across their respective territories.
United States
Financial institutions deploy facial recognition APIs for card-not-present authentication, with Mastercard and Visa piloting embedded biometric cards. The FDA regulates healthcare biometric devices under 21 CFR Part 820 quality system requirements. Silicon Valley cloud providers compete on inference latency for enterprise facial recognition services.
India
UIDAI-mandated Aadhaar authentication drives hardware refresh cycles across rural banking networks and micro-ATM infrastructure. BIS certification governs biometric device specifications for financial inclusion programs. Maharashtra and Karnataka host enrollment infrastructure vendors serving credential issuance at scale.
Germany
Manufacturing enterprises adopt edge AI biometric modules to satisfy GDPR data minimization requirements where cloud transmission is prohibited. KBA and federal conformity assessment bodies backlog EU AI Act certification requests for high-risk identification systems. Bavaria's automotive suppliers integrate contactless fingerprint sensors into workforce access control.
China
Smart city surveillance networks and mobile payment ecosystems drive facial recognition deployment at massive scale. MIIT standards and GB certification frameworks govern biometric hardware specifications. Shenzhen hardware clusters supply ultrasonic fingerprint sensors to global smartphone OEMs.
United Kingdom
Franchise retail networks bundle facial recognition time clocks with cloud payroll systems, capturing recurring SaaS revenue. FCA guidelines shape biometric authentication protocols for digital banking services. London fintech clusters pioneer behavioral biometrics convergence for zero-trust security frameworks.
Global Biometric Technology Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors and algorithms to downstream assemblers. The vendor base concentrates around three strategic archetypes: immigration-focused platform vendors, digital identity suite providers, and cloud-native API disruptors. M&A activity targets behavioral biometrics capabilities, while technology licensing agreements proliferate as smartphone OEMs extend sensor stacks into building automation.
Within the platform integrator tier, NEC Corporation and Thales exemplify divergent positioning strategies. NEC leverages longstanding immigration authority relationships across multiple jurisdictions to sustain large-scale deployment contracts. Thales competes through integrated digital identity platforms extending beyond hardware into software analytics. IDEMIA anchors the civil identification archetype, controlling enrollment and credential issuance infrastructure for national identity programs.
| Leading Market Players |
|---|
| NEC Corporation |
| Socure |
| Thales |
| Alcatraz AI |
| HYPR Corp |
| IDEMIA |
| Fujitsu |
| Paravision |
| ASSA ABLOY |
| Others |
Supply & Pricing Matrix
Overcapacity in capacitive fingerprint sensor foundries across Taiwan and South Korea is compressing component pricing while forcing suppliers toward ultrasonic and optical-on-glass differentiation. This utilization squeeze cascades into OEM procurement posture, where buyers extract volume concessions while locking in long-term supply agreements for neural accelerator chips.
Pricing Analysis
Volume-discount tiering structures dominate enterprise biometric procurement, with three-tier pricing separating EU AI Act-certified multimodal suites from standard facial recognition APIs and economy-grade fingerprint terminals. Price differentiation hinges on NIST FRTE certification tier and after-sales analytics bundling. Pricing pressure stems from cloud-native API providers commoditizing facial recognition inference. Government agencies exhibit lowest price sensitivity due to compliance mandates, while franchise retail networks drive hardest bargain on per-unit hardware costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for biometric hardware OEMs. Advanced image signal processors and neural accelerators draw from Taiwan, South Korea, and China foundries. Raw material dependencies include gallium arsenide substrates, specialized optical glass, and rare-earth magnets for motor-actuated iris cameras. Distribution runs through systems integrators serving immigration authorities and direct OEM relationships with smartphone manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
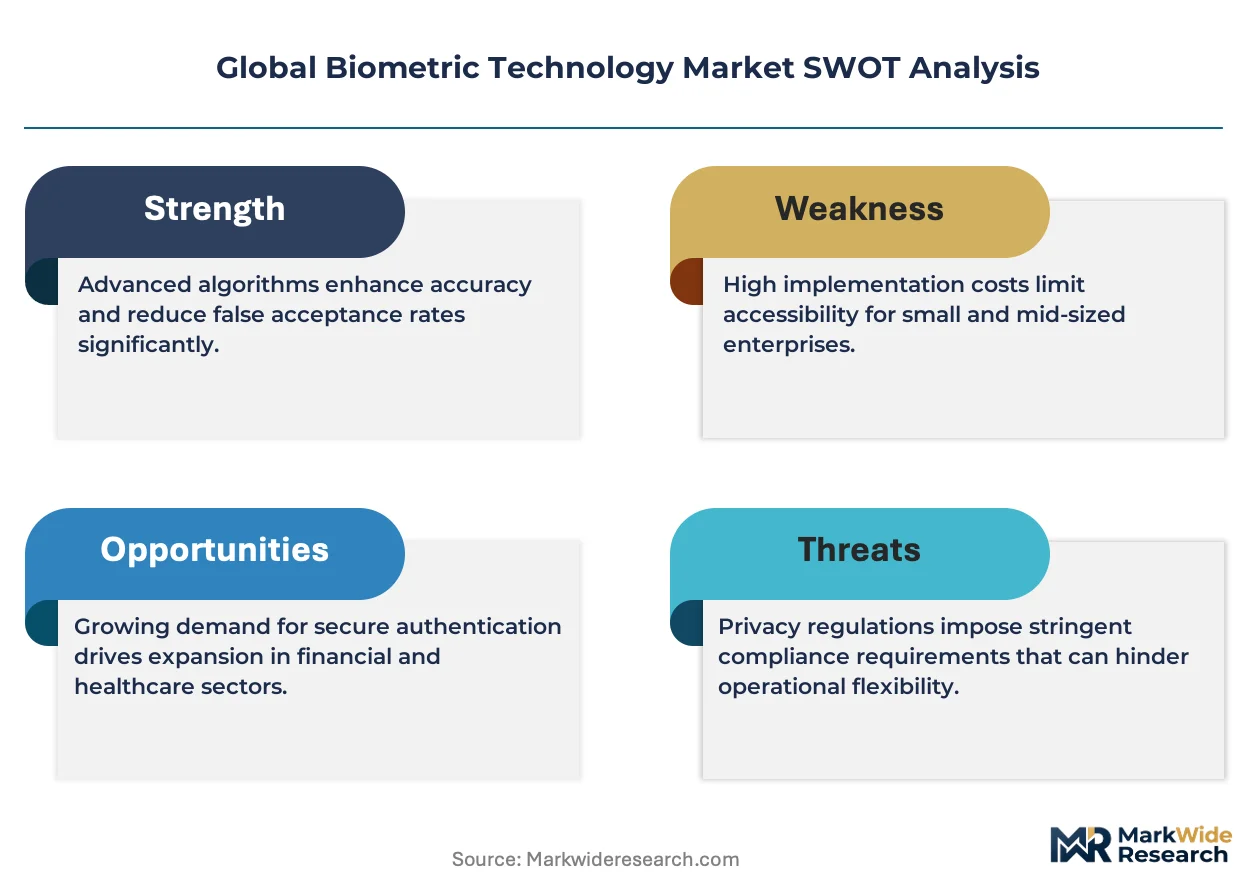
Passwordless FIDO2 authentication and decentralized identity wallets constitute credible substitution threats that incumbent biometric vendors must neutralize through continuous authentication value propositions.
For Market Incumbents: Entrench position through backward integration into edge AI silicon design and captive liveness detection algorithm development. NEC Corporation and IDEMIA should deepen control over enrollment infrastructure to lock out platform competitors. Prioritize EU AI Act conformity assessment pre-certification to compress competitor launch windows in European public sector channels. For New Entrants and Emerging Players: Pursue behavioral biometrics convergence for zero-trust financial services where keystroke dynamics and gait analysis remain underdeveloped. White-space concentrates in German manufacturing edge deployments where GDPR data minimization prohibits cloud transmission. Go-to-market should anchor on federated learning architectures with on-device template matching. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biometric-as-a-service platform providers bundling facial time clocks with cloud payroll systems. Long-term viability favors vendors with sticky enrollment-credential issuance infrastructure rather than commodity sensor manufacturers. Watch liveness detection algorithm performance against deepfake presentation attacks as the critical inflection signal for trust erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Module Development | On-device processing satisfies GDPR data residency requirements in German healthcare deployments. |
| Behavioral Biometrics Acquisition | Keystroke dynamics layering creates continuous authentication protocols for financial zero-trust frameworks. |
| EU Conformity Assessment Pre-Certification | Human-in-the-loop architectures preempt compliance failures in French and German police procurement. |
| Digital Identity Wallet Integration | EU Digital Identity Regulation mandates position vendors for recurring verification revenue streams. |
| Contactless Fingerprint-on-Display Licensing | Ultrasonic sensor stacks extend biometric touchpoints into elevator panels and vehicle entry systems. |
Research Methodology
A standing panel of biometric systems engineers, immigration authority procurement officers, cloud platform architects, and financial services fraud prevention leads provided ongoing calibration across primary fieldwork. Secondary validation drew from UIDAI hardware specifications, EU AI Act conformity assessment body disclosures, NIST FRTE test results, and SEC filings of publicly traded platform vendors. Bottom-up sensor shipment estimates and top-down identity infrastructure spending analysis were triangulated to anchor market sizing.
Scenario-bracketing framed projections across the analysis window, modeling biometric type, deployment model, end-user industry, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from curve-fitting historical procurement cycles against policy mandate timelines, with particular weighting of Aadhaar-linked hardware refresh patterns and EU Digital Identity Regulation implementation phases. Inference latency benchmarks and liveness detection accuracy metrics informed technology adoption rate assumptions.
Sensitivities concentrate around deepfake presentation attack proliferation, Taiwan foundry allocation constraints, and divergence between permissive national identity frameworks and restrictive privacy regimes. Forecasts reflect documented assumptions on compliance timeline adherence and hardware cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
FIDO Authentication Market