
 North America Bio-Ethanol Market | 2026-2036
North America Bio-Ethanol Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bio-Ethanol Market Analytics
US Midwest corn belt capacity expansion is reconfiguring supply flows across North America. POET, LLC leverages its network of biorefineries to sustain throughput advantages in grain-based ethanol production. ADM anchors its position through backward integration into corn origination and downstream distribution infrastructure. Valero competes by operating refineries with co-located ethanol blending capabilities that reduce logistics costs.
Bio-ethanol denotes a renewable alcohol fuel produced through fermentation of biomass carbohydrates, typically yielding 99% purity after distillation and dehydration, primarily serving as an oxygenate and octane enhancer in gasoline blends. Grain-based ethanol dominates current production volumes due to mature enzymatic conversion and well-established supply chains, while cellulosic pathways remain nascent but attract capital for their feedstock flexibility and lower indirect land-use change profile. The automotive end user segment absorbs the largest share of output under federal blending mandates, whereas industrial solvent applications command premium pricing for higher-purity product grades.
The US EPA administers Renewable Fuel Standard volume obligations that directly determine annual bio-ethanol demand floors, while Health Canada and PMRA coordinate North American fuel quality standards that affect cross-border product specifications. State-level low-carbon fuel programs in California and Oregon create additional compliance markets that pull ethanol from Midwest production centers. Stakeholders must monitor cellulosic technology cost curves and policy stability around federal tax credits to time capacity commitments effectively.
Market Dynamics
The US EPA's escalating Renewable Fuel Standard volume obligations are compressing blending economics across the automotive sector, forcing refiners to absorb higher ethanol volumes regardless of pump price differentials against gasoline.
Growth Catalysts
- Cellulosic conversion maturation:Pilot-scale enzymatic hydrolysis of agricultural residues is reducing feedstock dependency on corn starch alone.
- California LCFS compliance pull:The state's Low Carbon Fuel Standard generates credit premiums that attract Midwest ethanol volumes westward.
- Automotive octane demand:Higher compression engines from Detroit manufacturers require ethanol's 113 octane rating to meet efficiency targets.
Market Restraints
- Corn price volatility:Drought conditions in Illinois and Iowa feedstock regions compress crush margins unpredictably.
- Blending wall constraints:Legacy vehicle fleets and retail infrastructure limit E15 penetration beyond the current E10 saturation point.
- Gasoline demand erosion:Electric vehicle adoption in coastal states displaces the addressable gasoline pool for ethanol blending.
Strategic Opportunities
- Sustainable aviation fuel pathways:Alcohol-to-jet conversion technologies open aviation as a new offtake channel with premium pricing.
- Carbon capture retrofit:Biorefinery CCS installations qualify for 45Q tax credits while lowering lifecycle carbon intensity scores.
- Mexico import liberalization:Pemex infrastructure constraints create openings for US Gulf Coast ethanol exports southward.
Industry Challenges
- Enzyme biochemistry talent scarcity:Cellulosic operations struggle to recruit fermentation specialists with pilot-scale experience.
- Pipeline specification fragmentation:Batch integrity requirements for multiproduct pipelines complicate ethanol distribution logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bio-Ethanol Market |
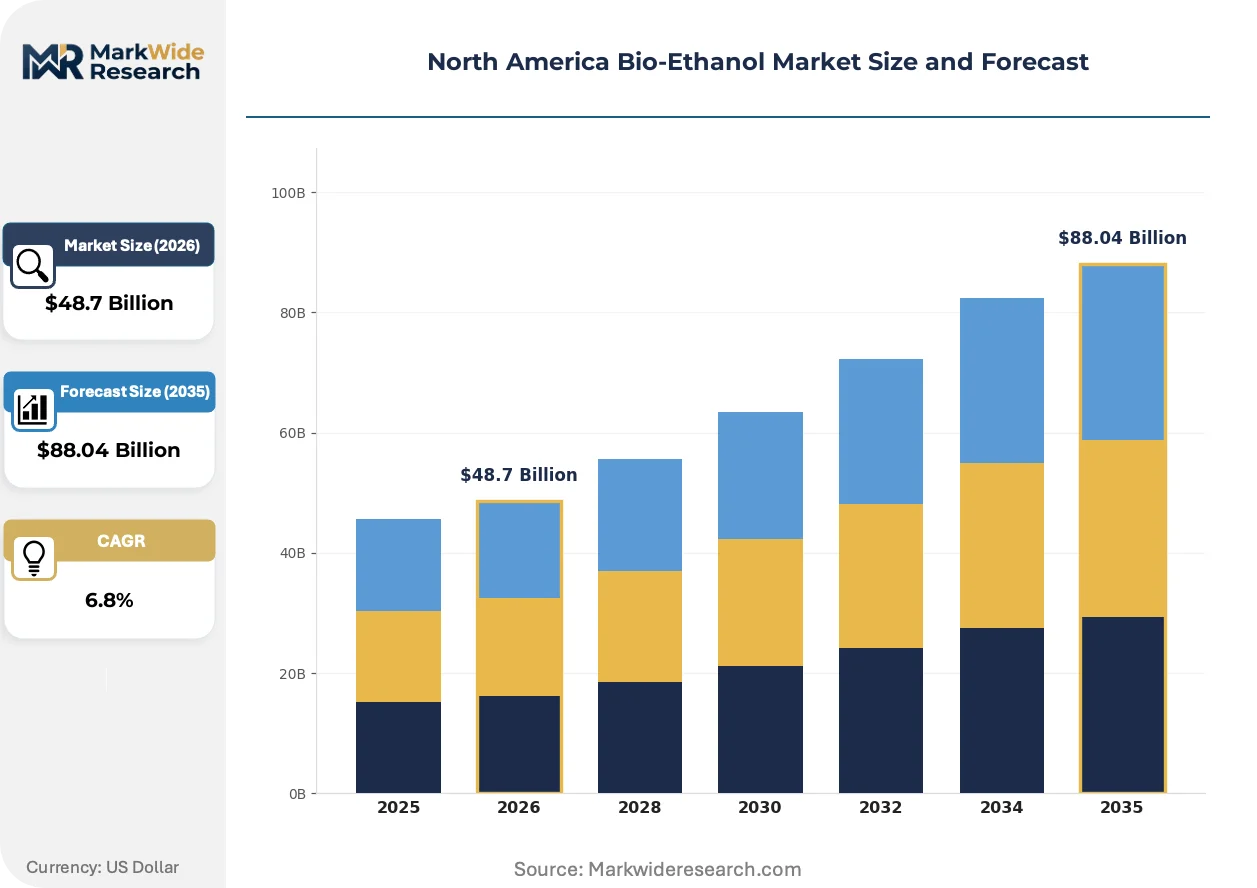
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain-Based, Sugarcane-Based, Cellulosic, Other Application: Fuel, Animal Feed, Beverage, Industrial Solvents Distribution Channel: Retail, Wholesale, Direct Sales, Online End User: Automotive, Industrial, Agricultural, Energy Sector |
| Companies Covered | ADM, POET, LLC, Valero, Green Plains Inc., Suncor Energy Inc., Cenovus Inc., The Andersons Inc., Flint Hills Resources, Alto Ingredients Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bio-Ethanol Market Evolving Landscape
Process intensification and carbon accounting precision are reconfiguring how North American biorefineries compete on cost and compliance credentials simultaneously.
Continuous enzymatic hydrolysis systems are collapsing the capital cost differential between first-generation and cellulosic ethanol platforms. POET and DSM partnerships have installed demonstration units in South Dakota that achieve 85% cellulose conversion rates. Refiners with backward integration into corn origination now face stranded asset risk if cellulosic yields achieve cost parity.
Health Canada and the US EPA are harmonizing lifecycle carbon accounting methodologies for cross-border fuel credit trading. The revised GREET model adoption compresses regulatory arbitrage opportunities between federal and state programs. Midwest producers with verified low-carbon intensity scores capture price premiums in Oregon and British Columbia compliance markets.
Fleet operators in the Upper Midwest are consolidating procurement through direct biorefinery offtake agreements rather than spot market purchases. Large agricultural cooperatives in Minnesota and Nebraska now contract ethanol volumes three years forward, displacing traditional merchant distributor relationships. This concentration of buying power squeezes margin capture for independent ethanol marketers without captive origination assets.
North America Bio-Ethanol Market Segmentation
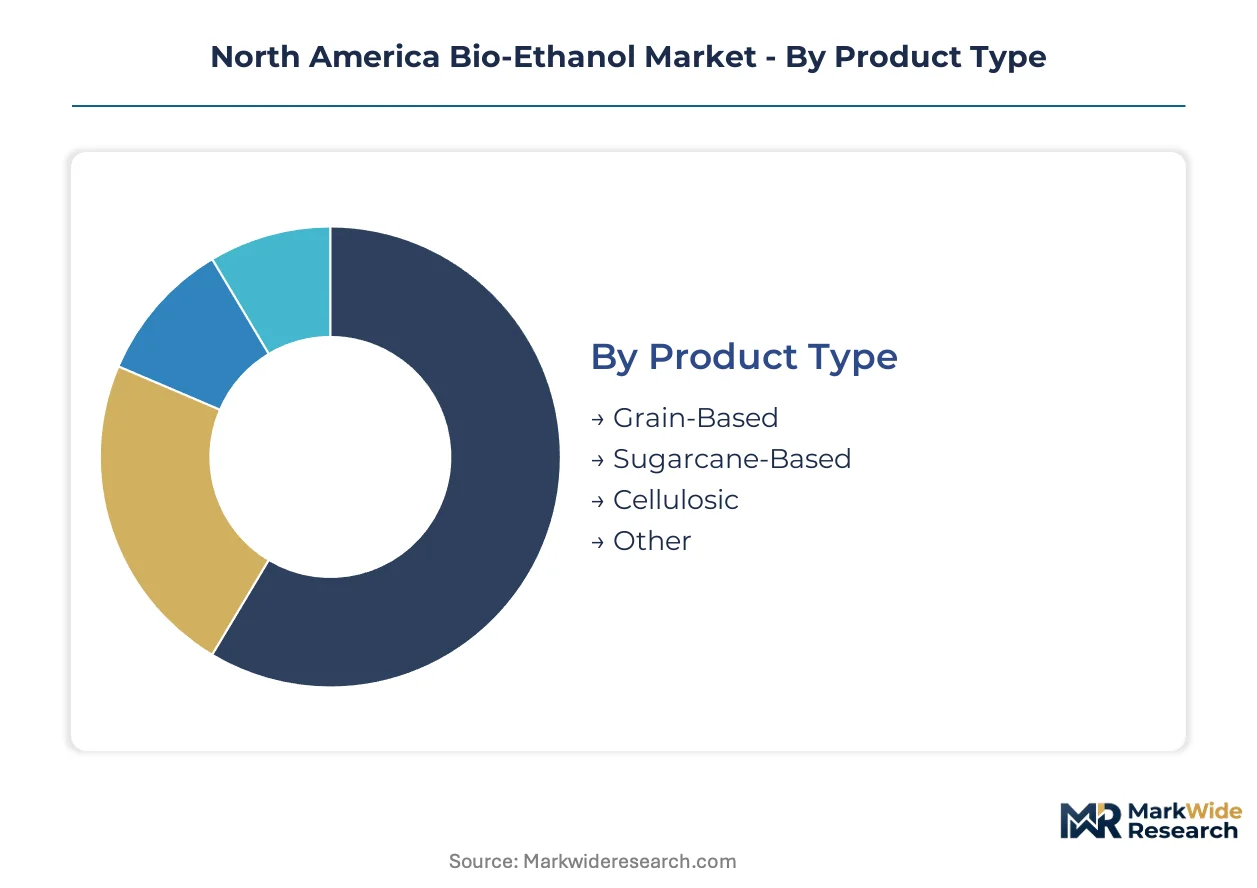
Segmentation in North American bio-ethanol reveals how feedstock chemistry, regulatory pathways, and end-use specifications create distinct commercial battlegrounds. Each dimension carries different margin profiles and capital intensity requirements that shape producer strategy across the US Midwest and beyond.
Product Type:
Cost tier differentiation separates mature starch fermentation from emerging conversion platforms competing on feedstock flexibility and carbon intensity scoring.
- Grain-Based:Corn starch enzymatic hydrolysis yields 99% purity ethanol through mature dry-mill or wet-mill processes. US EPA Renewable Fuel Standard obligations concentrate demand in Iowa and Illinois biorefineries where POET and ADM operate integrated origination-to-distillation networks. Drought-driven corn price spikes compress crush margins unpredictably.
- Cellulosic:Lignocellulosic biomass conversion via enzymatic hydrolysis of corn stover, wheat straw, or dedicated energy crops accesses agricultural residues without food-fuel competition. California LCFS compliance markets pull pilot-scale volumes from South Dakota demonstration facilities as conversion yields approach 85%. Capital costs remain 40-60% above first-generation platforms pending process intensification.
- Sugarcane-Based:Cane juice or molasses fermentation dominates Brazilian supply but captures minimal North American share due to import tariffs and freight disadvantages.
- Other:Waste starch from food processing and synthetic biology pathways occupy niche positions without material scale.
Grain-Based holds installed capacity. Cellulosic is rotating up the share rankings.
Application:
Volume concentration and margin structure diverge sharply between compliance-driven fuel blending and specialty chemical markets.
- Fuel:Gasoline oxygenation and octane enhancement absorb over 90% of North American ethanol output under federal blending mandates. E10 saturation across US retail infrastructure limits penetration growth, while E15 expansion faces legacy vehicle compatibility constraints and seasonal volatility restrictions from the EPA.
- Industrial Solvents:High-purity anhydrous ethanol commands premium pricing for pharmaceutical extraction, cosmetics, and electronics cleaning where residual moisture specifications below 0.5% justify specialized dehydration infrastructure. Health Canada and PMRA coordinate cross-border purity standards that fragment batch certification requirements.
- Animal Feed:Distillers dried grains with solubles (DDGS) from dry-mill operations provide protein-rich livestock nutrition, with Minnesota and Nebraska feedlots sourcing directly from biorefinery coproduct streams.
- Beverage:FCC-grade ethanol for spirits and flavor extracts represents sub-2% of volume but maintains pricing power through excise tax distinctions and organic certification premiums.
Fuel dominates volume throughput. Industrial Solvents is climbing the fastest on margin contribution.
Distribution Channel:
Customer type and procurement scale determine channel economics, with large fleet operators bypassing traditional merchant intermediaries.
- Wholesale:Terminal rack sales to refiners and blenders constitute the primary volume pathway, with Gulf Coast and Chicago hub pricing setting regional benchmarks. Valero and Marathon Petroleum capture logistics advantages through co-located ethanol receiving and gasoline blending infrastructure.
- Direct Sales:Agricultural cooperatives in Minnesota and Nebraska now contract three-year forward volumes directly with biorefineries, displacing spot market exposure and squeezing independent distributor margins. This concentration of buying power favors producers with captive origination assets.
- Retail:Branded E85 stations and flex-fuel pumps serve dedicated fleet operators in the Upper Midwest where vehicle compatibility and price spreads support consumption.
- Online:Digital procurement platforms for industrial solvent grades enable small-batch ordering with certificate-of-analysis documentation, though fuel ethanol remains physically delivered through established terminal networks.
Wholesale maintains infrastructure lock-in. Direct Sales is gaining share fastest as procurement consolidates.
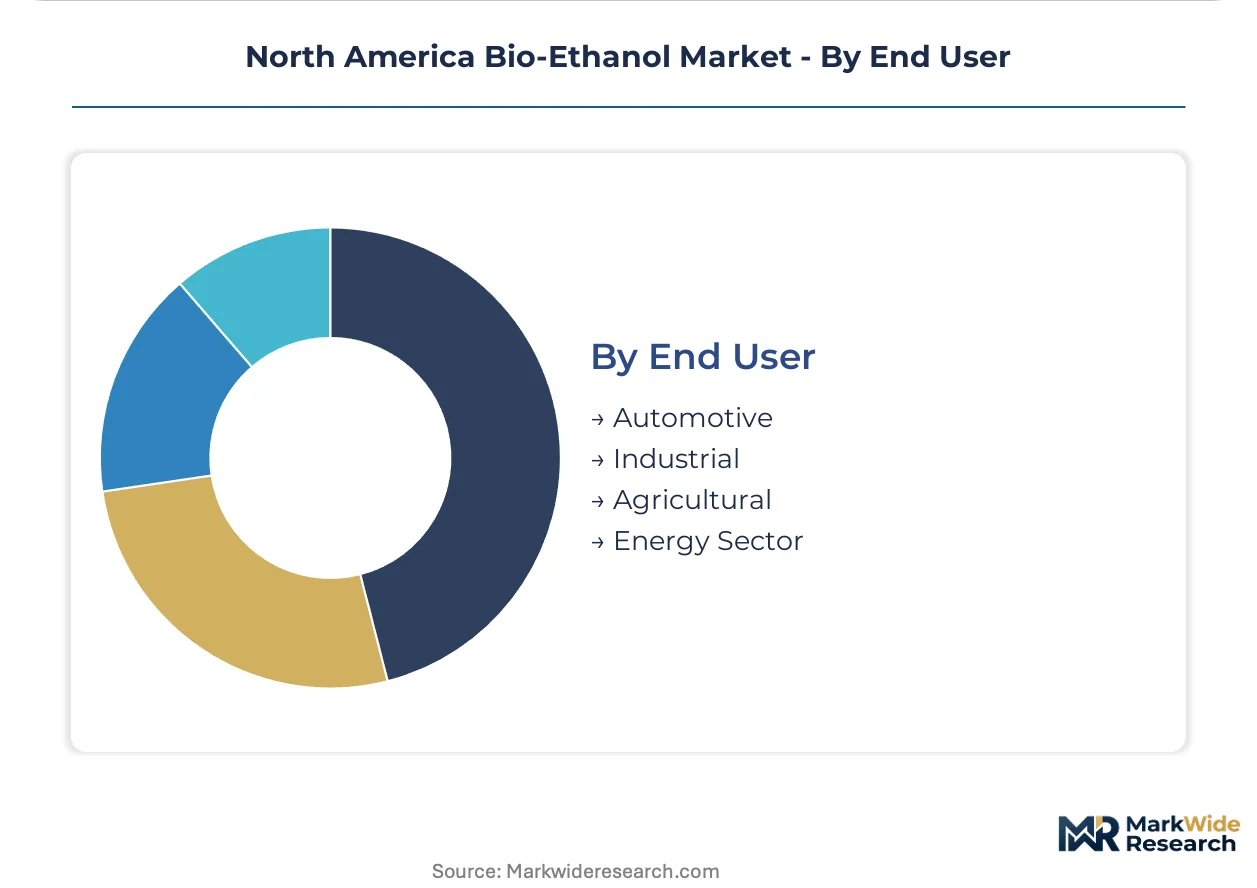
End User:
Geography and regulatory exposure segment demand between federal compliance markets and state-level low-carbon fuel programs.
- Automotive:Detroit manufacturers specify ethanol-blended gasoline for higher compression engines requiring 113 octane rating to meet Corporate Average Fuel Economy standards. Oregon and British Columbia compliance markets pull volumes westward from Midwest production centers through carbon intensity score arbitrage.
- Energy Sector:Power generation and heating applications absorb fuel ethanol in regions with renewable portfolio standards, though direct combustion remains marginal against blending economics.
- Industrial:Chemical manufacturers and coatings formulators purchase beverage-grade or industrial-grade ethanol based on purity specifications and excise tax status.
- Agricultural:On-farm equipment and irrigation pumps in corn belt states consume E85 where local supply proximity eliminates transportation cost penalties.
Automotive anchors demand volume. Energy Sector is rotating up the share rankings on sustainable aviation fuel pathway development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EPA anchors North American bio-ethanol demand through Renewable Fuel Standard volume obligations that cascade across federal and state compliance markets. Production clusters concentrate in the US Midwest corn belt, with Canadian and Mexican markets absorbing cross-border flows shaped by trade policy and infrastructure constraints.
United States
Iowa and Illinois biorefineries process over half of national ethanol output under EPA blending mandates. California's Low Carbon Fuel Standard pulls Midwest volumes westward through carbon intensity arbitrage. POET operates integrated origination-to-distillation networks across South Dakota and Iowa.
Canada
Ontario and Saskatchewan ethanol plants serve provincial renewable fuel regulations coordinated with Health Canada fuel quality standards. British Columbia compliance markets import US Midwest ethanol with verified low-carbon intensity scores. Suncor Energy processes grain ethanol at its St. Clair River facility.
Mexico
Pemex infrastructure constraints in Nuevo León and Tamaulipas create import dependence for oxygenate blending requirements. Energy regulatory reforms since 2013 opened fuel distribution to private terminal operators. US Gulf Coast exporters target Veracruz and Altamira port facilities.
North America Bio-Ethanol Market Competitive Landscape
Integrated agribusiness conglomerates and independent biorefinery specialists split the market between captive feedstock control and merchant processing flexibility. Market structure tilts toward consolidation in grain origination zones, with Iowa and Nebraska hosting the densest production clusters. Three archetypes dominate: backward-integrated grain processors, petroleum refinery co-locators, and pure-play ethanol marketers. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with carbon capture retrofits emerging as a differentiation mechanism.
Among backward-integrated processors, ADM and POET exemplify the archetype of captive corn supply chains and distributed distillation infrastructure. Valero occupies a position bridging petroleum refining and ethanol production through terminal co-location strategies. These three entities anchor competitive dynamics across the US Midwest production belt.
| Leading Market Players |
|---|
| ADM |
| POET, LLC |
| Valero |
| Green Plains Inc. |
| Suncor Energy Inc. |
| Cenovus Inc. |
| The Andersons Inc. |
| Flint Hills Resources |
| Alto Ingredients Inc |
| Others |
Value Network & Pricing Analysis
Overcapacity signals from Iowa and Illinois biorefineries are compressing spot market premiums and forcing suppliers toward long-term offtake contracting to defend utilization rates and margin stability.
Pricing Analysis
Chicago hub ethanol pricing runs at persistent discounts to California LCFS credit-adjusted delivered costs, creating arbitrage incentives for Midwest producers with verified low-carbon intensity scores. Pricing stratifies across fuel-grade, industrial-grade, and beverage-grade certification tiers with purity specifications and excise tax status as primary differentiation drivers. Cost compression in fuel-grade volumes is intensifying because drought-driven corn price volatility squeezes crush margins without corresponding RIN price relief. Agricultural cooperatives demonstrate highest price sensitivity through consolidated three-year forward contracting, while pharmaceutical extractors accept premiums for anhydrous grades below 0.5% moisture.
Supply Chain Analysis
Tariff exposure between the United States and Brazil limits sugarcane ethanol import competition and protects domestic corn-based production economics. Supply concentration centers on the US Midwest corn belt, with secondary clusters in Ontario and Saskatchewan drawing from regional grain origination networks. Raw material dependencies rest on corn starch, agricultural residues for cellulosic pilot operations, and specialized enzymes from biotechnology suppliers. Single-source vulnerability in fermentation biochemistry talent constrains cellulosic scale-up timelines. Distribution runs through Gulf Coast and Chicago terminal rack networks with co-located gasoline blending infrastructure at petroleum refinery sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as state-level low-carbon fuel programs proliferate, creating compliance market niches that reward carbon intensity differentiation over pure scale economics.
For Market Incumbents: Pre-empt cellulosic cost parity threats by retrofitting existing dry-mill infrastructure with carbon capture systems to qualify for 45Q tax credits and secure LCFS premium capture. Anchor backward integration into corn origination through direct contracting with agricultural cooperatives in Minnesota and Nebraska to defend against merchant processor margin erosion. Prioritize fermentation specialist recruitment pipelines to address biochemistry talent scarcity constraining pilot-scale operations.
For New Entrants and Emerging Players: Pursue sustainable aviation fuel pathway development through alcohol-to-jet conversion partnerships with aviation offtakers seeking premium-priced low-carbon feedstocks. Target Mexico import liberalization opportunities at Veracruz and Altamira port facilities where Pemex infrastructure constraints create demand pull for US Gulf Coast ethanol exports. Lead with direct biorefinery offtake agreements rather than spot market participation to bypass established distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward cellulosic technology platforms with demonstrated 85% conversion yields and established pilot-scale operations in South Dakota or adjacent feedstock-rich geographies. Long-term viability hinges on regulatory stability around federal tax credits and state LCFS program durability rather than pure commodity processing margins. Watch for EPA Renewable Fuel Standard volume obligation trajectory announcements as the critical inflection signal for grain-based capacity valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | 45Q tax credit qualification lowers lifecycle carbon intensity scores for LCFS premium capture. |
| Cellulosic Scale-Up | Continuous enzymatic hydrolysis demonstration units reduce capital cost differential against first-generation platforms. |
| Direct Offtake Contracting | Three-year forward volumes with agricultural cooperatives displace spot market exposure and independent distributor margins. |
| Cross-Border Infrastructure | Gulf Coast export terminal access to Veracruz and Altamira leverages Mexico energy regulatory reforms. |
| Fermentation Talent Pipeline | Biochemistry specialist recruitment addresses pilot-scale operational constraints constraining cellulosic commercialization. |
Research Methodology
Initial hypotheses were tested against primary input from biorefinery operations managers, agricultural cooperative procurement directors, petroleum refinery blending specialists, and EPA regulatory affairs consultants and refined through secondary validation. Trade data from US EIA, EPA Renewable Fuel Standard compliance reports, California Air Resources Board LCFS credit transaction records, and Health Canada fuel quality standards provided demand-side benchmarks. Bottom-up capacity utilization assessments across Iowa, Illinois, and South Dakota production facilities were triangulated against top-down EPA mandate volume obligations.
Demand-supply-balance modeling anchored projections across the analysis window, with segmentation dimensions spanning feedstock chemistry, application purity grade, distribution channel structure, and end-user regulatory exposure. CAGRs were derived from iterative reconciliation of production capacity expansion schedules, federal mandate trajectory assumptions, and state-level low-carbon fuel program adoption curves. Forecast inputs incorporated corn price volatility scenarios, cellulosic conversion yield improvement curves, and electric vehicle adoption impacts on gasoline pool erosion.
Sensitivities concentrate around EPA volume obligation stability, state LCFS program durability, and cellulosic technology cost curve progression relative to grain-based platforms. Forecasts reflect documented assumptions regarding federal tax credit continuity and drought frequency in feedstock origination regions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
China Biocontrol Agents Market