
 Japan Big Data Analytics in Energy Market | 2026-2036
Japan Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Big Data Analytics in Energy Market Insights
Project finance for smart grid infrastructure is narrowing the competitive field to vendors with balance-sheet scale. Siemens Aktiengesellschaft leverages its industrial automation heritage to anchor utility-scale deployments. NEC Corporation competes through deep domestic relationships with Tokyo Electric Power and regional grid operators. Microsoft Corporation extends its cloud footprint via Azure energy modules tailored to Japanese regulatory requirements.
Japan Big Data Analytics in Energy encompasses the computational processing of massive, heterogeneous datasets from generation, transmission, and consumption nodes to extract actionable intelligence for operational optimization, typically involving petabyte-scale time-series ingestion, distributed stream processing, and machine learning inference at sub-second latency. The technology stack spans machine learning algorithms for load forecasting, predictive analytics for asset degradation modeling, and data visualization for control room decision support. Software solutions command the primary margin pool due to recurring licensing economics, while managed services gain traction among mid-tier utilities lacking in-house data science capabilities. Grid optimization applications lead in deployment velocity as aging infrastructure strains under renewable intermittency.
METI enforces cybersecurity standards for critical energy infrastructure through its Agency for Natural Resources and Energy, while the Ministry of Economy, Trade and Industry coordinates cross-sector data sharing protocols under the Society 5.0 framework. JIS standards for industrial IoT interoperability shape procurement specifications and vendor qualification criteria. Stakeholders must weigh build-versus-buy decisions for edge computing capacity as distributed energy resources proliferate beyond centralized control architectures.
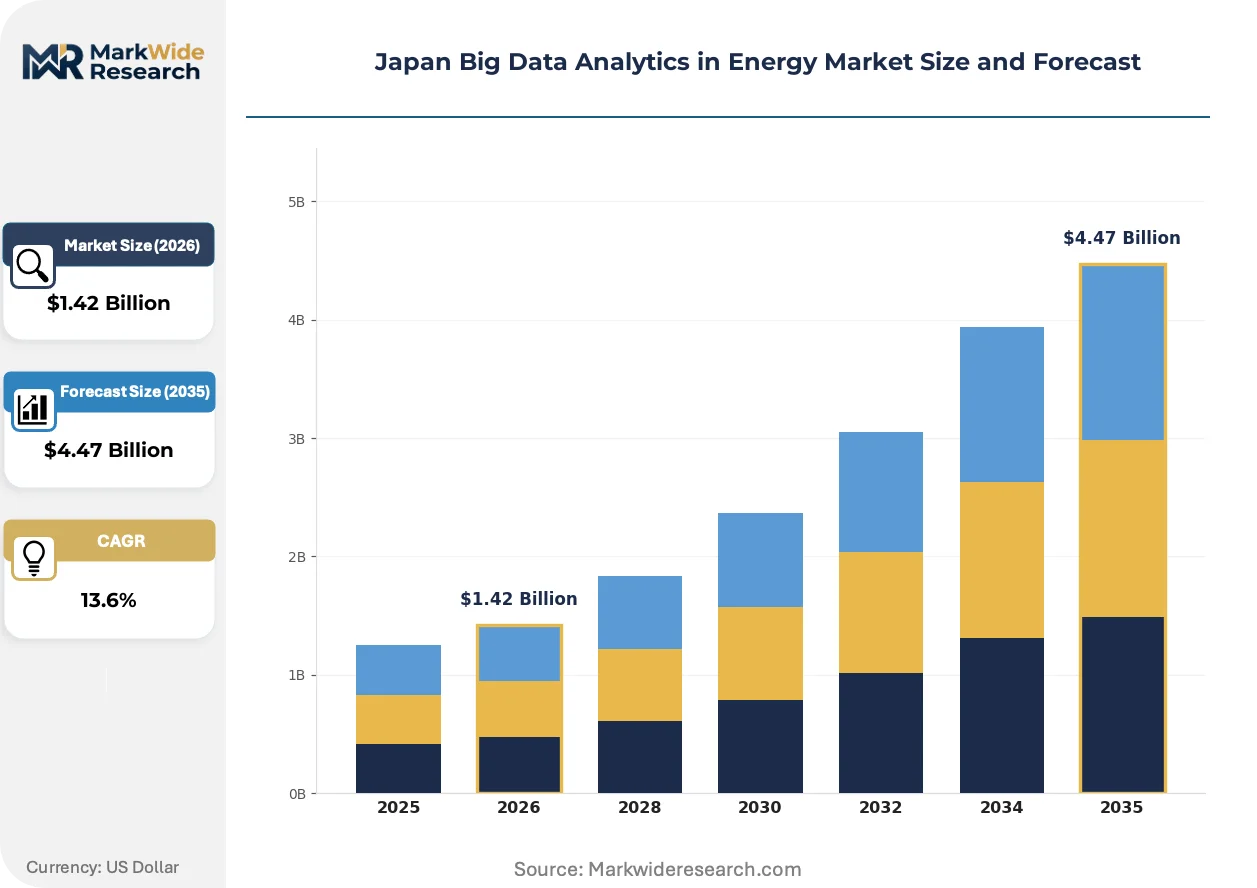
Market Dynamics
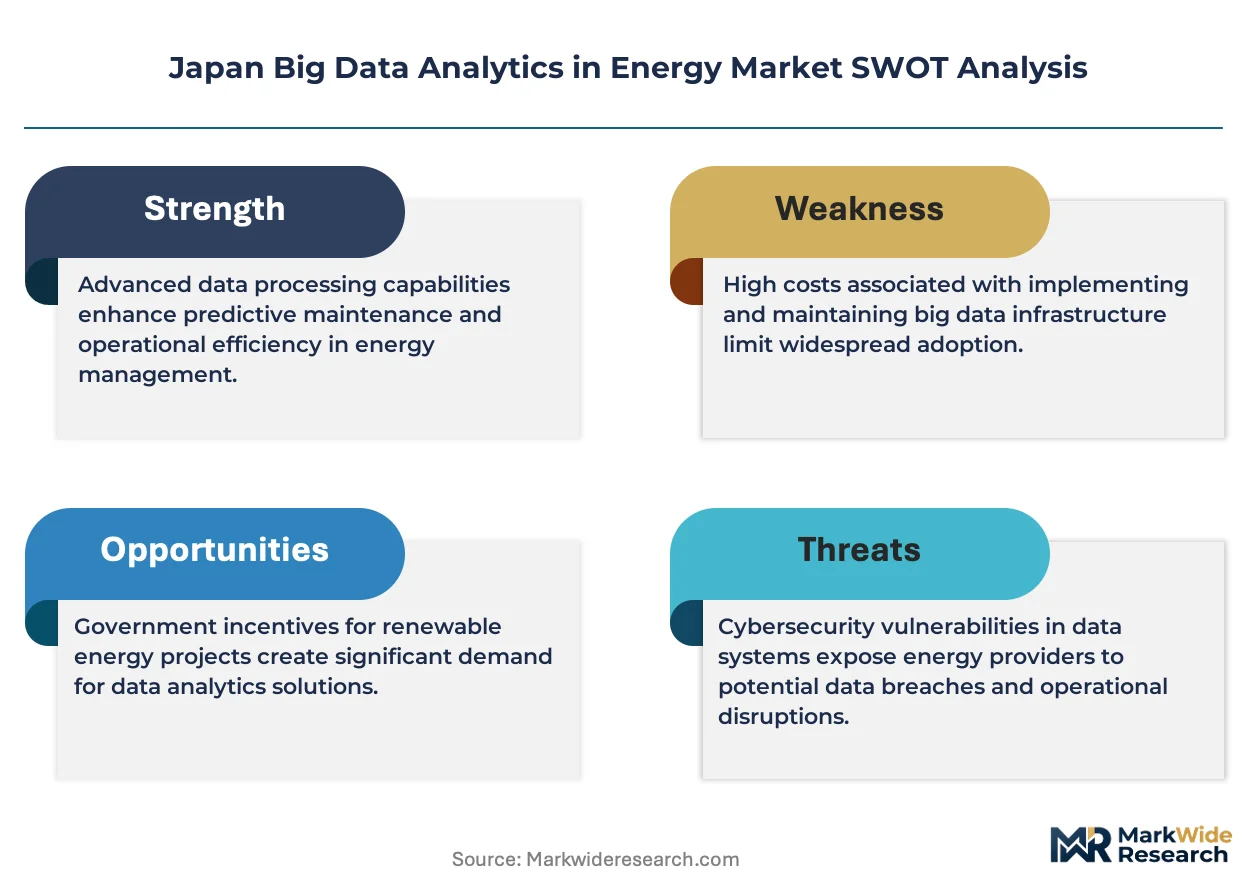
Japan's power sector faces structural pressure from renewable intermittency straining aging transmission infrastructure, forcing utilities to deploy real-time analytics at unprecedented scale across metropolitan load centers.
Growth Catalysts
- Green Transformation mandate:METI's GX initiative compels grid operators to modernize digital infrastructure, creating procurement pull for predictive maintenance platforms.
- Tokyo metropolitan complexity:Peak load volatility in the capital region demands sub-second inference capabilities that legacy SCADA systems cannot deliver.
- Distributed energy proliferation:Rooftop solar and battery storage assets fragment generation control, necessitating edge analytics for voltage regulation.
Market Restraints
- Domestic cloud concentration:Data sovereignty requirements limit foreign platform penetration, constraining vendor choice for regional utilities.
- Legacy system entrenchment:Decades-old control room architectures impose integration friction that extends deployment timelines.
- Specialized talent scarcity:Shortage of power systems engineers with machine learning fluency inflates implementation costs for mid-tier operators.
Strategic Opportunities
- Kansai industrial corridor:Osaka-Kobe manufacturing belt presents untapped demand for industrial load disaggregation analytics.
- Cross-sector data fusion:METI's Society 5.0 framework enables utility-telecom data sharing protocols for demand response optimization.
- Offshore wind integration:Planned Kyushu and Hokkaido projects require marine-environment predictive models absent from current vendor portfolios.
Industry Challenges
- JIS certification timelines:Industrial IoT interoperability standards create six-to-twelve month procurement delays for non-domestic equipment.
- Control room culture resistance:Operator trust deficits in algorithmic dispatch recommendations slow adoption of automated grid balancing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Big Data Analytics in Energy Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Managed Services, Software Solutions, Cloud Services Technology: Machine Learning, Data Visualization, Predictive Analytics, AI Algorithms End User: Utilities, Oil & Gas Companies, Renewable Energy Firms, Industrial Consumers Application: Demand Forecasting, Asset Management, Energy Trading, Grid Optimization |
| Companies Covered | International Business Machines Corporation, SAP SE, Microsoft Corporation, Siemens Aktiengesellschaft, Accenture plc, NEC Corporation, Hitachi, Fujitsu, Toshiba, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Big Data Analytics in Energy Market Trends and Innovations
Computational architectures for energy analytics are compressing latency thresholds while regulatory frameworks harden data governance requirements.
Digital twin technology is collapsing the cost structure of asset degradation modeling. Tepco and Chubu Electric deploy physics-informed neural networks for transformer health prediction. Sub-second simulation fidelity now enables condition-based maintenance that shrinks capital reserve requirements.
METI's cybersecurity directives for critical infrastructure tighten vendor qualification criteria. The Agency for Natural Resources and Energy mandates air-gapped architectures for transmission control systems. Domestic system integrators gain procurement preference as foreign cloud providers face localization requirements.
Subscription pricing for analytics software displaces perpetual licensing across regional utilities. Hokkaido Electric and Tohoku Electric Power favor operational expenditure models that transfer algorithm performance risk to vendors. Procurement committees now weight vendor balance-sheet strength alongside technical specifications.
Japan Big Data Analytics in Energy Market Segmentation
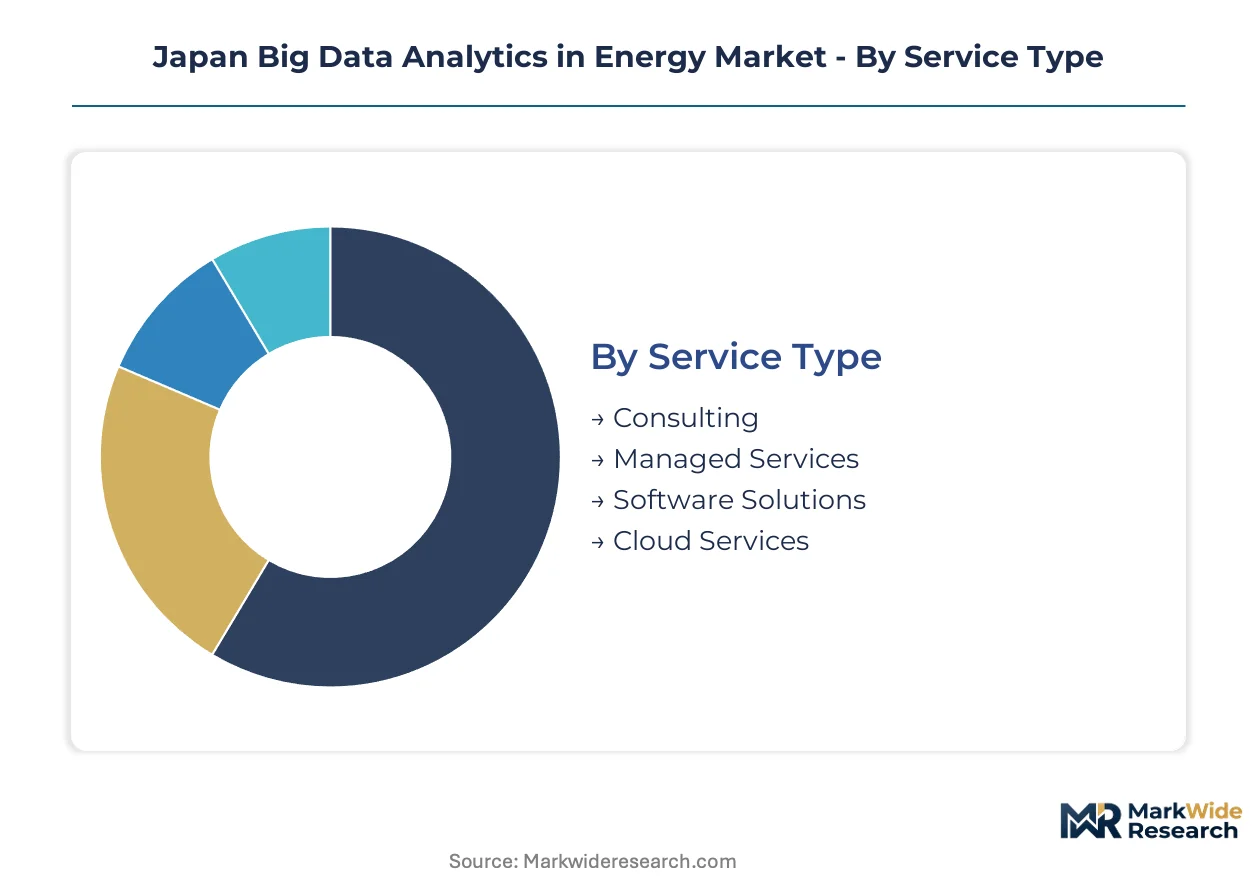
Segmentation in Japan's energy analytics market reveals distinct procurement rhythms across service layers and technology stacks. Understanding these cycles helps vendors align resource allocation with contract velocity and margin profiles.
Service Type:
Contract cycles vary dramatically across service layers, with subscription software turning over fastest and consulting engagements stretching across multi-year transformation programs.
- Software Solutions:Recurring licensing models dominate utility procurement, with predictive maintenance platforms commanding premium pricing due to embedded algorithmic IP. Tokyo Electric Power and Chubu Electric anchor demand for grid optimization modules as renewable intermittency strains dispatch operations.
- Managed Services:Mid-tier regional utilities lacking in-house data science capabilities outsource entire analytics operations, transferring algorithm performance risk to vendors through outcome-based pricing structures.
- Consulting:Grid modernization roadmapping and digital twin implementation planning for transmission operators.
- Cloud Services:METI data sovereignty requirements favor domestic hyperscale deployments over foreign platforms.
Software Solutions dominates installed base. Managed Services is where expansion concentrates.
Technology:
Technology layers stratify by implementation maturity, with visualization tools deployed universally while physics-informed neural networks remain concentrated at frontier utilities.
- Predictive Analytics:Asset degradation modeling for transformers and switchgear drives the largest procurement volumes, with Tepco deploying sub-second inference for condition-based maintenance that shrinks capital reserve requirements.
- Machine Learning:Load forecasting algorithms process petabyte-scale time-series data from smart meters across Tokyo's metropolitan load centers, where peak volatility exceeds legacy SCADA response capabilities.
- Data Visualization:Control room decision support interfaces standardizing across regional grid operators.
- AI Algorithms:Autonomous voltage regulation for distributed solar and battery storage assets proliferating beyond centralized control architectures.
Predictive Analytics commands the deepest deployment experience. Machine Learning is climbing the fastest as renewable penetration accelerates inference requirements.
End User:
User sophistication spans from algorithm-native industrial loads to risk-averse transmission incumbents with decades-old control room cultures.
- Utilities:Grid operators face METI Green Transformation mandates compelling digital infrastructure upgrades, with procurement committees now weighting vendor balance-sheet strength alongside technical specifications for mission-critical deployments.
- Industrial Consumers:Osaka-Kobe manufacturing belt demand for industrial load disaggregation analytics remains underpenetrated, with steel and chemical producers seeking granular consumption visibility for carbon accounting compliance.
- Renewable Energy Firms:Offshore wind developers require marine-environment predictive models absent from current vendor portfolios.
- Oil & Gas Companies:Refinery optimization and downstream logistics analytics for integrated energy majors.
Utilities anchor procurement volume. Industrial Consumers represent the steepest expansion trajectory as manufacturing decarbonization tightens.
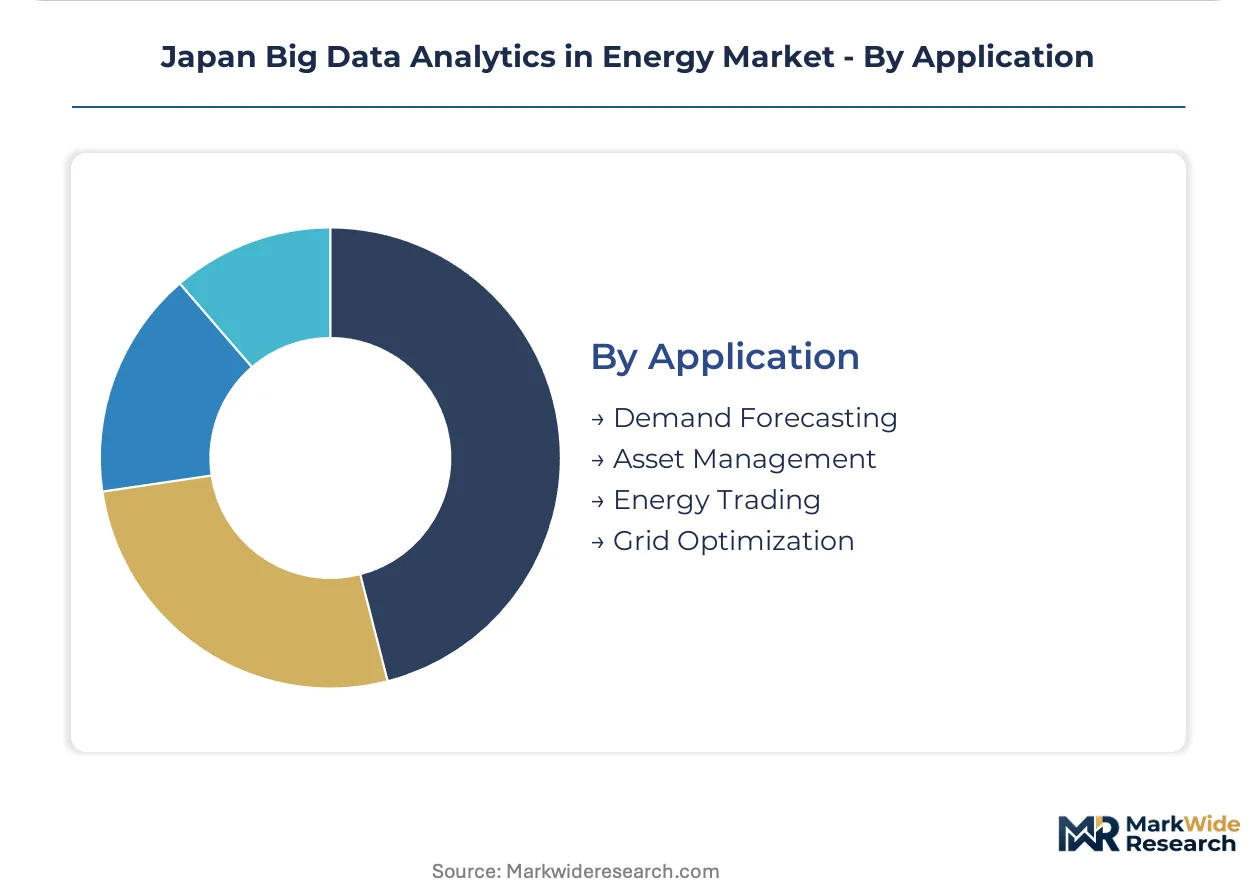
Application:
Application maturity correlates directly with infrastructure age, with grid optimization leading deployment velocity while energy trading analytics lag in liberalized market development.
- Grid Optimization:Real-time analytics deployment concentrates in Tokyo metropolitan load centers where aging infrastructure strains under renewable intermittency, forcing sub-second inference capabilities that fragment generation control necessitates edge computing architectures.
- Asset Management:Digital twin technology collapses cost structures for transformer health prediction, with physics-informed neural networks enabling condition-based maintenance across Tepco and Chubu Electric transmission networks.
- Demand Forecasting:Short-term load prediction for dispatch scheduling in deregulated power markets.
- Energy Trading:Price forecasting and risk analytics for emerging electricity market participants.
Grid Optimization holds the deepest deployment base. Asset Management is gaining share fastest as capital efficiency pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's energy analytics trade flows reflect concentrated domestic capability rather than import dependency, with technology development and deployment capacity concentrated in specific sub-regional clusters shaped by grid infrastructure age and industrial load density.
Kanto/Tokyo
Tokyo Electric Power Company anchors demand for sub-second inference platforms as renewable intermittency strains the capital region's aging transmission network. METI's Green Transformation initiative mandates digital infrastructure upgrades across this load center. Smart meter penetration exceeds national averages in the metropolitan belt, generating petabyte-scale time-series data for machine learning training.
Kansai/Osaka
Osaka-Kobe manufacturing belt demand for industrial load disaggregation analytics remains underpenetrated despite steel and chemical producers seeking carbon accounting visibility. Chubu Electric Power deploys physics-informed neural networks for transformer health prediction across its transmission footprint. The industrial corridor's distributed solar proliferation necessitates edge analytics for voltage regulation beyond centralized control architectures.
Chubu/Nagoya
Automotive and precision manufacturing clusters drive demand for granular consumption visibility tied to production scheduling optimization. Regional grid operators favor subscription pricing models that transfer algorithm performance risk to vendors. JIS certification requirements for industrial IoT interoperability shape procurement specifications and vendor qualification timelines.
Kyushu
Planned offshore wind projects in surrounding waters require marine-environment predictive models absent from current vendor portfolios. Kyushu Electric Power faces peak complexity from distributed energy resource proliferation beyond legacy SCADA response capabilities. METI data sovereignty requirements favor domestic hyperscale deployments over foreign cloud platforms for transmission control systems.
Hokkaido
Isolated grid architecture intensifies demand for autonomous voltage regulation as renewable penetration accelerates. Hokkaido Electric Power favors operational expenditure models for analytics software, displacing perpetual licensing structures. Cold climate conditions impose unique asset degradation patterns requiring specialized predictive maintenance training data.
Japan Big Data Analytics in Energy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the analytics stack. The vendor base stratifies between industrial automation heritage players with balance-sheet scale and domestic system integrators with regulatory relationship depth. Three archetypes dominate: multinational technology conglomerates with cloud infrastructure, industrial equipment manufacturers with utility relationships, and specialized domestic integrators with JIS certification pathways. Competitive moves concentrate on strategic partnerships for edge computing deployment and portfolio diversification into digital twin capabilities.
Within the multinational technology tier, Microsoft Corporation and Siemens Aktiengesellschaft exemplify divergent entry strategies, with cloud-native platforms competing against industrial automation heritage. NEC Corporation and Hitachi occupy positions as domestic anchors, leveraging deep relationships with Tokyo Electric Power and regional grid operators. IBM represents the services-integrated archetype, sitting between platform and consulting layers. These named entities collectively illustrate how METI's cybersecurity directives and data sovereignty requirements shape vendor qualification criteria and procurement committee weighting.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| SAP SE |
| Microsoft Corporation |
| Siemens Aktiengesellschaft |
| Accenture plc |
| NEC Corporation |
| Hitachi |
| Fujitsu |
| Toshiba |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic cloud infrastructure tilts procurement leverage toward vendors with localized data center footprints, compressing margins for foreign platform providers while inflating premiums for METI-compliant domestic deployments.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures across the analytics stack. Three-tier pricing stratifies across enterprise-grade predictive maintenance platforms, mid-market grid optimization modules, and entry-level visualization tools. Price differentiation hinges on JIS certification tier and algorithmic inference latency specifications. Cost compression in mid-tier software is intensifying because regional utilities favor operational expenditure models that transfer performance risk to vendors. Mid-tier regional operators exhibit highest price sensitivity; Tokyo Electric Power and Chubu Electric demonstrate lowest sensitivity due to mission-critical deployment requirements.
Supply Chain Analysis
Export control restrictions on GPU accelerators and advanced semiconductor manufacturing equipment limit flows of training hardware into Japanese data centers. Supply concentrates in Taiwan for foundry capacity, the United States for AI chip design, and domestic facilities for final system integration. The technology stack draws from specialized time-series databases, physics simulation engines, and edge computing hardware. Single-source vulnerability around NVIDIA GPU supply creates procurement bottlenecks for training-intensive workloads. Distribution runs through domestic system integrators with METI cybersecurity clearance rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors that control scarce power systems engineering talent with machine learning fluency, while penalizing pure-play software providers lacking utility operational credibility.
For Market Incumbents: Harden defensive positions through backward integration into edge computing hardware production, capturing margin pools currently flowing to semiconductor vendors. Deepen certification moats by accelerating JIS compliance timelines for industrial IoT interoperability. Lock in regional utility relationships via outcome-based pricing structures that cement switching costs. For New Entrants and Emerging Players: Pursue white-space opportunity in offshore wind predictive analytics for Kyushu and Hokkaido projects, where marine-environment modeling capabilities remain absent from incumbent portfolios. Target industrial load disaggregation analytics across the Osaka-Kobe manufacturing belt. Lead with carbon accounting compliance narratives that resonate with steel and chemical producers facing Scope 2 reporting pressures. For Investors and Strategic Acquirers: Capital is best deployed toward domestic system integrators with established METI regulatory relationships and JIS certification pathways. Long-term viability favors vendors that combine algorithmic IP with utility operational credibility rather than pure software plays. Watch for inflection signals around offshore wind procurement timelines and Green Transformation mandate enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Localization | Domestic production of inference accelerators satisfies METI data sovereignty requirements for transmission control systems. |
| Physics-Informed Neural Network Development | Digital twin fidelity for transformer health prediction shrinks capital reserve requirements at Tepco and Chubu Electric. |
| JIS Certification Fast-Track Investment | Compressed six-to-twelve month procurement timelines unlock regional utility contracts currently blocked by interoperability standards. |
| Offshore Wind Analytics Partnership | Marine-environment predictive models address capability gaps for Kyushu and Hokkaido project developers. |
| Cross-Sector Data Fusion Platform | Utility-telecom integration under Society 5.0 protocols enables demand response optimization in Tokyo metropolitan load centers. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, grid operators, EPC contractors, and system integration specialists and refined through secondary validation. Primary fieldwork encompassed structured interviews with procurement committees at Tokyo Electric Power, Chubu Electric, and regional utilities alongside technology vendors and domestic system integrators. Secondary sources included METI policy filings, Agency for Natural Resources and Energy cybersecurity directives, JIS standard documentation, and project development databases tracking smart grid infrastructure investments. Bottom-up demand aggregation across utility deployment pipelines was triangulated against top-down market sizing from technology stack component flows.
Demand-supply balance modeling anchored the quantitative framework across the analysis window. Segmentation dimensions encompassed service type, technology layer, end-user sophistication, and application maturity alongside regional grid infrastructure age and renewable penetration rates. CAGRs were derived from utility capital expenditure trajectories under Green Transformation mandates and algorithm deployment velocity curves. Forecast inputs incorporated smart meter penetration timelines, distributed energy resource proliferation rates, and offshore wind project development pipelines.
Macroeconomic conditions sit as an overlay; deviation in yen-denominated technology import costs or domestic construction labor availability would shift the trajectory. Forecasts reflect documented assumptions around METI enforcement consistency and JIS standard evolution timelines. Material shifts in cybersecurity directive stringency or data sovereignty requirement scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Power System Analysis Software Market