
 Box Sealing Machines Market | 2026-2036
Box Sealing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Box Sealing Machines Market Outlook
Remote diagnostics and predictive maintenance subscriptions is broadening what box sealing machine vendors actually monetize. 3M Company leverages its adhesive science heritage to bundle tape supply with equipment uptime guarantees. Lantech, Inc. anchors its position through stretch-wrap-to-seal integration that locks in packaging line contracts. SIAT S.p.A. competes on European aftermarket density, sustaining margin pools through rapid technician dispatch networks.
Box sealing machines are electromechanical systems that apply adhesive tape, hot melt glue, or pressure-sensitive materials to close corrugated cases at speeds ranging from 5 to 150 cases per minute depending on automation tier. Their primary commercial purpose is to secure goods for palletization, transport, and automated warehouse handling while maintaining case integrity through distribution shocks. Automatic systems now dominate capital expenditure flows as e-commerce order profiles demand throughput above 30 cases per minute with minimal changeover downtime. Tape seal technology leads installed base economics due to lower energy demand and simpler maintenance, though glue seal configurations are gaining share in food and beverage applications where hermetic closure meets sanitation protocols.
OSHA machine guarding standards in the United States and the EU Machinery Directive's safety integrity requirements shape automatic system design, forcing redundant light curtains and interlocked access panels that add cost but unlock industrial end-user procurement. The EU Green Deal's packaging and packaging waste regulation is concentrating OEM engineering resources on machines compatible with paper-based and recyclable sealing media. Stakeholders must monitor how quickly adhesive formulations and tape substrates can certify under emerging recyclability frameworks without degrading seal strength under humidity and load stress.
Market Dynamics
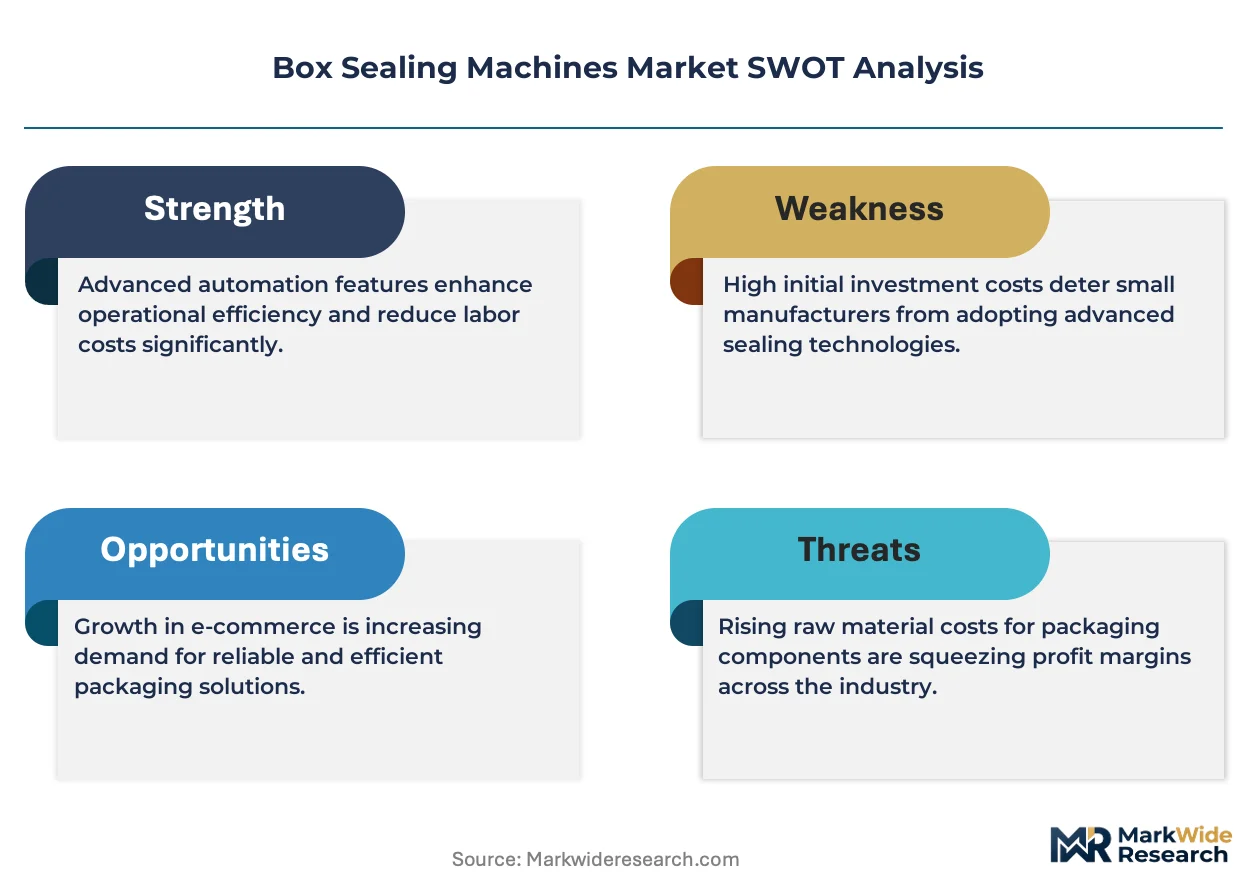
EU Green Deal packaging waste directives are forcing OEMs to redesign machines for recyclable tape compatibility while e-commerce fulfillment centers expand automated sealing lines to offset climbing labor costs.
Growth Catalysts
- E-commerce fulfillment automation:Third-party logistics operators in the United States are deploying high-throughput automatic systems to process order volumes exceeding 30 cases per minute with minimal changeover downtime.
- REACH-compliant adhesive formulations:European tape manufacturers are certifying paper-based sealing media under emerging recyclability frameworks without degrading seal strength under humidity stress.
- Automotive parts export packaging:German manufacturers require hermetic closure systems for precision components shipped across extended distribution networks.
Market Restraints
- Steel and aluminum input volatility:Frame and conveyor component costs fluctuate with commodity pricing, compressing margins for mid-tier equipment builders.
- Safety system mandates:OSHA machine guarding standards and the EU Machinery Directive force redundant light curtains and interlocked access panels that add 8-12% to system cost.
- Glue seal energy intensity:Hot melt adhesive systems consume 3-4x the electricity of tape configurations, limiting adoption outside food and beverage sanitation protocols.
Strategic Opportunities
- Predictive maintenance subscriptions:Remote diagnostics platforms allow vendors to monetize uptime guarantees rather than one-time equipment sales.
- India warehousing buildout:PLI scheme incentives for logistics infrastructure are creating first-mover advantage for automatic system suppliers in Mumbai and Delhi NCR fulfillment clusters.
- Stretch-wrap-to-seal integration:Converging palletization and case sealing into single-line contracts locks in multi-year packaging line agreements.
Industry Challenges
- Electromechanical technician scarcity:Maintenance networks struggle to dispatch qualified personnel for servo-driven automatic system repairs within guaranteed response windows.
- Legacy PLC integration friction:Brownfield facilities running 1990s-era controls face protocol incompatibility when retrofitting Industry 4.0 connectivity modules.
- Recyclability certification timelines:Paper-based tape substrates require 18-24 month validation cycles under emerging EU frameworks before OEMs can guarantee machine compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box Sealing Machines Market |
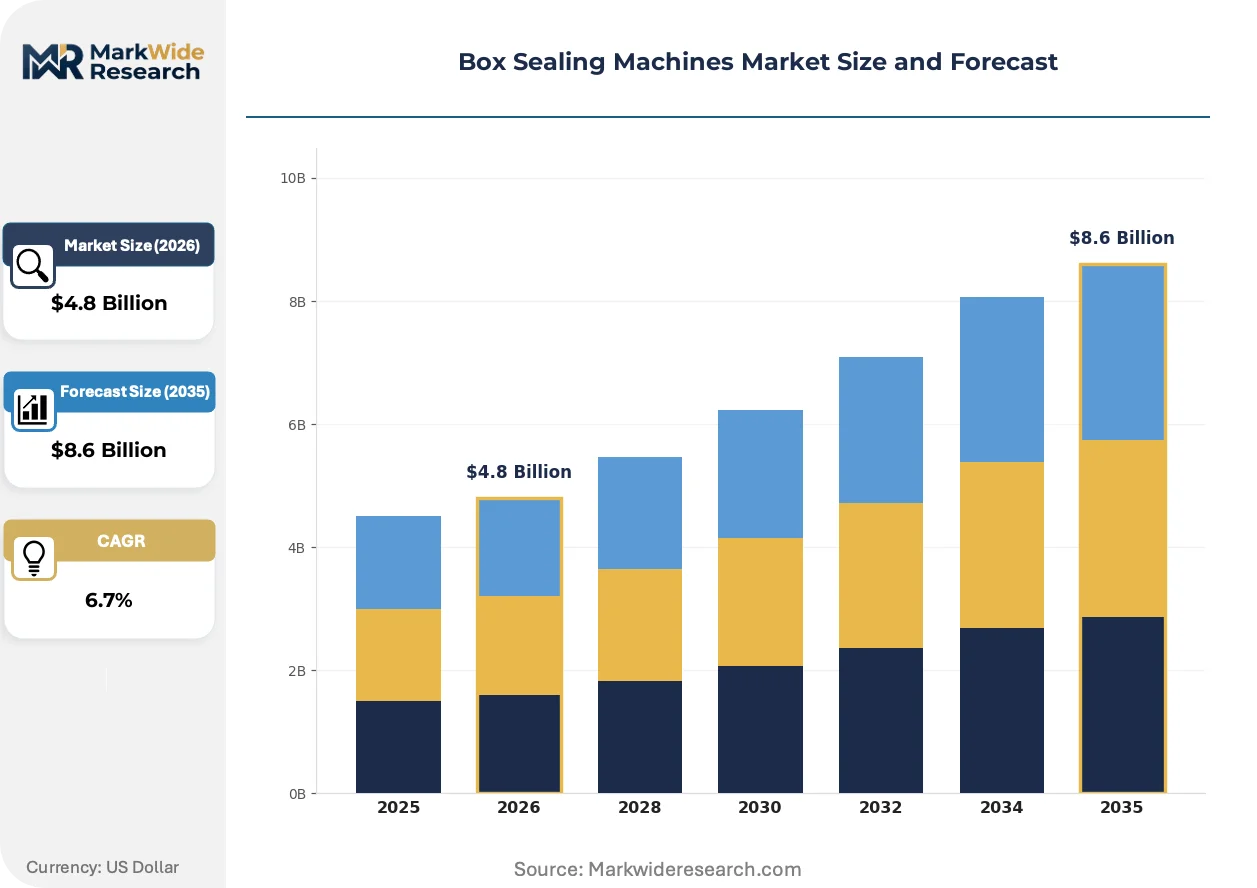
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Industrial Application: Packaging, Food & Beverage, Consumer Goods, Pharmaceuticals Technology: Heat Seal, Pressure Sensitive, Tape Seal, Glue Seal End User: Manufacturers, Distributors, Retailers, E-Commerce |
| Companies Covered | 3M Company, Intertape Polymer Group, Wexxar Bel, Lantech, Inc., SIAT S.p.A., Combi Packaging Systems LLC, Robopac, EndFlex, KOCH Pac-Systeme GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box Sealing Machines Market Strategic Shifts
Adhesive science advances and connectivity architectures are compressing the traditional boundary between equipment sale and ongoing service monetization in case sealing operations.
Vision-guided tape application systems are rewriting throughput economics for variable case sizes. E-commerce fulfillment centers in Germany and the United States are deploying camera-array alignment to eliminate manual changeover. This technology is compressing labor requirements per line while enabling mixed-SKU batch processing that was previously uneconomical.
The EU Green Deal's packaging and packaging waste regulation is redirecting R&D expenditure toward paper-based sealing media compatibility. OEM engineering teams must validate tape path geometries for fiber substrates that lack the tensile consistency of polypropylene. Food and beverage exporters in France and Italy face the tightest compliance deadlines for transitioning away from plastic-backed tapes.
Outcome-based service contracts are displacing traditional break-fix maintenance arrangements. Large retail distribution centers in the United Kingdom now specify availability-based pricing where vendors absorb downtime risk. This shift concentrates procurement authority among national account teams rather than regional plant engineers.
Box Sealing Machines Market Segmentation
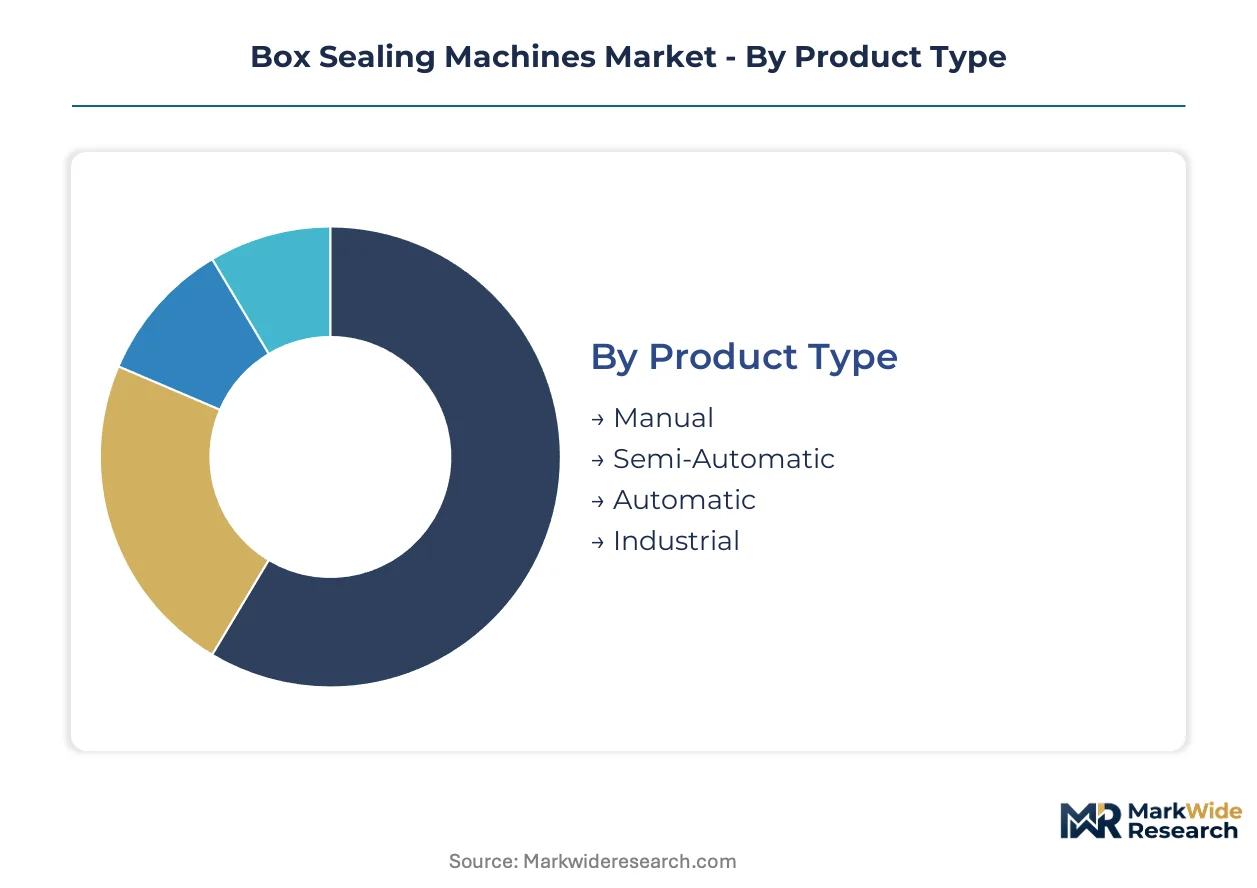
Box sealing machine purchasing decisions split sharply between standalone equipment for low-volume operations and integrated systems embedded within automated packaging lines. Equipment specification varies dramatically across end-use intensity, regulatory exposure, and throughput requirements.
Product Type:
Standalone manual units serve intermittent sealing needs while automatic and industrial configurations embed within continuous-flow packaging architectures.
- Manual:Hand-operated lever systems apply tape through mechanical feed mechanisms without electrical power. Small-batch manufacturers in India and Southeast Asia deploy these for seasonal production spikes where capital constraints block automation investment.
- Semi-Automatic:Motorized tape feed with operator-present case handling bridges intermittent and continuous operation modes. Mid-tier contract packagers in Germany favor this tier for mixed-SKU campaigns where full automation cannot amortize changeover complexity.
- Automatic:Conveyor-fed systems with programmable case sizing process 30-80 cases per minute without operator intervention. E-commerce fulfillment centers in the United States concentrate procurement here to offset warehouse labor cost inflation.
- Industrial:Heavy-gantry systems rated for 24/7 operation exceed 150 cases per minute with servo-driven precision. Automotive parts exporters in Germany require this tier for hermetic closure of precision components in extended distribution networks.
Automatic equipment leads volumes today; Industrial systems are gaining share fastest.
Application:
Regulatory exposure and contamination risk create divergent equipment specifications across end-use verticals.
- Packaging:General-purpose corrugated sealing spans contract packagers, third-party logistics operators, and industrial manufacturers with minimal product-specific constraints. German automotive suppliers drive specification intensity here for export-grade case integrity.
- Food & Beverage:Hermetic closure requirements and sanitation protocols demand stainless steel construction, washdown compatibility, and FDA or EFSA compliance documentation. Hot melt glue seal configurations dominate this vertical for tamper-evident hermetic seals.
- Consumer Goods:High-graphics retail presentation requires precise tape placement to avoid obscuring branding. Vision-guided alignment systems from United States and German vendors concentrate in this segment for cosmetic sealing standards.
- Pharmaceuticals:Lot tracking, serialization integration, and cGMP validation requirements add 40-60% equipment cost premiums. European manufacturers face the tightest compliance deadlines under EU MDR and Falsified Medicines Directive serialization mandates.
Packaging commands the largest installed base; Pharmaceuticals shows the steepest specification escalation.
Technology:
Energy intensity and consumables economics separate tape-based from adhesive-based sealing architectures.
- Heat Seal:Thermal welding of polymer films creates permanent closure for moisture-sensitive products. Medical device manufacturers in the United States specify this technology for sterile barrier packaging where reclosure is unnecessary.
- Pressure Sensitive:Self-adhesive tapes activate under mechanical pressure without thermal or chemical curing. This technology dominates e-commerce operations for energy efficiency and immediate handling strength.
- Tape Seal:Polypropylene or paper-based tapes applied through mechanical rollers represent the lowest total cost of ownership configuration. EU Green Deal recyclability mandates are accelerating paper tape validation cycles for this segment.
- Glue Seal:Hot melt adhesive systems deliver tamper-evident hermetic closure at 3-4x the energy consumption of tape alternatives. Food and beverage applications in France and Italy absorb this cost for sanitation protocol compliance.
Tape Seal retains the broadest installed footprint; Pressure Sensitive configurations are climbing fastest on e-commerce demand.
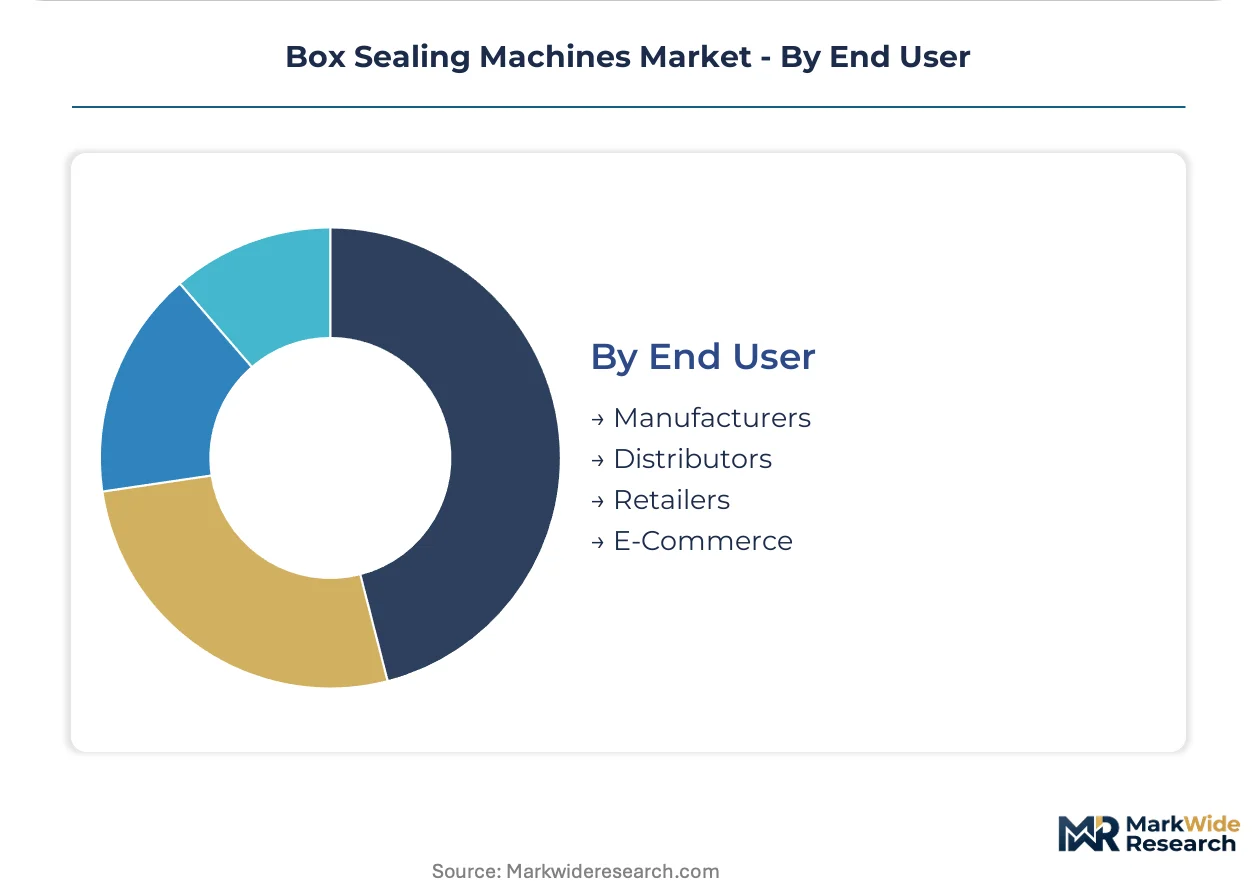
End User:
Procurement authority and service contracting models diverge sharply between production-integrated and distribution-centric buyers.
- Manufacturers:In-house packaging lines specify equipment for 10-15 year depreciation cycles with OEM service contracts. German automotive and industrial producers anchor this segment with availability-based pricing arrangements.
- Distributors:Third-party logistics operators prioritize throughput flexibility and rapid changeover across client portfolios. United States 3PLs are consolidating procurement authority at national account level for volume leverage.
- Retailers:Store-backroom and fulfillment center operations demand compact footprints with minimal skilled maintenance requirements. Large United Kingdom retail chains now specify outcome-based contracts where vendors absorb downtime risk.
- E-Commerce:Pure-play online retailers and marketplace fulfillment operations drive the fastest automation adoption for variable case size handling. Mumbai and Delhi NCR clusters in India represent emerging demand concentration for automatic system suppliers.
Manufacturers still account for the largest equipment fleet; E-Commerce is expanding most quickly on fulfillment automation buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates industrial-grade demand for hermetic closure systems, while the United States drives e-commerce automation adoption at scale. India and China are expanding fulfillment infrastructure, with European regulatory pressure reshaping equipment specifications across multiple jurisdictions.
United States
Third-party logistics operators deploy high-throughput automatic systems to process order volumes exceeding 30 cases per minute. OSHA machine guarding standards mandate redundant light curtains and interlocked access panels that add 8-12% to system cost. Chicago and Dallas fulfillment clusters concentrate procurement authority at national account level for volume leverage.
Germany
Automotive parts exporters require hermetic closure systems for precision components shipped across extended distribution networks. The EU Machinery Directive's safety integrity requirements shape automatic system design for industrial end-users. Stuttgart and Munich industrial corridors anchor specification intensity for export-grade case integrity.
China
E-commerce fulfillment centers expand automated sealing lines to offset warehouse labor cost inflation. GB standards and MIIT industrial equipment regulations govern safety certification for automatic systems. Yangtze River Delta logistics clusters in Shanghai and Suzhou represent emerging demand concentration for servo-driven precision equipment.
India
PLI scheme incentives for logistics infrastructure create first-mover advantage for automatic system suppliers. BIS certification requirements shape equipment specifications for industrial packaging applications. Mumbai and Delhi NCR fulfillment clusters drive fastest automation adoption for variable case size handling.
United Kingdom
Large retail distribution centers specify outcome-based contracts where vendors absorb downtime risk. REACH-compliant adhesive formulations from European tape manufacturers certify paper-based sealing media under emerging recyclability frameworks. Midlands logistics corridors concentrate procurement for availability-based pricing arrangements.
Box Sealing Machines Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with adhesive science heritage conferring bundling advantages in consumables-integrated models. The vendor base concentrates around three strategic archetypes: multinational materials conglomerates leveraging tape supply relationships, European precision engineering houses anchoring aftermarket density, and integrated packaging line contractors locking in multi-year agreements. Competitive moves center on predictive maintenance subscription rollouts and stretch-wrap-to-seal integration that converges palletization and case sealing workflows.
Within the multinational tier, 3M Company represents the materials science conglomerate archetype, while Lantech, Inc. and SIAT S.p.A. exemplify contrasting regional positioning strategies. Lantech anchors North American packaging line integration through stretch-wrap convergence, and SIAT occupies a position defined by European aftermarket density and rapid technician dispatch networks. These three players illustrate how adhesive heritage, line integration, and service geography respectively structure competitive differentiation in automatic sealing equipment.
| Leading Market Players |
|---|
| 3M Company |
| Intertape Polymer Group |
| Wexxar Bel |
| Lantech, Inc. |
| SIAT S.p.A. |
| Combi Packaging Systems LLC |
| Robopac |
| EndFlex |
| KOCH Pac-Systeme GmbH |
| Others |
Value Chain & Pricing Dynamics
Electromechanical technician concentration in Germany's Stuttgart industrial corridor widens pricing-tier spreads between premium automatic systems and economy manual configurations, as labor-cost differentials compound with safety-system mandates to stratify procurement budgets.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mid-tier automatic equipment, compressing margins for European precision engineering houses. Three-tier pricing structure across premium servo-driven, standard conveyor-fed, and economy lever-operated levels separates availability-guaranteed industrial systems from capital-constrained seasonal operators. Price differentiation hinges on CE certification tier and after-sales bundling intensity. Cost compression in manual equipment intensifies because of steel input volatility, while e-commerce fulfillment centers show lowest price sensitivity due to labor-offset calculations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese servo motor suppliers, exposing European OEMs to logistics chokepoint risk. Manufacturing concentrates in Germany, China, and the United States, with frame fabrication drawing from regional steel mills and control electronics sourcing from Taiwan and South Korea. Tape substrate supply rests on petrochemical feedstock flows from the Middle East and Southeast Asia. Distribution runs through packaging line integrators who bundle sealing equipment with stretch-wrap and palletizing modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with EU Green Deal recyclability mandates shifting procurement authority toward OEMs certifying paper-based tape compatibility.
For Market Incumbents: Extend predictive maintenance subscription penetration to lock in multi-year revenue streams against emerging Chinese equipment builders. Deepen backward integration into adhesive formulation partnerships to defend consumables attachment rates. Prioritize rapid technician dispatch network density in Germany and the United States where availability-based pricing concentrates. For New Entrants and Emerging Players: Direct-to-market digital channels bypass incumbent distributor relationships in India's Mumbai and Delhi NCR fulfillment clusters. Target semi-automatic equipment tier for mid-tier contract packagers in Germany facing mixed-SKU campaign complexity. Lead with vision-guided changeover elimination as the go-to-market wedge against legacy manual-changeover installed base. For Investors and Strategic Acquirers: Materials science conglomerates with adhesive heritage are the most active acquirer in this space, consolidating tape supply and equipment bundling capabilities. Long-term viability favors targets with installed base density enabling aftermarket service monetization. Watch EU recyclability certification timelines as the inflection signal for paper-based tape substrate validation.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Rollout | Transforms one-time equipment sales into recurring uptime-guarantee revenue for German automotive suppliers. |
| Stretch-Wrap-to-Seal Integration | Locks in multi-year packaging line contracts by converging palletization and case sealing workflows. |
| Paper-Based Tape Compatibility Investment | Positions OEMs for EU Green Deal compliance deadlines facing French and Italian food exporters. |
| Servo-Driven Precision Capacity Addition | Captures specification escalation in pharmaceutical serialization integration under EU MDR mandates. |
| India Fulfillment Cluster Market Entry | Exploits PLI scheme incentives creating first-mover advantage in Mumbai and Delhi NCR automation buildouts. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with packaging line engineers, maintenance directors at e-commerce fulfillment centers, OEM procurement teams, and aftermarket service heads with secondary validation. Data draws from SEC filings of listed packaging equipment manufacturers, EU Machinery Directive certification databases, customs trade records for corrugated machinery, and industrial equipment shipment statistics. Bottom-up equipment unit estimates triangulate against top-down end-use industry demand models.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. Segmentation dimensions modeled include automation tier, sealing technology architecture, end-use vertical intensity, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and fulfillment center automation penetration curves. Forecast inputs incorporate EU Green Deal implementation pace and e-commerce order profile evolution.
The model assumes a particular technology adoption path; alternative pathways for vision-guided mixed-SKU handling would alter the outlook. Forecasts reflect assumptions about recyclability certification timelines and labor cost inflation persistence that specific regulatory delays or automation breakthroughs could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Europe Blow Molding Machine Market
Packaging Machinery
Tamper Evidence Machinery Market