
 High-End Chinese Spirits Market | 2026-2036
High-End Chinese Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Chinese Spirits Market Insights
GB/T 10781.1, the national standard for strong-aroma baijiu, is redrawing competitive boundaries by mandating specific sorghum fermentation periods and distillation rounds. Kweichow Moutai leverages its Kweichow origin certification to command premium positioning. Wuliangye anchors the strong-aroma segment through controlled multi-grain fermentation at scale. Luzhou Laojiao differentiates via its state-protected cellar pits, some dating to the Ming dynasty.
High-end Chinese spirits denote grain-distilled alcoholic beverages, primarily baijiu, produced through solid-state fermentation with daqu starter cultures and aged in ceramic vessels for minimum periods spanning years to decades. These products serve ceremonial, investment, and prestige consumption functions across corporate gifting, banqueting, and private collection contexts. Baijiu dominates value capture within product type segmentation, while the collector customer type commands the highest per-unit margins and drives limited-edition release cycles. Specialty stores and duty-free shops together concentrate distribution value, though online retail is accelerating fastest among channels for verified vintage transactions.
SAMR enforces labeling and anti-counterfeiting provisions that shape packaging investments, while GB standards administered by the national standardization body define permissible raw materials and aging claims. China's dual carbon goals are pressuring distilleries to retrofit coal-fired steam systems, altering capital allocation across the production base. Stakeholders must monitor regulatory tightening on gift-giving practices and carbon intensity benchmarks as these forces reshape both demand patterns and production economics.
Market Dynamics
GB standards and SAMR labeling mandates are compressing production timelines while elevating quality thresholds, forcing distilleries to reconfigure fermentation infrastructure and authentication systems simultaneously.
Growth Catalysts
- Dual carbon goals:MEE emissions benchmarks are accelerating coal-to-biomass retrofits in Sichuan and Guizhou, unlocking green financing for cellar modernization.
- Collector networks:Yangtze River Delta private clubs are institutionalizing verified vintage trading, creating liquidity for aged inventory.
- Solid-state automation:Robotic daqu handling systems are reducing contamination risk while preserving traditional fermentation kinetics.
Market Restraints
- Sorghum price volatility:Red sorghum procurement costs fluctuate with Heilongjiang harvest yields, squeezing margin predictability.
- Cellar pit scarcity:Ming-dynasty fermentation pits are non-replicable heritage assets concentrated in Luzhou.
- GB/T compliance timelines:Extended aging verification periods delay new product launches by 18-24 months.
Strategic Opportunities
- Duty-free channel expansion:Hainan Free Trade Port policies are enabling tax-advantaged vintage releases for outbound Chinese travelers.
- Blockchain authentication:Distributed ledger integration with ceramic vessel provenance is miniaturizing counterfeiting windows.
- Corporate treasury allocation:Investment-grade baijiu is displacing traditional store-of-value assets in Guangdong family offices.
Industry Challenges
- Master blender succession:State-certified technicians require 15-year apprenticeships, constraining production scaling.
- Cross-border logistics:Ceramic vessel fragility and temperature sensitivity complicate direct-to-collector shipping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Chinese Spirits Market |
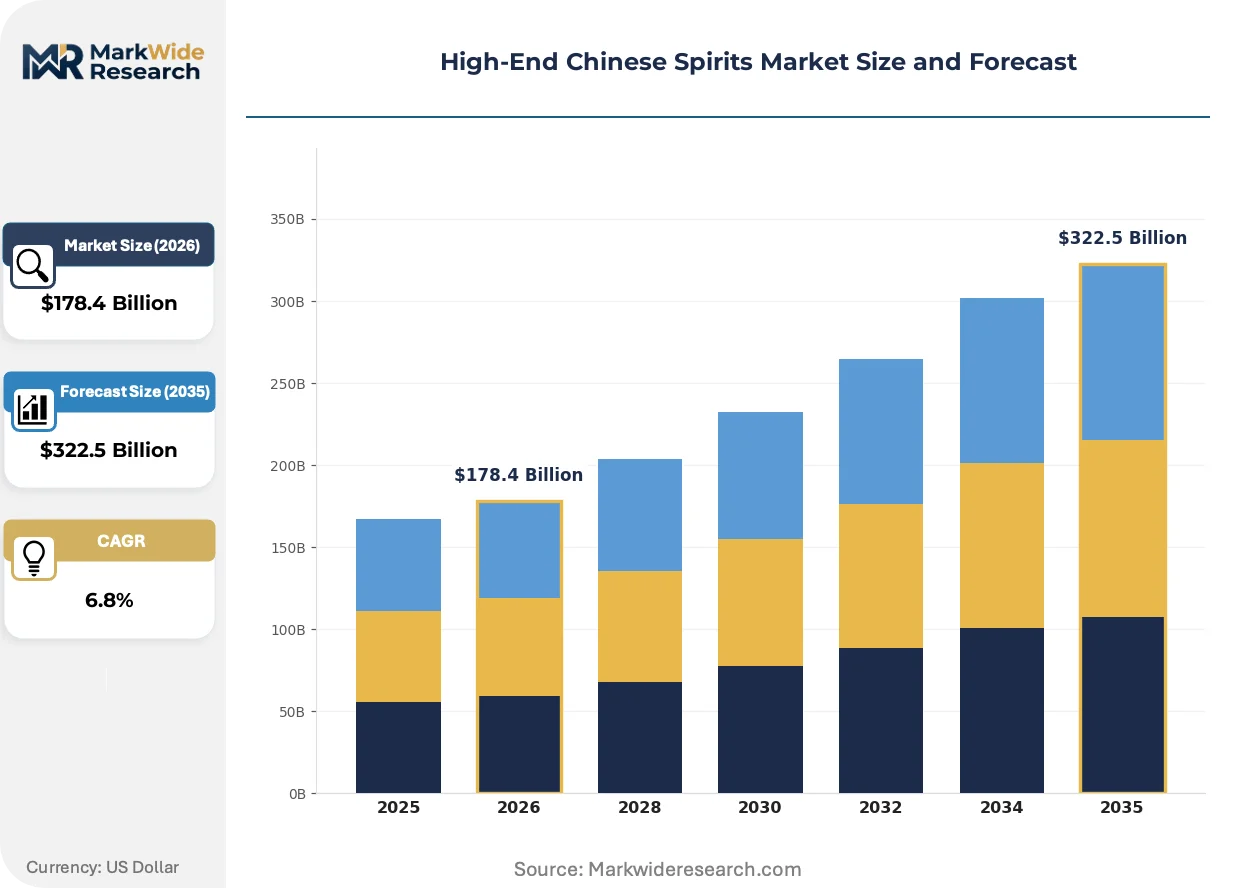
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $322.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baijiu, Huangjiu, Mijiu, Wine Customer Type: Affluent Consumers, Collectors, Hospitality Industry, Retailers Distribution Channel: Online Retail, Specialty Stores, Duty-Free Shops, Supermarkets Packaging Type: Glass Bottles, Ceramic Jars, Tins, Gift Boxes |
| Companies Covered | Kweichow Moutai, Wuliangye, Luzhou Laojiao, Yanghe, Langjiu, Gujing Group, Shede, Jiangxian Liquor Company, Kou Zi Jiu Ye, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Chinese Spirits Market Trends and Innovations
Digital authentication and precision fermentation are converging with heritage production methods, creating tension between scalability and terroir preservation that defines competitive differentiation.
Near-infrared spectroscopy is miniaturizing quality verification. Collector networks in Shanghai deploy handheld devices for real-time ethanol congener analysis. This technology is compressing authentication from laboratory timelines to point-of-sale seconds.
SAMR anti-counterfeiting provisions now mandate traceable packaging layers. Distilleries must integrate holographic seals with batch-specific QR codes. The strong-aroma segment bears the heaviest compliance burden due to higher counterfeiting incidence.
Direct-to-collector platforms are displacing traditional auction houses for verified vintage transactions. Specialty stores in Beijing and Shenzhen now offer digital custody certificates alongside physical cellar storage. This channel shift concentrates highest-margin sales within domestic private networks rather than export markets.
High-End Chinese Spirits Market Segmentation
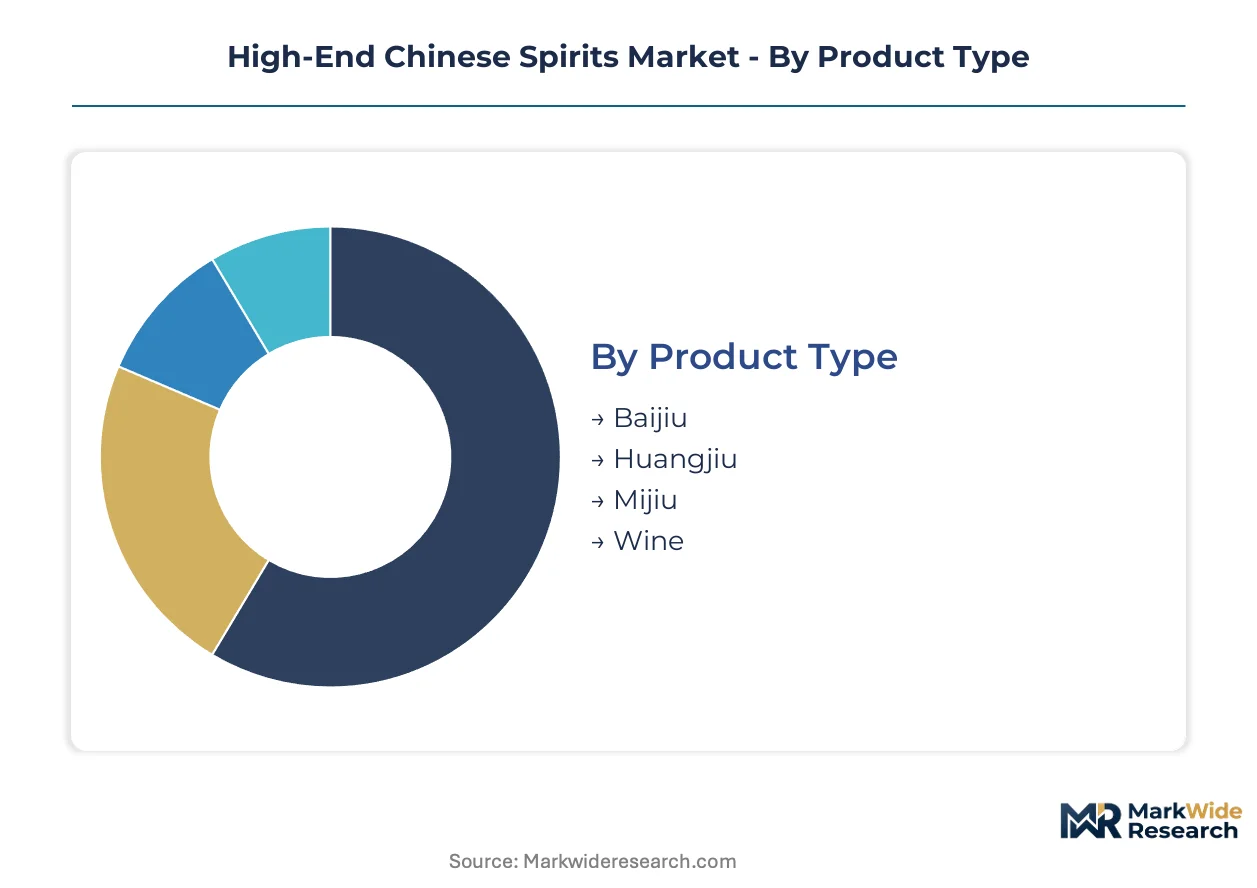
Segmentation in high-end Chinese spirits reveals distinct margin profiles and channel requirements across production methods and buyer motivations. Grain fermentation techniques and aging protocols create irreplicable product differentiation that shapes competitive boundaries.
Product Type:
Domestic consumption concentrates in sorghum-based categories with heritage production credentials, while export traction remains limited to diaspora communities and specialist retailers.
- Baijiu:Solid-state fermentation with daqu starter cultures produces the dominant revenue pool. Collector networks in Shanghai and Beijing drive limited-edition releases tied to verified ceramic vessel aging.
- Huangjiu:Rice-wheat fermentation yields lower-alcohol products with concentrated demand in Jiangsu and Zhejiang heritage cuisines. Restaurant procurement teams favor this category for banquet pairings requiring subtler flavor profiles.
- Mijiu:Glutinous rice fermentation serves ceremonial and cooking applications with thinner margins than aged grain spirits.
- Wine:Grape-based products occupy peripheral positioning, imported primarily for Western-influenced hospitality settings in first-tier cities.
Baijiu holds the largest share; momentum sits with Huangjiu as regional cuisine promotion expands beyond traditional strongholds.
Customer Type:
Margin concentration follows buyer sophistication, with verified provenance requirements escalating across tiers and authentication infrastructure becoming a competitive prerequisite.
- Collectors:Private clubs in the Yangtze River Delta institutionalize vintage trading with blockchain-backed custody certificates. Per-unit margins peak here due to scarcity engineering and release cycle control.
- Affluent Consumers:Corporate gifting and family celebration procurement drives volume with moderate price elasticity. GB/T compliance and SAMR labeling requirements shape purchase confidence.
- Hospitality Industry:Luxury hotel cellar programs in Shanghai and Beijing expand baijiu selections for inbound business entertainment.
- Retailers:Specialty store networks concentrate distribution value through staff-trained recommendation systems.
Collectors command premium positioning; the hospitality segment is expanding most quickly as international hotel chains localize beverage programs.
Distribution Channel:
Channel selection determines authentication burden and margin retention, with direct-to-collector platforms compressing traditional auction house intermediation.
- Specialty Stores:Staff expertise and verified provenance systems support highest-margin transactions outside direct collector relationships. Beijing and Shenzhen flagships now combine physical cellar storage with digital custody certificates.
- Duty-Free Shops:Hainan Free Trade Port policies enable tax-advantaged vintage releases targeting outbound Chinese travelers with concentrated purchasing power.
- Online Retail:Verified vintage transactions accelerate fastest here, though ceramic vessel fragility complicates logistics execution.
- Supermarkets:Mass-market positioning with limited aging claims serves entry-level experimentation and cooking-grade purchases.
Specialty stores retain margin leadership; online retail gains share fastest as authentication technology compresses trust barriers.
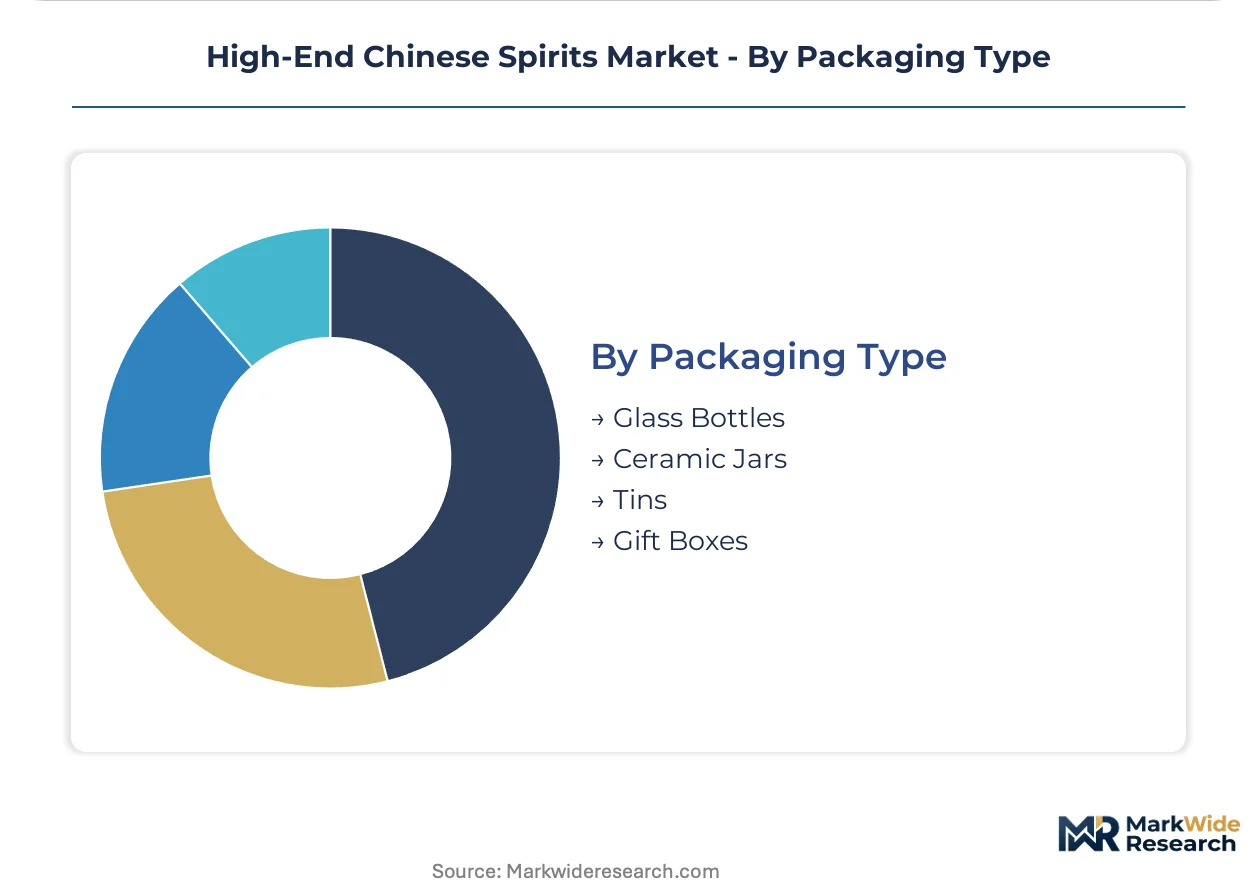
Packaging Type:
Material selection signals quality tier and shapes regulatory compliance burden, with SAMR anti-counterfeiting mandates driving layered traceability investments.
- Ceramic Jars:Traditional vessel material enables controlled micro-oxidation during extended aging. Ming-dynasty cellar pit associations in Luzhou Laojiao's heritage sites reinforce terroir credibility.
- Glass Bottles:Dominant format for commercial scale with holographic seal and QR code integration meeting SAMR batch traceability requirements.
- Gift Boxes:Multi-unit ceremonial packaging concentrates corporate gifting value with premium finishing and authentication documentation.
- Tins:Secondary protective packaging for ceramic vessels in transit, rarely constituting primary consumer-facing material.
Ceramic jars anchor prestige positioning; gift boxes climb the fastest as corporate treasury allocation to investment-grade baijiu expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual carbon goals under MEE emissions benchmarks are redirecting distillery capital toward biomass retrofits in Sichuan and Guizhou, while SAMR labeling mandates reshape authentication infrastructure nationwide. Collector networks in the Yangtze River Delta and Pearl River Delta institutionalize verified vintage trading with blockchain custody certificates.
Guizhou
Kweichow origin certification commands premium positioning through protected geographical indication status. GB standards administered by the national standardization body define sorghum fermentation periods and distillation rounds for strong-aroma categories. Maotai town distillery clusters concentrate heritage production assets, with MEE coal-to-biomass retrofits unlocking green financing for cellar modernization programs.
Sichuan
Yibin and Luzhou anchor the strong-aroma segment through controlled multi-grain fermentation at scale. SAMR anti-counterfeiting provisions mandate traceable packaging layers with holographic seals and batch-specific QR codes. Luzhou Laojiao leverages state-protected Ming-dynasty cellar pits as non-replicable heritage assets, creating irreplicable terroir credibility for aged inventory releases.
Jiangsu
Yanghe's production base serves affluent consumer demand across corporate gifting and family celebration procurement channels. GB/T 10781.1 compliance timelines extend aging verification periods, delaying new product launches by 18-24 months. Suqian distillery facilities integrate robotic daqu handling systems that reduce contamination risk while preserving traditional fermentation kinetics.
Beijing
Luxury hospitality procurement teams expand baijiu cellar programs for inbound business entertainment. SAMR enforces labeling and anti-counterfeiting provisions that shape packaging investments across premium tiers. Specialty store flagships in Chaoyang and Haidian districts combine physical cellar storage with digital custody certificates for direct-to-collector transactions.
Shanghai
Private clubs in Pudong and Xuhui institutionalize verified vintage trading with near-infrared spectroscopy authentication. Collector networks drive limited-edition release cycles with per-unit margins peaking on scarcity engineering. Duty-free channel expansion through Hainan Free Trade Port policies enables tax-advantaged vintage releases targeting outbound Chinese travelers with concentrated purchasing power.
High-End Chinese Spirits Market Competitive Landscape
Listed leaders compete with private specialists across authentication infrastructure and heritage production credentials. The market structures around state-owned enterprises with protected geographical indications, private distilleries with Ming-dynasty cellar assets, and emerging specialists in precision fermentation technology. Three archetypes dominate: origin-certified heritage producers, multi-grain scale operators, and technology-integrated craft specialists. Competitive moves concentrate on M&A for cellar pit access and strategic partnerships for blockchain provenance systems.
Within the heritage producer tier, Kweichow Moutai and Luzhou Laojiao exemplify origin-certified positioning through protected geographical indications and state-protected fermentation assets. Wuliangye occupies a position among multi-grain scale operators with controlled fermentation at volume. These three companies represent the competitive anchors that define quality tier boundaries and authentication infrastructure investments across the market.
| Leading Market Players |
|---|
| Kweichow Moutai |
| Wuliangye |
| Luzhou Laojiao |
| Yanghe |
| Langjiu |
| Gujing Group |
| Shede |
| Jiangxian Liquor Company |
| Kou Zi Jiu Ye |
| Others |
Pricing and Supply Chain Analysis
Red sorghum substitution for multi-grain blends is compressing input cost structures in Sichuan while elevating Guizhou's single-origin premium positioning, redrawing procurement geography and margin architecture across fermentation bases.
Pricing Analysis
Heritage certification tier (Kweichow origin, Ming-dynasty cellar pit provenance) creates the primary spread between collector-grade releases and commercial volume. Pricing stratifies across heritage-certified, GB/T-compliant standard, and entry-level economy tiers. Cost compression in the standard tier is intensifying because MEE-mandated coal-to-biomass retrofits are elevating energy input costs. Affluent consumers in corporate gifting channels exhibit moderate price elasticity, while collector networks show near-zero sensitivity to per-unit increases.
Supply Chain Analysis
Extended aging verification periods now stretch finished goods inventory to 18-24 months before release authorization. Geographic supply concentration centers on Guizhou, Sichuan, and Jiangsu as the three dominant fermentation clusters. Raw material sourcing draws from Heilongjiang red sorghum, Sichuan wheat, and Guizhou spring water reserves. Supply chain risk hinges on single-source vulnerability for Ming-dynasty cellar pit access in Luzhou. Distribution runs through specialty store networks with digital custody certificates displacing traditional auction intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by post-regulatory-tightening inventory restocking, as SAMR compliance delays created pent-up release pipelines now clearing through verified vintage channels.
For Market Incumbents: Fortify cellar pit access through strategic M&A in Luzhou and Maotai town clusters, where Ming-dynasty heritage assets face succession pressure from master blender retirements. Deepen backward integration into Heilongjiang sorghum procurement to lock in margin predictability against harvest volatility. Prioritize blockchain provenance infrastructure investment to defend authentication credibility against precision-fermentation entrants.
For New Entrants and Emerging Players: Differentiate on precision fermentation technology that replicates strong-aroma congener profiles without heritage cellar dependencies. Target the huangjiu segment in Jiangsu and Zhejiang, where regional cuisine promotion has outpaced supply-side investment and collector networks remain underdeveloped. Pursue direct-to-collector platform partnerships with Shanghai private clubs as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors heritage-asset aggregators over technology-first challengers. Long-term viability across the five-to-ten year window rests on irreplaceable fermentation pit portfolios rather than scalable production engineering. Target acquisition archetypes include second-tier distilleries with state-protected geographical indications and underutilized aging inventory. Watch MEE carbon intensity enforcement timelines as the critical inflection signal for capital allocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Cellar Pit Acquisition | Secures non-replicable Ming-dynasty fermentation assets in Luzhou Laojiao's competitive orbit. |
| Blockchain Provenance Integration | SAMR mandates compress counterfeiting windows for strong-aroma releases in collector channels. |
| Biomass Retrofit Completion | MEE emissions benchmarks unlock green financing for Guizhou and Sichuan modernization programs. |
| Direct-to-Collector Platform Launch | Shanghai private clubs displace auction houses for highest-margin verified vintage transactions. |
| Heilongjiang Sorghum Contracting | Long-term supply agreements hedge harvest yield volatility squeezing margin predictability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across distillery master blenders, luxury hospitality procurement directors in Shanghai and Beijing, specialty store network managers, and SAMR regulatory affairs specialists. Secondary validation drew from GB standards documentation, MEE emissions disclosure filings, customs trade records for ceramic vessel imports, and collector club transaction databases. Bottom-up volume modeling triangulated against top-down value estimates from hospitality procurement budgets and verified vintage platform flows.
Across the analysis window, forecasts integrated product type segmentation by fermentation method, customer type by buyer sophistication tier, distribution channel by authentication burden, and packaging type by regulatory compliance intensity. CAGRs were derived from trend extrapolation of collector network expansion rates and corporate gifting channel penetration. Industry-specific inputs included sorghum harvest yield projections and MEE retrofit capital deployment schedules.
The analysis sits within stated boundaries; outcomes outside sustained SAMR enforcement intensity or dual carbon goal acceleration would require recalibration. Forecasts reflect documented assumptions on collector liquidity and heritage asset scarcity premiums. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Middle East and Africa Kegs Market