
 Global Natural Food Flavors Market | 2026-2036
Global Natural Food Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Natural Food Flavors Market Foresight
Organic-certified and non-GMO specification tiers is bifurcating the competitive landscape into premium extract suppliers and conventional commodity players. DSM-Firmenich leverages its integrated biotechnology platform to secure fermentation-derived flavor precursors. Givaudan SA anchors its position through deep partnerships with tropical fruit sourcing cooperatives in Southeast Asia. Kerry Group plc differentiates via its taste modulation technologies that reduce sodium and sugar without sacrificing flavor intensity.
Natural food flavors comprise volatile aromatic compounds extracted from plant, microbial, or fermentation sources, typically standardized to specific fold concentrations, essential oil percentages, or GC-MS purity profiles for batch consistency in industrial food production. Their primary commercial purpose is to restore or enhance sensory profiles in processed foods where thermal processing, storage, or formulation changes degrade native taste and aroma. Fruit and citrus flavor types command the largest volume share due to their ubiquity across beverages and confectionery, though spice and herb segments are gaining traction in savory applications and functional food positioning. Liquid and extract product forms dominate manufacturing workflows for their ease of incorporation into high-throughput processing lines, while powder forms are expanding in dry-mix and shelf-stable categories where moisture control is critical.
The FDA's GRAS self-affirmation pathway and the EPA's oversight of agricultural pesticide residues on botanical raw materials both shape ingredient eligibility and sourcing geography for North American suppliers. EFSA's flavoring substance evaluation program under Regulation EC No 1334/2008 creates a harmonized positive list that determines market access across EU member states, directly influencing R&D investment priorities. China's SAMR and NMPA are tightening import documentation for natural extracts, adding compliance layers for multinational flavor houses. Stakeholders must monitor evolving clean-label certification schemes and regional enforcement disparities to align portfolio development with shifting procurement criteria.
Market Dynamics
Clean-label procurement mandates from multinational beverage and dairy processors are compressing synthetic flavor substitution timelines, forcing ingredient houses to reconfigure extraction and fermentation capacity ahead of regulatory deadlines.
Growth Catalysts
- EU Green Deal additive restrictions:REACH compliance deadlines are accelerating reformulation cycles across European food manufacturing, pulling forward natural extract procurement by 18-24 months.
- Biotechnology platforms:Precision fermentation for flavor precursors is collapsing cost curves for high-value compounds previously extracted from scarce botanicals.
- Southeast Asian sourcing cooperatives:Direct partnership models with tropical fruit growers are securing volume commitments for vanilla, cocoa, and citrus extracts before harvest volatility.
Market Restraints
- Raw material concentration:Madagascar and Indonesia supply 80% of global vanilla bean volumes, exposing processors to climate-induced crop failures and price spikes.
- Fermentation capex thresholds:Commercial-scale bioreactor facilities require $50-120 million per site, restricting biotechnology adoption to integrated multinationals.
- Regulatory fragmentation:China's SAMR import documentation requirements diverge from FDA GRAS pathways, forcing dual certification costs for cross-border suppliers.
Strategic Opportunities
- India functional food expansion:FSSAI's 2022 relaxation of natural flavor claims in ayurvedic-positioned products opens formulation white space for spice and herb extracts.
- Direct-to-manufacturer platforms:B2B marketplaces for botanical extracts are disintermediating traditional distributor networks in mid-tier food processing.
- Carbon labeling convergence:EU CSRD scope 3 disclosure rules are creating first-mover advantages for suppliers with verified low-carbon extraction methods.
Industry Challenges
- GC-MS analytical talent scarcity:Batch consistency verification requires specialized chromatography expertise that outpaces university pipeline output in key production regions.
- Legacy ERP integration:Traceability systems for organic certification must interface with decades-old manufacturing execution platforms at contract manufacturers.
- Cooperative quality variance:Smallholder sourcing partnerships struggle with moisture content and essential oil standardization across harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Natural Food Flavors Market |
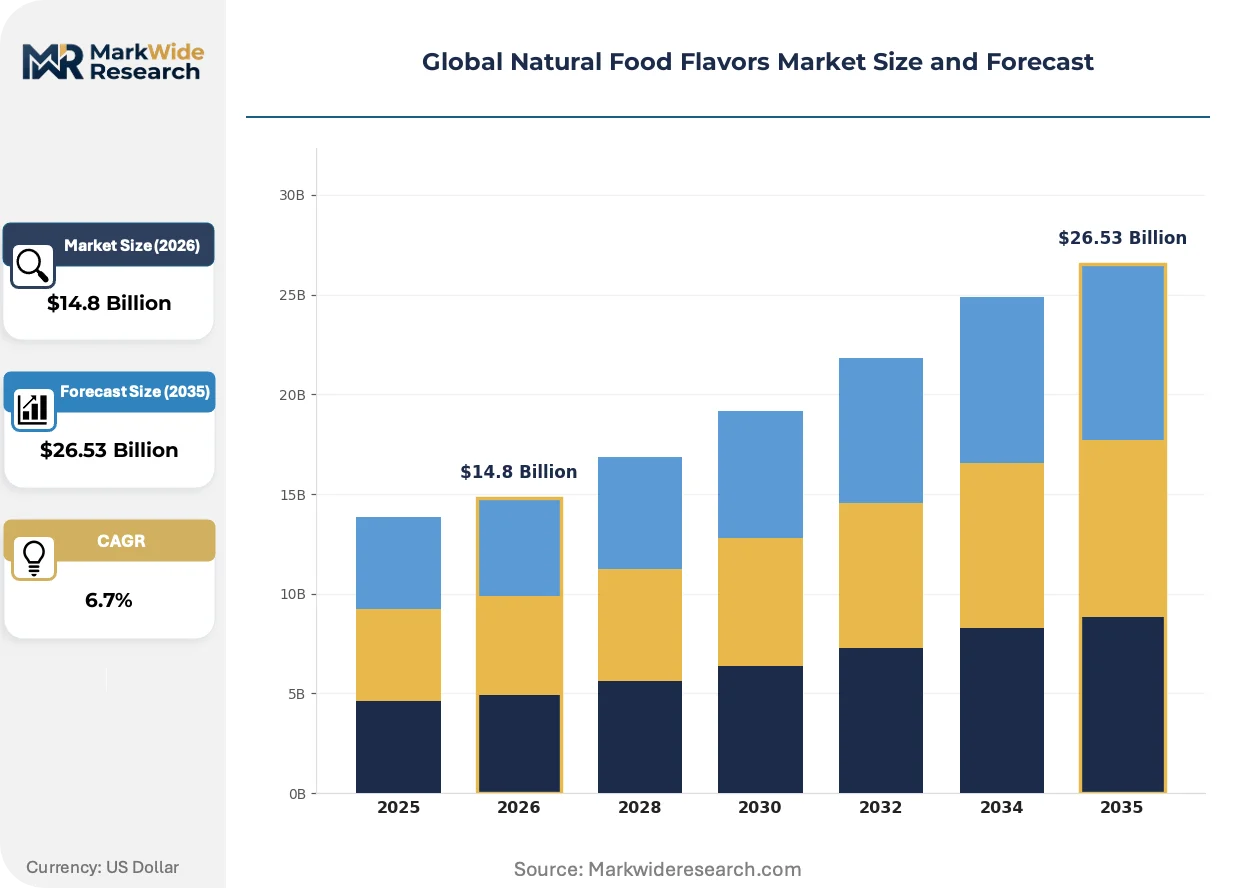
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Fruit, Spice, Herb, Nut, Floral, Citrus Application: Beverages, Confectionery, Snacks, Dairy Products, Bakery, Sauces Product Form: Liquid, Powder, Oil, Emulsion, Extract End User: Food Manufacturers, Beverage Producers, Culinary Professionals, Ingredient Suppliers |
| Companies Covered | DSM-Firmenich, Archer-Daniels-Midland Company, Givaudan SA, Takasago International Corp., Sensient Technologies Corporation, International Flavors & Fragrances Inc., Kerry Group plc, Döhler GmbH, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Natural Food Flavors Market Shifts & Advancements
Biotechnology, regulatory disclosure mandates, and procurement platform digitization are converging to restructure how flavor houses compete on speed-to-formulation and verified sustainability credentials.
Cell-culture-derived aromatic compounds are miniaturizing production footprints for high-value extracts like saffron and vanilla, enabling distributed manufacturing near end-use facilities rather than centralized extraction plants. Mid-sized beverage brands in Germany and the Netherlands are piloting these systems for limited-run seasonal formulations. The technology is miniaturizing capital requirements for entry into premium natural flavor categories previously blocked by agricultural land and climate dependencies.
EFSA's flavoring substance evaluation program under Regulation EC No 1334/2008 is tightening the positive list for botanical extracts, removing several traditional solvent-based compounds from approved use. Reformulation costs for affected savory and confectionery applications are redirecting R&D budgets toward supercritical CO2 and enzyme-assisted extraction methods. Southern European flavor houses near Barcelona and Milan are consolidating pilot facilities to share compliance testing burdens.
Ingredient sourcing decisions now integrate carbon accounting data from third-party verification platforms, with procurement teams weighting scope 3 emissions alongside price and sensory performance. This behavioral shift compresses supplier qualification timelines for certified low-carbon extractors while marginalizing conventional players without documented supply chain transparency. The pattern is most pronounced in Nordic markets where retail chains have mandated climate disclosures for private-label suppliers since 2023.
Global Natural Food Flavors Market Segmentation
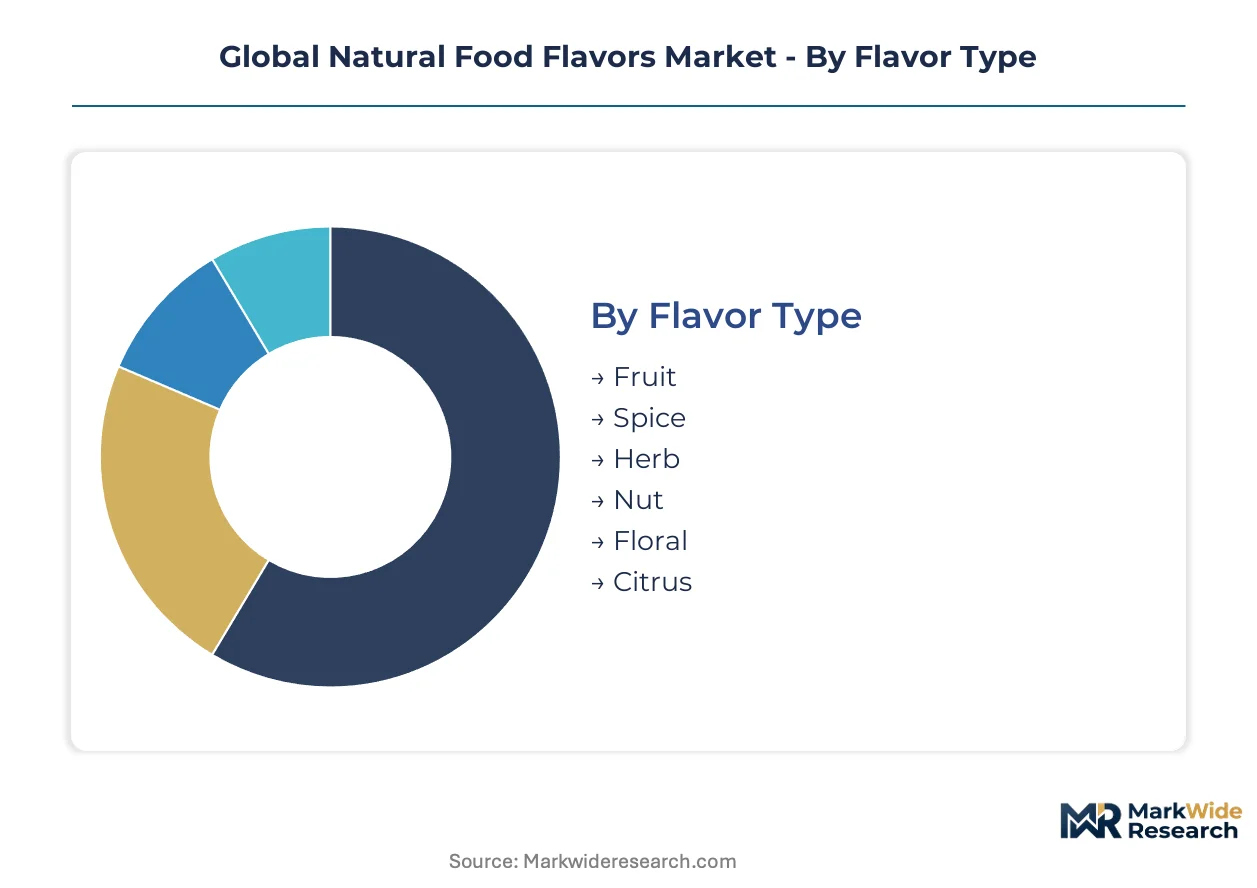
Flavor houses configure production assets around extraction chemistry and end-use processing requirements. Segmentation reveals where EFSA's positive list restrictions, FDA GRAS pathways, and FSSAI claim relaxations create divergent product qualification burdens across geographies.
Flavor Type:
EFSA's Regulation EC No 1334/2008 positive list and FDA GRAS self-affirmation create divergent approval burdens that reshape competitive positioning across extraction categories.
- Fruit:Volatile aromatic compounds standardized to specific Brix levels and fold concentrations for batch consistency. Beverage processors in Germany and the Netherlands concentrate procurement here, driven by clean-label mandates from retail chains. Established volume favors Fruit; emerging adoption favors Spice.
- Spice:Essential oil and oleoresin extracts from capsicum, black pepper, and cinnamon bark, typically specified by Scoville heat units or piperine content. FSSAI's relaxation of natural flavor claims in ayurvedic-positioned products is accelerating demand from Indian functional food manufacturers.
- Herb:Aqueous and solvent extracts of basil, oregano, and rosemary standardized to antioxidant compound markers.
- Nut:Roasted and unroasted profiles from almond, hazelnut, and peanut sources for confectionery and bakery applications.
- Floral:Rose, lavender, and orange blossom extracts serving premium confectionery and beverage categories.
- Citrus:Cold-pressed and distilled oils from lemon, lime, and grapefruit with specified limonene content.
Extraction complexity and regulatory scrutiny intensify moving from Fruit toward Floral categories.
Application:
Processing temperature tolerance and shelf stability requirements dictate extract specification tiers across manufacturing workflows.
- Beverages:Water-soluble extracts and emulsions formulated for thermal pasteurization and aseptic filling lines. Clean-label procurement mandates from multinational processors in Germany are compressing synthetic substitution timelines. Beverages command the steepest expansion trajectory; Dairy Products gain share through taste modulation deployment.
- Confectionery:Heat-stable oil-based and encapsulated flavors engineered for high-temperature cooking and panning processes.
- Snacks:Powder and oil-based topical applications for extruded and fried products requiring adhesion and oxidative stability.
- Dairy Products:Fermentation-compatible extracts that survive UHT treatment and extended cold-chain distribution.
- Bakery:Heat-resistant encapsulated flavors for oven environments and extended shelf-life requirements.
- Sauces:Acid-stable extracts formulated for pH extremes and retort processing conditions.
High-throughput liquid processing favors Beverages; premium positioning and margin capture favor Confectionery.
Product Form:
Moisture content, incorporation mechanics, and packaging format determine manufacturing workflow compatibility.
- Liquid:Standardized solutions and concentrates for pump-and-meter dosing in continuous processing lines. Frankfurt's ingredient innovation corridor clusters extraction capacity serving German beverage manufacturers. Liquid dominates volume throughput; Powder climbs fastest in dry-mix categories.
- Powder:Spray-dried and plated flavors on maltodextrin or gum arabic carriers for moisture-sensitive applications.
- Oil:Lipid-soluble extracts for fat-based confectionery and savory coating systems.
- Emulsion:Oil-in-water dispersions for beverage cloud and mouthfeel enhancement.
- Extract:High-fold concentrated aromatic compounds requiring precise dilution protocols.
Processing line integration favors Liquid; shelf-stable and e-commerce distribution favor Powder.
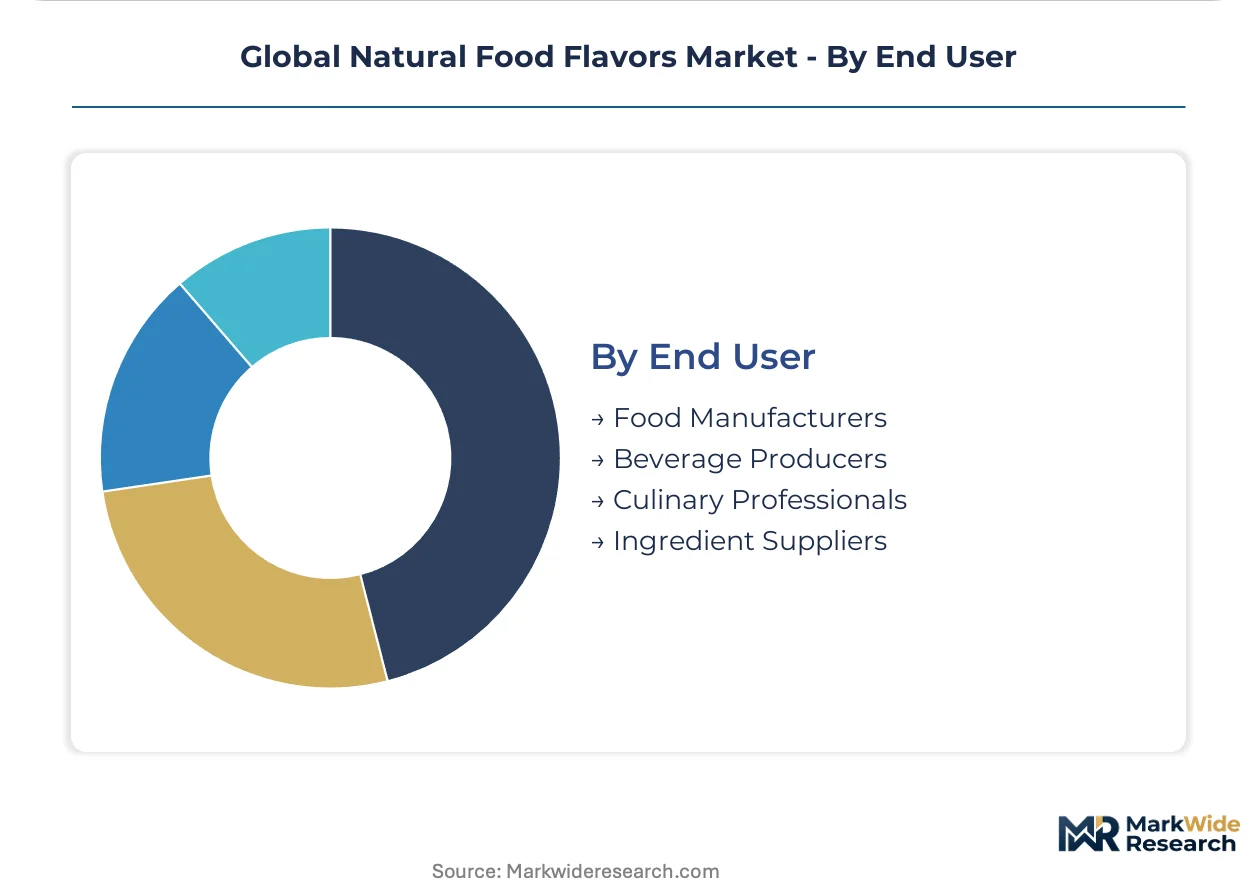
End User:
Scale of operation and technical capability determine service model and specification complexity.
- Food Manufacturers:Industrial-scale processors requiring batch consistency documentation and organic certification chain-of-custody. REACH compliance deadlines across European manufacturing are pulling forward natural extract procurement cycles. Food Manufacturers anchor volume concentration; Beverage Producers drive fastest specification evolution.
- Beverage Producers:Brand owners with dedicated R&D facilities demanding rapid formulation iteration and seasonal limited-run support.
- Culinary Professionals:Chefs and institutional kitchens sourcing small-batch extracts for menu differentiation.
- Ingredient Suppliers:Distributors and blenders repackaging bulk extracts for mid-tier processor access.
Contract manufacturing scale favors Food Manufacturers; direct-to-brand platform disintermediation favors Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vanilla bean sourcing concentrates in Madagascar and Indonesia, exposing processors to climate volatility. Flavor houses are diversifying extraction capacity across multiple geographies to reduce agricultural dependency. Procurement teams now weight carbon accounting alongside sensory performance.
Germany
Clean-label beverage mandates from retail chains are compressing synthetic substitution timelines. REACH compliance deadlines under the EU Green Deal are pulling forward natural extract procurement by 18-24 months. Frankfurt's ingredient innovation corridor clusters flavor houses serving German beverage manufacturers with fermentation-derived precursors.
United States
Multinational dairy and beverage processors are accelerating botanical extract procurement ahead of regulatory deadlines. FDA's GRAS self-affirmation pathway shapes ingredient eligibility while EPA oversight of pesticide residues determines sourcing geography. Midwest manufacturing hubs around Chicago and Minneapolis anchor industrial-scale flavor incorporation capacity.
India
FSSAI's 2022 relaxation of natural flavor claims in ayurvedic-positioned products is opening formulation white space for spice and herb extracts. Domestic functional food manufacturers are expanding procurement of standardized oleoresins. Maharashtra and Gujarat host concentrated mid-tier food processing capacity driving regional demand.
China
SAMR and NMPA are tightening import documentation for natural extracts, adding compliance layers for multinational flavor houses. Domestic biotechnology platforms are collapsing cost curves for fermentation-derived compounds. Yangtze River Delta manufacturing clusters around Shanghai are integrating precision fermentation capacity for local supply security.
Netherlands
Nordic retail chains' climate disclosure mandates since 2023 are weighting scope 3 emissions in procurement decisions. EFSA's flavoring substance evaluation program under Regulation EC No 1334/2008 is redirecting R&D budgets toward supercritical CO2 extraction. Rotterdam's logistics infrastructure supports carbon-verified botanical distribution across Northern European markets.
Global Natural Food Flavors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the competitive landscape. Integrated multinationals with biotechnology platforms command premium positioning through fermentation-derived precursors, while commodity extractors compete on volume scale. The market structures around three archetypes: biotechnology-integrated houses, tropical sourcing specialists, and regional extraction cooperatives. Dominant competitive moves include strategic partnerships with agricultural cooperatives and capacity expansion in precision fermentation facilities.
Within the biotechnology-integrated tier, DSM-Firmenich and Givaudan SA exemplify archetypes leveraging fermentation platforms to secure flavor precursor supply. Kerry Group plc occupies a position bridging taste modulation technology with extraction capabilities. These three anchors represent divergent strategic positioning—biotechnology integration, tropical sourcing depth, and functional ingredient convergence—shaping how procurement teams evaluate supplier portfolios.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Archer-Daniels-Midland Company |
| Givaudan SA |
| Takasago International Corp. |
| Sensient Technologies Corporation |
| International Flavors & Fragrances Inc. |
| Kerry Group plc |
| Döhler GmbH |
| Symrise AG |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with Madagascar and Indonesian vanilla cooperatives lock in both supply access and price visibility for European flavor houses facing REACH compliance deadlines. These agreements insulate processors from spot market volatility while committing capital to fermentation capacity expansion.
Pricing Analysis
EFSA's Regulation EC No 1334/2008 dictates the pricing tier structure by restricting solvent-based extraction methods and elevating supercritical CO2 and enzyme-assisted processes to premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified extracts from conventional commodities and fermentation-derived precursors. Cost compression in standard tiers is intensifying because biotechnology platforms are collapsing production costs for high-value compounds. Mid-tier beverage processors in Germany exhibit the highest price sensitivity, while premium confectionery houses in the Netherlands prioritize sensory performance over unit economics.
Supply Chain Analysis
Madagascar-Indonesia vanilla bean concentration creates a chokepoint that exposes processors to cyclone-induced crop failures and speculative price spikes. The supply chain draws from Southeast Asian citrus cooperatives, Indian spice growing regions, and Chinese fermentation facilities for precursor manufacturing. Single-source vulnerability in tropical botanicals forces dual-sourcing investments and climate-resilient agricultural partnerships. Distribution runs through Rotterdam's carbon-verified logistics infrastructure for Northern European markets, with Frankfurt's ingredient innovation corridor serving as the primary consolidation hub for German beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among multinational beverage and dairy processors is shifting bargaining power toward buyers with volume commitments and clean-label mandates. This fragmentation among suppliers compresses margins for undifferentiated extractors.
For Market Incumbents: Shield fermentation-derived precursor margins by accelerating capacity additions in the Yangtze River Delta and securing exclusive partnerships with Southeast Asian sourcing cooperatives before harvest windows. Biotechnology platforms represent the critical lever against commodity price volatility in vanilla and citrus extracts. For New Entrants and Emerging Players: Differentiate on carbon-verified extraction methods to capture procurement preference from Nordic retail chains with scope 3 disclosure mandates. India's ayurvedic-positioned functional food segment offers the most penetrable white space following FSSAI claim relaxations. A direct-to-manufacturer platform strategy disintermediates legacy distributor networks in mid-tier food processing. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors biotechnology-integrated houses with captive fermentation capacity over conventional extraction-dependent players. Long-term viability hinges on backward integration into precision fermentation and controlled-environment agriculture for high-value botanicals. Watch EFSA's positive list expansion pace as the inflection signal for regulatory-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Collapses cost curves for vanilla and saffron precursors previously constrained by agricultural land. |
| Supercritical CO2 Extraction Adoption | Secures EFSA compliance under Regulation EC No 1334/2008 while eliminating solvent residues. |
| Cooperative Partnership Deepening | Locks in volume commitments from Madagascar and Indonesian growers before climate volatility. |
| Carbon Verification Certification | Captures procurement preference from Dutch and German retail chains with CSRD scope 3 mandates. |
| Taste Modulation Technology Integration | Enables sodium and sugar reduction claims for Kerry Group plc's beverage manufacturer clients. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including flavor house R&D directors, beverage processor procurement leads, tropical cooperative agronomists, and fermentation facility engineers. Secondary validation drew from EFSA flavoring substance evaluations, FDA GRAS notifications, FSSAI regulatory circulars, and customs trade data for botanical extract flows. Bottom-up volume modeling from extraction capacity and top-down market sizing from end-use consumption patterns were triangulated for convergence.
Across the analysis window, forecasts incorporate flavor type segmentation by extraction chemistry, application segmentation by thermal processing requirements, and geographic segmentation by regulatory cluster. CAGRs were derived from elasticity modeling against clean-label procurement mandate adoption curves and biotechnology cost curve trajectories. Inputs include vanilla bean harvest forecasts from Madagascar agricultural ministries and fermentation yield improvements from Chinese biotechnology platforms.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement and FSSAI regulatory stability would require recalibration. Forecasts reflect assumptions on climate patterns in tropical growing regions and biotechnology scale-up timelines. Practitioners should keep alternative scenarios live as EFSA positive list revisions and SAMR import documentation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
Ylang Ylang Extract Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market