
 Beaded Jewelry Market | 2026-2036
Beaded Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Beaded Jewelry Market Intelligence
A divergence in capital intensity between mass-produced, machine-strung items and handcrafted, artisanal pieces is reorganizing the competitive landscape. Large luxury conglomerates like LVMH Group leverage their brand portfolio and distribution networks to dominate the high-end segment. Swarovski AG differentiates through its proprietary crystal bead manufacturing and strong brand identity in the premium space. In contrast, Stuller, Inc. operates as a key supplier of findings and materials to independent jewelers and small-scale producers.
Beaded jewelry consists of decorative items created by stringing or weaving together individual beads. The construction process, from simple stringing to complex loom-weaving, dictates the product's final durability and design intricacy. Necklaces and bracelets represent the largest product categories, fitting easily into both traditional and contemporary design aesthetics. Material selection, from mass-market glass and wood to luxury-tier stone, is the primary driver of price differentiation.
The US Consumer Product Safety Improvement Act (CPSIA) sets strict limits on lead and phthalates in children's products, including jewelry. In parallel, the EU's REACH regulation governs chemical safety for all consumer goods, impacting the types of metals and coatings used in beads. Navigating these disparate material compliance standards while managing supply chain ethics is the central challenge for market participants.
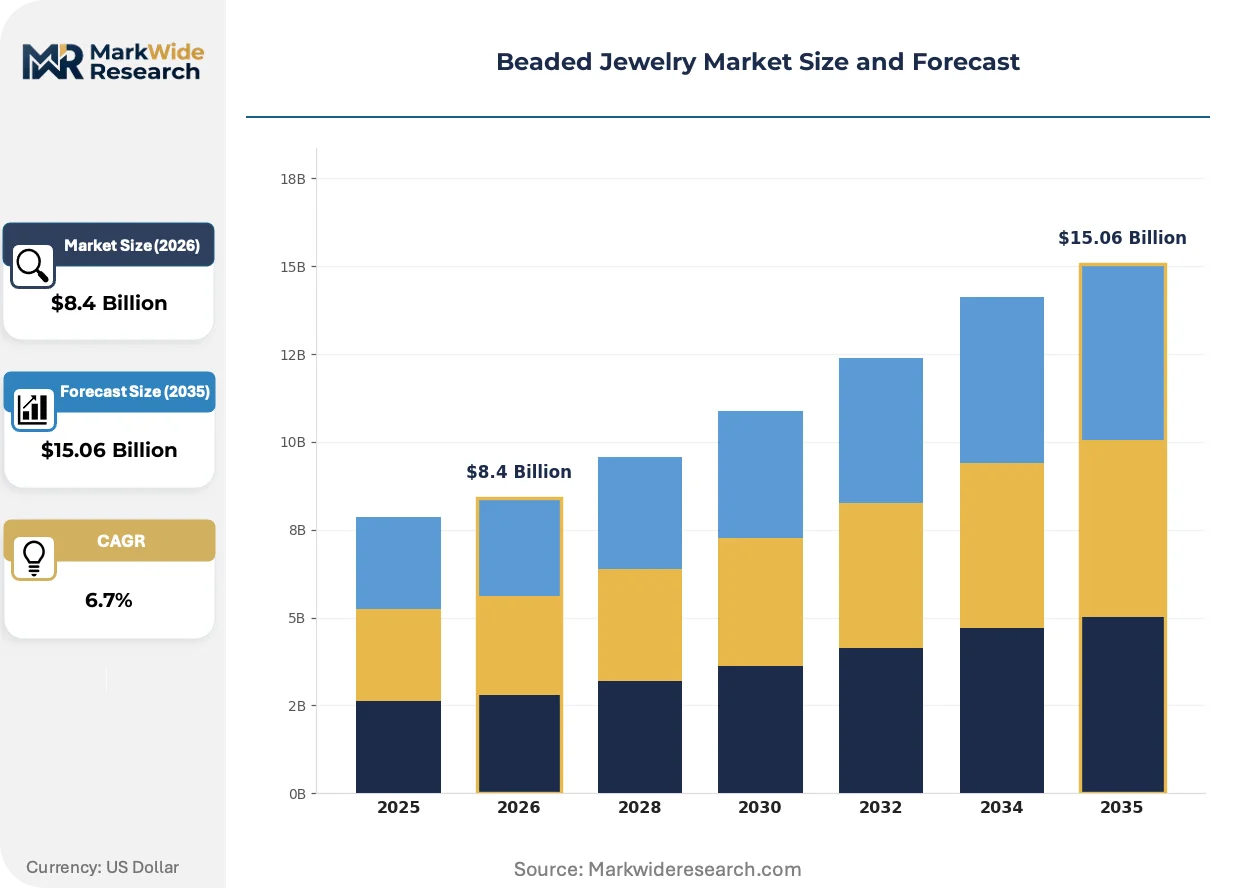
Market Dynamics
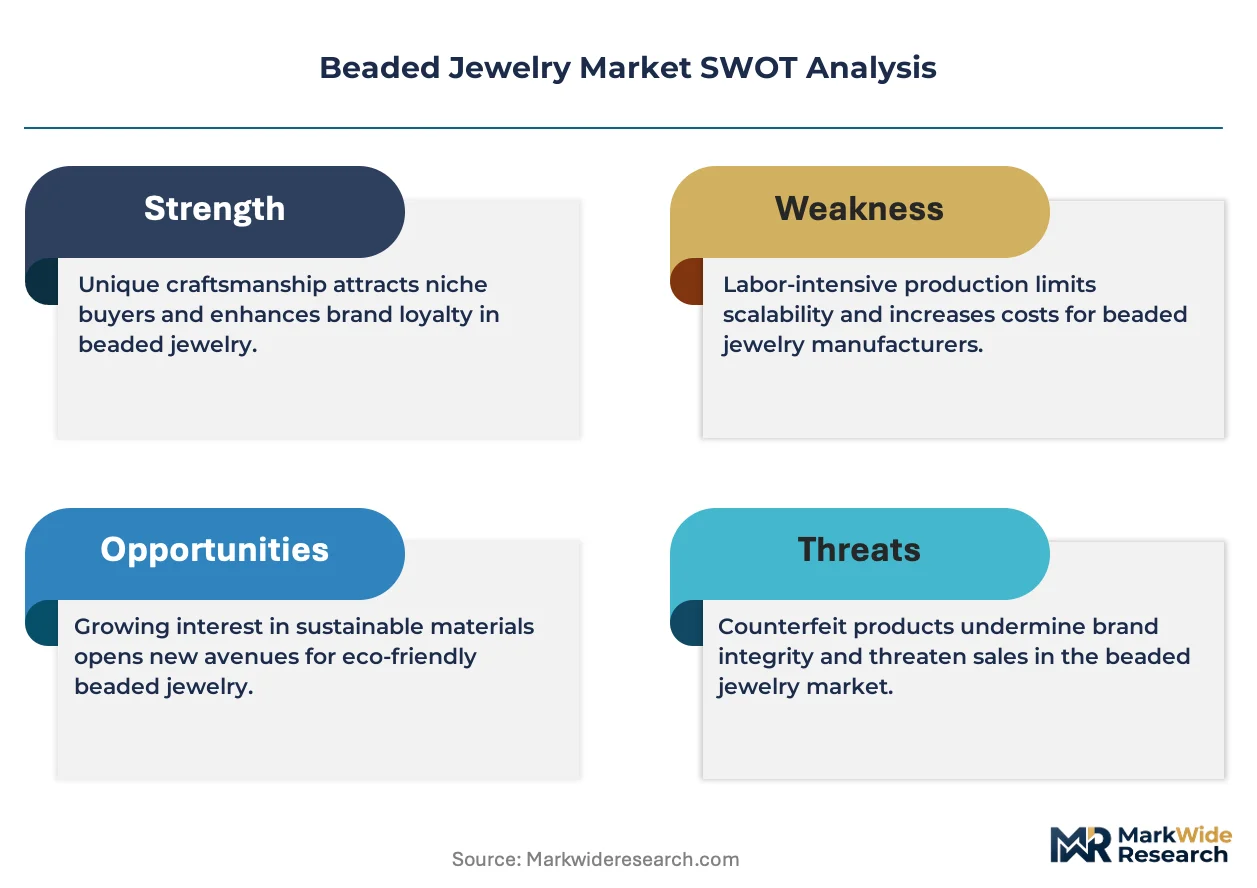
The central structural force shaping the beaded jewelry market is the divergence between high-volume, machine-strung production and low-volume, artisanal craft. This split is driven by consumer demand for ethical sourcing and personalization, amplified by regulatory pressures on material safety from frameworks like the EU's REACH.
Growth Catalysts
- Personalization Demand:The fashion enthusiast segment’s preference for unique, customizable jewelry drives adoption of varied bead materials, from glass and wood to semi-precious stones, and intricate, non-standard designs.
- Cultural Authenticity:Strong demand in India and Southeast Asia for jewelry reflecting traditional craftsmanship and cultural heritage supports artisanal producers and preserves regional design languages.
- Direct-to-Consumer Channels:E-commerce platforms and social media marketplaces empower independent designers to bypass traditional retail, connecting them directly with a global customer base seeking unique pieces.
Market Restraints
- Regulatory Compliance Complexity:Navigating disparate chemical safety standards, such as the EU's REACH regulation and the US Consumer Product Safety Improvement Act (CPSIA), creates significant operational overhead.
- Material Price Volatility:Sharp fluctuations in the cost of input materials like semi-precious stones and metals create margin pressure, particularly for small-scale independent jewelers with limited purchasing power.
- Counterfeit Goods:The proliferation of low-cost, machine-made imitations, primarily from manufacturing hubs in China, erodes brand value and market share for authentic artisanal products.
Strategic Opportunities
- Sustainable Materials:Developing and marketing beads made from recycled materials like glass or ethically sourced, lab-grown gemstones appeals to environmentally conscious consumer segments in Europe and North America.
- Traceability Technology:Integrating blockchain or NFC tags to verify the provenance of materials and the authenticity of handcrafted designs can create a premium value proposition and build consumer trust.
- Latin American Market Entry:Expanding into countries like Mexico and Peru, which possess rich traditions in beadwork, offers access to new consumer segments and skilled artisan communities.
Industry Challenges
- Artisan Skill Scarcity:A diminishing pool of artisans skilled in complex, time-intensive techniques such as loom-weaving and intricate embroidery threatens the production of high-value, heritage-based designs.
- Supply Chain Auditing:The operational burden of conducting rigorous audits to ensure compliance with ethical sourcing and fair labor standards across fragmented global supply chains is substantial for all market participants.
- Design IP Protection:Artisans and independent designers face significant difficulty in protecting unique beadwork patterns from rapid imitation by fast-fashion companies with superior production and distribution scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beaded Jewelry Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Bracelets, Earrings, Anklets Material: Glass, Wood, Polymer, Stone Design: Traditional, Contemporary, Custom, Minimalist End User: Women, Men, Children, Fashion Enthusiasts |
| Companies Covered | Avon Products, Inc., Buckley London, Stuller, Inc., Giorgio Armani S.p.A., Yurman Design Inc., LVMH Group, Pandora A/S, Swarovski AG, Van Cleef & Arpels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beaded Jewelry Market Strategic Shifts & Innovations
The market's evolution is defined by a dual focus on technological enablement for mass customization and a concurrent push towards transparent, ethically verifiable supply chains. This bifurcation shapes product innovation, branding, and consumer engagement strategies across all price points.
3D printing of custom components allows for unprecedented design freedom in jewelry creation. Independent designers and bespoke brands are adopting this technology to create unique findings and beads that are not available through mass-produced catalogs. This capability is fragmenting the reliance on standardized parts, enabling hyper-personalized products and short production runs that cater to niche consumer tastes.
Heightened regulatory scrutiny, exemplified by the EU's Corporate Sustainability Reporting Directive (CSRD), is elevating transparency requirements beyond basic chemical safety. This regulation compels larger firms to disclose detailed environmental and social governance data related to their entire value chain. Jewelry brands sourcing raw materials from Africa and Asia are most impacted, now needing to implement robust supplier verification systems.
A pronounced consumer shift toward purchasing items with a verifiable story is altering retail dynamics. Anonymous mass-market channels are losing ground to direct-to-artisan platforms and brands that offer clear provenance for their materials and craftsmanship. This demand for narrative-rich products is especially strong among Millennial and Gen Z consumers in North America and European markets.
Beaded Jewelry Market Segmentation
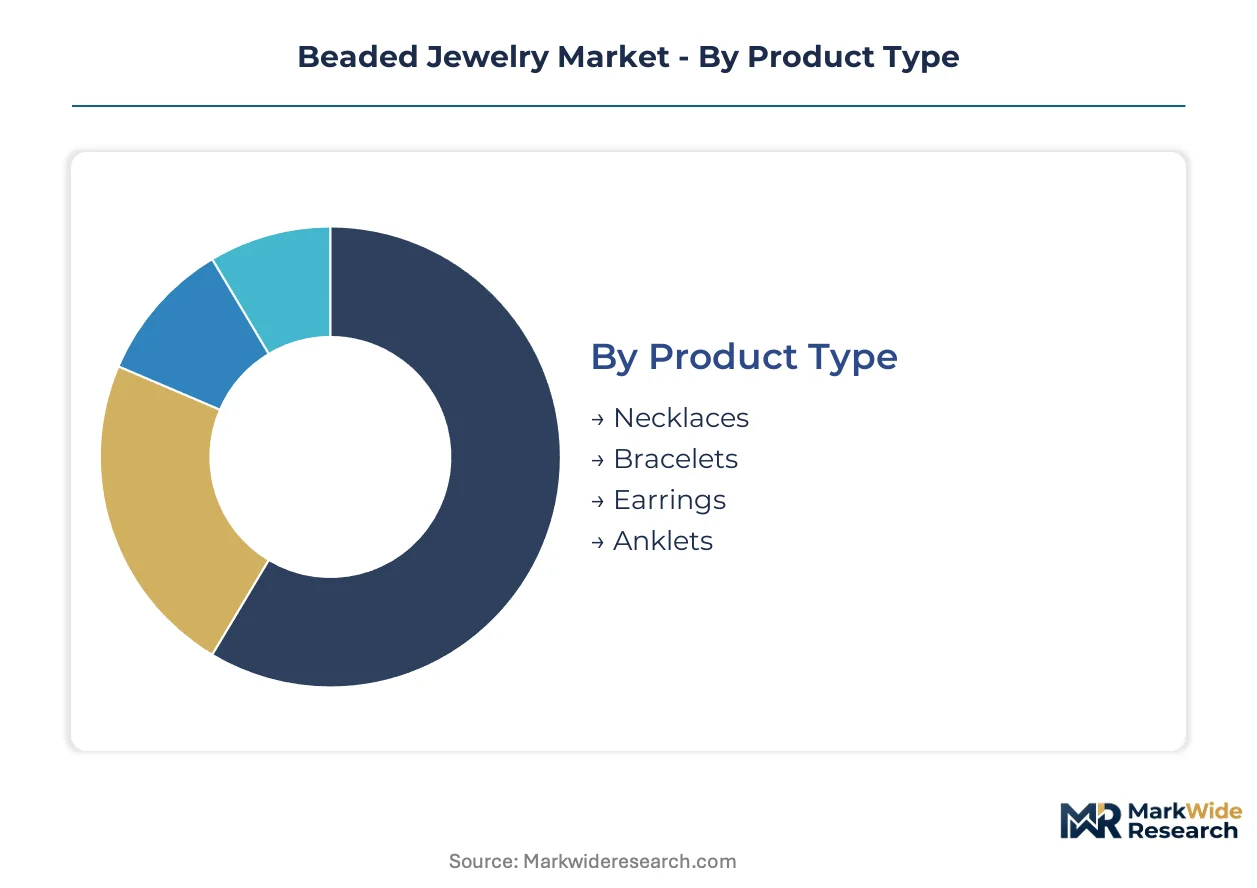
The beaded jewelry market’s segmentation reveals diverse consumer preferences and production methodologies. Understanding these distinct divisions assists market participants in tailoring product development and distribution strategies. Each segment presents unique challenges and opportunities, influencing material sourcing and design innovation.
Product Type:
Regulatory frameworks significantly differentiate product types, particularly concerning safety standards for items intended for children.
- Necklaces:These decorative items adorn the neck, typically featuring a string of beads, pendants, or charms. Demand for unique, personalized necklaces is particularly strong among fashion enthusiasts seeking expressive pieces across European and North American markets.
- Bracelets:Worn around the wrist, bracelets can range from simple strings of beads to intricate woven designs. The segment experiences high demand for customizable options, often incorporating semi-precious stones, appealing to consumers in India and Southeast Asia.
- Earrings:These ornaments are worn on the earlobe, often incorporating smaller beads or delicate beadwork.
- Anklets:Worn around the ankle, anklets frequently feature lightweight beads and are popular in warmer climates.
Necklaces handle the majority of throughput; Bracelets are the fastest mover on share.
Material:
Material selection primarily drives the final product's cost tier and aesthetic appeal.
- Stone:This segment includes beads crafted from various natural and semi-precious stones, offering unique textures and inherent value. Demand for these luxury-tier materials is robust in high-end markets like France and Italy, where consumers prioritize natural aesthetics and durability.
- Glass:Glass beads, available in a wide array of colors and finishes, form a significant portion of the mass-market segment. This material's versatility supports diverse design aesthetics, with strong appeal in both North American and European consumer bases.
- Polymer:Lightweight and versatile, polymer beads allow for intricate designs and vibrant colors, often used in contemporary and children's jewelry.
- Wood:Sourced from various tree species, wooden beads offer an organic, earthy aesthetic and are frequently used in artisanal and ethically conscious designs.
The Stone segment commands premium pricing due to its inherent value, while Glass materials offer broad accessibility.
Design:
Customer preferences for specific design aesthetics influence production techniques and market reach.
- Custom:These designs are tailored to individual client specifications, emphasizing uniqueness and personalization. The direct-to-consumer channel facilitates the growth of custom designs, connecting artisans with a global clientele seeking bespoke pieces.
- Contemporary:Reflecting current fashion trends, contemporary designs often feature modern aesthetics and innovative material combinations. This segment appeals to a younger demographic in urban centers, driving demand for fresh and evolving styles.
- Traditional:Traditional designs draw inspiration from cultural heritage and historical patterns, often employing specific beadwork techniques.
- Minimalist:Characterized by simplicity and clean lines, minimalist designs focus on understated elegance and subtle bead arrangements.
Custom designs exhibit the highest margin potential, whereas Contemporary styles capture the broadest consumer interest.
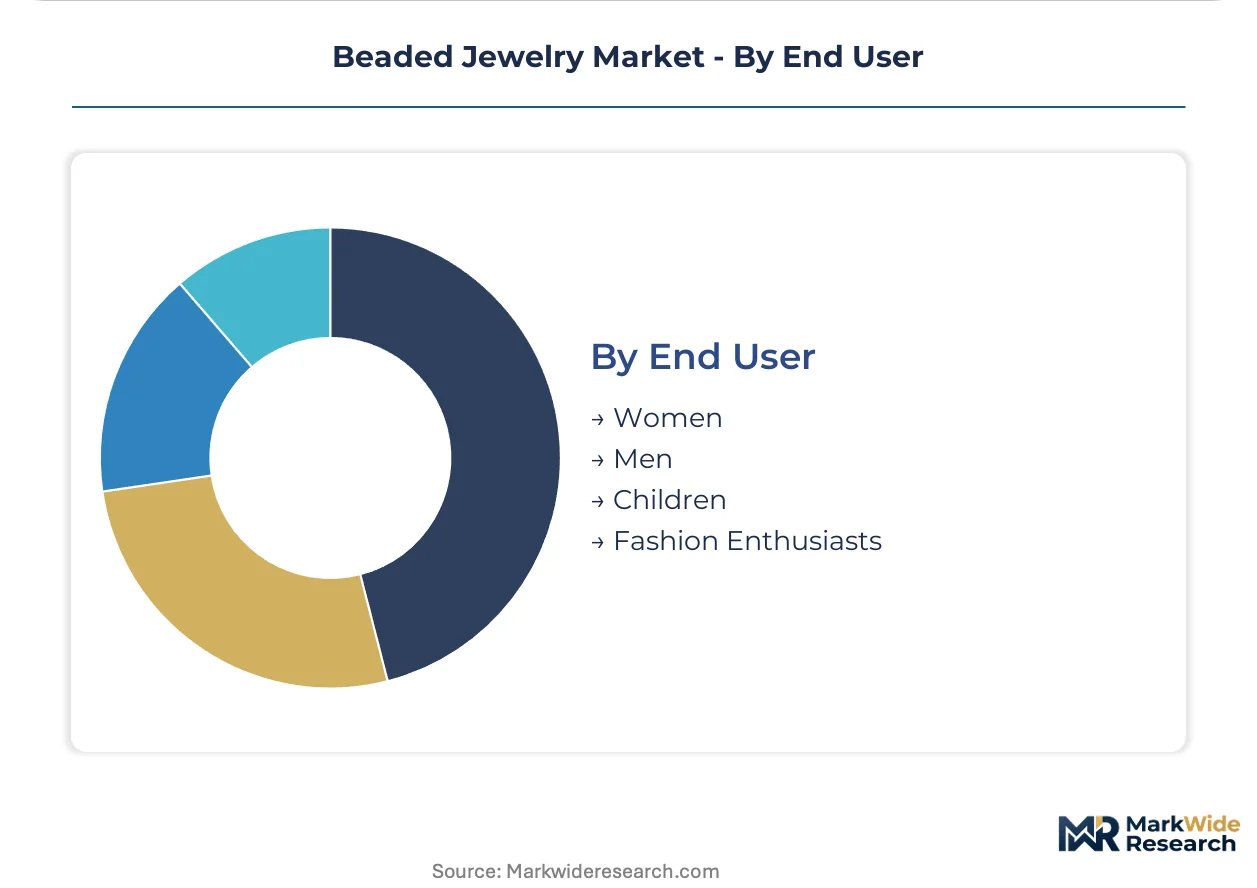
End User:
Specific end-user demographics shape product features, marketing approaches, and regulatory considerations.
- Fashion Enthusiasts:This segment comprises consumers highly engaged with current trends and seeking unique, personalized items to express individual style. Their demand drives innovation in bead materials and design intricacy, particularly within Western markets.
- Women:Representing the largest consumer base, women purchase beaded jewelry for various occasions, from daily wear to special events. This broad demographic influences demand across all product types and material categories, from mass-market to luxury.
- Men:The men's segment shows increasing interest in subtle beaded accessories, often featuring natural materials like wood or stone.
- Children:Beaded jewelry for children is subject to stringent safety regulations, such as the US Consumer Product Safety Improvement Act (CPSIA), dictating material composition and design.
Fashion Enthusiasts represent the fastest-growing segment, while Women continue to form the foundational demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power asymmetry exists between established luxury markets and emerging artisanal hubs. While European markets command premium pricing for high-end materials, countries in Asia often compete on value for handcrafted pieces. This divergence shapes investment and distribution strategies across the market.
United States
Fashion enthusiasts drive demand for unique, personalized beaded jewelry, particularly customizable necklaces and bracelets. The US Consumer Product Safety Improvement Act (CPSIA) imposes strict limits on lead and phthalates for children's jewelry. New York City's fashion district continues to influence bespoke jewelry trends and material innovation.
India
Cultural authenticity and traditional craftsmanship fuel strong demand for beaded jewelry, especially customizable bracelets with semi-precious stones. The country's national quality standards guide material sourcing and production processes for local artisans. Jaipur, Rajasthan, remains a significant hub for traditional jewelry manufacturing and gemstone trade.
France
Luxury-tier stone materials and natural aesthetics command high demand among discerning consumers in the French market. The EU's REACH regulation dictates chemical safety for all consumer goods, impacting bead and coating selection. Paris designers continue to set global luxury beaded jewelry trends and support artisanal production methods.
Vietnam
Traditional beadwork techniques and culturally authentic designs are highly sought after by local and international buyers. Vietnam's national consumer protection laws ensure product safety and material integrity for jewelry exports. Hanoi's Old Quarter preserves numerous workshops dedicated to intricate, heritage-based beaded designs.
Germany
Environmentally conscious consumer segments show strong preference for sustainable materials like recycled glass and ethically sourced wood beads. The EU's Corporate Sustainability Reporting Directive (CSRD) increasingly influences transparency requirements for larger jewelry firms. Idar-Oberstein maintains its reputation as a global center for gemstone cutting and processing, crucial for high-value beaded pieces.
Beaded Jewelry Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the beaded jewelry market. The market structure exhibits a tiered consolidation, with large luxury groups at the high end and fragmented artisanal producers at the lower end. Strategic archetypes include luxury conglomerates, premium material specialists, and independent artisan enablers. Dominant competitive moves involve leveraging extensive brand portfolios and strengthening proprietary manufacturing capabilities.
Within the luxury conglomerate tier, LVMH Group utilizes its vast brand portfolio and extensive distribution networks to dominate high-end segments. Swarovski AG, a premium specialist, differentiates through proprietary crystal bead manufacturing and a strong brand identity. Stuller, Inc. occupies a unique position as a key supplier of findings and materials, directly supporting independent jewelers and smaller-scale producers across the industry.
| Leading Market Players |
|---|
| Avon Products, Inc. |
| Buckley London |
| Stuller, Inc. |
| Giorgio Armani S.p.A. |
| Yurman Design Inc. |
| LVMH Group |
| Pandora A/S |
| Swarovski AG |
| Van Cleef & Arpels |
| Others |
Cost & Logistics Intelligence
Sustainable material adoption, such as recycled glass replacing conventional glass, simultaneously reshapes supply geography and introduces new pricing economics. This shift diversifies sourcing away from traditional raw material extraction sites.
Pricing Analysis
Customization-premium spreads between configured-to-order artisanal pieces and mass-produced standard items define market pricing. Pricing stratifies across premium, standard, and economy tiers, driven by material quality and design intricacy. Pricing softness affects mass-market glass beads due to intense competition from manufacturing hubs in China. Fashion enthusiasts exhibit lower price sensitivity for unique, custom pieces, while general consumers prioritize value in mass-market offerings.
Supply Chain Analysis
Inventory management for semi-precious stones often involves longer lead times due to their extraction and processing cycles. Geographic supply concentrates in India for traditional beadwork, China for mass-produced glass beads, and Germany for high-value gemstone cutting. The market relies on diverse inputs including semi-precious stones, glass, and metal findings, facing regulatory restriction risks like the EU's REACH framework. Distribution runs through e-commerce platforms for independent artisans and established retail networks for larger brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beaded jewelry market presents a significant fragmentation opportunity, driven by consumer demand for personalized and culturally authentic pieces. This shift enables niche development across diverse design aesthetics and material preferences.
For Market Incumbents: Consolidate brand portfolios to leverage existing distribution networks, particularly in high-end markets. Invest in robust supply chain auditing to mitigate regulatory compliance complexity from frameworks like REACH. This defends against erosion from counterfeit goods and bolsters consumer trust in ethical sourcing. Strengthen proprietary manufacturing capabilities for unique materials like Swarovski's crystals.
For New Entrants and Emerging Players: Differentiate on sustainable materials and traceability technology for environmentally conscious segments in Europe and North America. Target underpenetrated Latin American markets like Mexico and Peru, leveraging local artisan communities. Utilize direct-to-consumer e-commerce platforms to connect directly with global customers seeking unique pieces. This approach bypasses traditional retail barriers and builds authentic brand narratives.
For Investors and Strategic Acquirers: The EU's Corporate Sustainability Reporting Directive (CSRD) reshapes the acquisition landscape, favoring firms with verifiable ethical supply chains. Long-term viability rests on resilience against evolving regulatory demands and consumer preference for transparency. Target niche artisanal brands with strong provenance or technology providers specializing in supply chain traceability. A key signal to watch is the adoption rate of blockchain or NFC tags for material verification.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Direct-to-Consumer Channels | Connects artisans directly with global customers, bypassing traditional retail intermediaries and increasing margin potential. |
| Invest in Traceability Technology | Verifies material provenance and design authenticity, building consumer trust and enabling premium pricing. |
| Develop Sustainable Material Lines | Appeals to environmentally conscious consumer segments, aligning with evolving regulatory and ethical standards. |
| Acquire Niche Artisanal Brands | Integrates unique design capabilities and cultural authenticity into larger portfolios, diversifying product offerings. |
| Strengthen Regulatory Compliance Systems | Ensures adherence to chemical safety standards like REACH and CPSIA, mitigating operational and reputational risks. |
Research Approach
Operator-level perspectives from independent jewelers, material suppliers, luxury brand managers, and e-commerce platform executives anchored the qualitative base for this analysis. Primary interviews were triangulated with secondary validation from customs trade data, national consumer protection reports, and fashion industry trend analyses. A bottom-up validation of market size estimates was then cross-referenced with top-down macroeconomic indicators.
Sensitivity analysis assessed the impact of material price volatility and regulatory shifts on market projections across the analysis window. The analytical framework modeled market dynamics by product type, material, design, end user, and regional demand patterns. Compound annual growth rates were derived through regression analysis, incorporating consumer spending on fashion accessories and artisan skill availability as key inputs.
Forecasts assume regulatory continuity in the EU (REACH, CSRD) and US (CPSIA); material policy shifts would require re-modeling. Unforeseen geopolitical events affecting supply chains or rapid shifts in fashion trends present key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Qatar Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
3D Printing for Jewelry Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Jewellery Market
Jewelry
Brazil Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
South Africa Luxury Jewelry Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Japan Jewellery Market