
 Asia-Pacific Luxury Jewelry Market | 2026-2036
Asia-Pacific Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Luxury Jewelry Market Insights
Asset-light retail leasing models is reconfiguring competitive entry barriers across the Asia-Pacific Luxury Jewelry Market, allowing new contenders to secure prime mall presence without capital-heavy store ownership. Chow Tai Fook leverages its vertically integrated gold supply chain to sustain margin control across Greater China. Cartier anchors its position through maison-level experiential retail in Shanghai and Tokyo. Titan Company competes via regional manufacturing scale that supports price accessibility in South Indian markets.
Asia-Pacific luxury jewelry encompasses high-value ornamental pieces crafted from precious metals and gemstones, typically achieving purity grades of 18K to 24K gold and VS-clarity diamonds, serving primarily as wealth preservation instruments and status-signaling accessories. Necklaces and rings dominate transaction value among product types due to their centrality in bridal and ceremonial gifting across the region. Gold and diamond material segments command the deepest margin pools, reflecting cultural preference density in India and China. Specialty stores and online retail distribution channels are expanding fastest, though department stores retain concentrated footfall in Japan and South Korea.
India's BIS hallmarking standards and China's GB precious metals purity regulations shape product certification requirements, while Japan's METI consumer protection frameworks govern disclosure standards for gemstone treatments. These regulatory layers elevate compliance costs for entrants but reinforce trust premiums for established houses. Stakeholders must monitor evolving e-commerce disclosure rules and traceability mandates as digital channels capture greater share of regional transactions.
Market Dynamics
China's dual carbon goals and India's BIS hallmarking mandates are compressing traditional sourcing timelines while elevating transparency requirements across the Asia-Pacific Luxury Jewelry Market. These regulatory pressures are forcing established houses to reconfigure supply chain documentation and retail disclosure protocols ahead of enforcement deadlines.
Growth Catalysts
- GB Precious Metals Purity Standards:China's national purity certification requirements are accelerating consumer trust formation in tier-one cities, driving transaction velocity for 24K gold collections.
- Heritage Gold Collections:Affluent Chinese buyers are consolidating purchases around culturally resonant designs that signal intergenerational wealth preservation intent.
- Metropolitan Corridor Concentration:India's tier-one cities are generating density-driven retail expansion as specialty stores capture ceremonial gifting demand.
Market Restraints
- Gold Price Volatility:Raw material cost swings are compressing margin predictability for 18K to 24K product lines, forcing inventory hedging costs onto retailers.
- Supply Concentration Risk:Polished diamond sourcing concentrates in Surat and Mumbai cutting clusters, creating single-point vulnerability for South Indian manufacturers.
- MEI Consumer Protection Friction:Japan's disclosure standards for gemstone treatments impose documentation burdens that extend product launch timelines by 30-45 days.
Strategic Opportunities
- Vietnam and Indonesia Expansion:Underpenetrated Southeast Asian markets present whitespace for heritage-focused entrants targeting emerging HNW segments in Ho Chi Minh City and Jakarta.
- E-Commerce Traceability Mandates:China's SAMR digital disclosure rules are creating first-mover advantage for houses with blockchain-enabled provenance systems.
- AI-Driven Personalization:Machine learning configurators are converging with virtual try-on platforms to compress design-to-purchase cycles in bridal segments.
Industry Challenges
- Gemological Certification Bottlenecks:BIS hallmarking laboratory capacity constraints are extending product approval timelines, delaying seasonal collection launches.
- Legacy ERP Integration:Traditional inventory management systems require costly reconfiguration to support real-time traceability reporting under evolving METI and SAMR frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Luxury Jewelry Market |
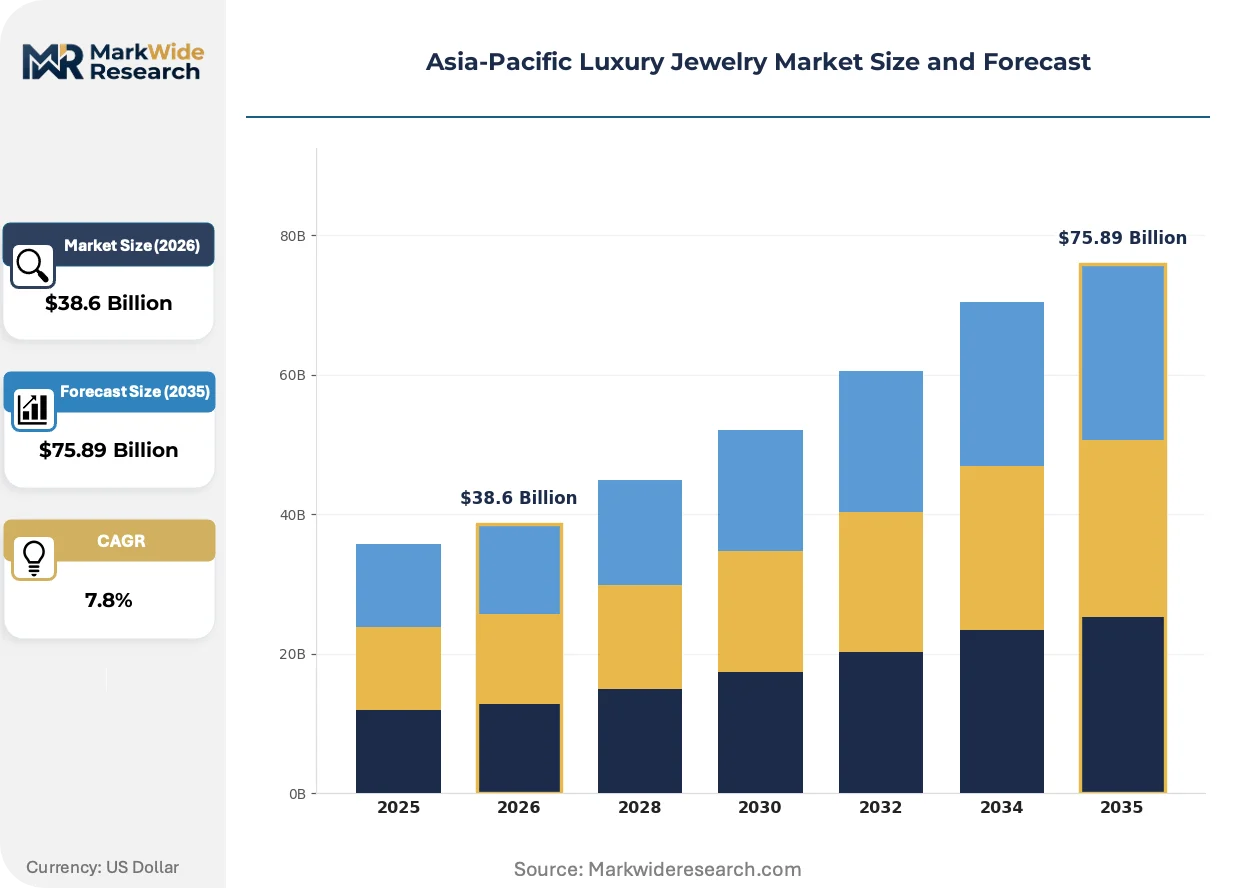
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Earrings, Bracelets, Rings Material: Gold, Silver, Platinum, Diamond Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales Customer Type: Affluent Consumers, Millennials, Gifting Customers, Luxury Enthusiasts |
| Companies Covered | Chow Tai Fook, Chanel S.A., Cartier, Kering S.A., Hermès International S.A., Bulgari, Titan Company, Compagnie Financiere Richemont SA, LVMH Moet Hennessy Louis Vuitton SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Luxury Jewelry Market Trends and Innovations
Digital provenance systems and experiential retail formats are compressing traditional value chain steps while elevating transparency expectations across the Asia-Pacific Luxury Jewelry Market. These shifts are reshaping how houses authenticate heritage claims and engage ceremonial buyers.
Blockchain-enabled origin tracking is digitizing custody documentation from mine to retail counter, creating immutable chain-of-custody records that satisfy China's SAMR disclosure mandates. High-net-worth collectors in Shanghai and Tokyo are demanding this verification layer for diamond purchases above VS clarity grades. The technology is digitizing trust formation that previously required physical inspection and paper certificates.
India's BIS hallmarking mandate expansion is forcing nationwide compliance infrastructure buildout, with CDSCO-aligned testing laboratories scaling capacity to handle 25 million annual jewelry pieces. Regional manufacturers are consolidating around certified production facilities to avoid distribution lockouts. South Indian bridal retailers face the steepest adaptation curve as hallmarking becomes compulsory for all gold above 2 grams.
Ceremonial buyers are compressing research-to-purchase cycles through mobile-first discovery platforms that aggregate certification data, price transparency, and virtual try-on capabilities. Specialty stores in China's tier-one cities are responding by unbundling after-sales services into subscription tiers. This behavioral shift is most pronounced among millennial bridal purchasers in Mumbai and Delhi metropolitan corridors.
Asia-Pacific Luxury Jewelry Market Segmentation
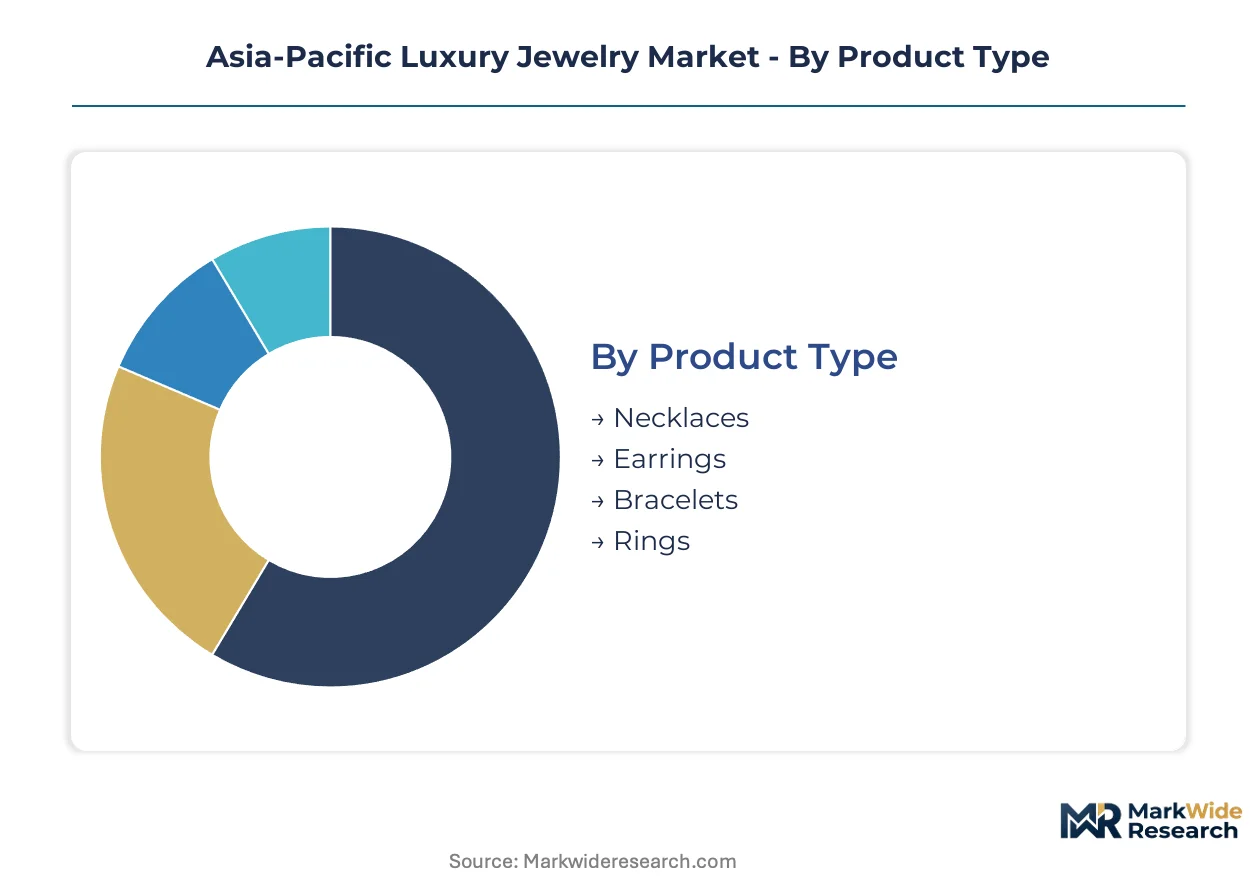
Segmentation in the Asia-Pacific Luxury Jewelry Market reveals how ceremonial traditions, wealth preservation motives, and channel preferences split demand across distinct purchasing contexts. Each dimension exposes different margin structures and competitive intensity patterns.
Product Type:
Use-case spectrum spans daily adornment through lifecycle ceremonial events, with form factor determining both price architecture and purchase frequency.
- Necklaces:Heavy 22K to 24K gold constructions dominate Indian bridal trousseaus and Chinese dowry preparations. Tier-one cities in China and metropolitan corridors in India concentrate demand during Q4 festival and wedding seasons.
- Rings:Diamond solitaire and eternity bands anchor engagement rituals across South Korea, Japan, and Australia. VS-clarity certification requirements from GIA and IGI laboratories elevate trust premiums in Tokyo and Sydney retail.
- Earrings:Lightweight daily-wear studs and chandelier ceremonial drops split demand by occasion type.
- Bracelets:Bangle stacks for Indian weddings and delicate chain designs for Japanese office wear occupy opposite ends of the weight spectrum.
The dominant share belongs to Necklaces, while Rings is closing the gap fastest.
Material:
Cost tier stratification separates wealth preservation buyers from fashion-forward purchasers, with purity grades and rarity premiums defining margin capture.
- Gold:18K to 24K purity grades serve distinct functions — 24K for Indian and Chinese intergenerational transfer, 18K for durability in Japanese and Australian daily wear. BIS hallmarking in India and GB standards in China enforce certification compliance that elevates established house advantages.
- Diamond:Polished stones above VS clarity with GIA documentation command price premiums in Shanghai, Tokyo, and Sydney collector circles. Blockchain traceability systems are becoming table stakes for stones above one carat.
- Silver:Sterling 925 purity anchors accessible luxury positioning in Southeast Asian emerging markets.
- Platinum:Purity density and hypoallergenic properties drive Japanese bridal preference and South Korean male jewelry adoption.
Gold captures the largest revenue pool, though Diamond is expanding most quickly among younger affluent cohorts.
Distribution Channel:
Volume concentration varies sharply by geography, with digital penetration rates diverging between mature East Asian markets and developing Southeast Asian corridors.
- Specialty Stores:Maison-level experiential retail in Shanghai, Tokyo, and Mumbai provides authentication theater for high-consideration purchases. Chow Tai Fook and Tanishq flagship formats concentrate footfall in premium mall locations.
- Online Retail:China's Tmall Luxury Pavilion and JD.com capture millennial bridal research-to-purchase compression. SAMR disclosure mandates for digital provenance are reshaping platform seller requirements.
- Department Stores:Isetan in Tokyo, Lotte in Seoul, and Tangs in Singapore retain concentrated footfall for gift occasions.
- Direct Sales:Private appointments and trunk shows serve ultra-HNW collectors in Hong Kong and Singapore.
Specialty Stores retain the dominant position, while Online Retail is climbing the fastest as mobile-first discovery platforms mature.
Customer Type:
Customer maturity and purchase motivation separate transactional buyers from relationship-driven collectors, with lifetime value calculations favoring certain profiles.
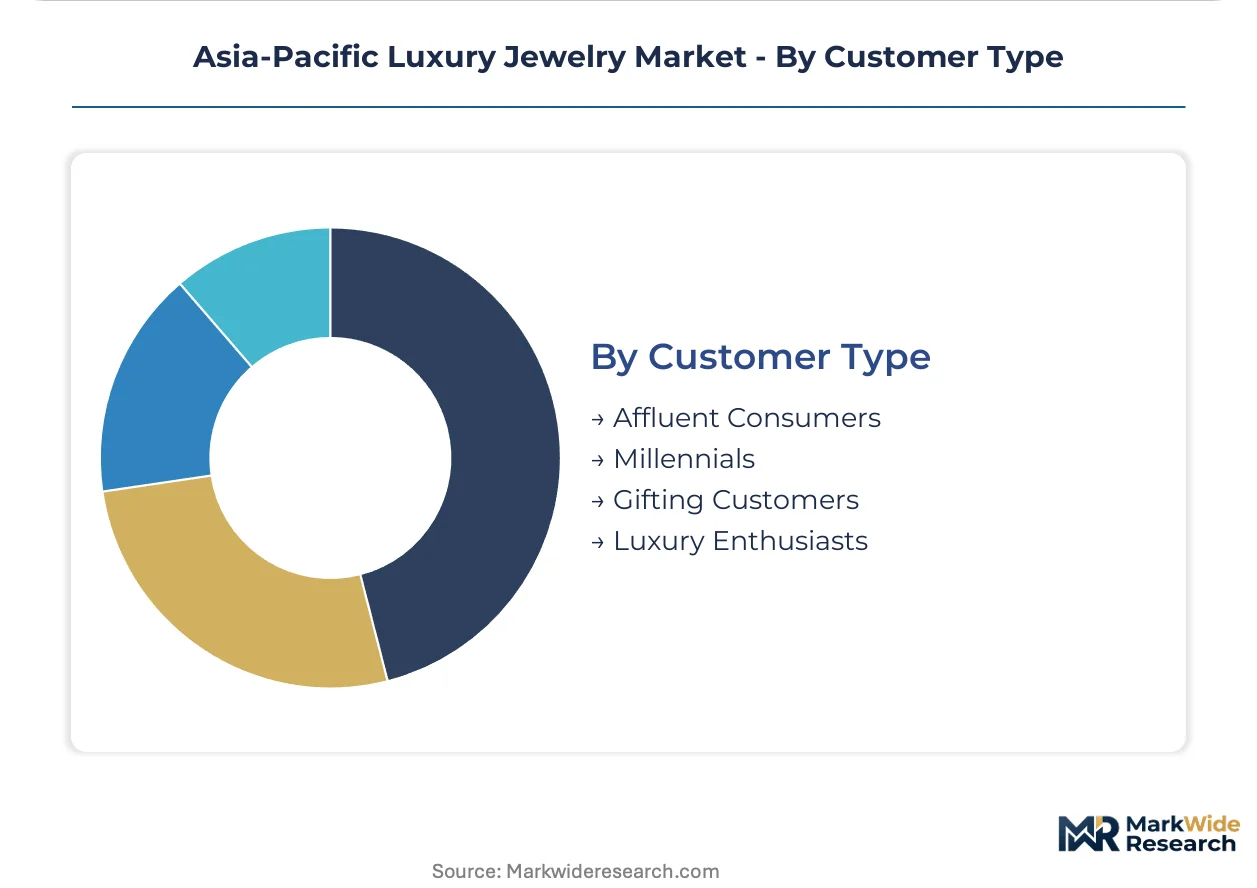
- Affluent Consumers:Established HNW individuals prioritize heritage craftsmanship and documented provenance for wealth preservation. Shanghai, Mumbai, and Sydney households drive 24K gold and investment-grade diamond acquisition.
- Gifting Customers:Ceremonial occasion purchasers concentrate spending around Diwali, Lunar New Year, and wedding seasons with rigid timing requirements.
- Millennials:Digital-native buyers compress research cycles through social commerce and virtual try-on platforms.
- Luxury Enthusiasts:Brand-loyal collectors chase limited editions and designer collaborations across Tokyo and Seoul.
Affluent Consumers command the deepest share, while Millennials is gaining share fastest through digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Mumbai command 35-40% price premiums over Bangkok and Jakarta for equivalent 24K gold constructions, reflecting wealth concentration and certification infrastructure gaps across the Asia-Pacific Luxury Jewelry Market.
China
GB precious metals purity standards and dual carbon goals are compressing supply chain timelines for heritage gold collections. SAMR digital disclosure mandates force real-time provenance documentation for e-commerce channels. Shanghai's Nanjing Road corridor concentrates maison-level experiential retail where Chow Tai Fook and Cartier anchor flagship formats.
India
BIS hallmarking mandates for all gold above 2 grams are reshaping quality assurance across bridal trousseau purchases. CDSCO-aligned laboratory capacity expansion targets 25 million annual jewelry pieces. Mumbai's Zaveri Bazaar and Surat's diamond cutting clusters face certification bottlenecks extending seasonal collection launches.
Japan
METI consumer protection frameworks govern gemstone treatment disclosure standards that extend product launch timelines by 30-45 days. Isetan and Mitsukoshi department stores retain concentrated footfall for gift occasion purchases. Tokyo's Ginza district hosts maison-level experiential formats serving ultra-HNW collectors.
South Korea
Lotte department stores and Shinsegae luxury halls anchor bridal jewelry discovery for diamond solitaire and eternity band purchases. MFDS-aligned disclosure requirements shape e-commerce platform seller qualifications. Seoul's Gangnam corridor concentrates millennial research-to-purchase compression through mobile-first platforms.
Australia
GIA and IGI laboratory documentation elevates trust premiums for VS-clarity diamonds in Sydney collector circles. TGA consumer protection frameworks govern precious metals purity claims for online retail channels. Sydney's Castlereagh Street and Melbourne's Collins Street host specialty store concentrations for affluent household wealth preservation purchases.
Asia-Pacific Luxury Jewelry Market Competitive Landscape
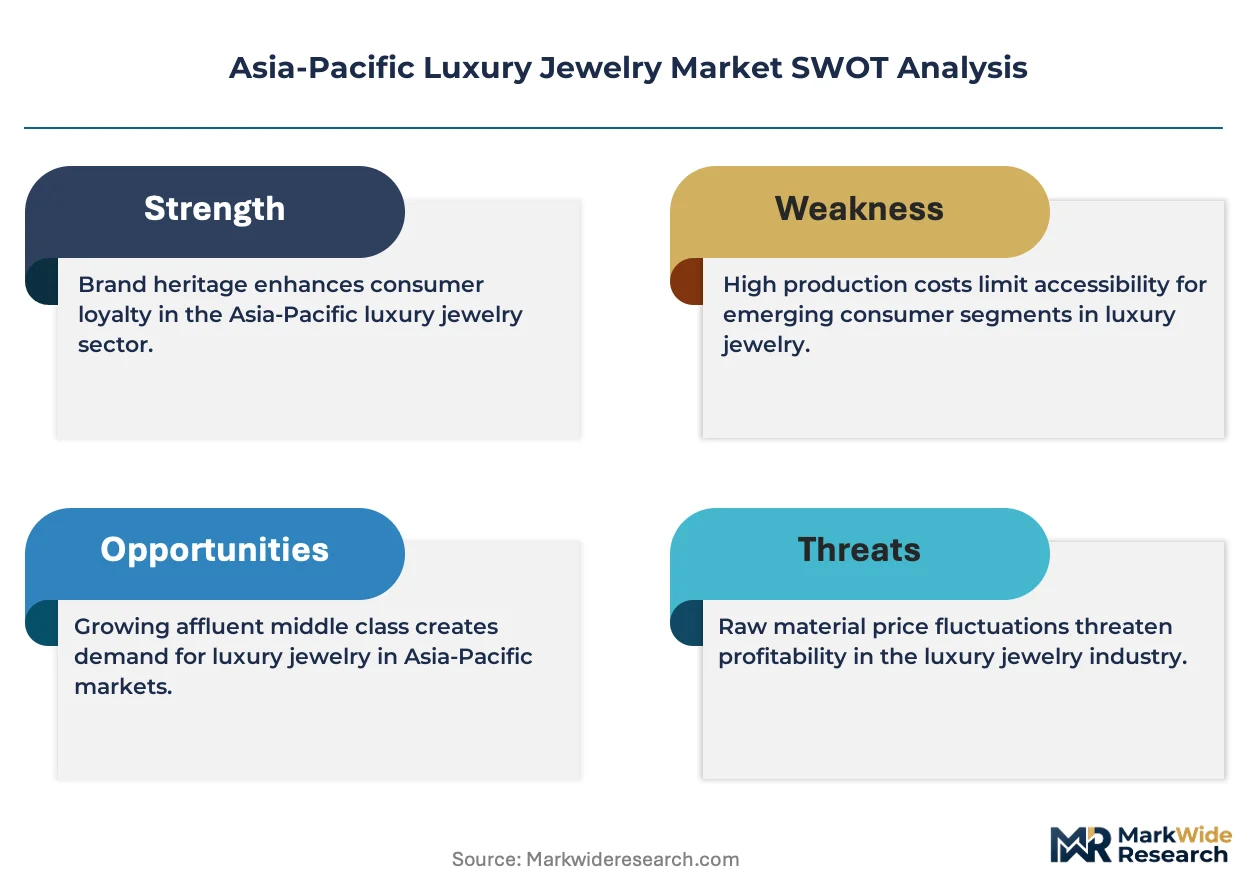
Platform integrators command the system tier; component specialists sit upstream in raw material and manufacturing layers. The Asia-Pacific Luxury Jewelry Market exhibits tiered consolidation where heritage houses with vertically integrated gold supply chains coexist with regional manufacturing specialists and pure-play luxury conglomerates. Three archetypes dominate: vertically integrated heritage houses with captive sourcing, regional scale manufacturers serving price-accessible segments, and luxury conglomerates with multi-brand portfolio diversification. Competitive moves concentrate on maison-level experiential retail expansion and blockchain-enabled provenance system deployment.
Among heritage-focused integrated houses, Chow Tai Fook anchors Greater China presence through gold supply chain control, while Cartier exemplifies maison-level experiential retail positioning in Shanghai and Tokyo. Titan Company occupies a regional manufacturing scale position supporting South Indian market accessibility. These three represent distinct competitive vectors: upstream integration, experiential premiumization, and manufacturing-led price positioning.
| Leading Market Players |
|---|
| Chow Tai Fook |
| Chanel S.A. |
| Cartier |
| Kering S.A. |
| Hermès International S.A. |
| Bulgari |
| Titan Company |
| Compagnie Financiere Richemont SA |
| LVMH Moet Hennessy Louis Vuitton SE |
| Others |
Pricing and Supply Chain Analysis
Surat diamond cutting cluster undercapacity is compressing polished stone availability while elevating BIS certification premiums across Indian bridal markets. This utilization squeeze forces South Indian manufacturers to absorb extended hallmarking timelines or forfeit seasonal collection windows, reshaping procurement posture toward captive assay laboratory investment.
Pricing Analysis
Customization-premium spreads widen most dramatically between configured heritage gold bridal sets and standard 22K necklace constructions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth: GB-standard 24K with blockchain provenance commands peak positioning, BIS-hallmarked 22K occupies mid-tier reliability, while unmarked regional production faces margin erosion. Pricing pressure stems from raw gold volatility transmitted through Mumbai bullion markets. Millennial digital-native buyers exhibit lowest price sensitivity when virtual try-on platforms reduce perceived purchase risk.
Supply Chain Analysis
Contract manufacturing concentrates among Surat diamond processing houses, Shenzhen precious metals fabricators, and Panyu gemstone setting facilities. Raw material flows draw from South African rough diamond auctions, Australian gold refining, and Myanmar jadeite extraction corridors. Single-source vulnerability concentrates in Surat-Mumbai polished diamond logistics. Distribution runs through Shanghai Nanjing Road flagship formats, Mumbai Zaveri Bazaar wholesale clusters, and Tmall Luxury Pavilion digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance verification is disrupting trust formation across the Asia-Pacific Luxury Jewelry Market, compressing traditional certification hierarchies while elevating transparency expectations among Shanghai and Tokyo collectors.
For Market Incumbents: Harden maison-level experiential retail positioning against digital-native entrants by embedding SAMR-compliant traceability systems into flagship Shanghai and Tokyo locations. Invest in captive BIS-aligned assay laboratory capacity to circumvent CDSCO certification bottlenecks during Indian festival seasons. Vertical integration into Surat diamond cutting relationships mitigates single-source vulnerability.
For New Entrants and Emerging Players: Build out Vietnam and Indonesia heritage-focused positioning targeting Ho Chi Minh City and Jakarta emerging HNW segments where established house footprint remains thin. Mobile-first discovery platforms with integrated virtual try-on compress research-to-purchase cycles most effectively among millennial bridal purchasers. Subscription-tier after-sales bundling differentiates against transactional department store competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage houses with vertically integrated gold supply chains and established maison-level retail networks. Long-term viability favors archetypes with blockchain-enabled provenance deployment ahead of SAMR enforcement deadlines. Monitor CDSCO laboratory capacity expansion timelines as inflection signal for Indian market access constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Deployment | SAMR digital disclosure mandates in China reward first-mover houses with immutable chain-of-custody records. |
| Captive Assay Laboratory Investment | CDSCO-aligned capacity insulates South Indian manufacturers against BIS hallmarking bottlenecks during festival peaks. |
| Maison-Level Experiential Retail Expansion | Shanghai Nanjing Road and Tokyo Ginza flagship formats authenticate heritage claims through theatrical retail environments. |
| Southeast Asian Geographic Expansion | Ho Chi Minh City and Jakarta present whitespace for heritage-focused entrants targeting emerging HNW density. |
| AI-Driven Personalization Platform Launch | Machine learning configurators compress design-to-purchase cycles for millennial bridal segments in Mumbai and Delhi corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association disclosures. Primary interviews engaged jewelry house supply chain directors, CDSCO laboratory certification officers, Tmall Luxury Pavilion category managers, and Mumbai Zaveri Bazaar wholesale operators. Secondary sources include BIS hallmarking compliance records, SAMR e-commerce disclosure frameworks, METI consumer protection guidelines, and customs trade data for precious metals flows. Bottom-up transaction analysis triangulates against top-down market sizing across material, product, and channel dimensions.
Forecast inputs incorporate GB precious metals purity standard enforcement timelines, BIS hallmarking mandate expansion trajectories, and digital channel penetration rates across tier-one Chinese cities and Indian metropolitan corridors. Segmentation modeling spans product type, material grade, distribution channel, and customer archetype dimensions. CAGRs derive from regression analysis of historical transaction velocity adjusted for regulatory inflection points and wealth concentration patterns. Gold price volatility assumptions and diamond sourcing concentration risks inform scenario-weighted projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated heritage houses or pure-play digital-native entrants would shift outcomes beyond modeled ranges. Quarterly review of CDSCO laboratory capacity utilization, SAMR blockchain disclosure adoption rates, and Surat-Mumbai logistics throughput is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Japan Jewellery Market
Jewelry
3D Printing for Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
Jewellery Box Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Bead Products Market
Jewelry
Jewelry Repair Market
Jewelry
Diamond Jewelry Market
Jewelry
Customized Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Crystal Bracelets Market