
 Global Horse Riding Equipment Market | 2026-2036
Global Horse Riding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Horse Riding Equipment Market Analysis
Recreational and leisure riders is collapsing the once-dominant professional segment as the primary volume driver across distribution channels. Ariat International leverages its heritage positioning to anchor premium leather boot demand among amateur enthusiasts in North America. Decathlon competes aggressively on price-accessible synthetic lines, while Georg Kieffer Sattlerwarenfabrik GmbH specializes in artisanal saddle craftsmanship for discerning competition riders.
Horse riding equipment encompasses protective, functional, and comfort-oriented gear manufactured from leather, synthetic polymers, textiles, and composite materials to ensure rider safety and equine performance across disciplines. Leather saddles require hand-stitched tree construction with adjustable gullet systems to distribute rider weight and prevent equine back trauma, while helmets incorporate multi-density EPS liners and ABS shells tested to impact-absorption thresholds. Saddles and helmets capture the deepest margin pools due to safety-critical replacement cycles and fit-sensitive purchase behavior. Synthetic materials in bridles and stirrups represent the fastest-expanding segment as plant-based polyurethane alternatives gain traction among environmentally conscious buyers.
ASTM International governs helmet impact standards in the United States, while CE marking under the EU Personal Protective Equipment Regulation mandates conformity assessment for protective gear sold across Europe. REACH restricts chromium VI in leather tanning processes, compelling manufacturers to reformulate finishing chemicals or source vegetable-tanned alternatives. ISO 9001 quality management certification increasingly functions as a procurement gatekeeper for institutional buyers operating equestrian centers. Stakeholders must monitor how divergent safety test protocols between North American and European frameworks influence product line rationalization and inventory allocation decisions.
Market Dynamics
Amateur rider entry is compressing replacement cycles and fragmenting distribution channels as leisure enthusiasts demand fashion-forward, multi-use equipment that diverges from traditional competition-grade specifications.
Growth Catalysts
- REACH chromium VI restrictions:European leather tanning reformulation is accelerating vegetable-tanned saddle adoption among environmentally conscious buyers seeking chemical-free alternatives.
- Wellness tourism infrastructure:Equestrian retreat investments in the United States and Australia are institutionalizing rental equipment demand and certified instructor procurement.
- Plant-based polyurethane bridles:Synthetic material innovation is displacing petroleum-derived components in price-accessible segments across German and French retail channels.
Market Restraints
- Leather price volatility:Argentine and Brazilian hide supply fluctuations are compressing margin pools for artisanal saddle manufacturers dependent on full-grain inputs.
- CE marking conformity costs:EU Personal Protective Equipment Regulation assessment fees are creating barriers for small-batch helmet producers in Eastern European markets.
- ASTM-EU test protocol divergence:Incompatible impact-absorption thresholds between United States and European certification bodies are forcing redundant R&D expenditure.
Strategic Opportunities
- Indian metropolitan expansion:Mumbai and Bangalore equestrian club formation is creating first-mover advantage for synthetic equipment distributors targeting nascent leisure demand.
- Subscription rental models:Seasonal equipment access programs are penetrating Australian coastal tourism corridors where visitor equipment transport friction remains high.
- ISO 9001 procurement gating:Institutional buyer certification mandates are creating compliance-based differentiation for quality-managed manufacturers serving United States equestrian centers.
Industry Challenges
- Master saddler apprenticeship gaps:Hand-stitched tree construction expertise concentration in Germany and Argentina is constraining scalable artisanal production.
- Multi-density EPS liner integration:Helmet manufacturer technical capability gaps are delaying next-generation impact-absorption product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Horse Riding Equipment Market |
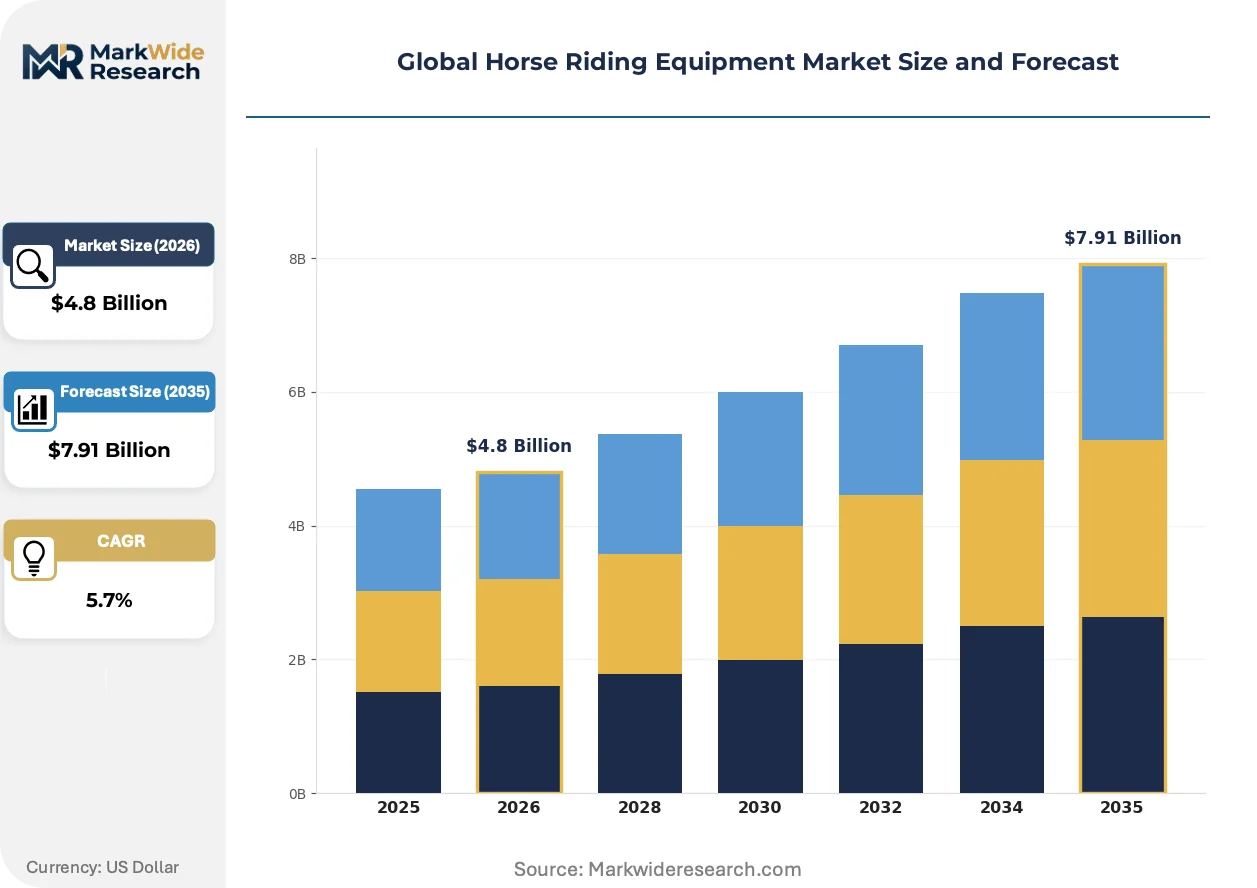
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saddles, Bridles, Stirrups, Helmets Material: Leather, Synthetic, Nylon, Cotton Use Case: Competition, Leisure, Training, Casual Riding End User: Professional Riders, Amateur Riders, Trainers, Equestrian Centers |
| Companies Covered | Dainese, Ariat International, Decathlon, Georg Kieffer Sattlerwarenfabrik GmbH, Cavallo GmbH, HKM Sports Equipment, Antares Sellier, Mountain Horse, Colonial Saddlery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Horse Riding Equipment Market Emerging Trajectories
Material science advancement and regulatory harmonization pressures are simultaneously elevating safety thresholds and democratizing access across price tiers.
Smart helmet sensor integration is bifurcating protective gear into connected performance-tracking units for competitive riders and simplified passive designs for leisure users. Amateur enthusiasts in Australian and United States markets are adopting basic impact-detection models at three times the rate of professional segments. This technology divergence is compressing mid-tier helmet margins as manufacturers struggle to serve divergent feature-expectation sets with unified production lines.
REACH leather chemical restrictions are compelling tannery reformulation across Italian and Spanish supply bases. Chromium VI elimination mandates are elevating vegetable-tanning process costs by fifteen to twenty percent while extending production timelines. Premium saddle manufacturers serving German competition riders are absorbing these costs through heritage positioning rather than passing through to price-sensitive amateur channels.
Direct-to-rider digital platforms are displacing traditional tack shop intermediaries in United States and United Kingdom metropolitan markets. Fit-sensitive purchase behavior for helmets and saddles is migrating to virtual consultation and home-trial programs. This channel shift is most visible in California and Texas equestrian corridors where rural buyer density previously sustained independent retail networks.
Global Horse Riding Equipment Market Segmentation
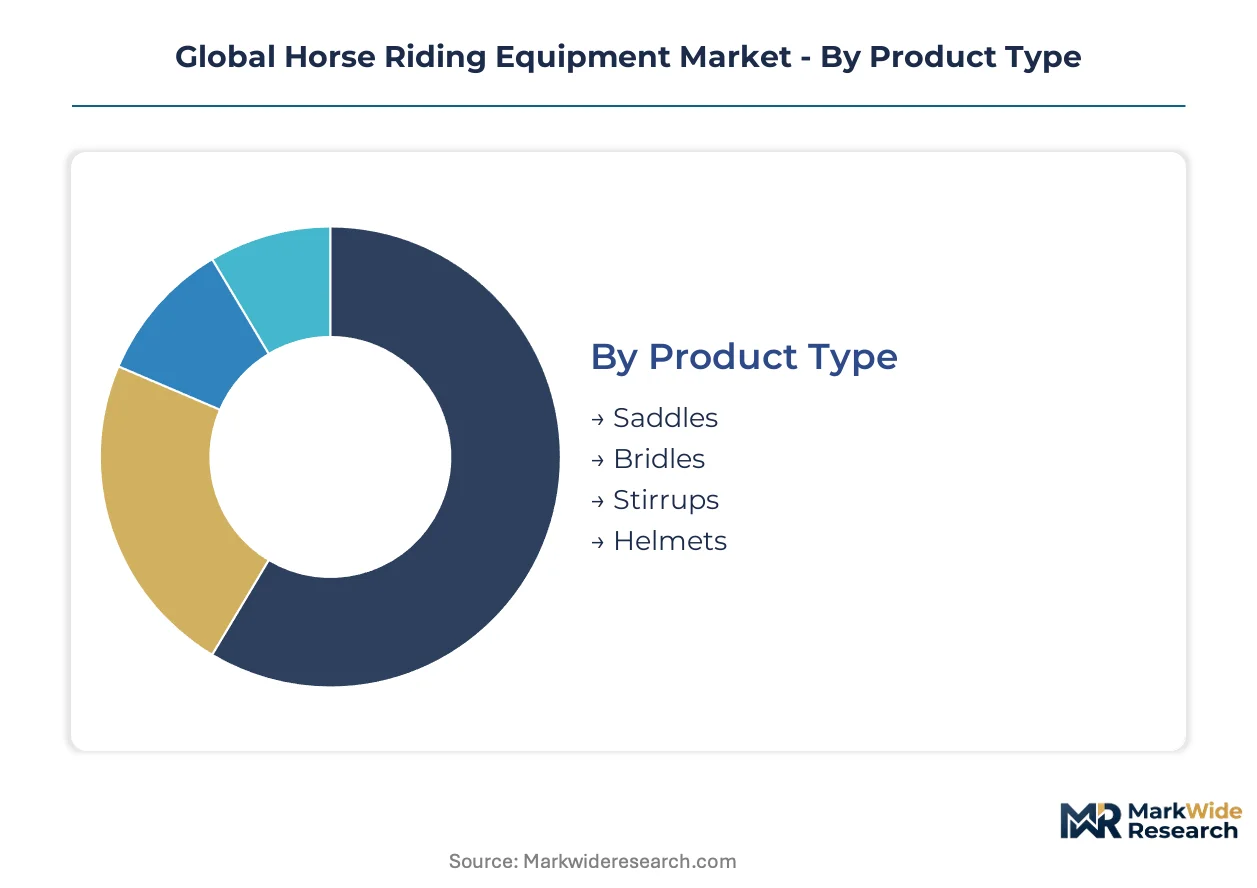
Equipment segmentation in horse riding markets reveals divergent margin structures across protective, functional, and comfort categories. Material composition and end-user sophistication create distinct pricing architectures that manufacturers must navigate through specialized distribution strategies.
Product Type:
Margin pools concentrate in fit-sensitive, safety-critical categories with mandated replacement cycles and technical certification requirements.
- Saddles:Hand-stitched tree construction with adjustable gullet systems distributes rider weight across equine back structures. German and Argentine master saddlers command premium positioning through heritage craftsmanship, while synthetic alternatives penetrate price-accessible leisure channels in Australian wellness tourism corridors.
- Helmets:Multi-density EPS liners bonded to ABS shells must satisfy ASTM impact thresholds in United States markets and CE marking protocols across Europe. Amateur rider entry in California and Texas metropolitan zones drives threefold adoption of basic sensor-integrated models versus professional segments.
- Bridles:Headstall and bit assembly configurations vary by discipline-specific rein control requirements.
- Stirrups:Safety-release mechanisms and composite material construction address fall-prevention specifications.
Saddles hold installed capacity through artisanal production constraints. Helmets are rotating up the share rankings on safety regulation enforcement and replacement cycle compression.
Material:
Cost tier stratification separates heritage-positioned natural inputs from rapidly scaling synthetic alternatives.
- Leather:Vegetable-tanned hides from Italian and Spanish tanneries face fifteen to twenty percent cost elevation under REACH chromium VI restrictions. Full-grain saddle demand concentrates among German competition riders absorbing reformulation premiums rather than passing through to amateur channels.
- Synthetic:Plant-based polyurethane formulations displace petroleum-derived components in bridles and stirrups across French and German retail networks. Decathlon price-accessible lines exploit this material shift to capture leisure rider volume.
- Nylon:High-tensile webbing dominates halter and lead rope construction for training applications.
- Cotton:Breathable textile layers line protective gear for climate-sensitive riding environments.
Leather maintains heritage-premium positioning. Synthetic is climbing the fastest on environmental credential alignment and manufacturing scalability.
Use Case:
Application context determines equipment specification rigor and corresponding margin capture potential.
- Competition:FEI-compliant saddles and protective gear require certified fit assessment and discipline-specific configuration. German and United States elite riders sustain artisanal manufacturer margins through replacement sensitivity and brand loyalty concentration.
- Leisure:Multi-use, fashion-forward equipment specifications diverge from traditional competition-grade requirements. Australian coastal tourism corridors and United States equestrian retreat investments institutionalize rental equipment demand with lower technical barriers.
- Training:Durability-focused construction withstands repetitive use patterns in instructional settings.
- Casual Riding:Entry-level price points accommodate infrequent participation without fit-sensitive customization.
Competition holds installed capacity through certification gatekeeping. Leisure is gaining share fastest on wellness tourism infrastructure expansion.
End User:
Customer type segmentation maps directly to distribution channel configuration and service intensity requirements.
- Professional Riders:Sponsored athletes and elite competitors demand bespoke equipment with direct manufacturer relationships. Ariat International anchors premium leather boot demand through heritage positioning in North American professional circuits.
- Amateur Riders:Leisure enthusiasts represent the steepest expansion trajectory as equestrian sports democratize beyond traditional elite circles. Direct-to-rider digital platforms displace traditional tack shop intermediaries in United States and United Kingdom metropolitan markets.
- Trainers:Certified instructors procure institutional-grade equipment for instructional fleet maintenance.
- Equestrian Centers:ISO 9001 quality management certification functions as procurement gatekeeper for equipment vendors serving United States institutional buyers.
Professional riders hold installed capacity through sponsorship concentration. Amateur riders are rotating up the share rankings on participation democratization and digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German saddle exports flow into United States equestrian centers and Australian wellness tourism operators, establishing a transatlantic trade corridor that shapes procurement standards across both destination markets.
United States
California and Texas metropolitan zones drive amateur rider equipment adoption through digital direct-to-rider platforms displacing traditional tack shops. ASTM International helmet impact standards govern protective gear certification, creating compliance thresholds for imported products. Kentucky's Bluegrass region anchors elite competition saddle demand through concentrated thoroughbred racing infrastructure.
Germany
Master saddler apprenticeship programs in Bavaria and Baden-Württemberg sustain artisanal leather saddle production for FEI-compliant competition riders. REACH chromium VI restrictions under ECHA mandates compel vegetable-tanning process adoption across Italian and Spanish tannery suppliers. The Rhine-Main corridor hosts specialized bridle manufacturers serving both domestic and export channels.
Australia
Queensland and New South Wales coastal tourism corridors institutionalize rental equipment demand through equestrian retreat investments. TGA alignment with ISO safety protocols facilitates equipment import acceptance from European and North American suppliers. Melbourne's metropolitan equestrian clubs generate synthetic material demand among environmentally conscious leisure participants.
United Kingdom
Home counties surrounding London concentrate amateur rider population growth driving fashion-forward multi-use equipment specifications. CE marking under EU Personal Protective Equipment Regulation applies to cross-border trade with Irish suppliers. The Cotswolds region maintains heritage-positioned leather boot demand through established hunt and eventing cultures.
France
Provence-Alpes-Côte d'Azur wellness tourism operators procure price-accessible synthetic lines for seasonal rental fleets. ANSM oversight of product safety standards intersects with EU-wide harmonization pressures. Normandy's competition riding infrastructure sustains premium saddle demand through FEI event hosting and certified instructor concentration.
Global Horse Riding Equipment Market Vendor Landscape
Listed leaders compete with private specialists across heritage craftsmanship and price-accessible synthetic segments. The vendor base stratifies into three tiers: multinational sporting goods conglomerates with diversified equestrian portfolios, regional leather specialists with master saddler credentials, and mass-market retailers exploiting material cost advantages. Strategic archetypes include heritage-positioned artisanal manufacturers, vertically integrated synthetic material innovators, and digital-native direct-to-rider platforms. Competitive moves concentrate on M&A activity targeting master saddler expertise and capacity expansion into plant-based polyurethane formulation.
Among heritage-anchored specialists, Ariat International occupies a position exemplifying premium leather boot positioning in North American amateur channels. Georg Kieffer Sattlerwarenfabrik GmbH represents the master saddler archetype with German GmbH structure signaling artisanal credential concentration. Decathlon sits within the scale-driven sporting goods tier, exploiting synthetic material innovation to capture price-sensitive leisure volume across French and German retail networks.
| Leading Market Players |
|---|
| Dainese |
| Ariat International |
| Decathlon |
| Georg Kieffer Sattlerwarenfabrik GmbH |
| Cavallo GmbH |
| HKM Sports Equipment |
| Antares Sellier |
| Mountain Horse |
| Colonial Saddlery |
| Others |
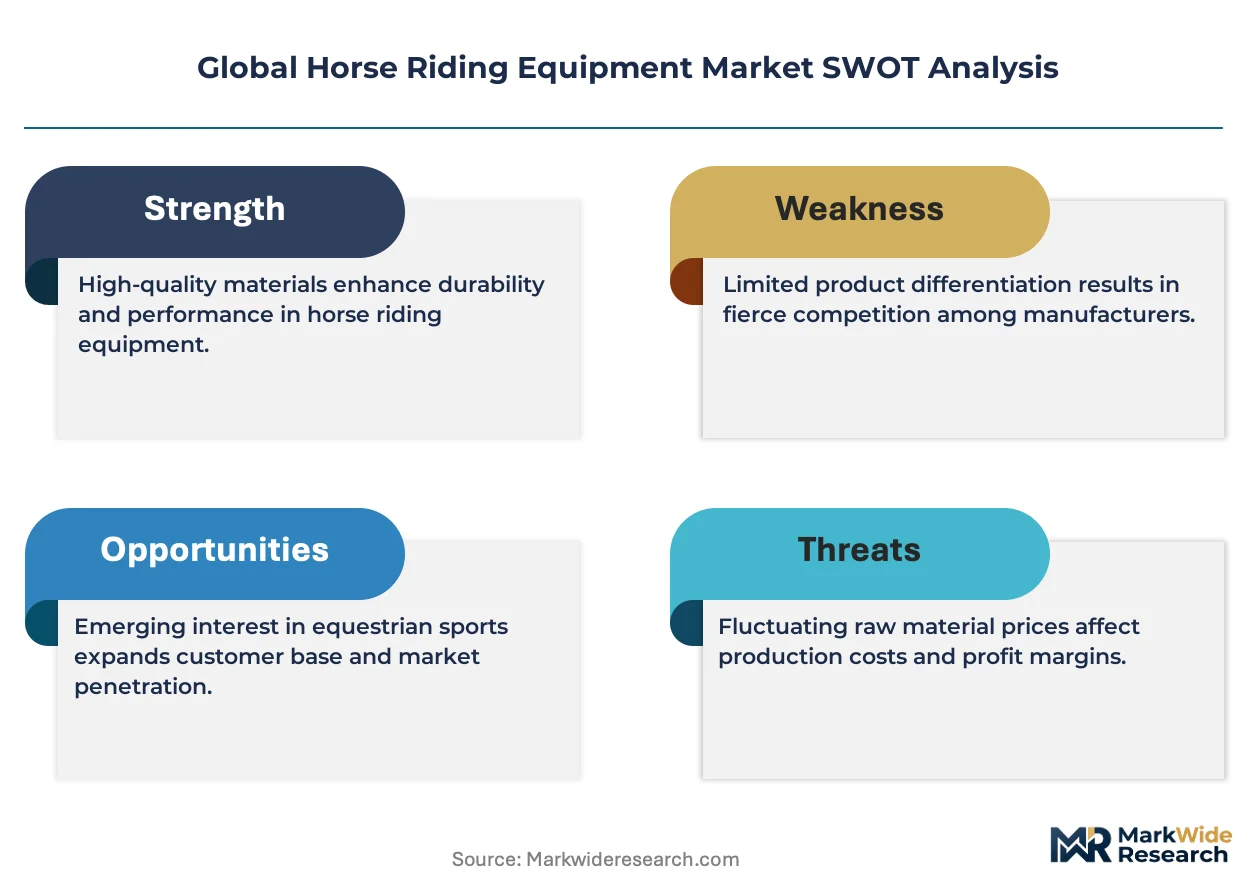
Supply Flow & Price Mechanics
Plant-based polyurethane displacement of petroleum-derived bridle components simultaneously shifts manufacturing gravity toward German and French synthetic specialists while compressing margin capture for traditional leather tanneries facing REACH reformulation costs. This material transition reconfigures pricing power away from heritage-positioned artisans toward scale-driven chemical formulators.
Pricing Analysis
Sensor-integrated helmet pricing diverges sharply from passive designs, with connected performance-tracking units commanding premiums against basic impact-absorption models for leisure riders. Three-tier pricing structure across premium, standard, and economy levels separates FEI-certified competition gear from institutional rental fleets and entry-level casual equipment. Cost compression in synthetic bridles intensifies because plant-based polyurethane manufacturing scales faster than vegetable-tanned leather alternatives. Amateur riders in Australian wellness tourism corridors exhibit highest price sensitivity, while German competition riders absorb heritage premiums with minimal elasticity.
Supply Chain Analysis
Master saddler apprenticeship concentration in Bavaria and Baden-Württemberg creates a chokepoint constraining scalable artisanal saddle production for global competition riders. Raw material flows draw from Italian and Spanish tanneries for vegetable-tanned hides, Argentine and Brazilian full-grain suppliers, and German chemical plants for polyurethane formulations. Single-source vulnerability runs through concentrated master saddler expertise pools in Germany and Argentina. Distribution runs through direct-to-rider digital platforms displacing traditional tack shop networks in United States and United Kingdom metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce hand-stitched tree construction expertise constrains artisanal saddle scalability, creating defensive moats for incumbent heritage manufacturers while opening synthetic substitution pathways for challengers. This capability gap defines competitive positioning across price tiers.
For Market Incumbents: Compound defensive positioning through captive vegetable-tanning capacity in Italian supply bases and ISO 9001 certification investment for United States equestrian center procurement gating. Vertical integration into tannery operations mitigates REACH chromium VI cost volatility threatening margin pools. For New Entrants and Emerging Players: Lead with plant-based polyurethane bridle lines targeting price-sensitive amateur riders in Australian coastal tourism corridors and Indian metropolitan equestrian club formation. Direct-to-rider digital platforms offer lowest-friction go-to-market penetration against established tack shop networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale synthetic material innovators with backward integration into polyurethane formulation and established CE marking pathways for EU market access. Master saddler apprenticeship programs in Germany represent scarce intangible assets with decade-long replication timelines. Watch for REACH enforcement escalation signals indicating accelerated leather tanning cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Master Saddler Apprenticeship Acquisition | Captures scarce hand-stitched tree construction expertise concentrated in Bavaria and Baden-Württemberg. |
| Vegetable-Tanning Capacity Buildout | Secures compliant leather supply ahead of REACH chromium VI restriction tightening across Italian tanneries. |
| Direct-to-Rider Platform Launch | Displaces traditional tack shop intermediaries in California and Texas metropolitan equestrian corridors. |
| Plant-Based Polyurethane R&D Partnership | Accelerates synthetic bridle formulation scaling for price-accessible leisure rider segments. |
| ISO 9001 Certification Investment | Unlocks institutional procurement channels serving United States equestrian center buyers. |
Methodological Framework
The analysis maps protective gear, functional equipment, and comfort-oriented categories, each validated through master saddlers, equestrian center procurement directors, synthetic material R&D leads, and retail channel managers. Primary interview intelligence triangulates against customs trade records for leather and synthetic polymer flows, SEC filings from listed sporting goods conglomerates, REACH compliance databases from ECHA, and ASTM certification registries. Bottom-up equipment unit economics reconcile with top-down market sizing across the projection horizon.
Consistency checks validate volume and value outputs against external benchmarks including equestrian participation surveys, wellness tourism infrastructure investment trackers, and institutional procurement database trends. Segmentation dimensions span product type, material composition, use case application, and end-user archetype across the modeling period. CAGRs derive from equipment replacement cycle analysis, regulatory enforcement trajectory modeling, and amateur rider demographic expansion patterns.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, stable Argentine hide supply, and continued wellness tourism capital deployment would require recalibration. Practitioners should keep alternative scenarios live as regulatory harmonization pressures between ASTM and CE marking protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Riding Gear Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Gym Bag Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Backboard Market
Sports Equipment
Trampoline Market
Sports Equipment
Golf Equipment Market
Sports Equipment
France Artificial Turf Market