
 Bicycle Pumps Market | 2026-2036
Bicycle Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Pumps Market Analytics
REACH compliance is decoupling European market access from low-cost Asian supply, forcing manufacturers to certify base materials and surface coatings for chemical safety. SRAM Corporation leverages its component ecosystem to bundle pump sales with drivetrain upgrades, while Specialized Bicycle Components anchors its premium positioning through in-house pressure-gauge calibration standards. TOPEAK INC competes on manufacturing scale across Taiwan and China, sustaining OEM relationships that supply mass-market retailers in North America and Europe.
A bicycle pump is a mechanical or electromechanical device designed to inflate pneumatic tires by forcing air through a valve stem, typically achieving pressures between 40 and 160 PSI depending on pump type and target application. Floor pumps employ a standing barrel with a base plate and long hose for high-volume, low-effort inflation in workshop or home settings, while hand pumps prioritize portability through telescoping barrels and integrated mounting brackets for on-trail use. Floor pumps occupy the largest volume share due to universal household penetration among regular cyclists, though electric pumps represent the fastest-expanding margin pool as battery-powered units gain traction among e-bike owners seeking roadside convenience. Aluminum barrel construction leads the material split for premium and mid-tier products, with composite materials growing fastest in weight-sensitive road cycling applications where every gram factors into purchase decisions.
The US Consumer Product Safety Commission monitors mechanical failure risks in pump handles and base plates, while the EU Machinery Directive governs electric pump motor safety and electromagnetic compatibility for battery-operated units sold across member states. Japan's Ministry of Economy, Trade and Industry enforces JIS standards for pressure measurement accuracy, creating a certification barrier for uncertified imports in that market. Stakeholders must monitor how diverging national standards for valve compatibility and pressure calibration reshape sourcing strategies and regional product line differentiation.
Market Dynamics
REACH compliance is decoupling European market access from low-cost Asian supply, forcing manufacturers to certify base materials and surface coatings for chemical safety while simultaneously creating tiered sourcing strategies that bifurcate product lines by regulatory jurisdiction.
Growth Catalysts
- EU Green Deal:Public investment into cycling networks across Germany, the Netherlands, and Denmark is expanding the addressable base for pump accessories and replacement units tied to infrastructure buildout.
- Mountain biking:Technical trail riding is pulling demand for high-pressure portable units across North America and Europe, with riders requiring roadside inflation capability for tubeless tire systems.
- E-bike proliferation:Battery-powered electric pumps are gaining traction among e-bike owners seeking roadside convenience without manual effort, creating a new margin pool distinct from traditional mechanical formats.
Market Restraints
- Aluminum price volatility:Barrel construction costs fluctuate with commodity markets, compressing margins for mid-tier manufacturers without long-term supplier contracts or in-house extrusion capability.
- Taiwan-China supply concentration:OEM relationships for mass-market retailers depend on concentrated East Asian manufacturing, exposing buyers to geopolitical friction and shipping cost spikes.
- Pressure calibration limits:Handheld pumps face technical constraints achieving consistent high-pressure output above 120 PSI, restricting adoption in competitive road cycling segments.
Strategic Opportunities
- Active mobility infrastructure:Germany's urban cycling adoption and tour-event density sustain replacement cycles for both floor and handheld pump formats, creating a predictable demand rhythm.
- Composite materials:Weight-sensitive road cycling applications are driving fastest growth in carbon-fiber and polymer barrel construction where every gram factors into purchase decisions.
- Direct-to-consumer channels:Specialty cycling retailers and brand-owned e-commerce are capturing margin previously allocated to mass-market distributors, enabling premium positioning.
Industry Challenges
- Valve standardization delays:Diverging national standards for valve compatibility and pressure calibration force manufacturers to maintain multiple SKU configurations, complicating inventory planning.
- REACH certification timelines:Chemical safety documentation for base materials and surface coatings extends product development cycles by 8-14 months for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Pumps Market |
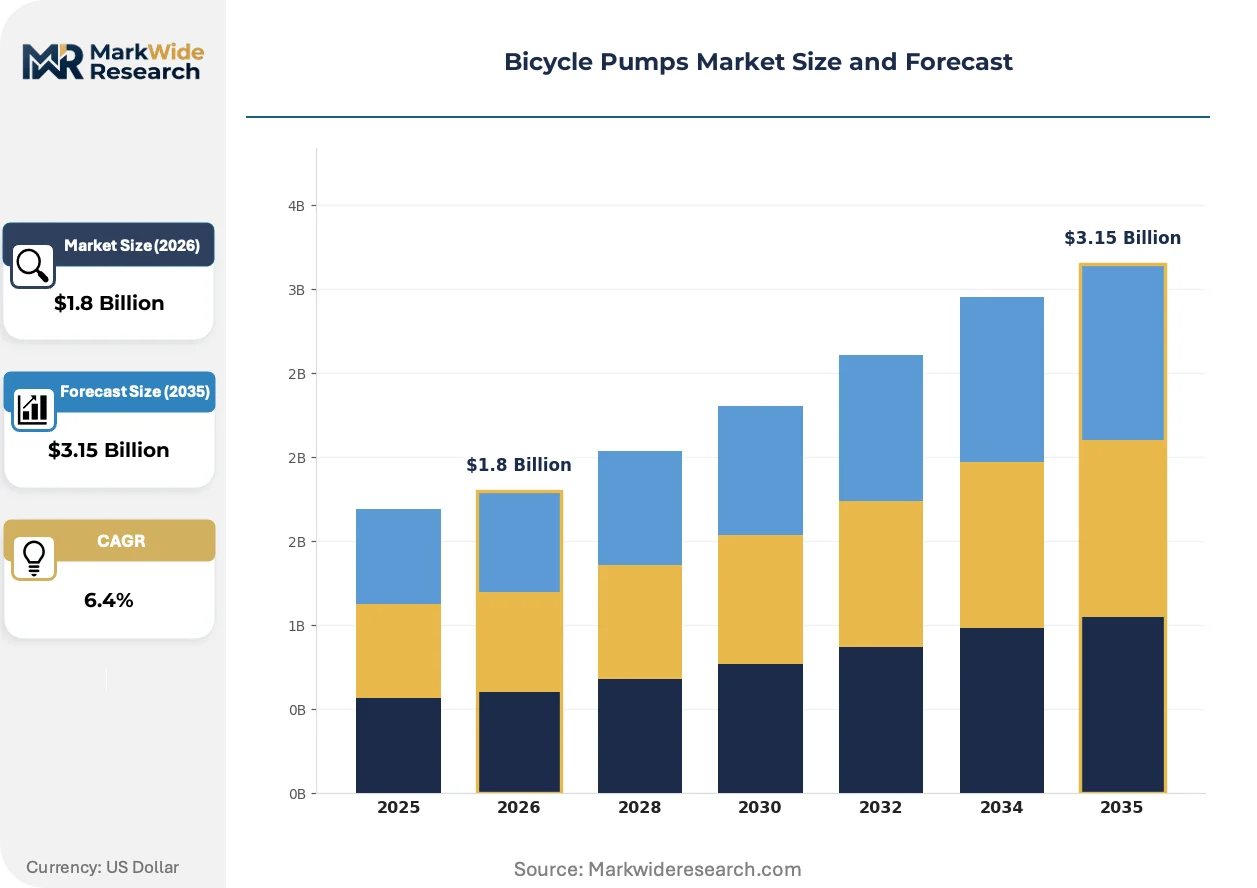
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Floor Pump, Hand Pump, Electric Pump, Cartridge Pump Material: Aluminum, Plastic, Steel, Composite Application: Road Cycling, Mountain Biking, Commuting, Recreational End User: Cyclists, Commercial Retailers, Repair Shops, Event Organizers |
| Companies Covered | SRAM Corporation, Trek Bicycle Corporation, Specialized Bicycle Components, Inc., Lezyne USA, Inc., TOPEAK INC, Zéfal SA, SKS metaplast Scheffer-Klute GmbH, Park Tool Co., Crankbrothers by Selle Royal Group S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Pumps Market Evolving Landscape
Battery-powered inflation systems are rewriting competitive boundaries between workshop-grade and portable equipment, while regulatory divergence across the US, EU, and Japan is fragmenting certification requirements. Distribution channels are compressing as direct-to-consumer models disintermediate traditional sporting goods retail.
Digital pressure sensing with Bluetooth connectivity is rewriting how cyclists monitor tire inflation. E-bike owners and touring cyclists are adopting these units fastest, valuing preset pressure alerts and ride-log integration. This capability is compressing the feature gap between consumer and professional-grade equipment, forcing traditional manufacturers to accelerate electronics integration or retreat to price-driven segments.
REACH chemical safety mandates are tightening surface coating specifications for aluminum barrels sold across EU member states. Manufacturers must now document base material composition through full supply chains or face market exclusion. German and Dutch distributors are responding by consolidating supplier relationships toward vertically integrated producers with captive testing laboratories.
Specialty cycling retailers are capturing share from mass-market sporting goods chains by bundling pump sales with maintenance services and pressure-gauge calibration. This channel shift is most visible in urban centers across Germany and the Netherlands, where cycling infrastructure density supports service-oriented retail formats. Traditional mass-market distributors are responding with private-label sourcing to defend shelf space.
Bicycle Pumps Market Segmentation
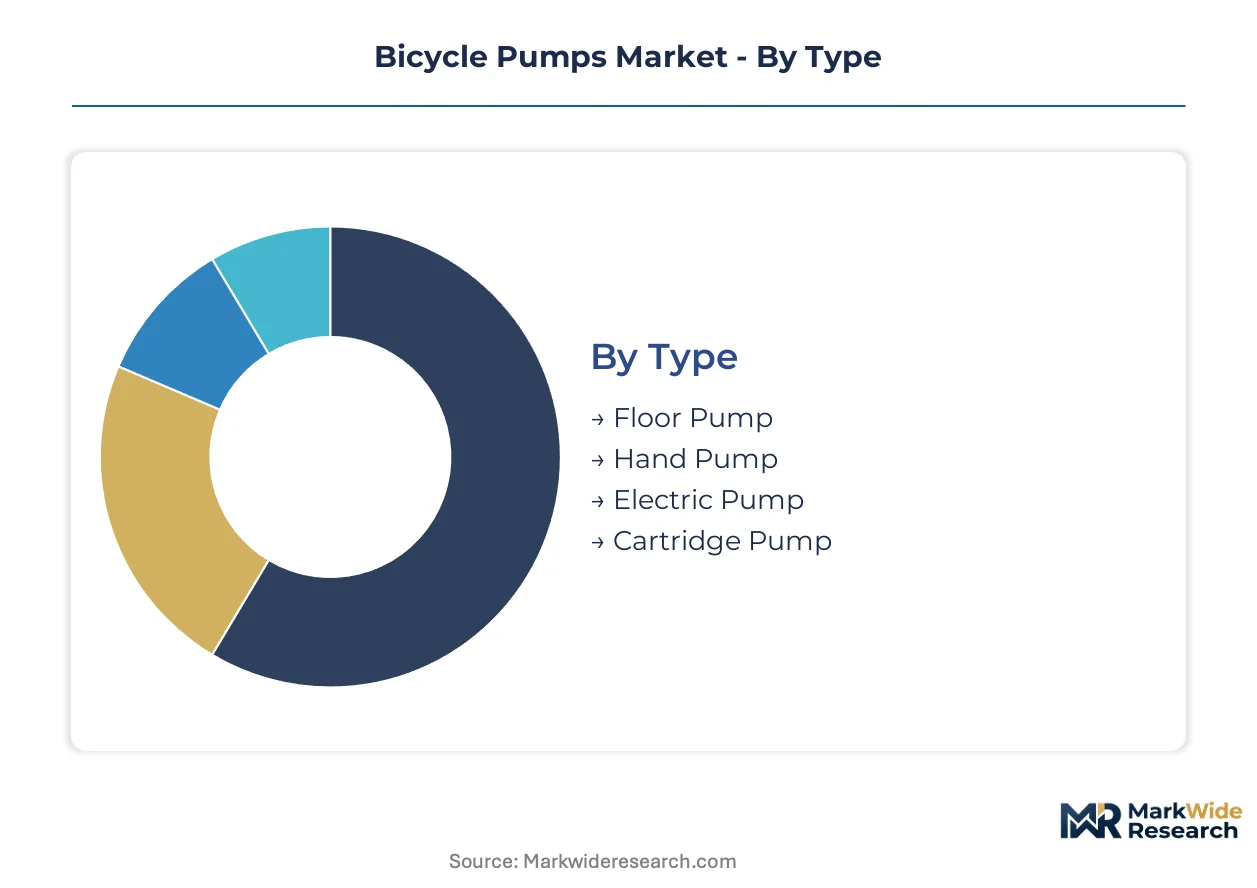
Pump manufacturers must align product architecture with diverging certification requirements across jurisdictions. Segment-level technical specifications determine which regulatory frameworks apply, from EU machinery safety for electric units to pressure calibration standards for precision cycling applications.
Type:
Floor pumps require only general product safety certification in most markets, while electric pumps trigger the full EU Machinery Directive and electromagnetic compatibility testing. Hand pumps face lighter documentation burdens but must still satisfy REACH chemical compliance for barrel coatings sold across Europe.
- Floor Pump:Standing barrel construction with base plate and long hose achieves 40-160 PSI with minimal effort. Demand concentrates in Germany and the Netherlands where urban cycling density sustains household replacement cycles tied to infrastructure buildout.
- Hand Pump:Telescoping barrel with integrated frame mount prioritizes roadside portability. Mountain bikers across Colorado and the Alps pull demand for high-pressure portable units supporting tubeless tire systems on technical trails.
- Electric Pump:Battery-powered motor systems require EU Machinery Directive compliance plus electromagnetic compatibility certification. E-bike owners in Denmark and California adopt these fastest for roadside convenience without manual effort.
- Cartridge Pump:CO2-based inflation delivers rapid pressure without mechanical pumping motion. Weight-sensitive road cyclists favor this format where every gram influences purchase decisions.
Leading the category by volume: Floor Pump. Growing fastest: Electric Pump.
Material:
Raw material selection drives both cost tier positioning and regulatory exposure. Aluminum barrel construction dominates premium and mid-tier products but faces REACH surface coating mandates in Europe, while composite materials escape chemical documentation burdens but carry higher unit economics.
- Aluminum:Extruded barrel construction delivers durability and thermal stability under repeated pressurization. Mid-tier manufacturers without long-term supplier contracts face margin compression from commodity price volatility.
- Plastic:Polymer injection molding enables lowest-cost production at scale. Mass-market retailers in North America source predominantly from Taiwan-based OEM relationships.
- Steel:Chromed barrel construction offers workshop-grade durability for repair shop environments. Demand clusters in commercial settings where equipment longevity outweighs weight considerations.
- Composite:Carbon-fiber and advanced polymer construction targets gram-conscious road cyclists. This segment climbs the fastest as competitive racing applications drive material substitution.
Dominant by production volume: Aluminum. Expanding most quickly: Composite.
Application:
Application segments map directly to pressure requirements and valve compatibility standards. Road cycling demands consistent high-pressure output above 120 PSI where handheld pumps face technical constraints, while mountain biking emphasizes volume delivery and tubeless system compatibility.
- Road Cycling:Narrow tire profiles require precise high-pressure inflation typically above 100 PSI. Competitive segments in France and Italy sustain demand for precision gauge calibration and consistent output performance.
- Mountain Biking:Tubeless tire systems and technical terrain demand volume-focused inflation with roadside repair capability. Trail networks across British Columbia and the Swiss Alps drive portable pump adoption.
- Commuting:Urban utility cycling prioritizes reliability and moderate pressure maintenance. Germany's cycling infrastructure density supports predictable replacement demand for this segment.
- Recreational:Casual cycling applications tolerate lower precision and broader product compatibility. Family-oriented retail channels in the US and UK capture this volume-driven demand.
Highest volume concentration: Road Cycling. Steepest expansion trajectory: Mountain Biking.
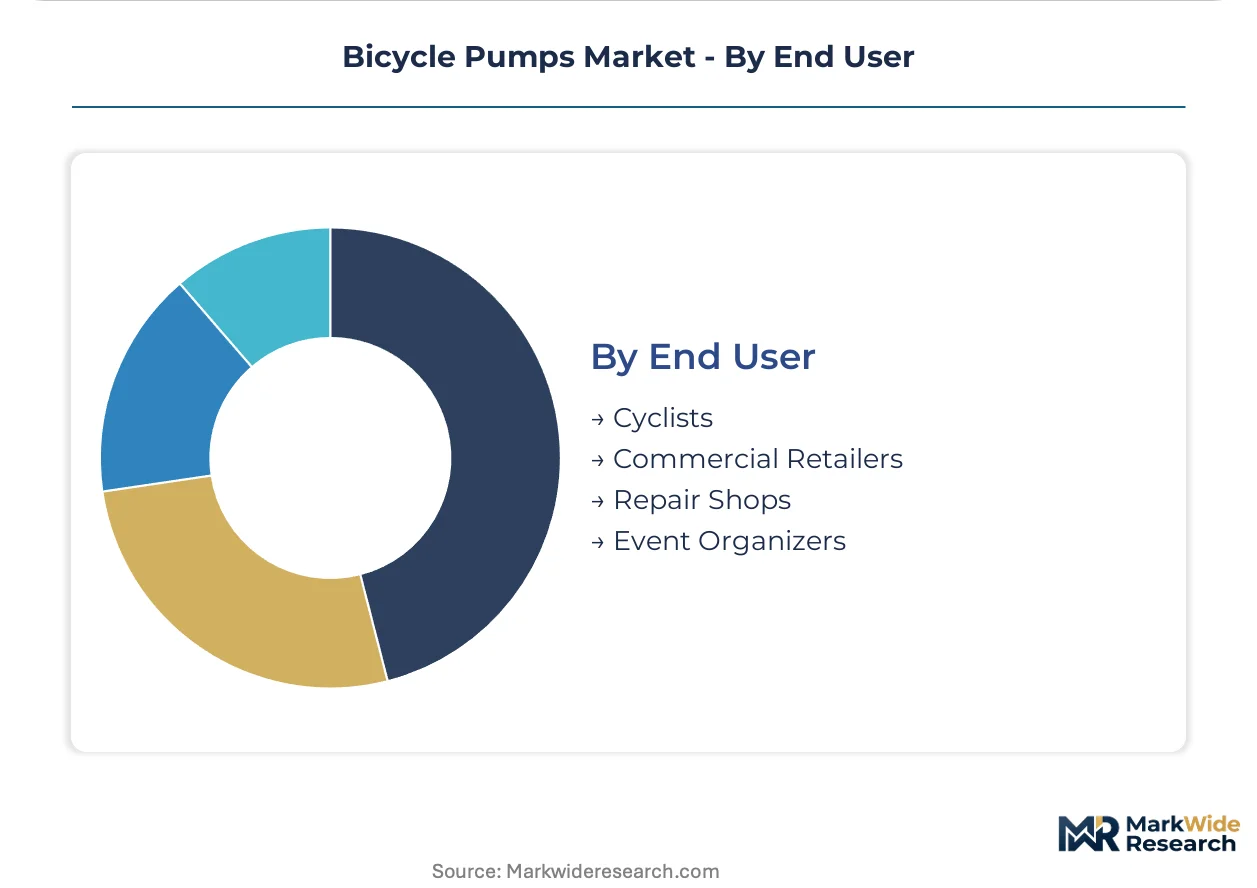
End User:
End user segments determine channel strategy and service bundling requirements. Commercial retailers and repair shops demand bulk pricing and calibration services, while individual cyclists purchase through direct-to-consumer channels with higher margin capture.
- Cyclists:Individual consumers purchase through specialty retailers and brand-owned e-commerce. Germany and the Netherlands show strongest channel shift toward service-oriented retail formats bundling pump sales with maintenance.
- Commercial Retailers:Mass-market sporting goods chains and online marketplaces require private-label sourcing to defend shelf space. Inventory planning complicates from diverging national valve standards forcing multiple SKU configurations.
- Repair Shops:Workshop-grade equipment demands durability and precision calibration standards. Japan's METI enforces JIS pressure measurement accuracy creating certification barriers for uncertified imports.
- Event Organizers:Race and tour operations require portable high-volume inflation for participant support. European tour-event density in Belgium and northern France sustains seasonal procurement cycles.
Capturing largest revenue share: Cyclists. Gaining share fastest: Repair Shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's export processing zones concentrate bicycle component manufacturing, channeling OEM supply toward North American and European distribution networks. Special economic zones in Shenzhen and Dongguan anchor aluminum extrusion and barrel finishing for mass-market pump production.
Germany
Urban cycling infrastructure density in Berlin, Munich, and Hamburg sustains replacement demand for both floor and handheld pump formats. The EU Green Deal channels federal and municipal investment into cycling networks, expanding the addressable base for pump accessories. The Baden-Württemberg industrial cluster hosts precision gauge calibration facilities serving competitive road cycling segments.
United States
Mountain biking trail networks across Colorado, Utah, and the Pacific Northwest pull demand for high-pressure portable units supporting tubeless tire systems. The Consumer Product Safety Commission monitors mechanical failure risks in pump handles and base plates, creating compliance documentation requirements. California's e-bike adoption curve drives fastest uptake of battery-powered electric pumps among roadside convenience seekers.
Netherlands
Cycling infrastructure density in Amsterdam, Rotterdam, and Utrecht supports predictable replacement cycles for commuter-oriented pump formats. National active mobility targets align with EU Green Deal funding streams for cycling network expansion. The Randstad metropolitan corridor concentrates specialty retailers bundling pump sales with maintenance services and pressure-gauge calibration.
Japan
Precision cycling culture in Tokyo, Osaka, and Nagoya sustains demand for high-accuracy pressure measurement equipment. The Ministry of Economy, Trade and Industry enforces JIS standards for pressure measurement accuracy, creating certification barriers for uncertified imports. The Chubu industrial region hosts manufacturing facilities producing workshop-grade equipment for domestic and export markets.
Denmark
E-bike penetration rates in Copenhagen and Aarhus drive adoption of battery-powered electric pumps among riders seeking roadside convenience without manual effort. National carbon neutrality targets accelerate cycling infrastructure investment through 2030. The Zealand island corridor connects urban cycling networks with tour-event density sustaining seasonal procurement cycles.
Bicycle Pumps Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Component ecosystem bundling and manufacturing scale concentration define two dominant strategic archetypes. Premium positioning anchors on in-house calibration standards and direct-to-consumer channel control. Mid-tier manufacturers defend volume through OEM relationships supplying mass-market retailers. Competitive moves concentrate on geographic certification compliance and composite material substitution for weight-sensitive segments.
Among North American-based component integrators, SRAM Corporation and Specialized Bicycle Components occupy positions representing ecosystem bundling and premium calibration strategies respectively. TOPEAK INC anchors the scale-driven manufacturing tier with Taiwan-based production relationships. SKS metaplast Scheffer-Klute GmbH exemplifies the European precision-engineering archetype with German GmbH structure and workshop-grade market orientation.
| Leading Market Players |
|---|
| SRAM Corporation |
| Trek Bicycle Corporation |
| Specialized Bicycle Components, Inc. |
| Lezyne USA, Inc. |
| TOPEAK INC |
| Zéfal SA |
| SKS metaplast Scheffer-Klute GmbH |
| Park Tool Co. |
| Crankbrothers by Selle Royal Group S.p.A. |
| Others |
Value Network & Pricing Analysis
Aluminum extrusion costs cascade through three distinct pricing tiers, with commodity volatility compressing mid-tier margins while REACH-compliant surface coatings command premium positioning in German and Dutch distribution channels.
Pricing Analysis
Short lead-time premiums separate workshop-grade calibration services from spot inventory discounts in mass-market retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden divergence, with EU Machinery Directive compliance adding documentation cost layers to electric pump tiers. Cost compression in mid-tier aluminum barrel segments is intensifying because long-term supplier contracts concentrate among vertically integrated producers. Commercial repair shops show lowest price sensitivity due to calibration service bundling, while family-oriented recreational cyclists drive volume at economy tiers.
Supply Chain Analysis
Dual-sourcing requirements from North American and European OEMs mandate multi-supplier qualification across Taiwan's export processing zones and Shenzhen-Dongguan special economic zones. Manufacturing gravity centers on East Asian aluminum extrusion and barrel finishing, with raw material flows drawing from bauxite refining networks and polymer resin suppliers. Single-source vulnerability concentrates in precision gauge calibration equipment tethered to Baden-Württemberg and Chubu industrial clusters. Distribution runs through specialty cycling retailers capturing margin from mass-market sporting goods chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified coating capacity constraints prop pricing premiums, as REACH documentation timelines extend product development cycles beyond uncertified competitor lead times.
For Market Incumbents: Deepen captive laboratory investments to compress REACH certification timelines from 14 months toward 8-month benchmarks, defending against emerging composite material specialists. Secure backward integration into aluminum extrusion to buffer commodity volatility eroding mid-tier positioning. Channel control through service-oriented retail formats in Germany and the Netherlands protects margin from direct-to-consumer disintermediation. For New Entrants and Emerging Players: Brand-owned e-commerce routes offer lowest barrier entry for electric pump segments where battery system integration demands lighter regulatory documentation than workshop-grade calibration tiers. Target Denmark and California e-bike owner clusters with roadside convenience positioning absent from incumbent mechanical pump portfolios. White-space exists in carbon-fiber barrel construction for gram-conscious road cycling applications. For Investors and Strategic Acquirers: Consolidation of German distributors bundling pump sales with maintenance services is the leading indicator that service-integrated retail formats are capturing durable margin pools. Five-to-ten year viability favors vertically integrated producers with captive testing laboratories over pure-play assemblers exposed to REACH compliance gaps. Monitor aluminum price volatility spikes as inflection signals for margin compression events.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Acceleration | Captive testing laboratories in Baden-Württemberg compress European market entry timelines against Asian competitors. |
| Composite Material Substitution | Carbon-fiber barrel construction targets gram-conscious road cyclists in France and Italy with premium positioning. |
| Direct-to-Consumer Channel Buildout | Brand-owned e-commerce captures margin previously allocated to mass-market sporting goods distributors. |
| Service Bundling Expansion | Specialty retailers in Randstad metropolitan corridor integrate pressure-gauge calibration with pump sales. |
| Electric Pump Platform Development | Battery-powered systems align with Denmark and California e-bike adoption curves for roadside convenience. |
Research Methodology
Trade customs records, EU ECHA registration databases, and bicycle component industry associations formed the secondary backbone, supplemented by primary interviews with pump manufacturing executives, specialty retail buyers, workshop service managers, and aluminum extrusion procurement leads. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Historical trendline analysis across type, material, application, and end-user segmentation dimensions informed projection modeling throughout the forecast period. CAGRs derived from slope-stability testing against infrastructure investment trajectories and regulatory compliance cost curves. E-bike penetration rates and REACH certification timeline data served as industry-specific forecast inputs.
Inputs from ECHA registration databases and Taiwan export processing zone filings were available through the study window; gaps in real-time aluminum spot pricing granularity introduce uncertainty bands around mid-tier margin projections. Deviation in EU Green Deal infrastructure appropriation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Skating Shoes Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Global Rock Climbing Equipment Market