
 Concussion Helmets Market | 2026-2036
Concussion Helmets Market Size, Share, and Industry Trends Forecast 2026-2036
Concussion Helmets Market Analytics
Youth football is decoupling from professional leagues as the primary volume driver for concussion helmets. Xenith leverages its Virginia Tech five-star ratings to anchor premium positioning in high school districts. Riddell competes through its SpeedFlex platform and extensive team-equipment relationships. Schutt sustains manufacturing scale across polycarbonate shell production for budget-conscious athletic programs.
Concussion helmets are protective headgear systems engineered with multi-layer energy-absorbing liners, typically combining expanded polypropylene or vinyl nitrile foam with polycarbonate or carbon fiber shells, designed to attenuate linear and rotational acceleration forces from head impacts. The primary commercial purpose centers on reducing traumatic brain injury incidence in contact sports and tactical training environments. Hybrid helmets represent the fastest-growing product configuration as programs balance protection weight against cost constraints. Carbon fiber material adoption extends into professional and military tiers where gram reduction justifies premium outlay. Smart helmet technology with embedded impact sensors is attracting capital as real-time telemetry reshapes sideline concussion protocols.
NOCSAE maintains baseline performance certification for US-market helmet legality while the FDA oversees emerging sensor-embedded devices making medical claims. Virginia Tech's independent STAR rating system shapes consumer perception and procurement criteria outside formal regulatory mandate. The Consumer Product Safety Commission monitors youth sports equipment recalls with increasing scrutiny on headgear failures. Stakeholders must track how state-level youth sports safety legislation and evolving sensor-data liability frameworks reshape product design requirements and channel economics.
Market Dynamics
Youth league procurement budgets are expanding faster than professional team equipment cycles, creating a volume shift toward high-school and middle-school programs with distinct price-performance requirements and certification-driven purchasing committees.
Growth Catalysts
- Virginia Tech STAR ratings:Independent five-star certification systems now dominate district-level RFP criteria, forcing manufacturers to engineer for measurable impact reduction rather than legacy brand preference.
- Texas youth football expansion:The state's UIL participation growth is concentrating helmet demand in a single procurement corridor with standardized bulk purchasing timelines.
- Polycarbonate shell advances:Thinner-wall molding techniques are reducing helmet weight without sacrificing NOCSAE impact thresholds, enabling longer practice wear times.
Market Restraints
- Carbon fiber input volatility:Aerospace and automotive demand for prepreg composites is compressing supply availability for premium helmet shell production, forcing allocation decisions.
- NOCSAE recertification costs:Biennial laboratory testing requirements impose fixed cost burdens on smaller manufacturers without captive testing facilities.
- Sensor module obsolescence:Embedded impact monitoring hardware faces 18-month replacement cycles as Bluetooth protocols and battery chemistries advance, creating stranded asset risk for early adopters.
Strategic Opportunities
- Florida charter school athletic programs:Private academy sports expansion outside traditional district purchasing is creating direct-to-program sales channels with faster decision cycles.
- Military tactical training crossover:Parachute and breaching simulation programs are adapting football helmet architectures for non-ballistic head protection, opening adjacent volume.
- California concussion protocol mandates:State legislation requiring documented head impact exposure limits is creating compliance-driven replacement demand independent of equipment age.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized expertise in rotational acceleration modeling and finite element analysis for helmet liner design concentrates at a handful of university laboratories.
- Legacy inventory compatibility:New facemask attachment standards and shell geometries are obsoleting existing accessory ecosystems, forcing complete system replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concussion Helmets Market |
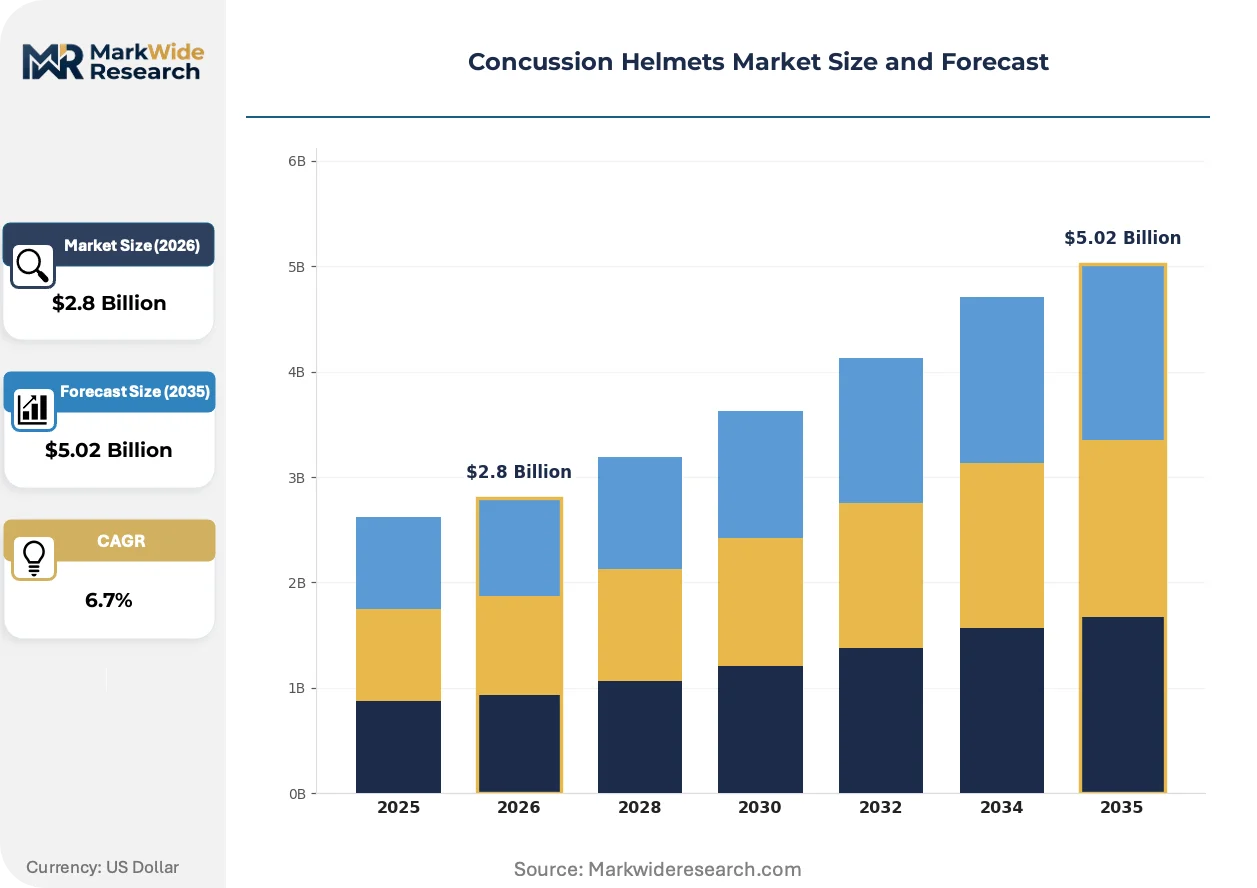
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Face Helmets, Open-Face Helmets, Hybrid Helmets, Youth Helmets Material: Polycarbonate, Carbon Fiber, EVA Foam, Polyurethane End User: Professional Athletes, Amateur Players, Recreational Users, Military Personnel Technology: Impact Sensors, Smart Helmets, Ventilation Systems, Shock Absorption Systems |
| Companies Covered | Xenith, VICIS, LIGHT Helmets, Nike, Under Armour, Riddell, Rocksolid, SG Helmets, Schutt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concussion Helmets Market Evolving Landscape
Real-time telemetry is migrating from sideline diagnostic tools to integrated helmet architecture, while certification standards fragment between baseline legality and premium performance tiers. Material science advances are compressing the protection-to-weight ratio.
Embedded accelerometer arrays with wireless transmission capability are converging with cloud-based impact databases. Collegiate athletic trainers are adopting these systems for immediate removal-from-play decisions. The technology is converging with liability insurance underwriting models, enabling usage-based premium structures that reward documented safer play environments.
The FDA is asserting oversight over helmet-embedded sensors making diagnostic claims, requiring 510(k) clearance pathways previously unnecessary for protective equipment. This regulatory expansion is extending product development timelines by 12-18 months for smart helmet variants. Professional and Division I programs are absorbing these delays; youth market entrants are retreating to sensor-free configurations.
California school districts are consolidating purchasing through cooperative procurement organizations, compressing vendor count and extending contract durations. Independent equipment dealers are losing access to volume accounts as Riddell and Xenith establish direct district relationships. This channel compression is most visible in Los Angeles and San Diego unified districts, where three-year sole-source agreements now predominate.
Concussion Helmets Market Segmentation
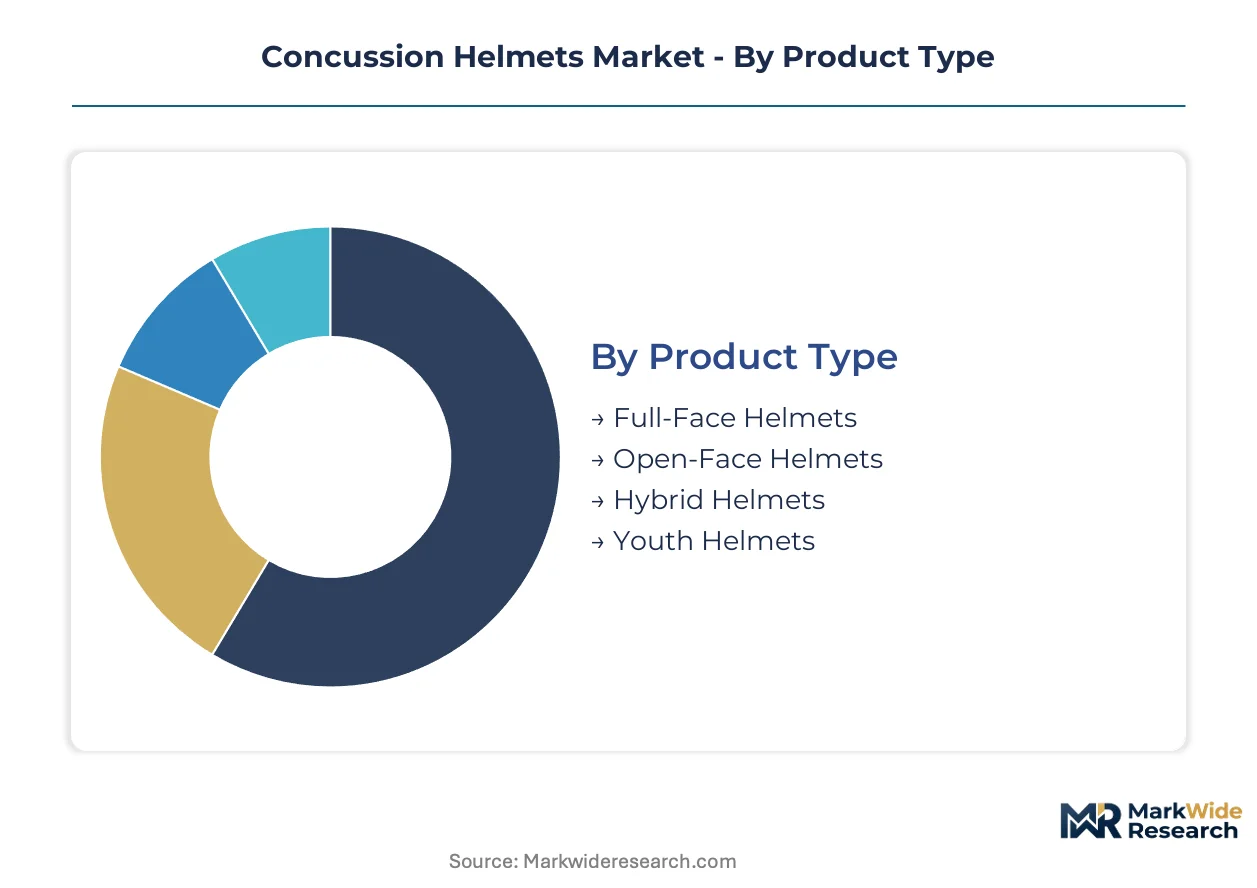
Helmet procurement committees weight certification tier against per-unit cost differently across age brackets and competitive levels. Material selection and embedded technology choices fragment the addressable market into distinct price-performance bands with separate channel economics.
Product Type:
League regulations and player age dictate shell coverage requirements and facemask integration standards.
- Full-Face Helmets:Integrated jaw protection and extended polycarbonate shell coverage address NOCSAE mandible impact thresholds. Texas UIL high school programs concentrate procurement volume here due to mandatory facemask specifications.
- Hybrid Helmets:Combining modular facemask attachment with adjustable liner systems, these configurations balance protection weight against cost constraints. Florida charter school athletic programs are expanding orders fastest as private academies seek flexible equipment pools.
- Open-Face Helmets:Reduced shell coverage serves flag football and seven-on-seven summer leagues with lighter impact exposure profiles.
- Youth Helmets:Scaled shell geometries and softer liner durometers accommodate developing cranial structures in middle-school programs.
Volume sits with Full-Face Helmets; growth tilts toward Hybrid Helmets.
Material:
Shell composition determines weight-to-protection ratios and manufacturing cost structures.
- Polycarbonate:Injection-molded thermoplastic shells dominate high school and youth procurement through cost-efficient mass production. California unified districts specify polycarbonate for bulk replacement cycles under cooperative purchasing agreements.
- Carbon Fiber:Prepreg composite layup achieves gram reduction critical for professional and Division I programs. Aerospace demand for carbon fiber prepreg is compressing supply availability and forcing allocation decisions among helmet manufacturers.
- EVA Foam:Closed-cell ethylene-vinyl acetate liners provide baseline energy absorption for entry-level helmet configurations.
- Polyurethane:Varying density formulations enable tunable impact response in multi-layer liner systems.
Procurement volume concentrates in Polycarbonate; Carbon Fiber commands the steepest expansion trajectory among premium tiers.
End User:
Risk tolerance and budget authority separate institutional buyers from individual purchasers.
- Professional Athletes:NFL and CFL equipment staffs prioritize Virginia Tech five-star ratings and custom-fit liner systems. Individual contract provisions often mandate specific helmet models.
- Amateur Players:High school and collegiate programs drive replacement demand through state concussion protocol mandates. California legislation requiring documented head impact exposure limits is creating compliance-driven procurement independent of equipment age.
- Recreational Users:Adult flag football and touch leagues purchase through retail channels with limited certification scrutiny.
- Military Personnel:Parachute and breaching simulation programs are adapting football helmet architectures for non-ballistic head protection, opening adjacent volume outside traditional sports channels.
Amateur Players account for the largest installed base; Military Personnel represents the most rapidly developing demand corridor.
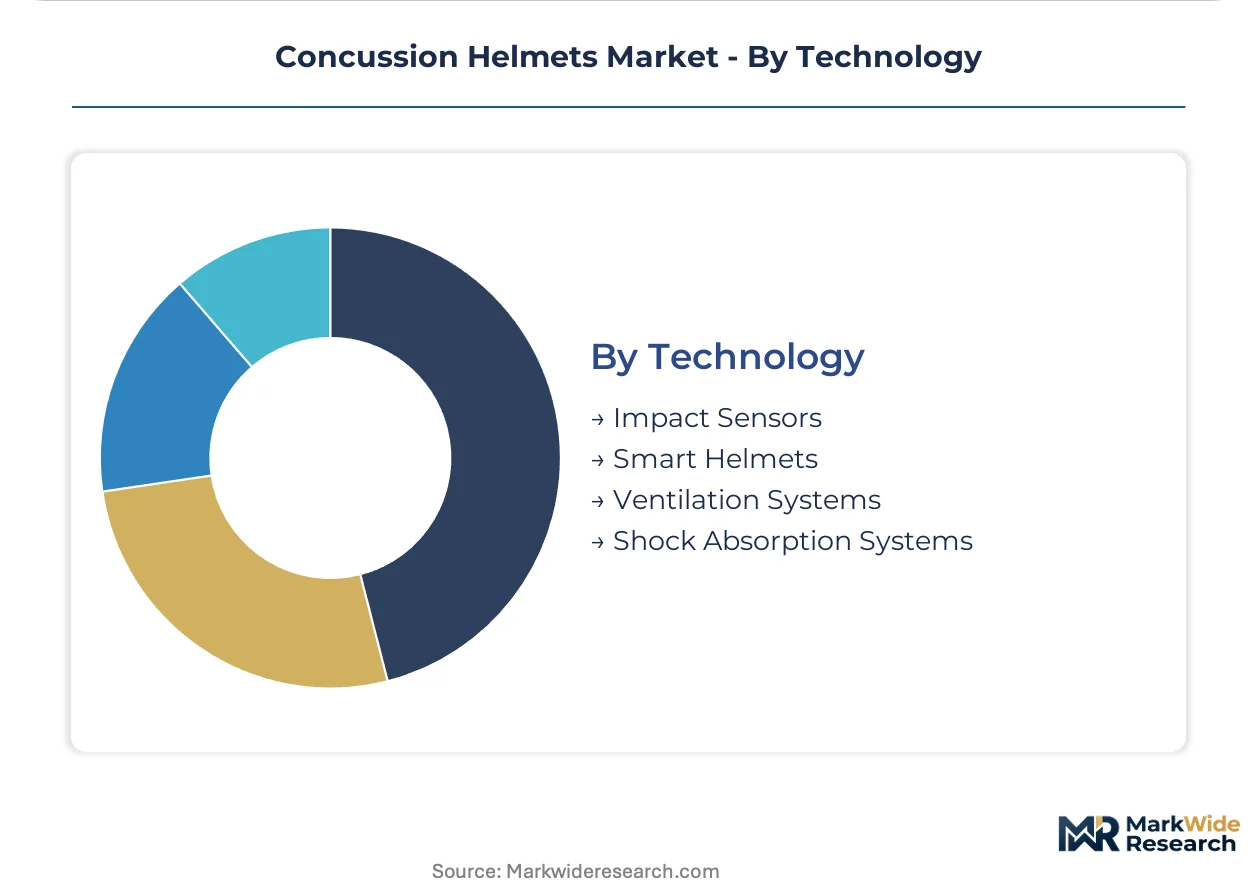
Technology:
Embedded systems are bifurcating the market between sensor-enabled premium tiers and standard protective configurations.
- Impact Sensors:Accelerometer arrays with wireless transmission enable real-time telemetry for immediate removal-from-play decisions. FDA 510(k) clearance requirements are extending development timelines by 12-18 months for diagnostic-claim variants.
- Smart Helmets:Integrated impact databases and cloud connectivity converge with liability insurance underwriting models. Professional and Division I programs absorb these costs; youth market entrants retreat to sensor-free configurations.
- Ventilation Systems:Engineered airflow channels extend practice wear times in hot-climate states.
- Shock Absorption Systems:Multi-layer liner architectures combining expanded polypropylene and vinyl nitrile foams attenuate linear and rotational acceleration forces.
Shock Absorption Systems anchor current volume; Smart Helmets are gaining share fastest as telemetry reshapes sideline protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Enterprise Zones and California Foreign Trade Zones concentrate helmet manufacturing incentives, drawing polycarbonate molding operations and testing laboratories into corridor economies with expedited customs processing and property tax abatements.
United States
Texas UIL expansion and Florida charter school athletic growth concentrate procurement volume in the Southeast and Southwest corridors. NOCSAE maintains biennial recertification mandates that shape manufacturer compliance costs. Dallas-Fort Worth hosts the densest cluster of helmet testing facilities serving district-level purchasing committees.
Canada
Provincial youth rugby and hockey-to-football crossover athletes expand addressable demand beyond traditional American football boundaries. Health Canada monitors equipment safety recalls with increasing scrutiny on headgear failures. Toronto's composite materials research institutes supply finite element analysis expertise to liner engineering programs.
Germany
Automotive carbon fiber prepreg suppliers divert allocation toward aerospace contracts, compressing availability for premium helmet shell production. REACH chemical safety standards regulate foam liner material composition. Bavaria's technical universities anchor rotational acceleration modeling research partnerships with equipment manufacturers.
Japan
American football participation growth in Kansai corporate leagues creates niche demand for Virginia Tech five-star rated configurations. METI industrial standards influence material import specifications for polycarbonate resin. Osaka's precision molding sector supplies thin-wall shell fabrication technology to regional licensees.
Australia
Gridiron football expansion in New South Wales and Victoria private schools imports US certification protocols into Commonwealth procurement frameworks. The TGA asserts oversight over sensor-embedded helmets making diagnostic claims. Sydney's sporting goods distribution hubs consolidate Oceania fulfillment for polycarbonate-based youth configurations.
Concussion Helmets Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary design houses capturing premium tiers while OEM fabricators supply private-label volume. The vendor base concentrates around three archetypes: Virginia Tech five-star rated engineering specialists, polycarbonate mass-production scale players, and carbon fiber premium-tier niche operators. M&A activity targets sensor technology startups, while capacity expansion focuses on automated polycarbonate shell molding lines in enterprise zone locations.
Within the engineering-specialist tier, Xenith and VICIS exemplify certification-driven positioning, with Xenith anchoring Virginia Tech five-star procurement criteria and VICIS occupying the multi-layer liner innovation vector. Riddell represents the scale-driven archetype, leveraging extensive team-equipment relationships across institutional purchasing channels. Schutt sits within the manufacturing-efficiency tier, sustaining polycarbonate production volume for budget-conscious athletic programs.
| Leading Market Players |
|---|
| Xenith |
| VICIS |
| LIGHT Helmets |
| Nike |
| Under Armour |
| Riddell |
| Rocksolid |
| SG Helmets |
| Schutt |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in polycarbonate shell production anchor supply concentration while enforcing pricing discipline through volume commitments and captive testing facility investments. Their consolidated ownership patterns compress supplier counts in Texas and California enterprise zones, translating procurement leverage into tiered contract structures that reward multi-year district agreements with per-unit discounts.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to rush orders outside standard Texas UIL procurement windows, while spot inventory from discontinued shell geometries trades at clearance discounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by Virginia Tech STAR certification tier and embedded sensor capability. Cost compression in polycarbonate configurations is intensifying because thinner-wall molding techniques reduce material input requirements. California unified districts exhibit highest price sensitivity due to cooperative purchasing consolidation, whereas NFL equipment staffs show least sensitivity as individual player contracts mandate specific helmet models regardless of unit cost.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Los Angeles anchor hub-and-spoke patterns that consolidate last-mile delivery to school districts. Manufacturing concentrates in China for polycarbonate resin injection molding, Mexico for facemask metal stamping, and the United States for final assembly and NOCSAE certification testing. Raw material dependencies draw from Saudi Arabia for polycarbonate feedstock, Japan for precision accelerometer components, and Germany for carbon fiber prepreg. Single-source vulnerability sits with aerospace allocation decisions for carbon fiber supply. Distribution runs through independent equipment dealers losing share to direct manufacturer-district relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time telemetry systems are displacing legacy sideline diagnostic protocols, creating product architecture transitions that favor sensor-integrated helmet platforms over standard protective configurations. This technology replacement cycle compresses development timelines and recertification burdens unevenly across manufacturer tiers.
For Market Incumbents: Lock in Virginia Tech five-star certification maintenance as a defensive moat against emerging sensor-technology entrants, while securing backward integration into polycarbonate resin supply through long-term offtake agreements with Saudi petrochemical producers. Carbon fiber allocation pressure from aerospace demand represents the primary margin threat requiring supply chain hedging. For New Entrants and Emerging Players: Florida charter school athletic programs outside traditional district purchasing structures offer the most penetrable white-space target, with faster decision cycles and flexible equipment pool requirements enabling direct-to-program sales channels. Military tactical training programs adapting football helmet architectures for parachute and breaching simulation present a second adjacent volume corridor. A go-to-market angle emphasizing modular facemask compatibility with existing accessory ecosystems reduces switching costs for budget-conscious buyers. For Investors and Strategic Acquirers: FDA 510(k) clearance grants for diagnostic-claim sensor helmets are the leading indicator that smart helmet platforms have crossed regulatory viability thresholds for premium-tier positioning. Long-term viability over a five-to-ten year window favors manufacturers with captive testing facilities and established district-level relationships over pure-technology sensor startups. Acquisition target archetype: sensor-technology startups with cloud-based impact database infrastructure but lacking manufacturing scale. The signal to watch is California legislation mandating documented head impact exposure limits triggering compliance-driven replacement cycles independent of equipment age.| Strategic Initiative | Industry Significance |
|---|---|
| Virginia Tech STAR Certification Investment | Five-star ratings now dominate district RFP criteria, forcing engineering prioritization toward measurable impact reduction metrics. |
| Direct District Relationship Establishment | Three-year sole-source agreements in Los Angeles and San Diego unified districts are compressing independent dealer channel access. |
| Sensor Technology Platform Integration | FDA 510(k) clearance pathways extend development timelines but enable convergence with liability insurance underwriting models. |
| Carbon Fiber Supply Agreement Structuring | Aerospace allocation decisions for prepreg composites require long-term contracts to secure premium helmet shell production capacity. |
| Military Tactical Training Market Entry | Parachute and breaching simulation programs are adapting football helmet architectures for non-ballistic head protection volume. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with athletic equipment procurement directors, NOCSAE laboratory testing managers, high school athletic trainers, and district-level purchasing committee members validated demand-side assumptions. Secondary sources included NOCSAE certification databases, Virginia Tech STAR rating publications, Texas UIL participation statistics, California Department of Education procurement records, and FDA 510(k) clearance filings for sensor-embedded devices. Bottom-up unit demand modeling across youth, high school, collegiate, and professional tiers was triangulated against top-down market value estimates derived from manufacturer revenue disclosures and distributor channel checks.
Data-stream reconciliation across shipment volumes, certification testing records, and district procurement databases informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled included product type, shell material composition, end-user category, and embedded technology tier. CAGRs were derived from trend extrapolation of historical procurement patterns adjusted for state-level concussion protocol mandate implementation schedules. Industry-specific forecast inputs incorporated polycarbonate resin price indices and carbon fiber aerospace allocation ratios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA regulatory expansion timelines, carbon fiber supply availability shifts, and state-level youth sports safety legislation adoption rates. Outputs reflect documented assumptions regarding Virginia Tech STAR rating influence on procurement criteria and cooperative purchasing organization consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Mountain Bicycle Fork Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Running Gear Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Bowling Lane Panels Market