
 Airlaid Textile Market | 2026-2036
Airlaid Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Airlaid Textile Market Outlook
A capital-intensity divergence between integrated pulp-to-fabric operators and merchant airlaid converters is unwinding competitive stability across the sector. Glatfelter leverages captive wood pulp supply and multi-continent mill networks to sustain cost advantages in absorbent pad grades. McAirlaid's Vliesstoffe anchors European medical demand through specialized latex-bonded and thermal-bonded capacity near German hygiene clusters.
Airlaid textiles are nonwoven structures formed by dispersing cellulose or synthetic fibers in air, then bonding them with latex, thermal, or hydrogen bonding to create absorbent, low-density webs with high bulk-to-weight ratios. The process yields materials engineered for rapid liquid acquisition and retention, serving hygiene cores, medical pads, and food-soaking applications. Absorbent pads dominate value generation due to diaper and adult incontinence demand, while wipes compete on sustainability credentials as brands shift from spunlace to airlaid substrates. Nonwoven fabrics occupy mature volume positions in industrial filtration and home textile interlinings where margin pools remain thin.
FDA biocompatibility requirements and EU REACH chemical restrictions shape product formulations and market access for medical and hygiene grades. EPA effluent guidelines and OSHA dust exposure limits govern U.S. pulp processing and fiber handling operations, raising compliance costs for non-integrated producers. Stakeholders must monitor cellulose cost volatility against synthetic fiber substitution economics while tracking regulatory tightening on disposable product biodegradability across multiple jurisdictions.
Market Dynamics
EU REACH chemical restrictions and the EU Green Deal's single-use plastics directives are compressing formulation flexibility for airlaid producers, forcing simultaneous retooling of fiber sourcing, bonding chemistry, and end-of-life biodegradability across European supply chains.
Growth Catalysts
- Adult Incontinence Demographics:Aging populations in Germany and Japan are expanding absorbent pad volumes for medical and hygiene applications.
- EU Green Deal Mandates:Biodegradability requirements under the single-use plastics directive are accelerating substitution of synthetic fibers with cellulose-based alternatives.
- Latex-Bonding Process Refinement:Thermal-bonding technology improvements are reducing energy intensity in high-bulk web formation for hygiene cores.
Market Restraints
- Wood Pulp Cost Volatility:Integrated pulp-to-fabric operators capture margin advantages that merchant converters cannot match, squeezing non-integrated players.
- Bonding Chemistry Constraints:FDA biocompatibility requirements limit latex formulation options for medical-grade airlaid pads entering U.S. healthcare channels.
- Spunlace Substitution Threat:Wet-laid nonwoven alternatives compete on softness and sustainability credentials in premium wipes segments.
Strategic Opportunities
- Indian Hygiene Penetration:Low per-capita diaper consumption creates expansion potential for airlaid absorbent cores as disposable income rises.
- Food-Soaking Applications:Meat and poultry packaging absorbents represent an underdeveloped end-use with specific liquid retention requirements.
- CSRD Reporting Alignment:EU corporate sustainability disclosure rules favor suppliers with certified fiber traceability and carbon footprint transparency.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Parallel FDA, EMA, and ANVISA biocompatibility approvals delay medical-grade product launches by 18-24 months.
- Legacy Hydrogen Bonding Equipment:Capital-intensive reactor upgrades for thermal-bonding capacity strain mid-tier producers' balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airlaid Textile Market |
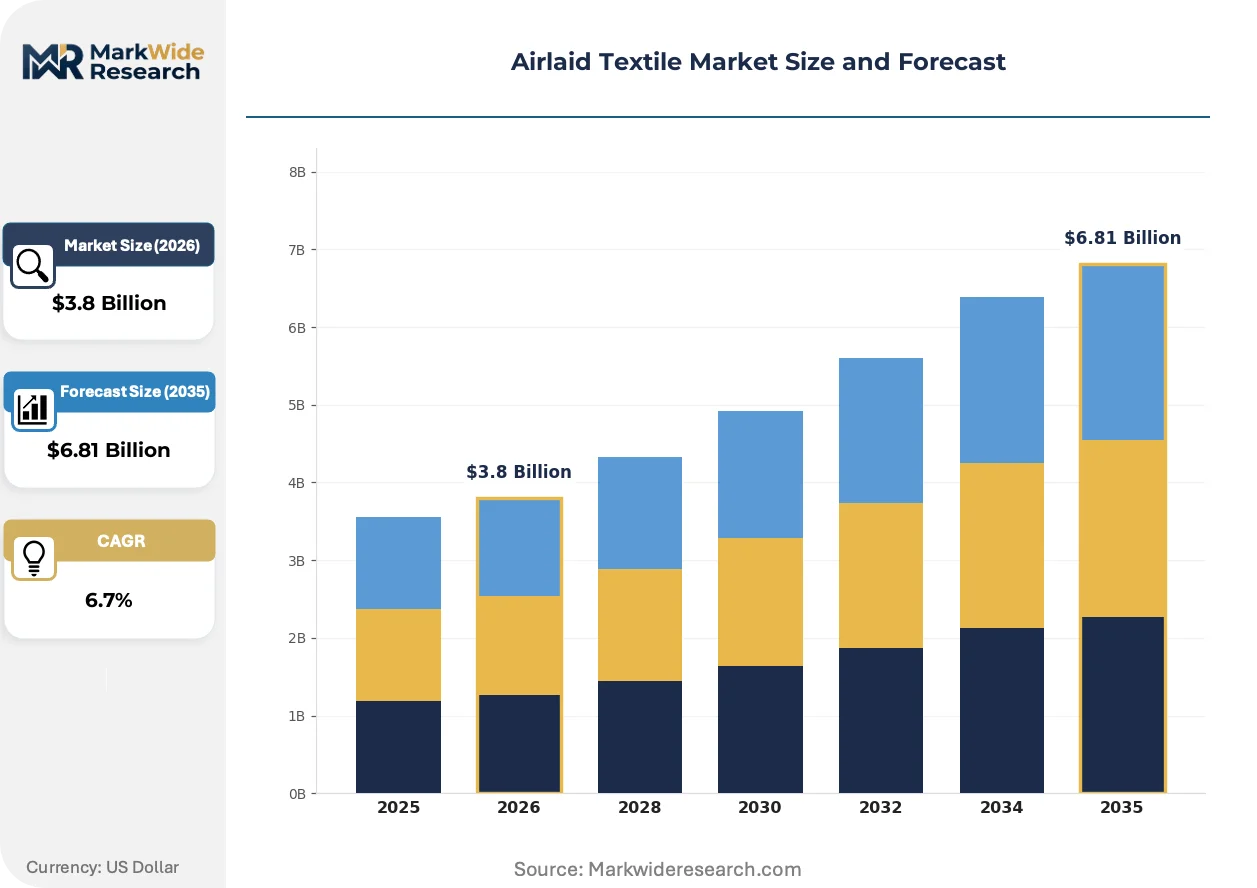
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonwoven Fabrics, Absorbent Pads, Table Covers, Wipes End User: Medical, Hygiene, Industrial, Home Textiles Application: Personal Care, Cleaning, Food Packaging, Protective Gear Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Glatfelter, McAirlaid's Vliesstoffe, Georgia-Pacific, EAM Corporation, Duni AB, Fitesa, M&J Airlaid Products, Oji Kinocloth, Main S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airlaid Textile Market Strategic Shifts
Biodegradable fiber engineering and regulatory chemistry restrictions are rewriting material specifications across hygiene, medical, and industrial airlaid segments simultaneously.
Cellulose microfiber densification technology is miniaturizing fiber diameter distributions while maintaining bulk-to-weight ratios critical for rapid liquid acquisition. Premium diaper manufacturers in Germany and the Netherlands are adopting these refined substrates for next-generation core designs. The structural consequence is compressing demand for conventional fluff pulp grades that cannot meet the new performance thresholds.
EU REACH Annex XVII restrictions on formaldehyde-releasing agents are eliminating legacy latex crosslinkers from hygiene-grade bonding formulations. Manufacturers serving European medical segments must reformulate with alternative chemistries or lose market access. German producers near Stuttgart and Saxony are investing in pilot lines for citric acid-based bonding systems to maintain compliance.
Hospital procurement consortia are consolidating absorbent product specifications around single-source contracts with full lifecycle documentation. This behavior is displacing fragmented purchasing through regional distributors in France and Belgium. The shift is most visible in acute care networks where infection control protocols now mandate batch-traceable airlaid supply chains.
Airlaid Textile Market Segmentation
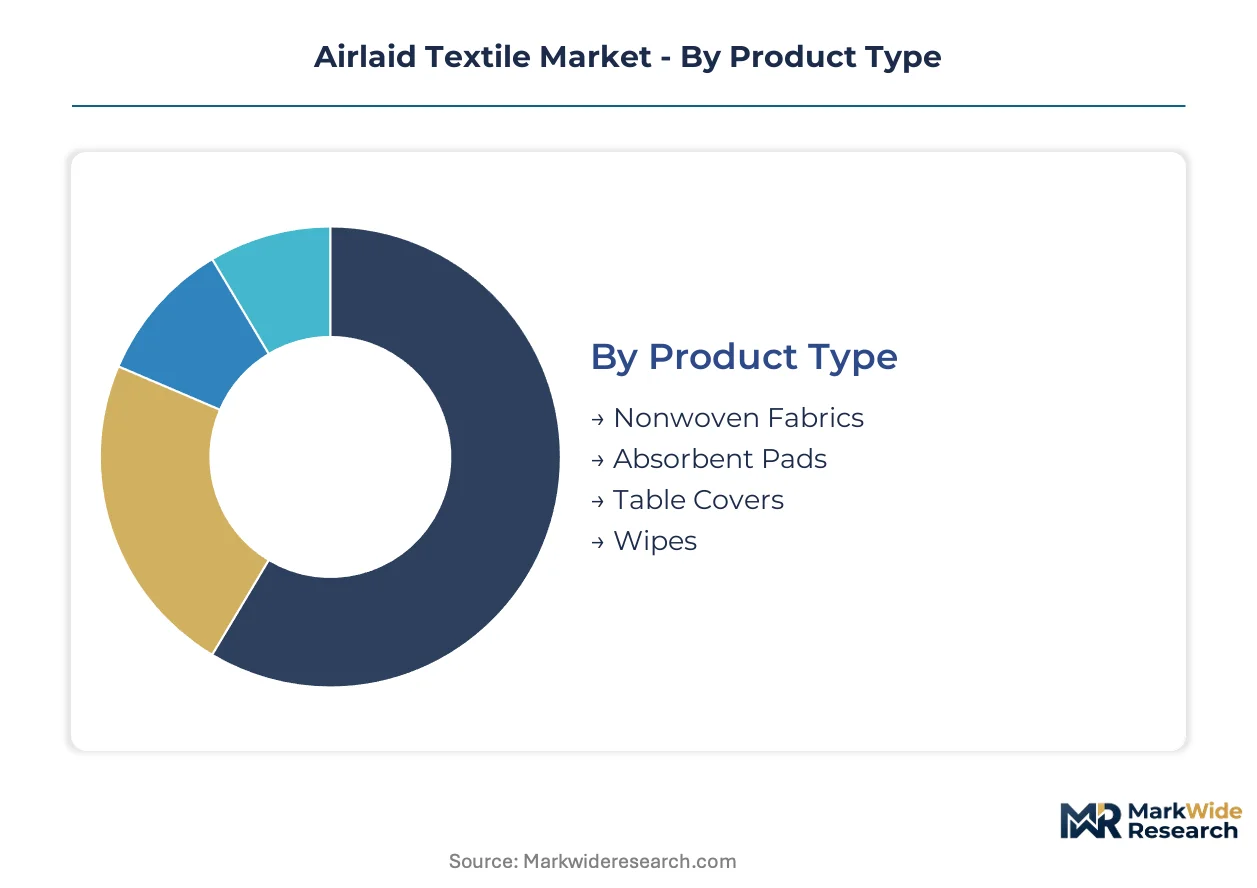
Airlaid textile segmentation reveals how bonding chemistry, fiber sourcing, and end-use certification requirements fragment manufacturing capabilities. Producers must align equipment configurations with specific regulatory pathways rather than pursuing universal product platforms.
Product Type:
FDA biocompatibility rules and EU REACH chemical restrictions create divergent compliance burdens across product categories, with medical and hygiene grades facing the strictest formulation controls.
- Absorbent Pads:High-bulk cellulose webs bonded through latex, thermal, or hydrogen processes form the core technology for liquid acquisition and retention. Demand concentrates in German hygiene clusters serving adult incontinence and diaper manufacturers, driven by aging demographics and EU Green Deal biodegradability mandates.
- Wipes:Low-density airlaid substrates compete with spunlace alternatives on sustainability credentials as brands eliminate plastic content. Adoption accelerates in the Netherlands and Belgium where retail chains enforce single-use plastics directive compliance through procurement specifications.
- Nonwoven Fabrics:Industrial filtration and home textile interlinings utilize mature thermal-bonded capacity with thin margin pools.
- Table Covers:Disposable food-service applications require grease-resistant latex formulations facing EU REACH Annex XVII scrutiny.
Established volume favors absorbent pads; emerging adoption favors wipes.
End User:
Cost tier differentiation separates integrated pulp-to-fabric operators from merchant converters across end-use segments.
- Hygiene:Diaper and adult incontinence manufacturers in Germany and Japan specify cellulose microfiber grades for next-generation core designs with rapid liquid acquisition. Procurement consortia are consolidating around single-source contracts with full lifecycle documentation.
- Medical:Hospital networks in France and Belgium mandate batch-traceable supply chains for infection control, displacing fragmented distributor purchasing. FDA biocompatibility requirements limit latex formulation options for U.S. market entry.
- Industrial:Filtration and absorbent applications serve mature volume positions with limited pricing power.
- Home Textiles:Interlining and decorative applications compete with alternative nonwoven technologies on cost.
Margin concentration sits with hygiene; regulatory complexity peaks in medical.
Application:
Application segmentation tracks how liquid retention specifications vary across end-use environments.
- Personal Care:Diaper cores and feminine hygiene products require optimized fiber diameter distributions for rapid acquisition. German premium manufacturers adopt cellulose microfiber densification technology that compresses demand for conventional fluff pulp grades.
- Food Packaging:Meat and poultry absorbents represent underdeveloped demand with specific retention requirements for blood and exudate management.
- Cleaning:Industrial and household wipes compete on disposability credentials against reusable alternatives.
- Protective Gear:Medical and industrial protective applications require breathable barrier properties with limited airlaid penetration.
Personal care commands the steepest expansion trajectory; food packaging offers untapped specification development.
Distribution Channel:
Customer type segmentation reveals how procurement centralization is restructuring channel economics.
- Wholesale Distributors:Traditional channel serving regional hygiene manufacturers and industrial converters with fragmented purchasing patterns.
- Direct Sales:Hospital procurement consortia and multinational hygiene brands negotiate single-source contracts with integrated producers.
- Online Retail:Emerging channel for specialty wipes and small-format absorbent products targeting sustainability-conscious consumers.
- Specialty Stores:Niche positioning for premium home textile and food-service applications.
Direct sales capture volume concentration; online retail enables sustainability premium extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes airlaid textiles primarily for medical-grade absorbent pads, while India deploys the same material for cost-optimized hygiene cores. Japan emphasizes ultra-thin diaper substrates with microfiber densification. This consumption-mix differential shapes regional investment priorities and regulatory compliance burdens.
Germany
Adult incontinence demographics and hospital procurement consolidation drive absorbent pad demand. EU REACH Annex XVII restrictions on formaldehyde-releasing agents force latex-bonding reformulation. Stuttgart and Saxony host pilot lines for citric acid-based bonding systems serving medical-grade specifications.
United States
FDA biocompatibility requirements limit latex formulation options for medical-grade pads entering healthcare channels. EPA effluent guidelines govern pulp processing operations, raising compliance costs for non-integrated producers. Wisconsin and Ohio maintain wood pulp-to-fabric integration serving North American hygiene manufacturers.
Japan
Aging populations expand adult incontinence volumes while premium diaper manufacturers adopt cellulose microfiber grades. METI standards guide sustainable fiber sourcing disclosures. The Kansai region around Osaka concentrates thermal-bonding capacity for next-generation core designs.
India
Low per-capita diaper consumption creates expansion potential for airlaid absorbent cores as disposable income rises. BIS certification requirements shape product quality thresholds for imported substrates. Maharashtra and Gujarat host emerging hygiene manufacturing clusters targeting domestic and export markets.
Netherlands
Retail chains enforce single-use plastics directive compliance through procurement specifications for sustainable wipes. ECHA chemical restrictions align with EU Green Deal biodegradability mandates. The Randstad region serves as a distribution hub for airlaid substrates entering Benelux hygiene supply chains.
Airlaid Textile Market Competitive Environment
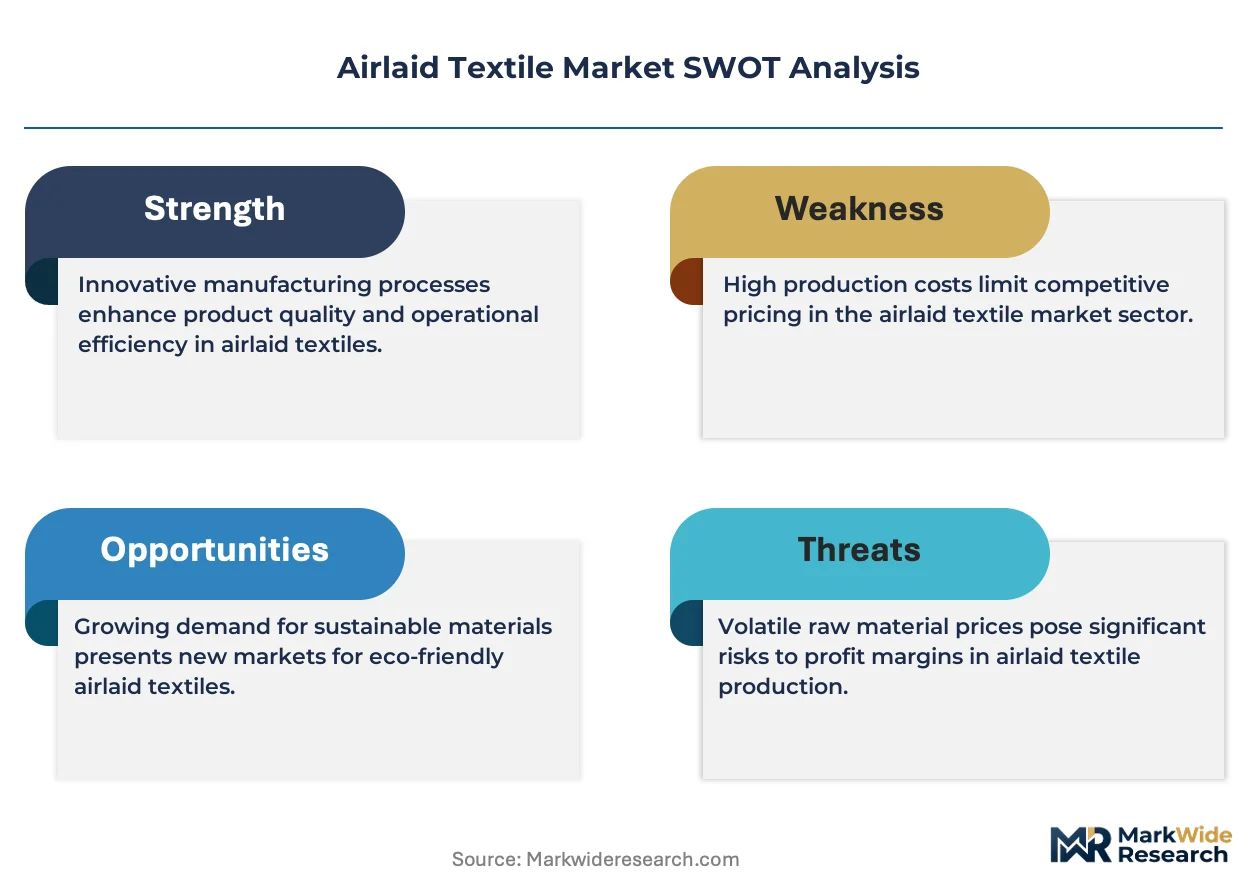
A small set of integrated leaders sits above a broader specialist tier in the airlaid textile sector. Integrated pulp-to-fabric operators capture margin advantages through captive wood pulp supply and multi-continent mill networks. Merchant converters without upstream fiber control face persistent cost pressure. The competitive terrain splits between scale-driven absorptive capacity builders and niche specialists in medical-grade bonding chemistry. Dominant moves include backward integration into pulp supply and geographic expansion through mill network replication.
Among European-based producers, Glatfelter and McAirlaid's Vliesstoffe occupy positions reflecting divergent strategic archetypes. Glatfelter represents the integrated multinational model with captive pulp supply spanning multiple continents. McAirlaid's Vliesstoffe exemplifies regional specialization anchored near German hygiene and medical clusters. Georgia-Pacific sits within the North American integrated tier, representing scale-driven absorbent capacity serving diaper and adult incontinence manufacturers. These three entities illustrate how fiber supply control and geographic proximity to demand clusters separate competitive positions.
| Leading Market Players |
|---|
| Glatfelter |
| McAirlaid's Vliesstoffe |
| Georgia-Pacific |
| EAM Corporation |
| Duni AB |
| Fitesa |
| M&J Airlaid Products |
| Oji Kinocloth |
| Main S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Cellulose microfiber substitution for conventional fluff pulp is redrawing supply geography toward German and Japanese densification facilities while compressing pricing power among non-integrated merchant converters. This input shift simultaneously elevates performance premiums for certified grades and erodes commodity-tier margins across European and North American hygiene supply chains.
Pricing Analysis
After-sales technical service contracts and formulation support agreements capture lifetime value beyond substrate sales. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified medical grades from industrial filtration tiers. Pricing pressure stems from wood pulp cost volatility favoring integrated operators with captive fiber supply. Small-format wipes manufacturers exhibit highest price sensitivity, while hospital procurement consortia absorb premiums for batch-traceable medical grades.
Supply Chain Analysis
Baltic Sea pulp transit corridors and Rhine River chemical feedstock routes constitute chokepoints for European airlaid production. Supply concentrates in Germany, the United States, and Japan for bonded web manufacturing. Raw material dependencies span Scandinavian wood pulp, Malaysian latex emulsions, and German citric acid bonding agents. Single-source vulnerability runs through concentrated fluff pulp suppliers. Distribution runs through direct sales channels serving consolidated hygiene manufacturers and hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against spunlace nonwoven alternatives in premium wipes segments, where wet-laid softness credentials threaten airlaid sustainability positioning.
For Market Incumbents: Compound captive pulp advantages through backward integration into cellulose microfiber densification capacity near Stuttgart and Osaka hygiene clusters. Deepen certification moats around FDA biocompatibility and EU REACH Annex XVII compliance to lock out merchant converters from medical-grade contracts. Thermal-bonding equipment upgrades represent the critical capacity lever for energy-efficient high-bulk web production. For New Entrants and Emerging Players: Differentiate on citric acid-based bonding chemistry for EU medical segments where incumbent latex reformulation lags regulatory deadlines. Target Indian hygiene penetration as the most penetrable geography, where low per-capita diaper consumption meets rising disposable income. Pursue food-soaking applications in meat packaging as a specification-white-space entry point with distinct liquid retention requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant converters lacking upstream fiber control and facing margin compression from integrated leaders. Five-to-ten year viability favors operators with certified fiber traceability aligning to CSRD disclosure requirements. Watch for EU Green Deal enforcement acceleration as the inflection signal separating compliant from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber control neutralizes wood pulp volatility for German hygiene manufacturers. |
| Citric Acid Bonding Pilot Investment | EU REACH Annex XVII compliance secures medical-grade market access near Stuttgart clusters. |
| Cellulose Microfiber Densification Scale-Up | Next-generation core designs for Japanese premium diaper specifications require refined substrates. |
| CSRD-Aligned Fiber Traceability Certification | Hospital procurement consortia in France mandate full lifecycle documentation for infection control. |
| Direct Sales Channel Consolidation | Single-source contracts with multinational hygiene brands displace fragmented distributor purchasing. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed nonwoven producers, and EU regulatory submission databases. Interviews with plant managers at integrated pulp-to-fabric operators, procurement leads at diaper manufacturers, and technical R&D directors at bonding chemistry suppliers informed capacity and formulation assumptions. Bottom-up mill capacity tallies triangulated against top-down hygiene demand projections.
Segmentation dimensions modeled include bonding chemistry type, fiber sourcing grade, end-use certification tier, and regional production hub across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating adult incontinence demographic trajectories and EU biodegradability mandate compliance timelines. Forecast inputs incorporated pulp cost volatility scenarios and thermal-bonding energy intensity improvements.
Material uncertainties — regulatory enforcement acceleration, synthetic fiber substitution economics, and hospital procurement centralization pace — sit outside the modeled envelope. Forecasts reflect documented assumptions on compliance cost pass-through and capacity utilization rates. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and FDA biocompatibility pathway clarifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
PP Nonwovens Market