
 US Banking-As-A-Service Market | 2026-2036
US Banking-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
US Banking-As-A-Service Market Analytics
Fintech startups is bifurcating from traditional banks as the dominant client archetype in US Banking-As-A-Service procurement. Galileo Financial Technologies anchors its position through deep API specialization for card-issuing programs. Marqeta differentiates via its ledger infrastructure that supports real-time transaction processing at scale. Treasury Prime competes by embedding compliance automation directly into its core banking APIs, reducing onboarding friction for emerging digital brands.
Banking-As-A-Service denotes the delivery of core banking functions—account origination, payment execution, and regulatory compliance—through modular APIs that licensed institutions expose to third-party distributors. These platforms typically process transactions via RESTful or gRPC interfaces with sub-second latency requirements, enabling non-bank enterprises to embed financial services without maintaining their own charter or Fedwire connectivity. Payment processing commands the largest service type revenue pool due to interchange economics, while compliance solutions capture expanding margin as KYC and BSA obligations intensify. API integration leads technology adoption among fintech startups, though AI-driven analytics is gaining traction for fraud detection and credit decisioning workflows.
The Office of the Comptroller of the Currency, the Federal Deposit Insurance Corporation, and state-level banking commissioners collectively shape market access through charter requirements, third-party risk management guidance, and consumer protection mandates. The FDIC's brokered deposit rules and OCC fintech charter pathways directly determine which BaaS providers can scale beyond state-by-state licensing fragmentation. Stakeholders must monitor evolving third-party risk management expectations from federal prudential regulators, as these standards will determine which platform architectures achieve sustainable operational scale.
Market Dynamics
API-native infrastructure is compressing time-to-market for financial product launches from months to days, forcing licensed banks to renegotiate their role from product providers to compliance backstops.
Growth Catalysts
- OCC Fintech Charter Pathway:The Office of the Comptroller of the Currency's special purpose national bank charter reduces state-by-state licensing friction for BaaS platforms seeking unified regulatory coverage.
- Embedded Card Issuance:E-commerce marketplaces and gig economy platforms are integrating virtual and physical card programs directly into their native user experiences.
- Real-Time Ledger Infrastructure:Sub-second transaction posting capabilities enable neobanks to offer instant balance updates and spending notifications that match consumer expectations set by payment apps.
Market Restraints
- FDIC Brokered Deposit Scrutiny:The Federal Deposit Insurance Corporation's evolving interpretation of brokered deposits creates uncertainty around funding models for digitally-acquired customer bases.
- Compliance Cost Concentration:Bank Secrecy Act and Know Your Customer obligations require specialized personnel that concentrate in New York and California, inflating operational overhead for providers in secondary markets.
- Fedwire Access Limitations:Direct central bank payment system connectivity remains restricted to chartered institutions, forcing BaaS providers into dependent relationships with sponsor banks.
Strategic Opportunities
- Texas and Florida Expansion:State banking regulators in Texas and Florida are streamlining fintech partnership approvals, creating lower-friction entry points outside legacy coastal financial centers.
- AI-Driven Fraud Detection:Machine learning models trained on transaction pattern recognition are converging with core banking APIs to offer predictive risk scoring as a bundled service.
- Payroll-Embdedded Banking:Workforce management platforms represent an underpenetrated distribution channel for earned wage access and salary-linked savings products.
Industry Challenges
- API Standardization Gaps:Absence of uniform data formats across sponsor banks forces BaaS providers to maintain multiple integration layers, increasing engineering overhead and error rates.
- Third-Party Risk Management Talent:Federal Reserve and OCC guidance on vendor oversight requires specialized compliance professionals whose supply lags demand by approximately eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Banking-As-A-Service Market |
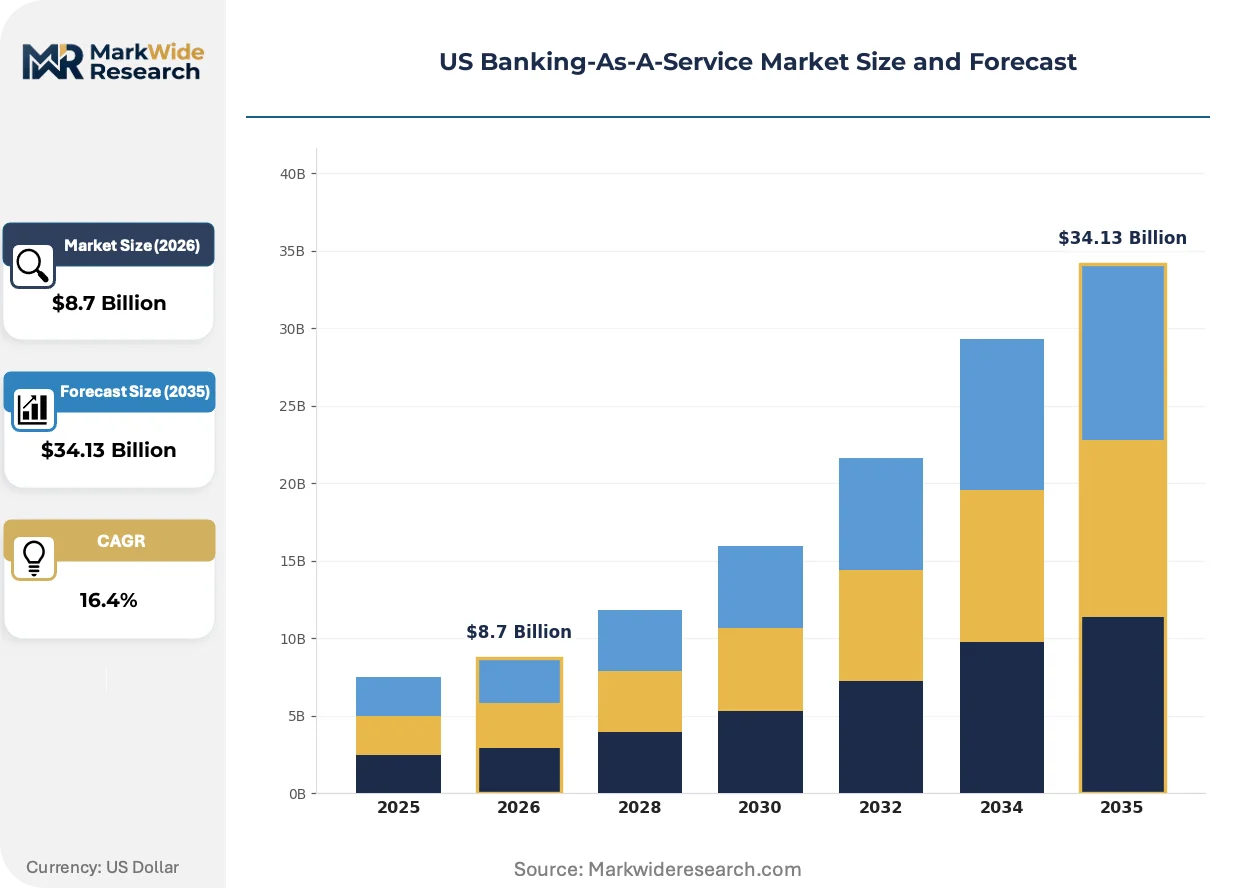
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Account Management, Compliance Solutions, Lending Services Client Type: Fintech Startups, Traditional Banks, Investment Firms, Credit Unions Technology: API Integration, Cloud Computing, Blockchain Solutions, AI-Driven Analytics End User: Businesses, Consumers, Financial Advisors, Third-Party Developers |
| Companies Covered | Synapse, Galileo Financial Technologies, Marqeta, Unit, Finix, Green Dot, Treasury Prime, Fiserv, FIS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Banking-As-A-Service Market Evolving Landscape
Modular financial infrastructure is fragmenting the traditional bank value chain, enabling non-financial enterprises to embed regulated services without charter ownership. This decomposition is redrawing competitive boundaries between technology platforms and licensed depositories.
Real-time ledger technology is displacing batch-based core banking systems that have dominated transaction processing for four decades. Neobanks and gig economy platforms are adopting these systems within twelve-month implementation cycles. The shift is compressing reconciliation windows from end-of-day to continuous, eliminating float-based revenue models for incumbent processors.
The Office of the Comptroller of the Currency's fintech charter framework is reshaping how non-bank entities access regulated infrastructure. Industrial consequence includes reduced state licensing fragmentation for nationally-scaled platforms. Early-stage fintechs in California and New York are responding by prioritizing OCC charter preparation over multi-state money transmission licenses.
Enterprise procurement of banking infrastructure is fragmenting from bundled core systems toward à la carte API selection. Fortune 500 retailers and healthcare systems are assembling financial stacks from multiple specialized providers rather than single-vendor relationships. This pattern is most visible in Texas, where energy and logistics conglomerates are unbundling treasury, card issuance, and lending functions across separate BaaS contracts.
US Banking-As-A-Service Market Segmentation
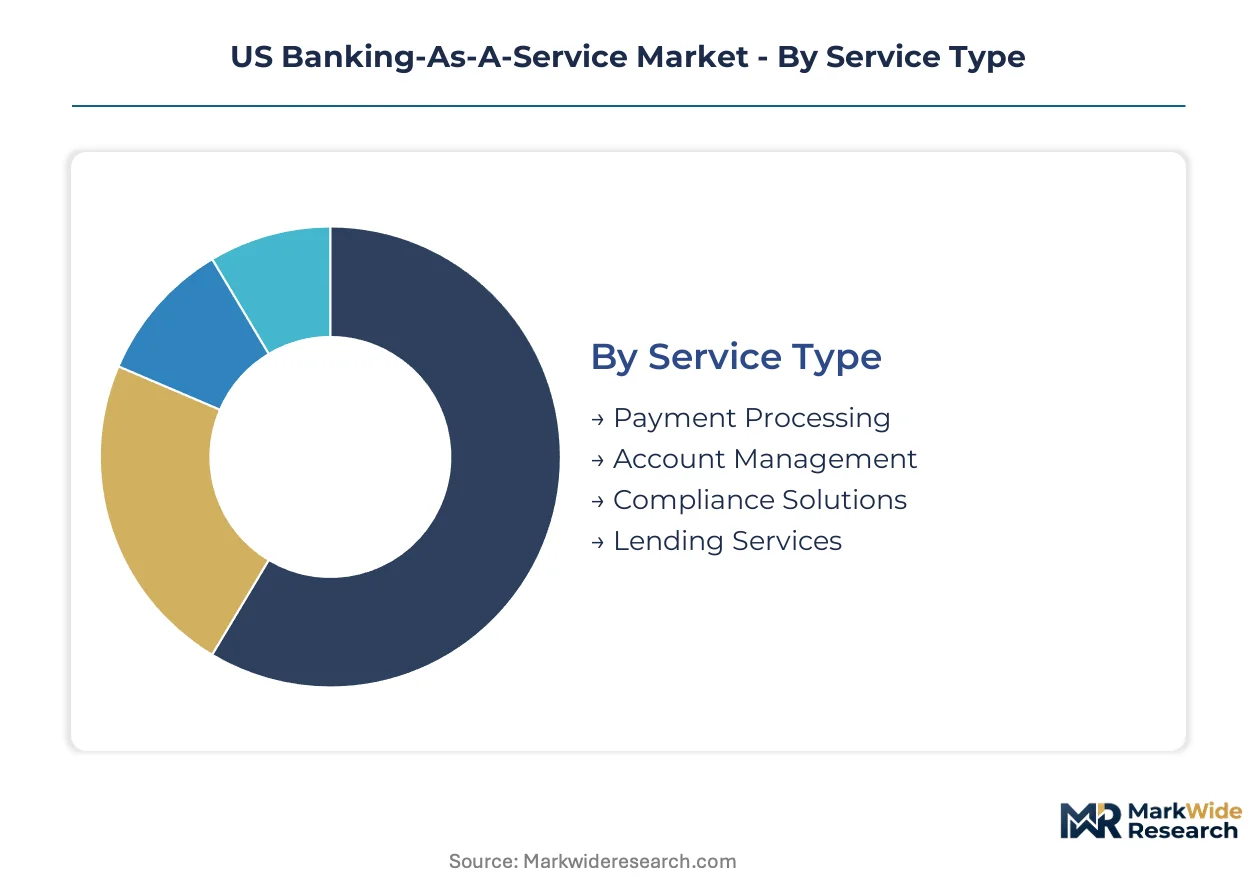
Segmentation in US Banking-As-A-Service reveals how regulatory requirements and technical capabilities reshape procurement patterns across sponsor banks and distributor platforms. Each dimension exposes distinct compliance burdens and integration architectures that determine platform scalability.
Service Type:
The OCC's third-party risk management guidance and FDIC brokered deposit rules create divergent licensing obligations across service categories.
- Payment Processing:Interchange economics drive revenue concentration here. RESTful and gRPC interfaces process card transactions with sub-second latency requirements. Demand concentrates among e-commerce marketplaces in California and New York where real-time settlement expectations are highest. The Fedwire access limitations force providers into sponsor bank dependencies that inflate per-transaction costs.
- Compliance Solutions:KYC and BSA automation modules embed directly into core banking APIs. Bank Secrecy Act obligations intensify as federal prudential regulators tighten third-party oversight. New York and California talent concentration inflates operational overhead for providers building automated sanction screening and transaction monitoring systems.
- Account Management:Modular account origination and ledger infrastructure.
- Lending Services:Credit decisioning workflows with embedded risk scoring.
Payment Processing handles the majority of throughput; Compliance Solutions is the fastest mover on share.
Client Type:
Cost tier differentiation separates lean API-native entrants from compliance-heavy institutional adopters.
- Fintech Startups:API-native business models dominate customer acquisition strategies with compressed time-to-market. California and New York clusters prioritize OCC charter preparation over multi-state money transmission licenses. The fintech charter pathway reduces state-by-state licensing friction for nationally-scaled platforms.
- Traditional Banks:Legacy core system modernization and compliance backstop repositioning. Texas and Florida regulators are streamlining partnership approvals, creating lower-friction entry points for regional banks seeking distributor relationships.
- Investment Firms:Treasury and custody infrastructure unbundling.
- Credit Unions:Member-facing digital product launches with limited engineering resources.
Fintech Startups command the volume pipeline; Traditional Banks are expanding most quickly as charter holders seek distributor economics.
Technology:
Application maturity separates production-grade infrastructure from experimental deployments.
- API Integration:RESTful and gRPC interfaces form the production backbone for card-issuing programs and real-time ledger posting. Sub-second transaction capabilities enable neobanks to match consumer expectations set by payment apps. Texas energy and logistics conglomerates are unbundling treasury functions across separate BaaS contracts using these interfaces.
- AI-Driven Analytics:Machine learning models trained on transaction pattern recognition converge with core banking APIs. Predictive risk scoring bundles with fraud detection workflows as federal regulators intensify BSA scrutiny. Talent supply for these specialized systems lags demand by approximately eighteen months.
- Cloud Computing:Scalable infrastructure for core banking workloads.
- Blockchain Solutions:Distributed ledger pilots for settlement and identity.
API Integration carries the operational load; AI-Driven Analytics is gaining share fastest on regulatory pressure.
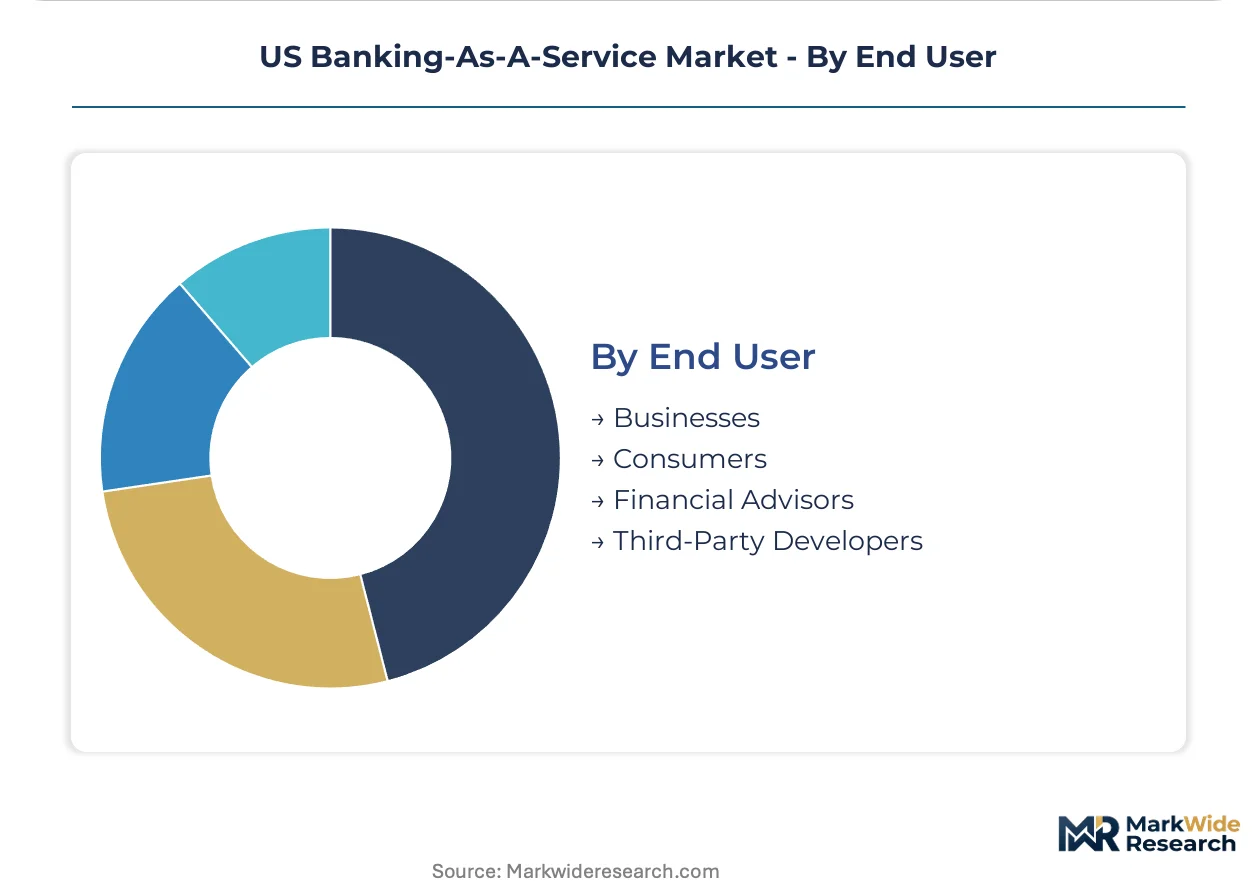
End User:
Geographic concentration of demand centers on coastal financial clusters with secondary market expansion.
- Businesses:Enterprise procurement fragments from bundled core systems toward à la carte API selection. Fortune 500 retailers and healthcare systems assemble financial stacks from multiple specialized providers. This pattern is most visible in Texas where conglomerates unbundle treasury, card issuance, and lending functions.
- Consumers:Neobank and gig economy platform adoption with instant balance update expectations. Real-time ledger technology displaces batch-based systems within twelve-month implementation cycles. The shift compresses reconciliation windows from end-of-day to continuous.
- Financial Advisors:Embedded planning and custody tools.
- Third-Party Developers:API marketplace access and sandbox environments.
Businesses anchor current deployment scale; Consumers are climbing the fastest on embedded finance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Banking-as-a-Service infrastructure concentrates in coastal financial centers where regulatory density and venture capital availability intersect. Texas and Florida are emerging as lower-cost alternatives with streamlined state banking commissioner frameworks.
California
Venture-backed fintech startups in San Francisco and Los Angeles drive API-native platform procurement. The state's Department of Financial Protection and Innovation enforces money transmission licensing that shapes distributor-sponsor bank relationships. Silicon Valley clusters prioritize OCC charter preparation over legacy multi-state compliance frameworks.
New York
Neobanks and embedded finance platforms concentrate in Manhattan and Brooklyn seeking proximity to sponsor bank headquarters. The New York State Department of Financial Services maintains BitLicense and banking charter requirements that elevate compliance infrastructure investments. Wall Street adjacency attracts Bank Secrecy Act specialist talent pools.
Texas
Energy and logistics conglomerates in Houston and Dallas are unbundling treasury functions across separate BaaS contracts. The Texas Department of Banking has streamlined fintech partnership approval timelines below national averages. Austin's technology corridor hosts emerging distributor platforms serving payroll-embedded banking use cases.
Florida
Miami's emerging fintech cluster targets Latin American cross-border payment integration. The Florida Office of Financial Regulation has reduced friction for sponsor bank-distributor partnerships compared to northeastern states. Orlando and Tampa house regional bank headquarters seeking distributor economics through BaaS enablement.
US Banking-As-A-Service Market Competitive Landscape
Concentration sits with API-specialized platforms that have secured sponsor bank relationships at scale. The market exhibits tiered structure with a handful of established infrastructure providers and a long tail of emerging entrants. Two strategic archetypes dominate: ledger-technology specialists competing on transaction processing latency, and compliance-embedded platforms reducing onboarding friction. Competitive moves center on strategic partnerships with regional banks and technology licensing arrangements that accelerate geographic expansion.
Among the API-native tier, Galileo Financial Technologies, Marqeta, and Treasury Prime exemplify distinct specialization vectors. Galileo occupies a position anchored in card-issuing program infrastructure. Marqeta represents the real-time ledger processing archetype with sub-second transaction capabilities. Treasury Prime sits within the compliance-automation segment, embedding Know Your Customer and Bank Secrecy Act workflows directly into core banking interfaces.
| Leading Market Players |
|---|
| Synapse |
| Galileo Financial Technologies |
| Marqeta |
| Unit |
| Finix |
| Green Dot |
| Treasury Prime |
| Fiserv |
| FIS |
| Others |
Value Network & Pricing Analysis
Per-transaction API fee structures lock in both sponsor bank access and interchange revenue visibility for BaaS distributors, embedding pricing power within charter-holder relationships that non-bank platforms cannot replicate without regulatory restructuring.
Pricing Analysis
FDIC brokered deposit rules dictate the pricing tier structure across sponsor bank partnerships. Three-tier pricing structure across premium, standard, and economy levels separates full-stack API providers from compliance-lite middleware vendors. Price differentiation rests on KYC automation depth and Fedwire access tier. Cost compression in the standard tier is intensifying because sponsor banks are consolidating distributor relationships. Fintech startups exhibit highest price sensitivity; Fortune 500 enterprises prioritize latency guarantees over per-call economics.
Supply Chain Analysis
Fedwire access chokepoints tether BaaS providers to chartered sponsor banks in New York, California, and Texas. Core banking infrastructure draws from Fiserv, FIS, and Jack Henry legacy systems alongside API-native alternatives. Raw material dependencies include cloud compute capacity, compliance talent pipelines, and card manufacturing partnerships. Single-source vulnerability concentrates in sponsor bank relationships where termination clauses carry 90-day wind-down obligations. Distribution runs through direct enterprise sales teams and embedded finance marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized Bank Secrecy Act engineering talent scarcity constrains platform scalability more than capital availability, privileging incumbents with existing compliance automation stacks over well-funded entrants lacking regulatory operations depth.
For Market Incumbents: Shield core sponsor bank relationships through exclusive API integration commitments that raise switching costs for fintech distributors. Deepen vertical integration into compliance automation by acquiring KYC workflow specialists before talent scarcity inflates acquisition premiums. The OCC's evolving third-party risk management guidance threatens non-compliant architectures; prioritize certification investments in Texas and Florida where regulatory friction is lowest. For New Entrants and Emerging Players: Payroll-embedded banking layers represent the most penetrable white-space where incumbent API providers under-serve workforce management platforms. Target Austin and Miami technology corridors where state banking commissioners have compressed partnership approval timelines below national averages. Lead with earned wage access use cases that bypass full charter requirements through existing money transmission frameworks. For Investors and Strategic Acquirers: Capital is best deployed toward compliance-embedded platforms with demonstrated sponsor bank exclusivity rather than pure-technology API layers vulnerable to commoditization. Long-term viability hinges on regulatory operational moats that survive interchange compression. Monitor OCC fintech charter approval velocity as the critical inflection signal for nationally-scaled platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Sponsor Bank Exclusivity Agreement | Locks in Fedwire access and reduces third-party risk management scrutiny from the OCC. |
| Compliance Automation Acquisition | Integrates KYC and BSA workflows directly into core APIs, compressing distributor onboarding cycles. |
| Texas/Florida Regulatory Expansion | Exploits streamlined state banking commissioner frameworks to bypass coastal compliance cost concentration. |
| AI-Driven Fraud Detection Launch | Bundles predictive risk scoring with transaction processing to capture margin from intensifying BSA obligations. |
| Payroll Platform Partnership | Opens earned wage access distribution channel with lower charter requirements than consumer neobanking. |
Research Methodology
The analysis maps payment processing, compliance solutions, account management, and lending services layers, each validated through BaaS platform executives, sponsor bank partnership leads, fintech product managers, and regulatory compliance officers. Primary interviews with these stakeholders combined with secondary validation from FDIC call reports, OCC fintech charter filings, state banking commissioner enforcement actions, and Fedwire access disclosures. Bottom-up transaction volume modeling and top-down market sizing triangulate across independent approaches.
Consistency checks against sponsor bank partnership announcements and fintech funding disclosures validated volume and value outputs across the modeling period. Segmentation dimensions include service type, client archetype, technology deployment, and end-user category with regional regulatory cluster overlays. CAGRs derive from sponsor bank revenue disclosure patterns and distributor platform growth trajectories. Forecast inputs incorporate API call volume elasticity and interchange rate stability assumptions.
Forecasts assume regulatory continuity in OCC fintech charter pathways and FDIC brokered deposit interpretations; material policy shifts would require re-modeling sponsor bank economics. Practitioners should keep alternative scenarios live as third-party risk management guidance and state-by-state licensing fragmentation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
China Data Analytics in Banking Market
Banking
Banking Credit Analytics Market
Banking
Banking ERP Software Market
Banking
Japan Data Analytics in Banking Market
Banking
Australia Neobanking Market
Banking
ATM Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Cardless ATM Market
Banking
UK Banking as a Service Market
Banking
United Kingdom Data Analytics in Banking Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Smart ATM Market
Banking
Singapore Data Analytics in Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Blockchain in Retail Banking Market
Banking
Global Certificate of Deposit Market