
 Smart ATM Market | 2026-2036
Smart ATM Market Size, Share, and Industry Trends Forecast 2026-2036
Smart ATM Market Insights
EMV Level 3 certification is reorganizing procurement priorities across the Smart ATM landscape. Diebold Nixdorf leverages its vertically integrated manufacturing footprint to sustain delivery timelines for certified hardware. NCR Atleos anchors its competitive stance through software-defined ATM architectures that reduce field-service dependency. GRG Banking Equipment specializes in cash-recycling modules for emerging-market deployments where uptime metrics dominate vendor selection.
A smart ATM integrates cash handling, cardless transaction processing, biometric verification, and remote monitoring capabilities within a self-service terminal designed for unsupervised banking operations. These machines incorporate encrypted PIN pads, cash-recycling drums with sensor-based counterfeit detection, and API-connected cloud middleware to enable real-time balance inquiry, deposit, withdrawal, and bill-payment functions. Multi-functional ATM configurations command the widest installed base, while contactless payment modules represent the fastest-expanding technology segment as NFC transaction volumes displace mag-stripe dependency. Cloud-based services concentrate margin pools for independent ATM deployers seeking to reduce on-premise server maintenance and accelerate software patch cycles across dispersed estates.
The US Federal Reserve's cash-access policies, the EU's PCI DSS enforcement through national banking regulators, and India's RBI financial-inclusion directives collectively shape hardware specifications, data-security architectures, and network-density requirements. EMVCo certification timelines and GDPR-aligned transaction-log retention rules extend product-development cycles and elevate compliance costs for manufacturers serving multiple jurisdictions. Stakeholders must monitor central-bank digital currency pilot programs and corresponding ATM-interface adaptation requirements to preserve terminal relevance as payment rails diversify.
Market Dynamics
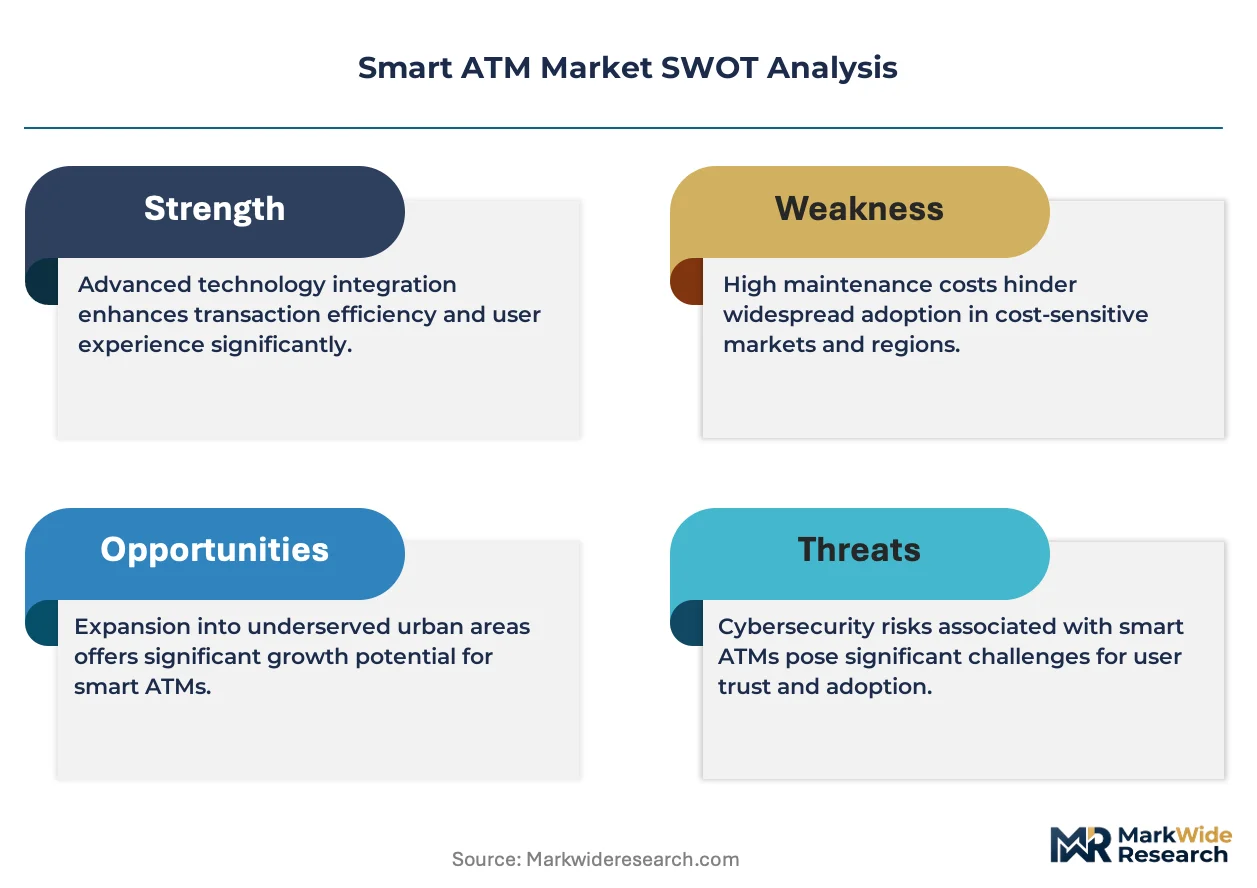
PCI DSS Level 3 certification deadlines are compressing hardware procurement cycles across retail banking networks, forcing ATM deployers to accelerate terminal refresh programs ahead of enforcement dates. EMVCo compliance mandates and biometric authentication standards now gate market access, reshaping vendor qualification criteria and fleet modernization priorities.
Growth Catalysts
- RBI Financial Inclusion Directives:India's central bank mandates kiosk and mini-ATM density targets in semi-urban districts, creating procurement pull for compact cash-recycling terminals.
- Biometric Authentication Standards:Fingerprint and iris verification modules are displacing mag-stripe dependency in unsupervised banking environments, expanding addressable use cases.
- Cloud Middleware Adoption:Independent ATM deployers are migrating transaction processing off-premise to reduce server maintenance overhead across dispersed estates.
Market Restraints
- Semiconductor Component Volatility:Cash-recycling drum controllers and encrypted PIN pad processors face extended lead times from concentrated Asian foundry capacity.
- GDPR-Aligned Data Retention Rules:EU transaction-log retention requirements extend product-development cycles and elevate compliance architecture costs for multi-jurisdiction manufacturers.
- Mobile Payment Substitution:NFC-enabled smartphone wallets are capturing low-value transaction volumes previously routed through ATM networks.
Strategic Opportunities
- Central Bank Digital Currency Interfaces:Pilot programs in India and other jurisdictions will require ATM terminal adaptations to preserve relevance as payment rails diversify.
- Contactless Payment Module Integration:NFC transaction hardware represents white-space expansion for terminal retrofit programs and new fleet specifications.
- Software-Defined ATM Architectures:Remote diagnostics and over-the-air patch capabilities reduce field-service dependency for independent deployers.
Industry Challenges
- EMV Level 3 Certification Timelines:Extended laboratory testing windows compress vendor revenue recognition and delay fleet deployment schedules.
- Legacy Host System Integration:Core banking protocol mismatches between cloud middleware and decades-old transaction switches create deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart ATM Market |
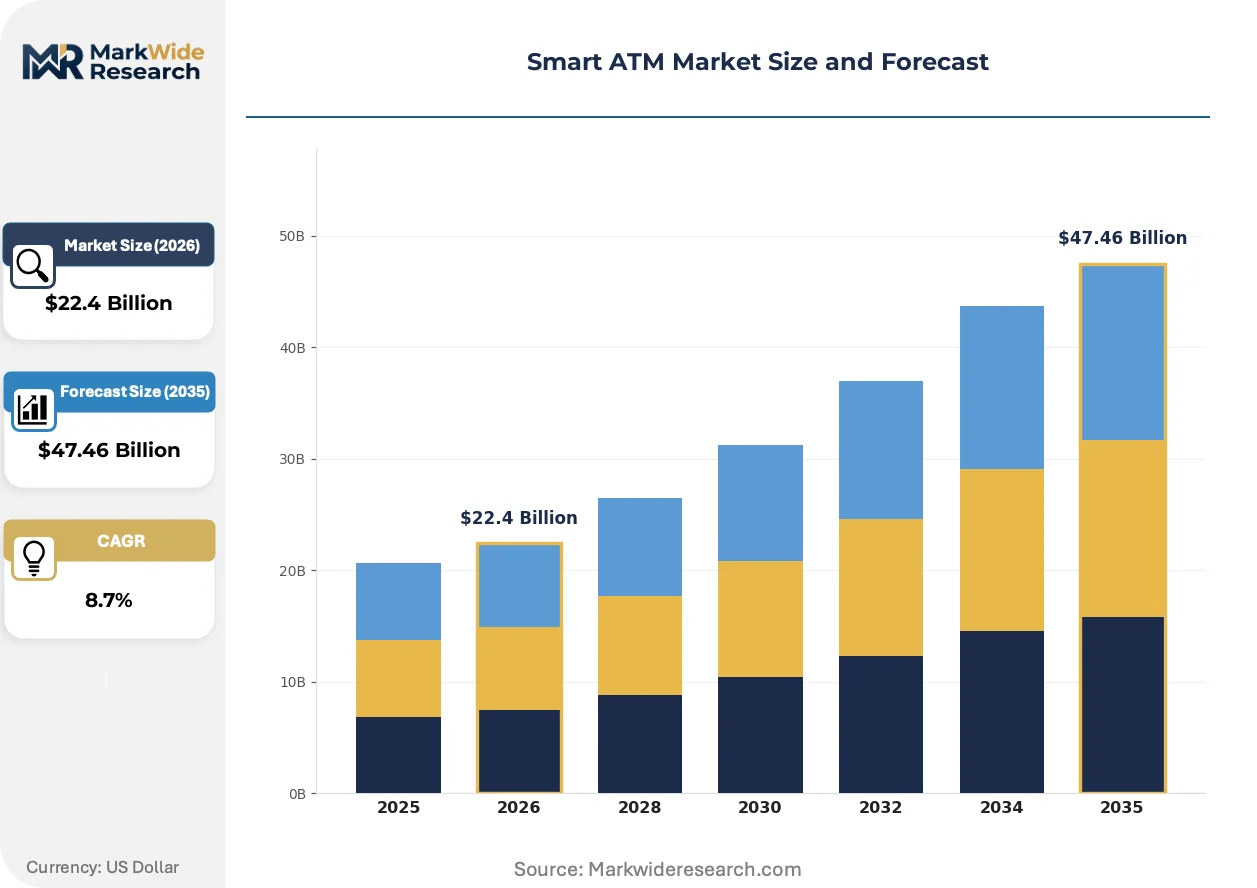
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $47.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cash Dispenser, Multi-Functional ATM, Kiosk, Mini-ATM End User: Retail Banks, Credit Unions, Independent ATM Deployers, Government Technology: Cash Recycling, Contactless Payments, Biometric Authentication, Cloud-Based Services Deployment: On-Premise, Off-Site, Remote Locations, Urban Areas |
| Companies Covered | Diebold Nixdorf, NCR Atleos, Hitachi-Omron Terminal Solutions, GRG Banking Equipment, Nautilus Hyosung, Fujitsu, OKI Electric Industry, Triton Systems, HESS Cash Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart ATM Market Trends and Innovations
ATM hardware architecture is separating into two distinct performance tiers as cloud-native transaction processing displaces legacy on-premise stacks. Certification-driven procurement preferences now favor terminals with API-connected middleware over closed-system designs.
Cash-recycling technology is bifurcating the installed base into high-uptime premium configurations and cost-optimized basic terminals. Tier-one retail banks in India and Southeast Asia are specifying sensor-based counterfeit detection drums for 24/7 operation, while independent deployers prioritize acquisition cost over recycling throughput. This split is compressing margin pools for mid-tier hardware lacking either extreme performance or extreme cost discipline.
The EU's GDPR enforcement through national banking regulators is mandating encrypted transaction-log architectures with strict retention limits. Hardware manufacturers must now embed tamper-evident storage modules and automated purge routines directly into terminal firmware. PCI DSS compliance timelines in the United States are synchronizing with European data-protection standards, forcing synchronized product-development roadmaps.
Buyer concentration among independent ATM deployers is consolidating procurement leverage and unbundling after-sales service contracts. Large estate operators now self-perform first-line maintenance and demand API access for remote monitoring rather than bundled field-service agreements. This pattern is most visible in India's semi-urban expansion zones where deployers prioritize uptime metrics over vendor-managed service levels.
Smart ATM Market Segmentation
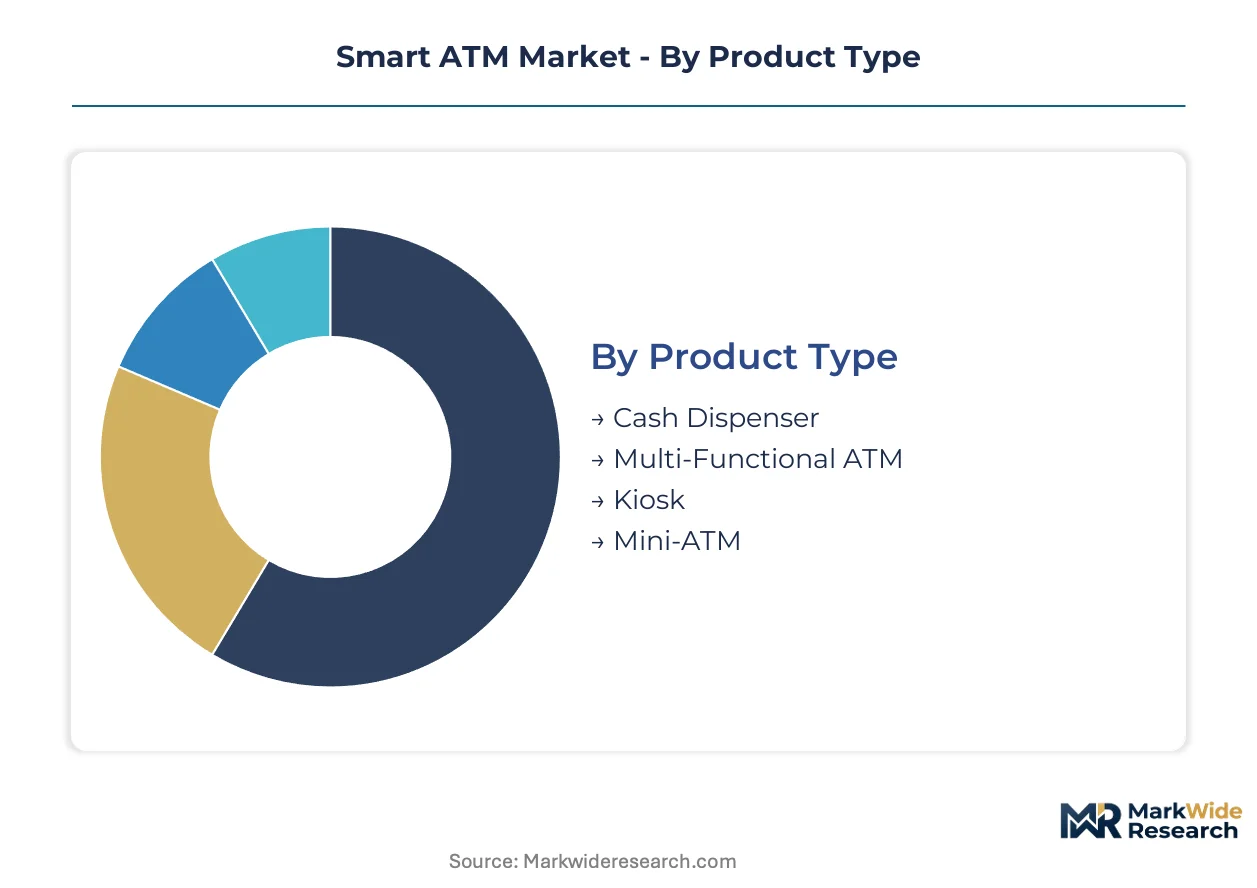
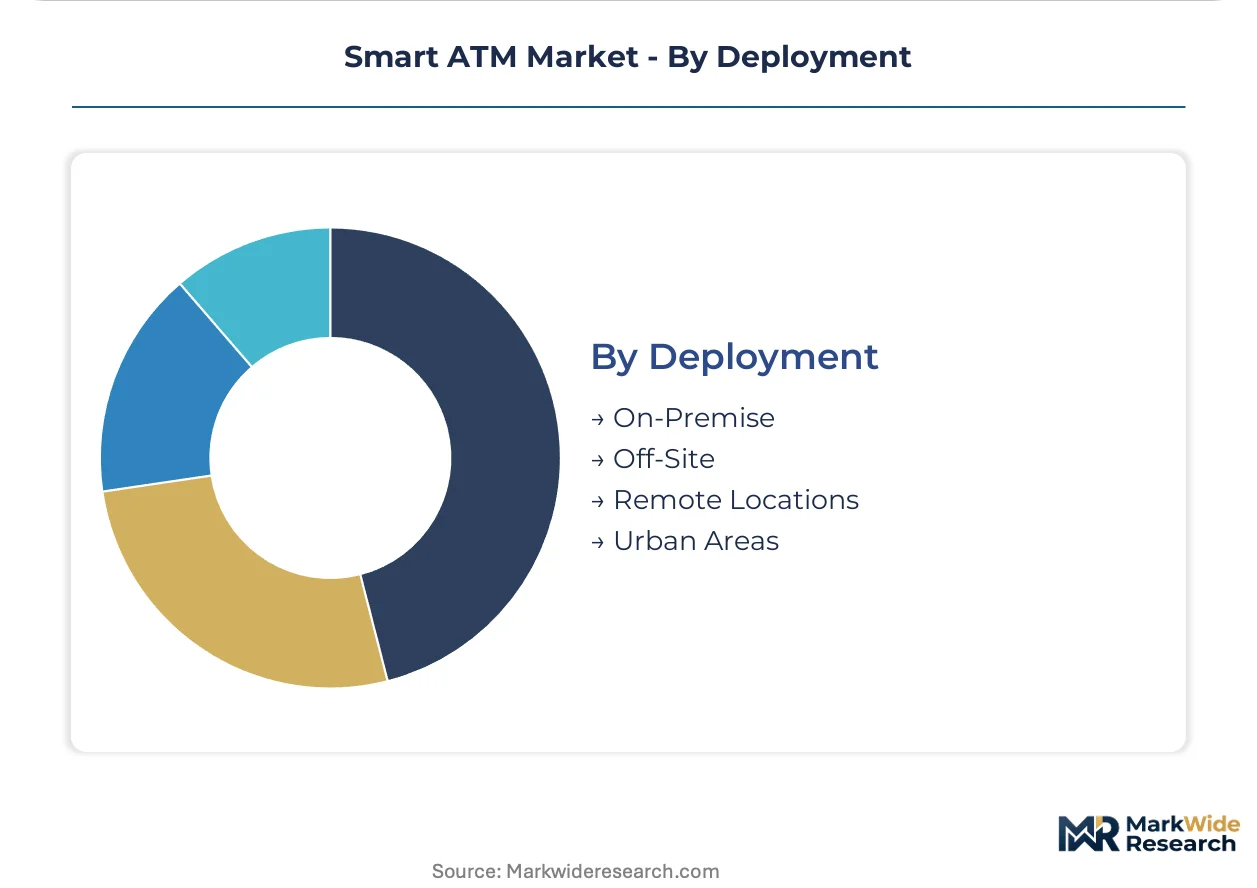
Smart ATM procurement patterns diverge sharply across product configurations and deployment contexts. Understanding these segment boundaries clarifies why hardware specifications, compliance architectures, and service models vary so dramatically between customer types.
Product Type:
Domestic manufacturing capacity for full-function terminals concentrates in China and India, while compact kiosk formats increasingly ship from Southeast Asian assembly plants serving regional financial inclusion programs.
- Multi-Functional ATM:These terminals integrate cash dispensing, deposit handling, bill payment, and account inquiry within a single footprint. Retail banks in India and Indonesia specify these for semi-urban branch replacements where transaction volume justifies capital investment.
- Cash Dispenser:Basic withdrawal-only configurations with encrypted PIN pads and single-drum cash cartridges. Independent deployers across India's tier-3 cities favor these for low-acquisition-cost estate expansion under RBI density mandates.
- Kiosk:Non-cash terminals focused on card issuance, statement printing, and account opening. Government financial inclusion programs in rural districts drive procurement for these compact, solar-compatible units.
- Mini-ATM:Portable battery-operated devices with fingerprint authentication for agent banking networks. These units address last-mile connectivity gaps in India's unbanked corridors where fixed infrastructure remains uneconomical.
Multi-Functional ATM holds the largest share; momentum sits with Mini-ATM as agent banking networks proliferate.
End User:
Cost tier separation defines procurement behavior, with retail banks prioritizing certified uptime performance while independent deployers optimize acquisition cost against transaction yield.
- Independent ATM Deployers:Estate operators managing dispersed terminal networks across convenience retail, transit hubs, and semi-urban corridors. These buyers self-perform maintenance and demand API-accessible remote monitoring to reduce field-service dependency.
- Retail Banks:Tier-one institutions replacing branch footprints with self-service zones in India and Southeast Asia. Their procurement specifications gate vendor access through EMV Level 3 certification and biometric module integration.
- Credit Unions:Member-owned institutions with concentrated geographic footprints and legacy host system constraints. These organizations prioritize backward-compatible middleware over cloud-native architectures to avoid core banking integration friction.
- Government:Central and state agencies procuring financial inclusion infrastructure under directed lending mandates. Their tenders emphasize domestic assembly content and rural serviceability over advanced feature sets.
Retail Banks dominate procurement volume; Independent ATM Deployers are expanding most quickly as estate consolidation accelerates.
Technology:
Application maturity varies dramatically, with cash recycling representing proven infrastructure while cloud migration introduces deployment complexity for legacy host environments.
- Cash Recycling:Sensor-based drums that authenticate, store, and redistribute deposited cash without human intervention. These modules command premium positioning in 24/7 urban deployments where uptime metrics dominate vendor selection.
- Cloud-Based Services:API-connected middleware enabling over-the-air software patches and real-time transaction monitoring. Independent deployers migrating dispersed estates off-premise drive demand for these subscription-linked architectures.
- Biometric Authentication:Fingerprint and iris verification modules displacing mag-stripe and PIN dependency. RBI mandates for Aadhaar-enabled transactions accelerate adoption across India's government-procured terminal base.
- Contactless Payments:NFC transaction hardware supporting smartphone wallet integration. These modules address low-value payment displacement as mobile wallets capture volumes previously routed through ATM networks.
Cash Recycling retains the largest installed base; Cloud-Based Services are gaining share fastest as independent deployers shed on-premise server maintenance.
Deployment:
Volume concentration follows urban density gradients, though regulatory pressure is redistributing terminal placement toward underserved geographies previously considered economically marginal.
- Urban Areas:High-traffic zones in metropolitan centers with 24/7 operation requirements and premium cash-recycling specifications. These deployments face intensifying competition from contactless payment acceptance at retail point-of-sale.
- Off-Site:Retail-adjacent placements in convenience stores, petrol stations, and shopping malls outside bank branch footprints. Independent deployers concentrate estate growth in these locations where rent structures favor transaction yield economics.
- Remote Locations:Low-connectivity rural and semi-urban sites requiring satellite or mesh network backhaul. Government financial inclusion programs subsidize these deployments to satisfy regulatory density targets.
- On-Premise:Branch-interior terminals replacing teller windows within controlled banking environments. Retail banks in India and Southeast Asia specify these for customer migration from high-cost service channels.
Urban Areas maintain the largest terminal population; Remote Locations show the steepest expansion trajectory as financial inclusion mandates reshape network geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in ATM hardware concentrate in East Asian manufacturing clusters, while import dependency defines procurement patterns across South Asian and Southeast Asian banking networks. Trade flows in cash-recycling modules and encrypted PIN pad components track regulatory compliance timelines rather than pure cost optimization.
India
RBI financial inclusion mandates drive kiosk and mini-ATM procurement across semi-urban districts and rural corridors. The central bank's density targets for unbanked areas accelerate agent banking network expansion. Manufacturing clusters in Pune and Chennai assemble compact terminals for domestic deployment under phased production-linked incentive schemes.
China
Domestic banking network modernization sustains demand for multi-functional terminals with integrated biometric modules. MIIT cybersecurity standards for financial infrastructure shape hardware certification requirements. Shenzhen and Hangzhou host vertically integrated production ecosystems serving both state-owned banks and export markets across Southeast Asia.
United States
Independent ATM deployers consolidate estate ownership and unbundle service contracts to reduce operating overhead. PCI DSS Level 3 enforcement through the Federal Reserve's compliance framework compresses hardware refresh cycles. Dallas and Atlanta anchor regional distribution networks for terminal deployment across convenience retail and transit corridors.
Germany
GDPR-aligned transaction-log retention rules elevate firmware architecture costs for manufacturers serving EU banking networks. The country's national banking regulator enforces encrypted storage mandates with automated purge routines. Industrial clusters in Baden-Württemberg specialize in cash-recycling drum controllers for premium uptime specifications.
Japan
Aging demographic profiles sustain demand for assisted-service terminals with enhanced accessibility interfaces. METI standards for financial infrastructure interoperability shape middleware procurement preferences. Nagoya and Osaka manufacturing bases focus on compact form factors for space-constrained urban deployment.
Smart ATM Market Competitive Landscape
Listed leaders compete with private specialists across certification timelines and service bundling strategies. The vendor base separates into three tiers: integrated hardware-software providers with vertically controlled manufacturing, modular component specialists supplying cash-handling subsystems, and regional assemblers competing on acquisition cost for price-sensitive deployers. Consolidation pressure intensifies as independent ATM deployers consolidate procurement leverage and demand API-accessible remote monitoring capabilities rather than bundled field-service agreements.
Within the integrated-system tier, Diebold Nixdorf and NCR Atleos occupy positions defined by vertically controlled production footprints and software-defined architectures. GRG Banking Equipment represents the component-specialist archetype with concentrated expertise in cash-recycling modules. These three entities exemplify how vendor qualification criteria now gate market access through EMVCo compliance and biometric module integration rather than legacy service relationships alone.
| Leading Market Players |
|---|
| Diebold Nixdorf |
| NCR Atleos |
| Hitachi-Omron Terminal Solutions |
| GRG Banking Equipment |
| Nautilus Hyosung |
| Fujitsu |
| OKI Electric Industry |
| Triton Systems |
| HESS Cash Systems |
| Others |
Pricing and Supply Chain Analysis
EMV Level 3 certification timelines gate both supplier qualification and terminal pricing tiers simultaneously, compressing procurement cycles while stratifying hardware premiums across certified and non-certified configurations. This regulatory architecture forces manufacturers to absorb extended laboratory testing costs into upfront pricing while buyers face accelerated refresh mandates that limit negotiation leverage.
Pricing Analysis
Independent ATM deployers anchor pricing stratification across premium, standard, and economy tiers based on uptime specifications and after-sales bundling. Certification grade and volume scale drive price differentiation, with EMVCo-validated terminals commanding substantial premiums over legacy configurations. Cost compression in the economy tier is intensifying because semiconductor component volatility elevates bill-of-material uncertainty. Government procurement programs exhibit the highest price sensitivity, while tier-one retail banks prioritize certified performance over acquisition cost.
Supply Chain Analysis
China and India anchor cash-recycling module assembly, while Taiwan and South Korea supply encrypted PIN pad processors and sensor-based authentication controllers. Cash-recycling drum controllers, biometric verification modules, and API-connected middleware stacks draw from concentrated Asian foundry capacity. Single-source vulnerability in semiconductor component sourcing creates procurement risk for manufacturers serving multi-jurisdiction compliance timelines. Distribution runs through regional assembly clusters in Pune, Chennai, Shenzhen, and Hangzhou before downstream deployment to banking networks and independent estate operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in EMVCo-certified manufacturing capacity limits vendor expansion velocity, concentrating margin capture among established players with vertically controlled production footprints. This capability gap shapes competitive dynamics across hardware procurement cycles.
For Market Incumbents: Consolidate certification-advantaged manufacturing positions through captive supply of cash-recycling drum controllers and encrypted PIN pad processors. Deepen backward integration into sensor-based authentication modules to defend against modular component specialists. Lock in long-term service contracts with independent deployers before API-accessible remote monitoring becomes table stakes.
For New Entrants and Emerging Players: Cloud middleware subscription gaps in legacy host system integration present white-space entry points for software-defined ATM architectures. Mini-ATM deployments for India's agent banking networks offer the most penetrable segment given RBI density mandates and domestic assembly incentives. Lead with over-the-air patch capabilities and API-first remote monitoring to differentiate against bundled field-service incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biometric authentication module production as RBI Aadhaar-enabled transaction mandates expand addressable hardware specifications. Long-term viability favors manufacturers with vertically integrated footprints spanning cash-handling subsystems and cloud-native middleware. Target acquisition profiles center on modular component specialists with concentrated cash-recycling expertise. The signal to watch is central bank digital currency pilot program announcements requiring terminal interface adaptations.
| Strategic Initiative | Industry Significance |
|---|---|
| EMV Level 3 Certification Investment | Validates hardware for PCI DSS compliance timelines across US Federal Reserve and EU national banking regulator frameworks. |
| Cloud Middleware Platform Integration | Enables over-the-air software patches for independent deployers reducing field-service dependency across dispersed estates. |
| Biometric Module Backward Integration | Captures RBI Aadhaar-enabled transaction specifications driving kiosk and mini-ATM procurement in India's semi-urban districts. |
| Cash-Recycling Capacity Expansion | Addresses 24/7 uptime requirements from tier-one retail banks in Indonesia and Southeast Asia branch replacement programs. |
| Contactless Payment Module Retrofit | Preserves terminal relevance as NFC smartphone wallets displace low-value transaction volumes from ATM networks. |
Research Methodology
A standing panel of ATM hardware procurement directors, independent deployer estate managers, core banking integration specialists, and RBI compliance officers provided ongoing calibration against secondary validation from PCI DSS enforcement documentation, EMVCo certification timelines, and central bank digital currency pilot disclosures. This primary fieldwork combined with customs records, SEC 10-K filings from listed manufacturers, and production-linked incentive scheme announcements to enable bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product configuration, end-user archetype, technology maturity, and deployment geography alongside hardware certification tier. CAGRs were derived from installed base evolution and replacement cycle compression under regulatory enforcement timelines, with inputs from semiconductor lead time volatility and cloud middleware adoption curves.
Material uncertainties — central bank digital currency interface standardization, GDPR-aligned data retention rule amendments, and geopolitical disruption to Asian foundry capacity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement schedules and hardware refresh elasticity. Recalibration cycles align with material shifts in PCI DSS compliance deadlines and RBI financial inclusion directive amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Southeast Asia Commercial Banking Market
Banking
South Korea Data Analytics in Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Global AI in Banking Market
Banking
US Retail Banking Market
Banking
GCC Mobile Banking Market
Banking
Digital LED Retail Banking Market
Banking
Banking Maintenance Support and Services Market
Banking
Global Neobanking Market
Banking
Voice Banking Market
Banking
Banking Wearable Devices Market
Banking
United Kingdom Data Analytics in Banking Market
Banking
India Data Analytics in Banking Market
Banking
UK Banking as a Service Market
Banking
Global Certificate of Deposit Market
Banking
Mobile Banking Market