
 Machine Learning in Banking Market | 2026-2036
Machine Learning in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Learning in Banking Market Analysis
Modular API-first deployment is recalibrating how banks procure machine learning capabilities, shifting from monolithic enterprise licenses to component-based service contracts. IBM leverages its hybrid cloud architecture to anchor multi-tenant banking infrastructure across regulated jurisdictions. AWS competes through dedicated financial services compliance programs that sustain institutional trust. Oracle controls database-to-model pipelines that extend its historical dominance in core banking systems.
Machine learning in banking encompasses algorithmic systems that ingest structured transaction data, unstructured customer communications, and real-time market feeds to generate predictive outputs for credit decisions, anomaly flagging, and portfolio optimization. These systems typically operate through cloud-native inference engines requiring sub-100-millisecond latency for payment authorization workflows. Fraud detection applications currently command the largest implementation budgets, while reinforcement learning for algorithmic trading represents the fastest-expanding technology segment with concentrated margin pools. Natural language processing for regulatory document analysis sits at a mature adoption curve in commercial banking, though investment banks show accelerating deployment for earnings call sentiment extraction.
The EU AI Act, SEC predictive data analytics rules, and the US Fair Credit Reporting Act collectively constrain model transparency requirements and restrict black-box algorithm deployment in lending decisions. HIPAA-aligned data handling protocols in US retail banking further shape cloud provider selection and on-premise retention policies. Stakeholders must monitor emerging model audit mandates that will determine which service architectures retain regulatory viability.
Market Dynamics
The EU AI Act's risk-based classification system is forcing banks to rearchitect their algorithmic decision-making infrastructure, compressing deployment timelines for high-risk credit scoring models and accelerating vendor consolidation around compliance-ready platforms.
Growth Catalysts
- EU AI Act risk-tier mandates:High-risk algorithmic lending systems now require mandatory conformity assessments, creating immediate procurement demand for auditable ML pipelines that satisfy national financial regulators.
- Real-time payment authorization:Sub-100-millisecond inference requirements for instant payment networks are expanding cloud-native inference engine deployments across retail banking transaction stacks.
- Fraud detection budget concentration:Supervised learning for anomaly flagging commands the largest implementation spend as retail banks expand dedicated fraud detection teams and model development centers.
Market Restraints
- Cloud provider concentration risk:AWS, IBM, and Oracle collectively anchor multi-tenant banking infrastructure, creating systemic dependency on three vendors for regulated inference workloads.
- Black-box algorithm prohibitions:The US Fair Credit Reporting Act and SEC predictive data analytics rules restrict opaque model deployment in lending decisions, forcing expensive explainability retrofits.
- Hybrid cloud infrastructure costs:On-premise data retention requirements under HIPAA-aligned protocols inflate total cost of ownership for US retail banks maintaining sensitive customer records.
Strategic Opportunities
- Reinforcement learning for algorithmic trading:Investment banks are deploying RL systems for portfolio optimization, representing the fastest-expanding technology segment with concentrated margin pools.
- NLP for regulatory document analysis:Commercial banking shows mature adoption curves for automated compliance scanning, while investment banks accelerate earnings call sentiment extraction deployments.
- API-first component procurement:Modular service contracts are displacing monolithic enterprise licenses, enabling banks to swap individual model components without platform lock-in.
Industry Challenges
- Model audit talent scarcity:Banks face acute shortages of professionals capable of conducting the technical documentation and risk assessments required by emerging EU AI Act audit mandates.
- Legacy core system integration:Oracle's historical dominance in core banking databases creates friction when connecting modern ML inference engines to decades-old transaction processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Learning in Banking Market |
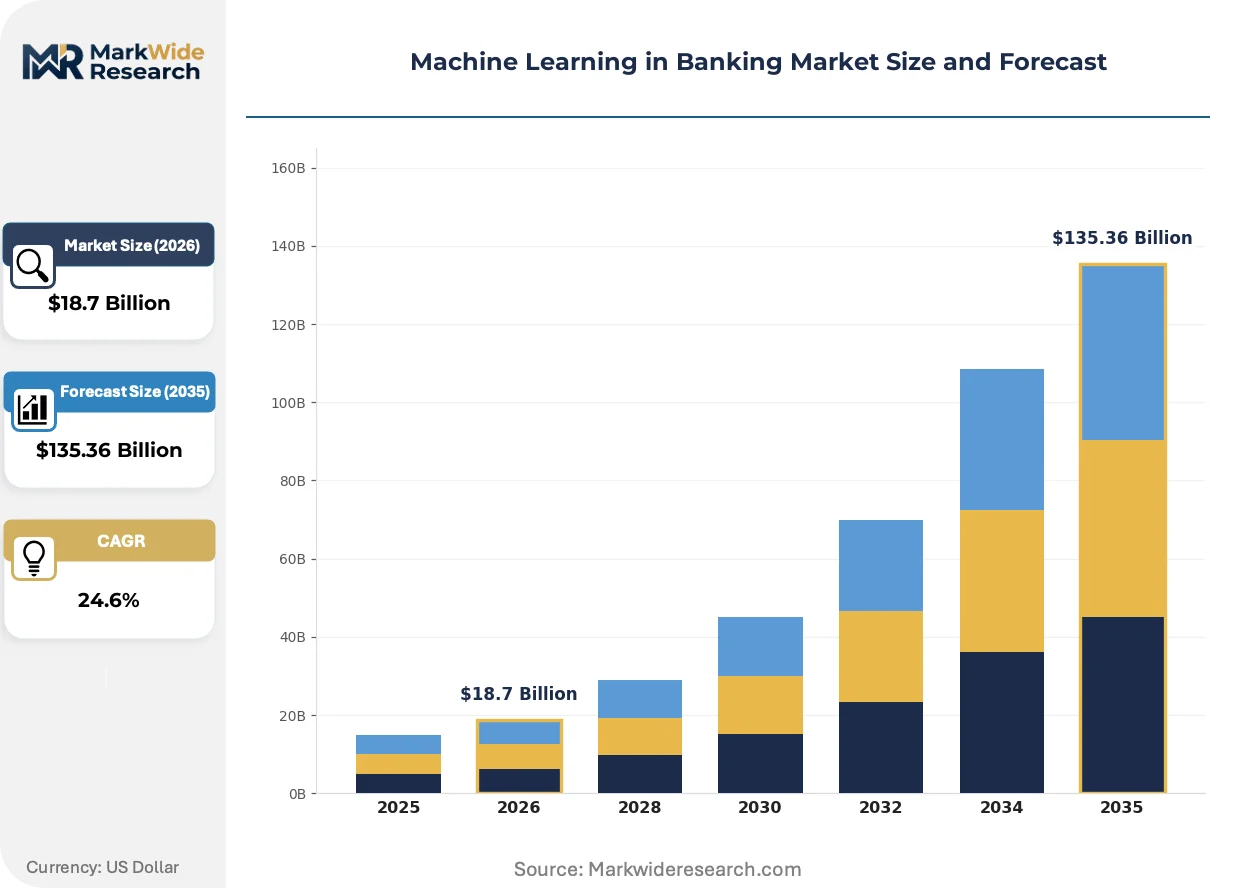
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Customer Segmentation, Predictive Analytics Technology: Supervised Learning, Unsupervised Learning, Reinforcement Learning, Natural Language Processing End User: Retail Banking, Investment Banking, Commercial Banking, Asset Management Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | IBM, AWS, Intellectyx, Finastra, Google Cloud AI, Oracle, Accenture, DataRobot, Deloitte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Learning in Banking Market Emerging Trajectories
Cloud-native inference architectures are compressing latency thresholds for real-time banking decisions while regulatory transparency mandates are reshaping how models are documented, validated, and deployed across jurisdictions.
Federated learning architectures are integrating distributed model training across bank consortiums without centralizing sensitive transaction data. European cooperative banks are adopting these frameworks at accelerated pace to satisfy GDPR data localization requirements while pooling fraud pattern recognition. This approach is integrating privacy-preserving computation into standard procurement specifications for inter-bank analytics platforms.
The EU AI Act's high-risk system designation is compelling banks to maintain comprehensive model cards and algorithmic impact assessments for credit decisions. National competent authorities in Germany and France are already enforcing documentation standards that exceed baseline requirements. Investment banking divisions face the steepest compliance curves as their algorithmic trading models fall under expanded scrutiny.
Chief data officers are consolidating vendor relationships around outcome-based performance guarantees rather than per-seat licensing. Tier-one US banks now require inference latency SLAs and model drift monitoring as standard contract terms. This restructuring is most visible in payment authorization workflows where sub-100-millisecond requirements have become non-negotiable procurement criteria.
Machine Learning in Banking Market Segmentation
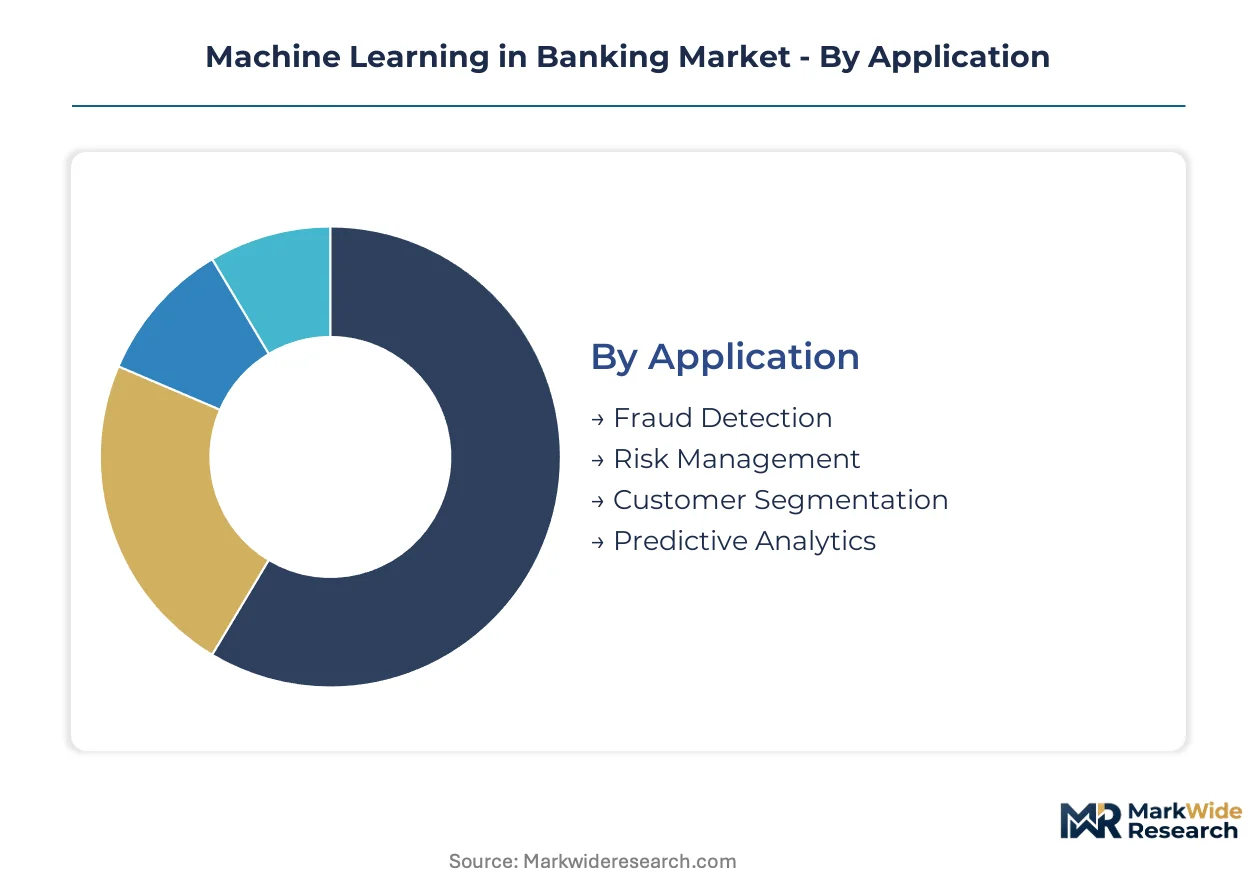
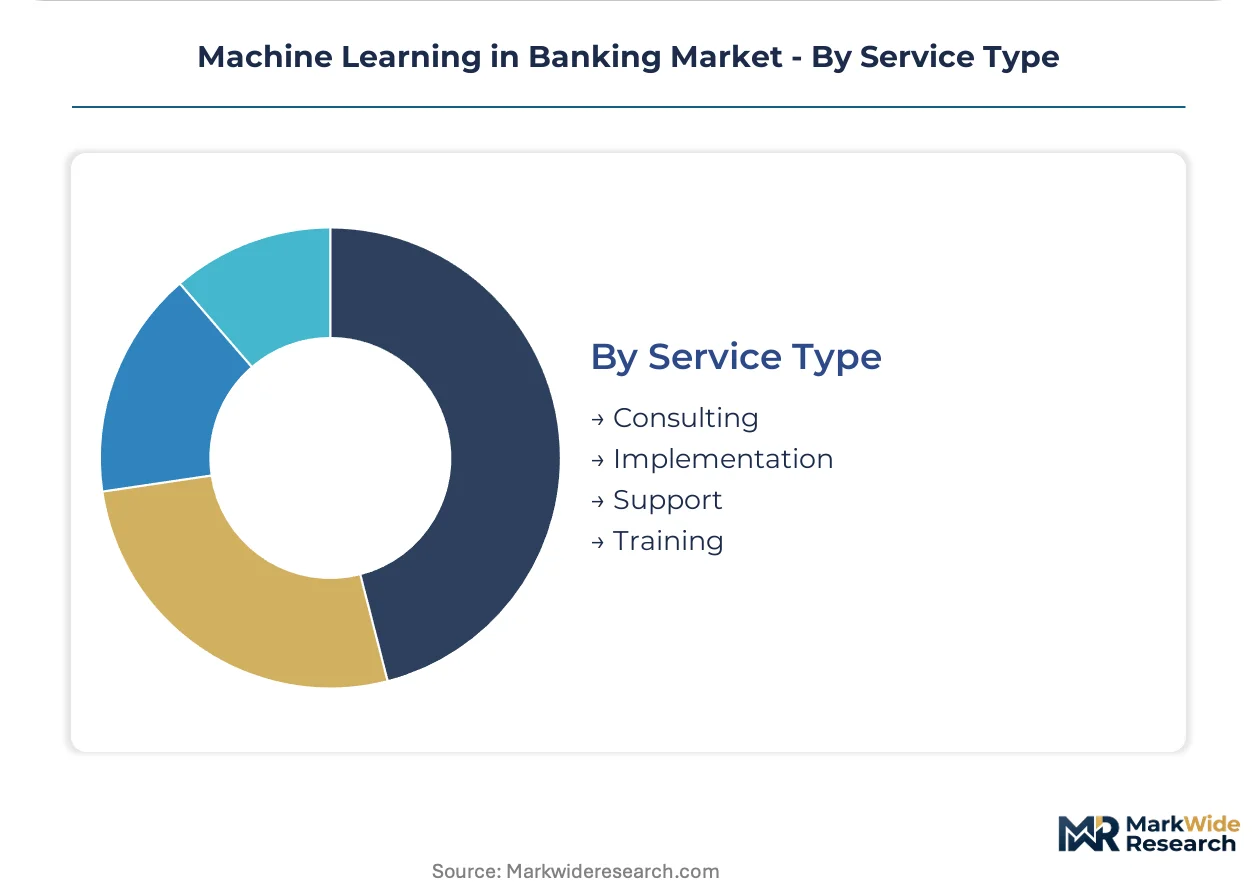
Banking machine learning deployments fragment across four structural dimensions that determine procurement patterns and vendor selection criteria. Application use cases, underlying algorithmic technologies, institutional end-user types, and service delivery models each create distinct commercial opportunities and integration requirements for platform providers.
Application:
Standalone fraud detection systems operate as discrete inference engines, while risk management and customer analytics embed more deeply into core banking infrastructure.
- Fraud Detection:Real-time transaction scoring systems process payment authorization requests through supervised anomaly classifiers. Retail banks in the United States command the largest implementation budgets as dedicated fraud detection teams expand internal model development centers. The sub-100-millisecond latency requirement for instant payment networks compresses deployment timelines and favors cloud-native inference architectures.
- Risk Management:Credit scoring and portfolio stress-testing models integrate directly with loan origination platforms and treasury systems. EU AI Act high-risk system designations are forcing mandatory conformity assessments for algorithmic lending decisions, accelerating procurement of auditable ML pipelines. German and French national competent authorities already enforce documentation standards exceeding baseline requirements.
- Customer Segmentation:Clustering algorithms identify behavioral patterns across transaction histories and digital engagement logs for targeted product positioning.
- Predictive Analytics:Forecasting models project deposit flows, churn probabilities, and lifetime value estimates to inform strategic planning.
Fraud detection leads volumes today; risk management is gaining share fastest as regulatory mandates reshape credit decision infrastructure.
Technology:
Cost tiering separates proven supervised methods from emerging reinforcement architectures that command premium implementation fees.
- Supervised Learning:Labeled training data powers classification and regression models for fraud flagging and credit default prediction. These mature techniques anchor the largest share of current banking ML spend, with labeled transaction datasets enabling rapid model iteration cycles.
- Reinforcement Learning:Sequential decision optimization drives algorithmic trading and dynamic pricing strategies. Investment banks deploy RL systems for portfolio optimization, representing the segment climbing fastest with concentrated margin pools and scarce technical talent.
- Unsupervised Learning:Anomaly detection and clustering algorithms uncover hidden patterns without labeled outcome data.
- Natural Language Processing:Text extraction and sentiment analysis parse regulatory filings, customer communications, and market intelligence. Commercial banking shows mature adoption for compliance document scanning, while investment banks accelerate earnings call sentiment extraction deployments.
Supervised learning dominates current procurement; reinforcement learning shows the steepest expansion trajectory among emerging techniques.
End User:
Customer type determines integration complexity, with retail banks requiring mass-market scale and investment banks demanding specialized performance guarantees.
- Retail Banking:Mass-market institutions deploy customer-facing chatbots, fraud prevention, and personalized product recommendations across millions of accounts. JPMorgan Chase and Bank of America have built captive AI research centers that internalize core model development capabilities.
- Investment Banking:Trading desks and advisory practices utilize algorithmic execution, M&A target identification, and risk arbitrage modeling. This segment faces the steepest EU AI Act compliance curves as proprietary trading algorithms fall under expanded scrutiny.
- Commercial Banking:Corporate lending and treasury services apply ML to cash flow forecasting and covenant monitoring.
- Asset Management:Portfolio construction and alternative data integration support systematic investment strategies.
Retail banking anchors current volumes; investment banking is expanding most quickly as trading algorithms proliferate.
Service Type:
Margin concentration varies sharply across the implementation lifecycle, with ongoing support contracts yielding recurring revenue at higher retention rates.
- Implementation:System integration and model deployment services connect ML pipelines to legacy core banking infrastructure. Oracle's historical dominance in core banking databases creates friction when embedding modern inference engines, inflating project complexity.
- Consulting:Strategy advisory and use-case identification engagements help banks prioritize ML investments. Tier-one institutions now require outcome-based performance guarantees rather than per-seat licensing, restructuring vendor economics.
- Support:Model monitoring, drift detection, and retraining services maintain production system performance. Chief data officers consolidate relationships around inference latency SLAs and automated drift alerts as standard contract terms.
- Training:Workforce development programs address acute shortages of professionals capable of conducting technical documentation and risk assessments required by emerging audit mandates.
Implementation commands the largest project values today; support services are climbing fastest as production deployments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The machine learning in banking industry traces its commercial roots to early algorithmic trading floors in Manhattan and London, where statistical arbitrage models first demonstrated scalable predictive value in financial decision-making.
United States
JPMorgan Chase and Bank of America operate captive AI research centers that internalize core model development for fraud detection and credit scoring. The SEC's predictive data analytics rules and HIPAA-aligned data retention protocols shape cloud provider selection and on-premise infrastructure requirements. New York City anchors the largest concentration of banking ML engineering talent, with Boston and San Francisco forming secondary clusters for quantitative research.
Germany
Deutsche Bank and Commerzbank accelerate procurement of auditable ML pipelines to satisfy national competent authority enforcement of EU AI Act documentation standards. The Bundesbank and BaFin coordinate stress-testing requirements for algorithmic lending models that exceed baseline EU conformity assessments. Frankfurt's financial district hosts the densest concentration of compliance-ready inference infrastructure vendors serving continental European retail banks.
United Kingdom
Barclays and HSBC deploy NLP systems for regulatory document analysis across mature commercial banking operations and accelerating investment banking sentiment extraction. The Financial Conduct Authority's evolving algorithmic trading guidelines intersect with EU AI Act extraterritorial provisions for firms maintaining European operations. London's Square Mile and Canary Wharf retain Europe's deepest pool of quantitative finance and machine learning engineering expertise.
France
BNP Paribas and Société Générale expand dedicated fraud detection teams with supervised learning models for real-time payment authorization. The Autorité de Contrôle Prudentiel et de Résolution enforces model card documentation requirements for high-risk credit scoring systems ahead of full EU AI Act implementation. Paris La Défense clusters fintech vendors specializing in explainable AI retrofits for legacy lending platforms.
India
State Bank of India and HDFC Bank scale customer-facing chatbots and personalized product recommendation engines across mass-market retail portfolios. The Reserve Bank of India's guidelines on algorithmic decision-making in digital lending create compliance frameworks that anticipate formal statutory requirements. Mumbai's Bandra-Kurla Complex and Bangalore's Electronic City host captive development centers for global banks seeking cost-optimized model training operations.
Machine Learning in Banking Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the compliance-readiness spectrum, with vendors offering auditable ML pipelines capturing pricing power while generic cloud providers compete on standardized inference capacity. The vendor base concentrates around three strategic archetypes: hybrid cloud infrastructure anchors, database-to-model pipeline controllers, and API-first component specialists. Consolidation pressures favor vendors with pre-certified regulatory frameworks over point-solution providers requiring expensive retrofitting. Dominant competitive moves include strategic partnerships with national regulators and vertical integration into model monitoring services.
Within the hybrid cloud infrastructure tier, IBM exemplifies the multi-tenant banking anchor archetype through regulated jurisdiction presence, while AWS occupies a position as the dedicated financial services compliance program standard-setter. Oracle sits within the database-to-model pipeline controller archetype, extending historical core banking system relationships into modern inference workloads. These three vendors collectively represent the systemic dependency concentration for regulated banking ML infrastructure.
| Leading Market Players |
|---|
| IBM |
| AWS |
| Intellectyx |
| Finastra |
| Google Cloud AI |
| Oracle |
| Accenture |
| DataRobot |
| Deloitte |
| Others |
Supply Flow & Price Mechanics
Cloud-native inference architectures are compressing latency thresholds while simultaneously redrawing cost economics across banking ML procurement, concentrating supply power among three hyperscalers and fragmenting pricing leverage for downstream buyers. This technological shift forces tier-one institutions to accept outcome-based contracts with embedded performance guarantees, while mid-market banks face escalating integration costs from legacy system friction.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates compliance-ready inference pipelines from commodity cloud compute and bare-metal licensing. Price differentiation hinges on audit documentation depth and sub-100-millisecond latency guarantees. Cost compression in the standard tier is intensifying because AWS, IBM, and Oracle are consolidating multi-tenant infrastructure bids. Retail banks with captive AI centers exhibit the lowest price sensitivity; regional cooperatives dependent on external model development face the highest.
Supply Chain Analysis
Freight costs for specialized GPU clusters and liquid-cooled inference hardware from Taiwan, South Korea, and the United States are inflating total landed costs for European banking infrastructure deployments. Raw material dependencies span advanced lithography silicon, high-bandwidth memory modules, and rare-earth magnet arrays for cooling systems. Single-source vulnerability concentrates in NVIDIA's datacenter GPU supply, which feeds from TSMC's N4 and N3 process nodes. Distribution runs through direct hyperscaler contracts and systems integrators like Accenture and Deloitte for on-premise hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Banking ML infrastructure represents a margin-expansion story as regulatory compliance mandates force premium-tier procurement and API-first componentization reduces switching costs for buyers. Cloud-native deployment models are compressing implementation timelines while expanding recurring revenue pools for vendors with pre-certified audit frameworks.
For Market Incumbents: Anchor compliance-ready platform positions by embedding automated model card generation and drift monitoring into standard service tiers. Defend against emerging API-first specialists through backward integration into training data pipelines. Invest in captive model audit talent pools before EU AI Act enforcement accelerates in Germany and France. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for explainable AI retrofits targeting legacy lending platforms at BNP Paribas and Société Générale. Penetrate the mid-market cooperative banking segment through federated learning consortiums that satisfy GDPR localization without centralizing data. Lead with outcome-based pricing tied to fraud detection accuracy benchmarks rather than per-seat licensing. For Investors and Strategic Acquirers: Valuations sit cheapest among component-specialist vendors lacking pre-certified regulatory frameworks but possessing core technical IP in NLP or reinforcement learning. Long-term viability favors platforms with proven inference latency SLAs and established relationships with national competent authorities. Monitor BaFin and ACPR enforcement patterns as the primary inflection signal for compliance-ready vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Partnership | BaFin collaboration accelerates EU AI Act conformity assessment timelines for German retail banks. |
| Federated Learning Consortium Launch | GDPR-compliant data pooling across European cooperative banks reduces fraud model training costs. |
| API-First Component Marketplace | Modular procurement displaces Oracle monolithic licenses for core banking ML integration. |
| Model Audit Talent Acquisition | Scarce technical documentation expertise commands premium pricing under emerging EU mandates. |
| Hybrid Cloud Inference Expansion | IBM multi-tenant architecture captures HIPAA-aligned US retail banking retention requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chief data officers, ML platform engineers, regulatory compliance leads, and procurement heads at tier-one banks with secondary validation against SEC filings, EU AI Act implementation guidance, hyperscaler financial services compliance disclosures, and cloud infrastructure capex reports. Bottom-up segment sizing and top-down macro anchoring were cross-checked for consistency.
Historical reference periods spanning pre-pandemic baselines through recent regulatory implementation phases anchored the projection horizon across application, technology, end-user, and service-type dimensions. CAGRs were derived from segmented growth rate modeling incorporating real-time payment network expansion, EU AI Act enforcement timelines, and captive AI center buildout patterns at JPMorgan Chase and Bank of America.
Revisions become necessary when EU AI Act enforcement intensity exceeds baseline assumptions, hyperscaler supply constraints disrupt GPU availability, or federated learning adoption accelerates beyond cooperative banking into investment banking divisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
France Data Analytics in Banking Market
Banking
Banking ERP Software Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Smart Machines in Banking Market
Banking
E-Banking Market
Banking
Smart Banking Solutions Market
Banking
Cloud-Based Core Banking Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Global Banking Systems Software Market
Banking
Banking Credit Analytics Market
Banking
Middle East Data Analytics in Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
US Data Analytics in Banking Market
Banking
Corporate Digital Banking Market
Banking
US Retail Banking Market
Banking
Blockchain in Retail Banking Market