
 Retail Banking Market | 2026-2036
Retail Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Banking Market Analysis
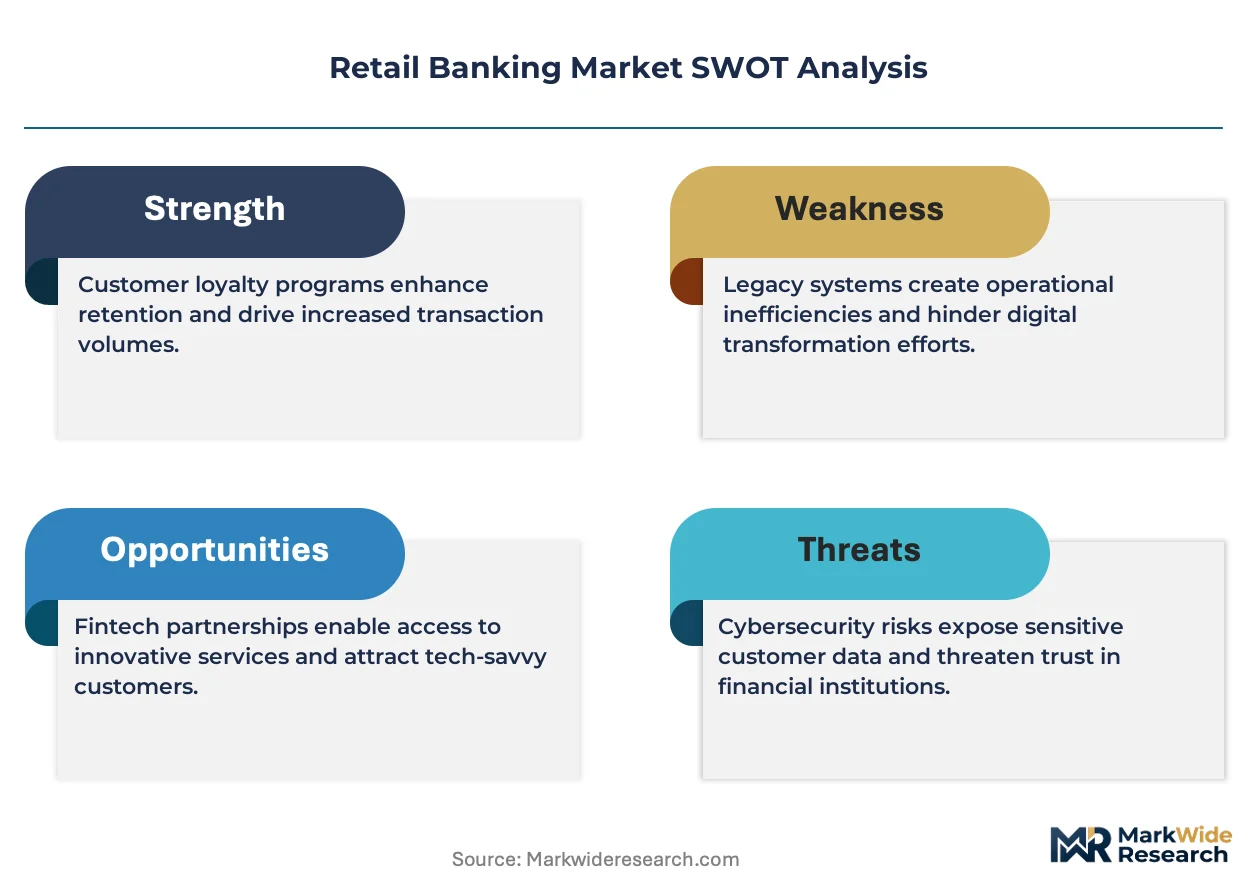
Fee-based advisory revenue is rewriting profit allocation across retail banking value chains. JPMorgan Chase leverages its wealth management infrastructure to capture recurring non-interest income. Bank of America anchors its competitive stance through digital channel density and consumer deposit scale. Wells Fargo specializes in mortgage servicing workflows that sustain long-duration customer relationships.
Retail banking encompasses deposit-taking, lending, and payment services delivered to individual and small business clients through regulated financial intermediaries, operating on net interest margin spreads typically measured in basis points and supplemented by interchange fees, account service charges, and advisory commissions. Its primary commercial purpose is maturity transformation—converting short-term liabilities into longer-term assets while managing liquidity, credit, and operational risk. Checking and savings accounts dominate liability-side volume but carry thin spreads, while mortgages and loans concentrate asset-side returns with higher duration risk. Mobile banking and digital wallets represent the fastest-expanding technology segment, displacing branch-based transaction volume and compressing cost-to-serve ratios.
The Federal Reserve, OCC, and CFPB collectively shape US retail banking through capital adequacy rules, consumer protection enforcement, and fair lending oversight that dictate product pricing and account access standards. The SEC and state insurance regulators extend this framework where banks distribute investment and annuity products through dual-registered channels. Stakeholders must monitor how generative AI deployment in credit decisioning triggers supervisory scrutiny under fair lending statutes and emerging algorithmic accountability requirements.
Market Dynamics
Deposit beta pressure and generative AI deployment are compressing net interest margins while forcing infrastructure reinvestment across retail banking value chains.
Growth Catalysts
- EU AI Act compliance mandates:European banks are accelerating explainable credit-scoring system upgrades to meet algorithmic accountability deadlines, creating demand for transparent machine-learning infrastructure.
- Small business cash management integration:Entrepreneurs now expect unified receivables, payables, and liquidity forecasting within single digital interfaces, expanding product attach rates.
- India mobile-first distribution:Digital-only platforms serve previously underbanked populations through smartphone penetration, bypassing legacy branch economics entirely.
Market Restraints
- Deposit beta volatility:Rising rate environments force faster pass-through to savers than borrowers, squeezing spread capture and pressuring liability-side pricing discipline.
- Core banking system concentration:Three incumbent technology vendors dominate legacy infrastructure, creating switching costs and vendor lock-in for mid-tier institutions.
- Fintech deposit substitution:High-yield savings aggregators and Treasury management platforms divert transactional balances from traditional insured deposits.
Strategic Opportunities
- Embedded finance convergence:Banking-as-a-Service APIs and commerce platform integration enable deposit and lending products to surface within non-financial customer journeys.
- Wealth management adjacencies:Mass-affluent segments seek unified banking and investment interfaces, creating recurring fee revenue pools beyond net interest income.
- United Kingdom open banking mandates:PSD2-driven data-sharing protocols lower customer acquisition costs for account aggregation and personalized financial management tools.
Industry Challenges
- Model risk management talent scarcity:Institutions lack sufficient quantitative analysts versed in both credit underwriting and algorithmic fairness validation under evolving supervisory guidance.
- Core system migration complexity:Decades-old COBOL architectures resist cloud-native replacement without multi-year transformation programs and operational continuity risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Banking Market |
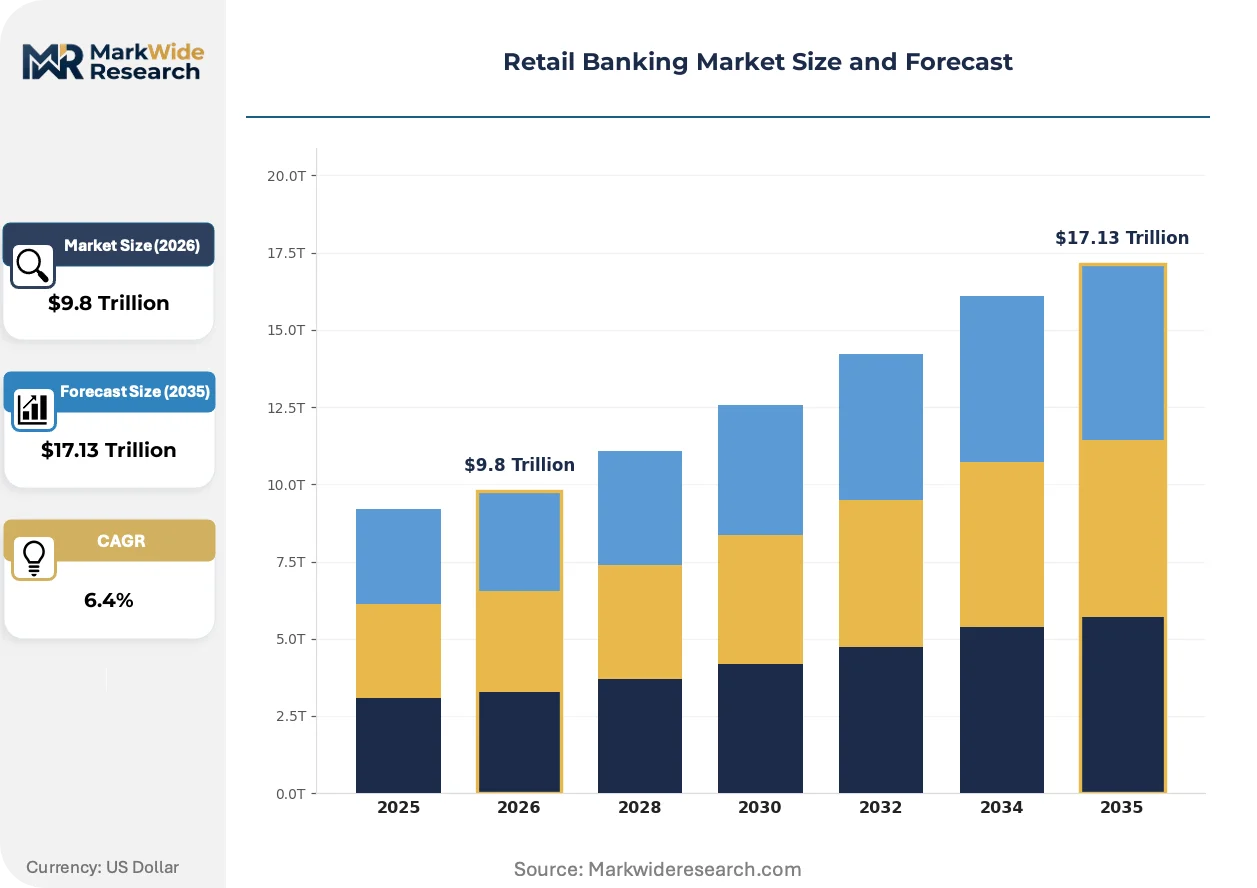
| Market Size in 2026 | $9.8 Trillion |
| Market Size in 2035 | $17.13 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Checking Accounts, Savings Accounts, Loans, Mortgages Customer Type: Individual Consumers, Small Businesses, Corporations, Non-profits Technology: Mobile Banking, Online Banking, ATMs, Digital Wallets Channel: Branch, Online, Mobile, Telephone |
| Companies Covered | JPMorgan Chase, Bank of America, Wells Fargo, Citigroup, U.S. Bank, PNC Financial Services, Truist Financial, Capital One, HSBC Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Banking Market Emerging Trajectories
Virtualized delivery infrastructure and algorithmic decision systems are collapsing physical distribution requirements while elevating data governance standards across retail banking operations.
Generative AI is virtualizing credit decision workflows by automating document extraction, income verification, and exception handling. Regional banks and credit unions adopt these tools fastest to match large-bank underwriting speed. The technology is virtualizing back-office functions previously requiring branch-based manual review, compressing cost-to-originate metrics by half.
The EU AI Act establishes risk-tiered compliance obligations for credit-scoring algorithms, mandating human oversight and bias testing for high-risk automated decisions. European institutions now embed fairness metrics directly into model development pipelines. Retail mortgage and small business lending segments face the steepest documentation and audit requirements.
Self-directed digital onboarding is replacing branch-based account origination for mass-market segments, with mobile identity verification and e-signature workflows becoming baseline expectations. Neobanks and technology-forward incumbents capture switching customers through sub-ten-minute enrollment experiences. India and Brazil demonstrate the most pronounced channel migration velocity among large population markets.
Retail Banking Market Segmentation
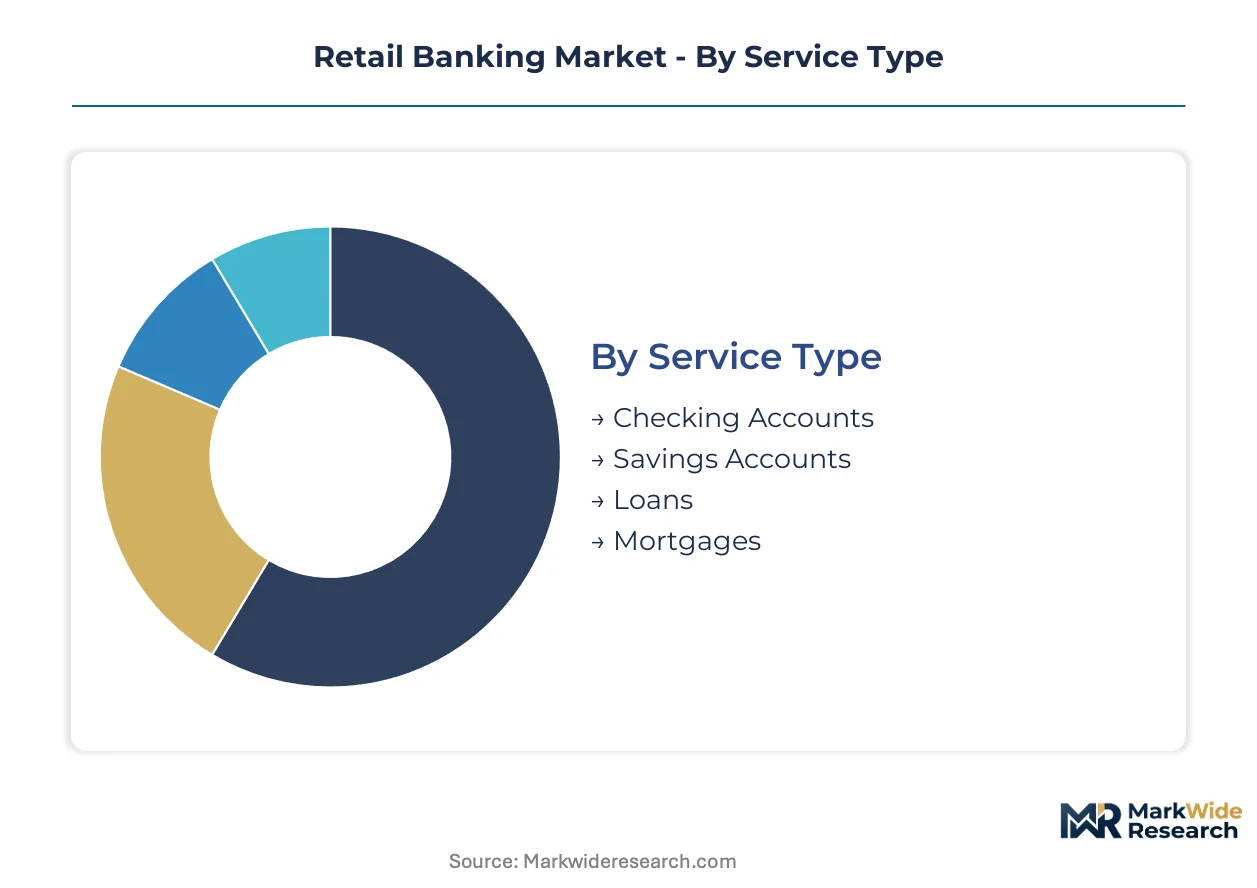
Retail banking segmentation reveals how service delivery, customer economics, and technology infrastructure allocate capital and operating expense across distinct value pools. Understanding these divisions exposes where margin compression concentrates and where fee-based revenue opportunities emerge.
Service Type:
After-sales service intensity varies sharply across product lines, with transaction accounts requiring continuous platform maintenance while lending products demand ongoing credit monitoring and servicing workflows.
- Checking Accounts:Core transactional products with thin net interest margins rely on interchange fees and overdraft charges for profitability. Demand concentrates among individual consumers in India and Brazil where digital-first platforms displace cash-based payments. Deposit beta volatility squeezes spread capture as rate environments shift.
- Savings Accounts:Interest-bearing liability products with higher funding costs but stickier customer relationships. Small businesses in the United Kingdom seek integrated cash management tools through open banking APIs. Fintech deposit substitution diverts balances to high-yield aggregators.
- Loans:Asset-side products spanning personal, auto, and small business credit with duration risk and credit spread components.
- Mortgages:Long-duration secured lending with servicing revenue streams and prepayment risk exposure.
By volume, checking accounts lead. By growth pace, small business loans are expanding most quickly.
Customer Type:
Cost-to-serve economics stratify sharply across customer categories, with individual consumers driving transaction volume but corporations commanding relationship pricing and treasury management fees.
- Individual Consumers:Mass-market segment with high account counts but fragmented balances and price-sensitive switching behavior. Mobile-first distribution in India captures underbanked populations through smartphone penetration. Generative AI deployment in credit decisioning raises supervisory scrutiny under fair lending statutes.
- Small Businesses:Entrepreneurs demand unified receivables, payables, and liquidity forecasting within single digital interfaces. EU AI Act compliance mandates accelerate explainable credit-scoring upgrades for automated underwriting. Embedded finance convergence enables banking products within commerce platform journeys.
- Corporations:Institutional clients with complex treasury needs and negotiated pricing structures.
- Non-profits:Mission-driven organizations with specialized compliance requirements and grant-dependent cash flows.
By volume, individual consumers dominate account openings. By growth pace, small businesses are climbing the fastest.
Technology:
Application intensity determines infrastructure investment priorities, with mobile and digital wallet platforms commanding the largest development budgets while legacy ATM networks face rationalization pressures.
- Mobile Banking:Smartphone-native interfaces displacing branch transaction volume and compressing cost-to-serve ratios. Self-directed digital onboarding with identity verification and e-signature workflows becomes baseline expectation. Neobanks capture switching customers through sub-ten-minute enrollment experiences.
- Online Banking:Browser-based platforms serving complex product research and account management needs for mass-affluent segments.
- ATMs:Cash dispensing infrastructure facing volume decline as digital payments proliferate.
- Digital Wallets:Payment credential storage and tokenization enabling contactless commerce integration.
By volume, mobile banking leads transaction migration. By growth pace, digital wallets are gaining share fastest.
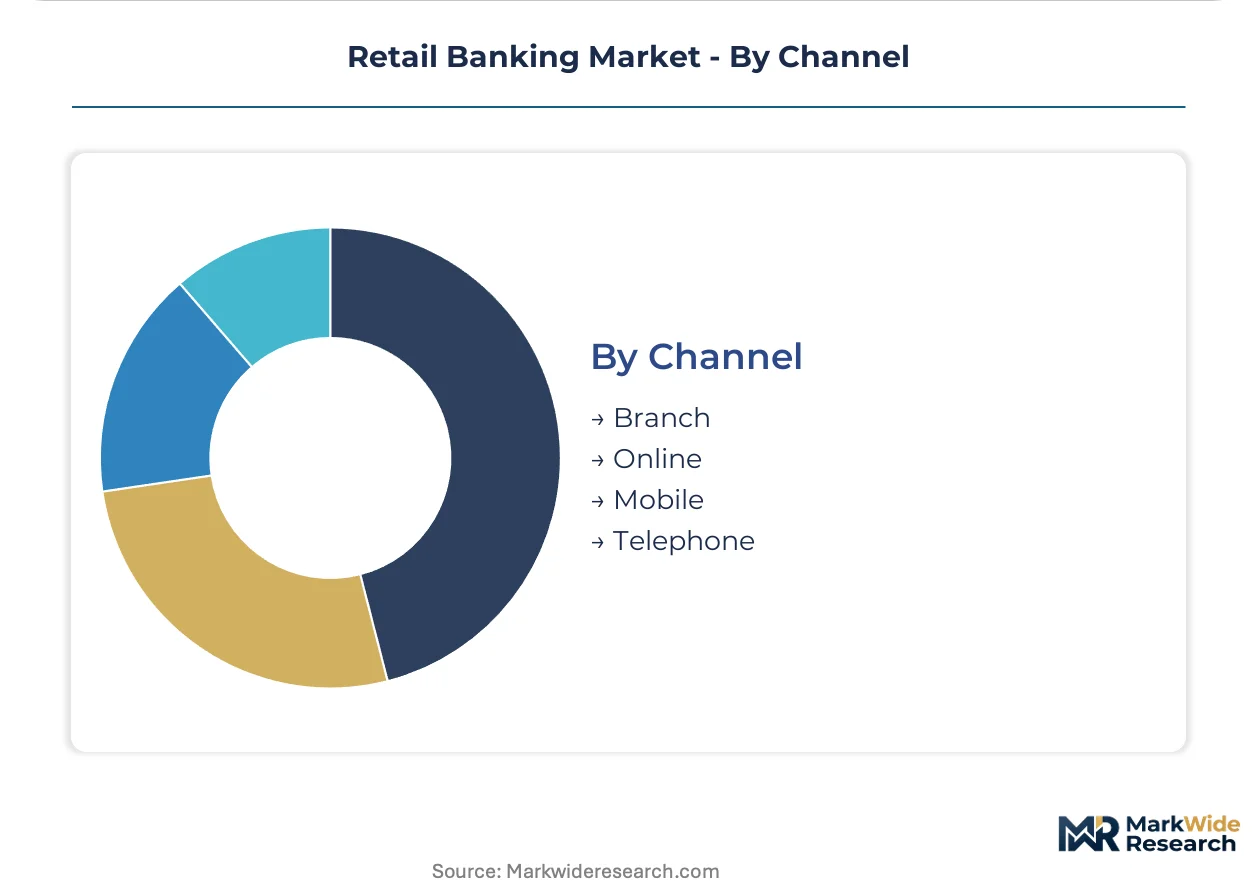
Channel:
Margin structure varies by fulfillment method, with branch networks carrying fixed real estate costs while digital channels scale with variable technology expense.
- Branch:Physical distribution points sustaining mortgage servicing workflows and advisory relationships at Wells Fargo and comparable institutions. Core banking system concentration in three incumbent vendors creates switching costs for branch technology refresh.
- Online:Web-based origination and servicing platforms with lower acquisition costs than physical presence.
- Mobile:Application-based interfaces with biometric authentication and push notification engagement.
- Telephone:Voice channel handling exception resolution and elderly customer segments.
By volume, mobile channels lead transaction throughput. By growth pace, online origination is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deposit beta sensitivity varies sharply across geographies, with Indian and Brazilian savers exhibiting highest rate elasticity while United Kingdom and German customers demonstrate stronger relationship stickiness.
United States
Mass-affluent households drive wealth management adjacency demand as JPMorgan Chase and Bank of America deploy unified banking-investment interfaces. The Federal Reserve, OCC, and CFPB collectively enforce capital adequacy rules and fair lending oversight that shape product pricing. Deposit concentration clusters in New York and Charlotte sustain the largest liability bases.
United Kingdom
Open banking mandates under PSD2 accelerate account aggregation and personalized financial management tool adoption among small businesses. The Financial Conduct Authority and Prudential Regulation Authority supervise algorithmic accountability standards alongside the EU AI Act's extraterritorial influence. London fintech clusters around the Square Mile and Canary Wharf pioneer embedded finance API development.
India
Underbanked populations access digital-first platforms through smartphone penetration, bypassing legacy branch economics entirely. The Reserve Bank of India regulates payment system operators and digital lending guidelines while promoting financial inclusion. Mumbai and Bangalore host the densest concentrations of neobank headquarters and mobile wallet infrastructure.
Germany
Savings bank federations and cooperative structures face margin compression as fintech deposit substitution diverts transactional balances. BaFin enforces EU AI Act compliance timelines for credit-scoring algorithm documentation and bias testing. Frankfurt's banking district anchors continental European treasury management and cross-border payment processing.
Brazil
Self-directed digital onboarding with biometric identity verification captures switching customers through sub-ten-minute enrollment experiences. The Central Bank of Brazil's Pix instant payment system displaces cash-based transactions and compresses interchange fee pools. São Paulo's financial district concentrates digital wallet and neobank engineering talent.
Retail Banking Market Vendor Landscape
Capability concentration sits with universal banks commanding wealth management infrastructure; scale advantage sits with deposit-heavy institutions optimizing digital channel density. The market structures around three tiers: integrated financial supermarkets, specialized lending and servicing platforms, and technology-forward direct banks. Strategic moves concentrate on embedded finance API partnerships and core banking system modernization programs.
Within the universal banking tier, JPMorgan Chase and Bank of America exemplify institutions leveraging wealth management infrastructure to capture recurring non-interest income. Wells Fargo occupies a specialized position in mortgage servicing workflows that sustain long-duration customer relationships. These three represent divergent archetypes: fee-based advisory integration, digital channel scale, and secured lending servicing depth.
| Leading Market Players |
|---|
| JPMorgan Chase |
| Bank of America |
| Wells Fargo |
| Citigroup |
| U.S. Bank |
| PNC Financial Services |
| Truist Financial |
| Capital One |
| HSBC Holdings |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Singapore undersea cable corridor carries cloud infrastructure costs that cascade through retail banking technology procurement, concentrating pricing power among three incumbent core banking vendors while forcing tiered service differentiation across digital and branch delivery channels.
Pricing Analysis
Long-term offtake contracts dominate core banking system procurement, locking mid-tier institutions into multi-year service agreements with limited renegotiation leverage. Three-tier pricing structure across premium, standard, and economy levels separates white-glove implementation support from self-service API tiers. Cost compression in the standard tier intensifies because fintech deposit substitution erodes the deposit bases that fund technology budgets. Small business segments exhibit highest price sensitivity due to fragmented balances, while mass-affluent households accept premium pricing for unified wealth management interfaces.
Supply Chain Analysis
Upstream feedstock for retail banking technology draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with cloud compute hardware resting on advanced node chip supply. Legacy COBOL talent pools, API middleware licenses, and biometric authentication modules constitute critical input dependencies. Single-source vulnerability concentrates in the three dominant core banking vendors serving the majority of mid-tier institutions. Distribution runs through direct enterprise sales teams and systems integrator partnerships for implementation deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail banking transformation hinges on scarce quantitative talent capable of bridging credit underwriting expertise with algorithmic fairness validation, creating asymmetric advantage for institutions that secure this hybrid skill base before supervisory deadlines tighten.
For Market Incumbents: Pre-empt generative AI deployment risks by embedding fairness metrics directly into model development pipelines ahead of EU AI Act enforcement timelines. Accelerate core banking system modernization through phased cloud-native migration to reduce vendor lock-in exposure. Defensive consolidation of wealth management infrastructure captures recurring fee revenue pools as net interest margins compress. For New Entrants and Emerging Players: Pursue embedded finance convergence through Banking-as-a-Service APIs that surface deposit and lending products within non-financial customer journeys. White-space concentration sits in India mobile-first distribution and United Kingdom open banking aggregation, where regulatory frameworks lower customer acquisition barriers. Go-to-market execution should anchor on sub-ten-minute digital onboarding experiences with biometric identity verification. For Investors and Strategic Acquirers: Carve-out targets emerge from universal bank technology subsidiaries and regional bank digital transformation programs stalled by core system migration complexity. Long-term viability favors institutions with demonstrated model risk management capabilities and explainable credit-scoring infrastructure. The signal to watch is supervisory guidance tightening on algorithmic accountability standards across multiple jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Core Banking Modernization | Cloud-native replacement of COBOL architectures reduces operational continuity risk and vendor concentration. |
| Embedded Finance API Development | Banking-as-a-Service partnerships with e-commerce platforms expand deposit acquisition beyond traditional channels. |
| Explainable AI Implementation | Fairness metric integration satisfies EU AI Act documentation requirements for automated credit decisions. |
| Wealth Management Integration | Unified banking-investment interfaces capture mass-affluent fee revenue beyond net interest income spreads. |
| Mobile-First Distribution Buildout | Smartphone-native platforms serve underbanked populations in India and Brazil through biometric onboarding. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, earnings disclosures, and technology vendor documentation to establish baseline market sizing. Primary interviews engaged retail banking executives, model risk officers, fintech product managers, and regulatory compliance leads across the United States, United Kingdom, India, Germany, and Brazil. Secondary sources encompassed Federal Reserve and OCC guidance documents, EU AI Act regulatory texts, Reserve Bank of India circulars, and cloud infrastructure capex disclosures from hyperscaler providers. Bottom-up segmentation analysis triangulated against top-down macroeconomic indicators.
Forecast inputs considered deposit beta sensitivity curves, generative AI adoption velocity, open banking API penetration rates, and mobile wallet transaction migration patterns across the projection horizon. Segmentation modeling spanned service type, customer category, technology platform, and delivery channel dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution effects. Core banking system replacement cycles and neobank customer acquisition economics served as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, deposit flight velocity, or semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions regarding supervisory enforcement timelines and technology adoption S-curves. Cross-checking against central bank payment system statistics and fintech funding databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
API Banking Market
Banking
Retail Banking IT Spending Market
Banking
Cardless ATM Market
Banking
India Data Analytics in Banking Market
Banking
US Commercial Banking Market
Banking
Smart Banking Solutions Market
Banking
Cybersecurity in Banking Market
Banking
UK Banking as a Service Market
Banking
Australia Data Analytics in Banking Market
Banking
Investment Banking Market
Banking
Internet of Things (IoT) in Banking Market
Banking
Armenia Banking Market
Banking
Third-Party Banking Software Market
Banking
Asia-Pacific Islamic Finance Market
Banking
UK Retail Banking Market
Banking
Open Banking Market