
 Banking As a Service (BAAS) Market | 2026-2036
Banking As a Service (BAAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Banking As a Service (BAAS) Market Outlook
The EU Green Deal's digital finance taxonomy is realigning how financial infrastructure providers prioritize energy-efficient data center operations and carbon disclosure. Solarisbank AG leverages its German banking license to anchor embedded finance services across continental Europe. Railsr specializes in card-issuing and payment APIs, competing aggressively with vertically integrated providers. Marqeta sustains technology leadership in programmable payment card infrastructure, extending its developer-centric platform to neobank and fintech clients.
Banking as a Service denotes a licensed banking infrastructure model where regulated institutions expose core banking functions—account creation, payment processing, compliance verification—through APIs to non-bank entities. API integration constitutes the technical backbone, requiring RESTful or GraphQL protocols with sub-second latency thresholds and OAuth 2.0 authentication frameworks to enable real-time financial operations for third-party applications. Payment processing dominates current revenue pools due to transaction volume density, while cloud-based deployment is accelerating fastest as tier-one providers migrate from on-premises legacy stacks to multi-tenant SaaS architectures. White-label solutions command premium positioning among neobanks seeking rapid market entry without proprietary banking license acquisition.
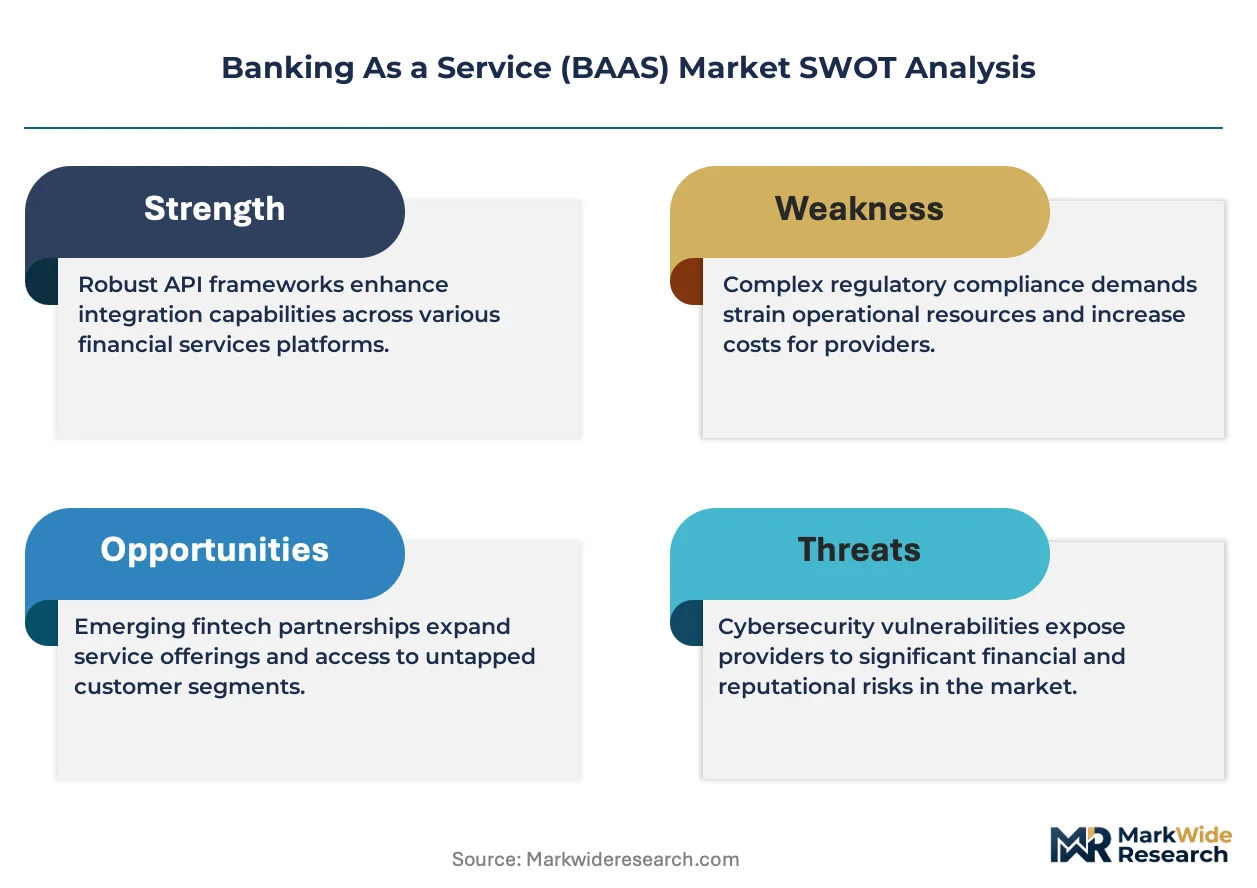
The European Banking Authority's PSD3 framework and the UK's Financial Conduct Authority's operational resilience requirements are tightening API security standards and incident reporting obligations for BaaS providers. The US Federal Reserve's FedNow instant payment system and the Securities and Exchange Commission's custody rule proposals are reshaping demand for real-time settlement infrastructure and qualified custodian partnerships. Stakeholders must monitor how divergent regulatory timelines across jurisdictions fragment platform standardization and force architecture decisions that lock in geographic service capabilities.
Market Dynamics
API-driven banking infrastructure is consolidating control over financial service delivery, as licensed institutions expose core functions through standardized interfaces that compress the traditional bank-to-customer relationship into embedded software layers.
Growth Catalysts
- PSD2 Open Banking Mandates:The European Union's revised Payment Services Directive forces legacy banks to expose account data and payment initiation capabilities through standardized APIs, creating regulatory pull for BaaS infrastructure.
- Embedded Finance Integration:E-commerce platforms and SaaS providers are embedding lending, payments, and card issuance directly into customer journeys, driving demand for licensed banking backends they cannot build independently.
- Cloud-Native Core Banking Migration:Tier-one financial institutions are abandoning on-premises legacy stacks for multi-tenant SaaS architectures, enabling faster API deployment and reducing time-to-market for third-party financial products.
Market Restraints
- Banking License Scarcity:Full BaaS operation requires a regulated banking license, with concentration of viable licenses in Germany and the United Kingdom creating geographic supply bottlenecks for pan-European service expansion.
- Compliance Cost Escalation:Anti-money laundering verification, know-your-customer protocols, and transaction monitoring systems impose fixed operational overhead that squeezes margins on low-value accounts.
- API Standardization Fragmentation:Divergent technical specifications between the European Banking Authority's PSD3 framework and the UK's Financial Conduct Authority requirements force platform architectures that lock in geographic service limitations.
Strategic Opportunities
- Cross-Border SME Banking:Small and medium enterprises operating across multiple European jurisdictions remain underserved by traditional correspondent banking relationships, creating white space for unified multi-currency account infrastructure.
- Real-Time Settlement Infrastructure:The US Federal Reserve's FedNow instant payment system and similar schemes are reshaping treasury operations, opening demand for BaaS providers that can embed instant settlement into enterprise software.
- Carbon-Linked Financial Products:The EU Green Deal's digital finance taxonomy is mandating carbon disclosure in financial services, enabling BaaS platforms to differentiate through energy-efficient data center operations and climate-linked account offerings.
Industry Challenges
- OAuth 2.0 and Cryptographic Key Management:Sub-second latency requirements for payment APIs demand specialized engineering talent in zero-trust security architectures, with scarcity of qualified personnel extending implementation timelines.
- Legacy Core System Integration:Many licensed banks operate on decades-old mainframe infrastructure, and API layering atop these systems introduces failure points that complicate service-level agreement guarantees to embedded finance clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking As a Service (BAAS) Market |
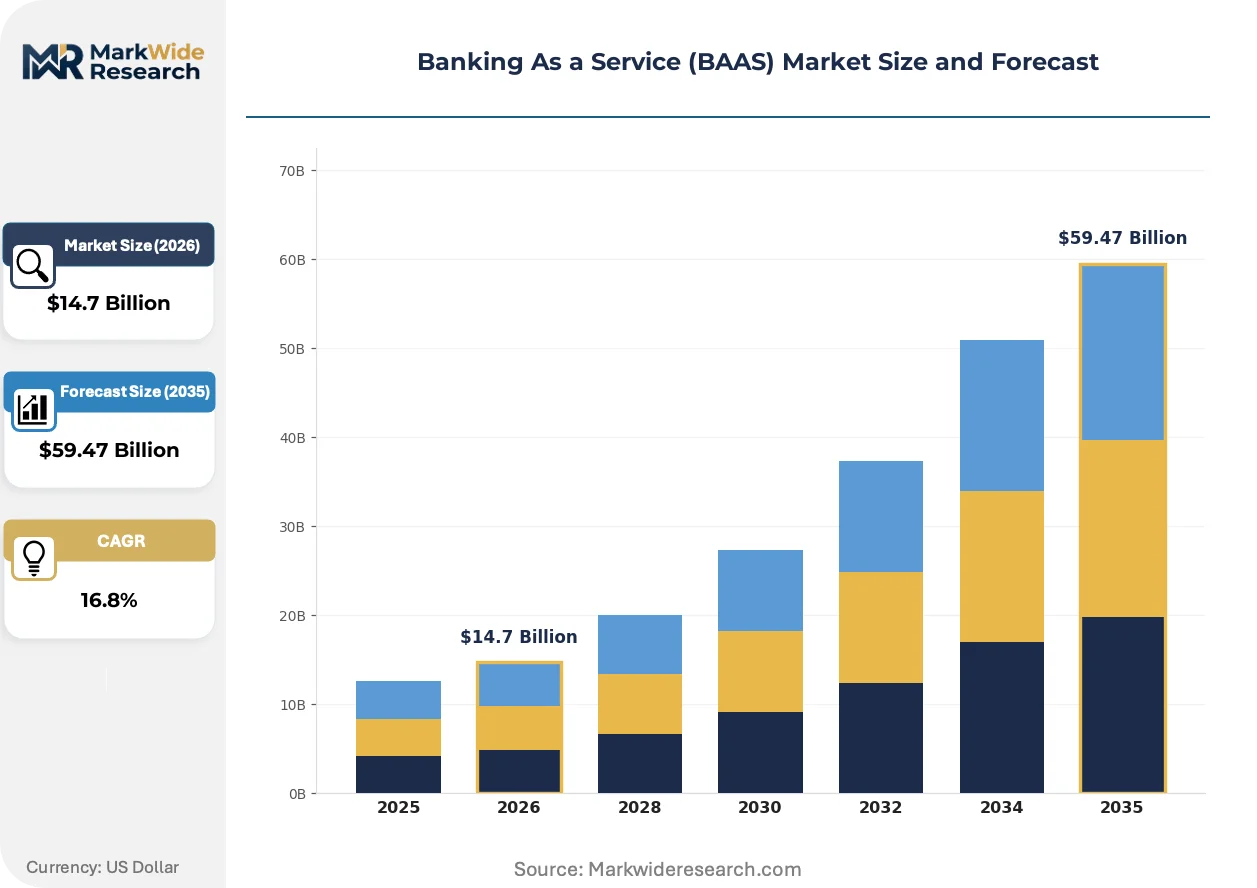
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $59.47 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Account Verification, API Integration, Fraud Detection Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Tenant End User: Fintech Companies, Traditional Banks, Credit Unions, Neobanks Feature: White-Label Solutions, Customizable Accounts, Transaction Monitoring, Compliance Management |
| Companies Covered | Green Dot Bank, Solarisbank AG, PayPal Holdings, Inc., Marqeta, Mambu, Railsr, Block, Inc., Fiserv, ClearBank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking As a Service (BAAS) Market Strategic Shifts
GraphQL query protocols and event-driven architectures are displacing RESTful API designs as the dominant technical foundation, enabling more flexible data fetching and real-time webhook notifications that reduce polling overhead for high-frequency financial operations.
Containerized microservices deployed on Kubernetes orchestration platforms is consolidating how BaaS providers manage core banking functions. Neobanks and fintech developers are adopting these architectures to achieve horizontal scaling during transaction spikes. This consolidation is compressing the infrastructure cost gap between established banks and digital-native competitors, forcing legacy institutions to accelerate cloud migration timelines.
The European Banking Authority's PSD3 framework is tightening API security standards and incident reporting obligations for BaaS providers. This regulatory pressure is elevating operational resilience requirements above prior PSD2 thresholds. Tier-one providers serving UK and EU markets simultaneously are responding by bifurcating their technical stacks to satisfy divergent compliance timelines.
Subscription-based pricing for embedded finance modules is displacing per-transaction fee structures among enterprise software vendors. SaaS platforms distributing banking services to their customer bases prefer predictable cost models that align with their own recurring revenue economics. This preference shift is most visible in Germany and the United Kingdom, where neobank-BaaS partnerships have matured toward volume-commitment contracts with fixed monthly platform fees.
Banking As a Service (BAAS) Market Segmentation
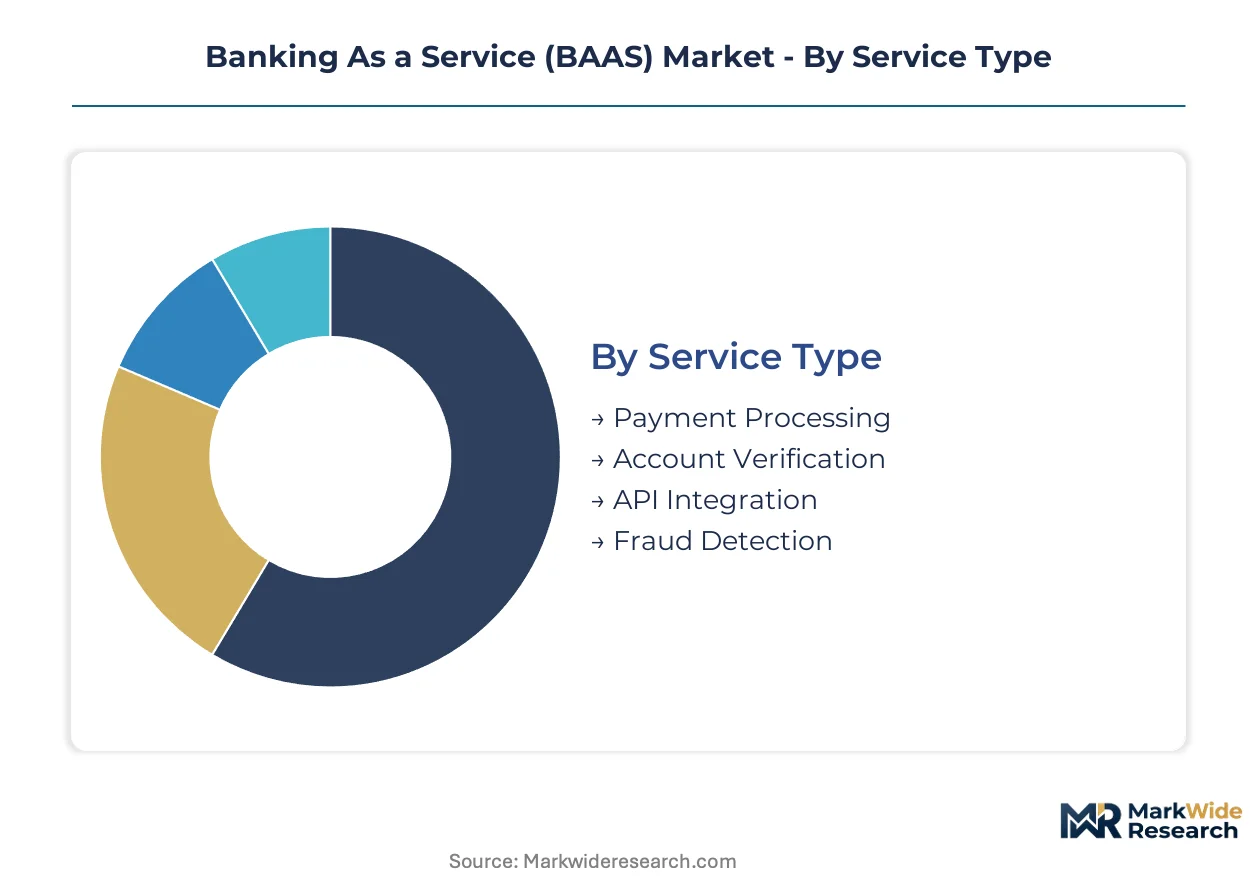
Banking as a Service platforms fragment across technical implementation paths, each segment imposing distinct latency thresholds, compliance architectures, and integration complexity. Understanding these divisions clarifies where infrastructure investments concentrate and which service configurations unlock geographic expansion.
Service Type:
Upgrade cycles in core banking APIs accelerate as embedded finance clients demand sub-second response times and OAuth 2.0 security frameworks that legacy protocols cannot support.
- Payment Processing:RESTful and GraphQL interfaces handle transaction authorization, settlement routing, and real-time ledger updates. German neobanks and UK fintech platforms drive concentration here, compelled by PSD2 mandate timelines and FedNow instant settlement requirements. Volume density in this segment sustains the largest revenue pools across BaaS operations.
- API Integration:Protocol standardization layers expose account creation, balance inquiry, and payment initiation to third-party developers. Demand clusters among SaaS providers embedding financial services, constrained by the scarcity of engineering talent fluent in zero-trust security architectures and cryptographic key management.
- Account Verification:Know-your-customer and anti-money laundering checks execute through automated document scanning and biometric validation.
- Fraud Detection:Machine learning models flag anomalous transaction patterns in real-time streams.
Volume placements concentrate in Payment Processing; the faster expansion belongs to API Integration.
Deployment:
Cost tiering separates enterprise-grade multi-tenant architectures from constrained on-premises installations that carry heavier fixed infrastructure burdens.
- Cloud-Based:Kubernetes-orchestrated microservices enable horizontal scaling during transaction spikes. Tier-one providers migrating from legacy mainframe stacks favor this model, reducing time-to-market for embedded finance products while satisfying EU Green Deal energy-efficiency disclosure requirements.
- Multi-Tenant:Shared infrastructure partitions isolate client data while consolidating operational overhead. Neobanks across Germany and the United Kingdom prefer this configuration for its predictable subscription economics aligned with recurring revenue models.
- Hybrid:Sensitive compliance functions remain on-premises while customer-facing APIs deploy to cloud edge nodes.
- On-Premises:Legacy core banking systems persist in regulated institutions with decades-old mainframe dependencies.
Volume placements concentrate in Cloud-Based; Multi-Tenant gains share fastest among new market entrants.
End User:
Customer type determines API complexity tolerance, with fintech developers accepting granular technical documentation that traditional bank procurement departments reject.
- Fintech Companies:Venture-backed startups and scale-ups consume modular banking services through developer-centric documentation. These clients cluster in London and Berlin, drawn by proximity to Solarisbank AG and Railsr infrastructure and the regulatory clarity of UK FCA and German BaFin frameworks.
- Neobanks:Digital-native retail banks white-label entire banking stacks to accelerate market entry without license acquisition. Their procurement patterns favor volume-commitment contracts with fixed monthly platform fees over per-transaction pricing.
- Traditional Banks:Established institutions layer APIs atop legacy core systems to extend service reach.
- Credit Unions:Member-owned cooperatives adopt BaaS selectively for payment card issuance and digital account opening.
Volume placements concentrate among Fintech Companies; Neobanks show the steepest expansion trajectory.
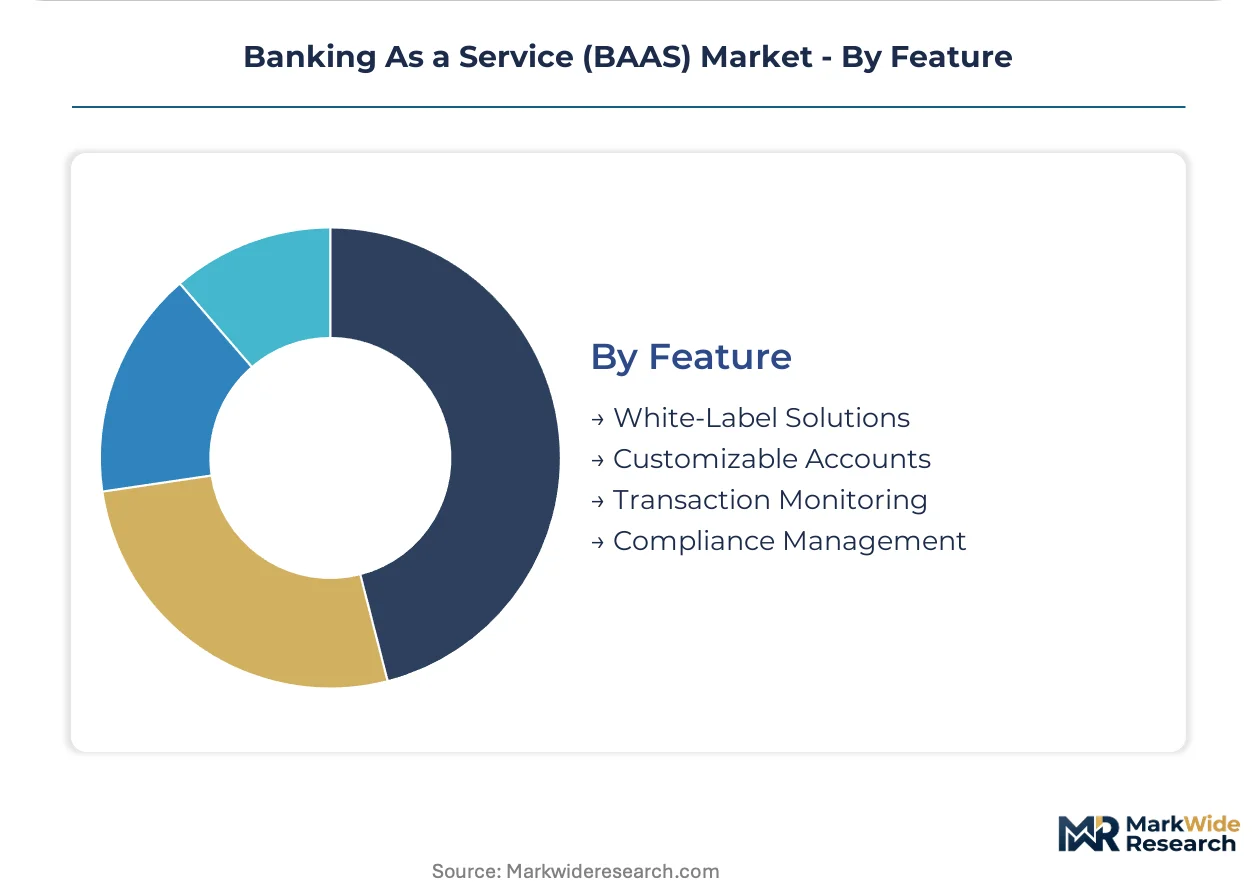
Feature:
Margin structures diverge sharply between standardized white-label modules and compliance-heavy customizable configurations that demand dedicated engineering support.
- White-Label Solutions:Pre-built mobile interfaces, card designs, and onboarding flows enable rapid brand deployment. These offerings command premium positioning among neobanks seeking speed-to-market, particularly in Germany where banking license scarcity extends development timelines.
- Compliance Management:Automated regulatory reporting, audit trails, and PSD3-aligned incident response systems embed directly into platform operations. European Banking Authority tightening of API security standards elevates demand here among providers serving both UK and EU markets simultaneously.
- Customizable Accounts:Flexible ledger structures support multi-currency balances and sub-account hierarchies.
- Transaction Monitoring:Real-time surveillance engines flag suspicious activity for regulatory filing.
Volume placements concentrate in White-Label Solutions; Compliance Management climbs fastest as regulatory timelines diverge across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors European Banking as a Service concentration, with Solarisbank AG and Railsr operating licensed infrastructure from Germany's capital. The city's regulatory proximity to BaFin and embedded finance startup density create a self-reinforcing cluster for API-driven banking expansion.
Germany
PSD2 compliance deadlines and banking license scarcity concentrate BaaS demand among neobanks seeking rapid market entry. The Federal Financial Supervisory Authority (BaFin) maintains strict operational resilience requirements that elevate platform security investments. Berlin's fintech corridor hosts the continent's densest concentration of white-label banking partnerships, with infrastructure providers serving cross-border clients from German regulatory bases.
United Kingdom
Open Banking standards and instant payment adoption drive API infrastructure procurement from fintech developers and digital lenders. The Financial Conduct Authority's operational resilience framework tightens incident reporting obligations for third-party banking providers. London's Square Mile and Shoreditch tech cluster sustain the highest BaaS partnership density outside Germany, with ClearBank and Railsr maintaining significant technical operations.
United States
FedNow instant settlement rollout and embedded finance integration by enterprise SaaS platforms reshape treasury infrastructure demand. The Federal Reserve's real-time payment system and SEC custody rule proposals create compliance complexity for cross-border service providers. New York and San Francisco financial technology corridors concentrate venture-backed neobank formation, driving API consumption from licensed banking backends.
France
PSD2 mandate enforcement and EU Green Deal carbon disclosure requirements align BaaS procurement with sustainability-linked financial products. The French Prudential Supervision and Resolution Authority (ACPR) implements EBA technical standards for API security and customer authentication. Paris fintech clusters in Station F and La Défense attract embedded finance startups seeking continental European licensing pathways.
Netherlands
Digital banking adoption and cross-border SME payment corridors concentrate demand for multi-currency account infrastructure. The Dutch Central Bank (DNB) enforces PSD2 strong customer authentication requirements that shape API development priorities. Amsterdam's financial district hosts regulatory technology firms that intermediate between licensed banks and embedded finance platforms seeking EU market access.
Banking As a Service (BAAS) Market Competitive Environment
Premium-margin players sit above commodity-margin players across licensing tier and compliance specialization depth. Full banking license holders command structural advantages in account creation and payment processing against API-only intermediaries. Three archetypes dominate: vertically integrated license holders, modular API specialists, and legacy core banking extenders. Competitive moves concentrate on strategic partnerships with neobank clients and geographic expansion through regulatory passporting.
Within the license-holder archetype, Solarisbank AG and ClearBank exemplify the premium positioning derived from German and UK regulatory bases. Railsr occupies a position among modular specialists focused on card-issuing and payment API delivery. Marqeta represents the developer-centric platform tier that anchors programmable payment infrastructure for venture-backed fintech clients. Green Dot Bank, PayPal Holdings, Inc., Block, Inc., Fiserv, and Mambu sit within broader financial services ecosystems that extend into BaaS modules.
| Leading Market Players |
|---|
| Green Dot Bank |
| Solarisbank AG |
| PayPal Holdings, Inc. |
| Marqeta |
| Mambu |
| Railsr |
| Block, Inc. |
| Fiserv |
| ClearBank |
| Others |
Value Chain & Pricing Dynamics
Venture-backed BaaS specialists rolled up through private-equity consolidation anchor supply-side discipline, linking their pricing power to banking license scarcity while passing through compliance cost escalations to embedded finance clients seeking rapid market entry.
Pricing Analysis
Outcome-based pricing tied to API uptime guarantees and transaction throughput volumes anchors BaaS commercial structures. Three-tier pricing stratifies across enterprise-grade multi-tenant deployments, mid-market hybrid configurations, and constrained on-premises installations. Price differentiation hinges on OAuth 2.0 security certification tiers and geographic regulatory passporting scope. Pricing pressure stems from neobank procurement teams demanding fixed monthly platform fees over per-transaction models. Fintech developers show highest price sensitivity; tier-one SaaS platforms exhibit lowest sensitivity due to embedded finance revenue recapture.
Supply Chain Analysis
EU Green Deal domestic-content mandates for carbon-efficient data center operations are reshaping cloud infrastructure sourcing across Germany, the United Kingdom, and the Netherlands. Core banking microservices draw from Kubernetes-orchestrated container platforms, cryptographic key management hardware, and real-time payment settlement networks. Supply chain risk centers on single-source vulnerability for qualified banking licenses concentrated in German and UK regulatory jurisdictions. Distribution runs through direct API marketplace integrations and strategic partnership channels with neobank and enterprise SaaS platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Banking as a Service sits at a technology-transition inflection where GraphQL and event-driven architectures displace legacy RESTful protocols, compressing infrastructure cost gaps between cloud-native entrants and mainframe-dependent incumbents.
For Market Incumbents: Extend API security investments to satisfy divergent PSD3 and UK FCA operational resilience timelines before compliance deadlines bifurcate technical stacks. Deepen backward integration into cloud-native core banking systems to eliminate legacy mainframe failure points that complicate service-level guarantees. The threat of modular API specialists capturing embedded finance volume demands preemptive certification in zero-trust security architectures. For New Entrants and Emerging Players: Begin with cross-border SME banking corridors linking Germany, the Netherlands, and France where correspondent banking relationships remain fragmented. Target white-label compliance management modules for providers serving simultaneous UK and EU markets facing regulatory timeline divergence. A developer-centric go-to-market anchored in programmable payment card infrastructure unlocks venture-backed fintech procurement channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular API specialists with German or UK banking license adjacency amid compliance cost escalation squeezing pure-technology intermediaries. Long-term viability over the projection horizon hinges on regulatory passporting depth and energy-efficient infrastructure positioning under EU Green Deal disclosure mandates. Watch FedNow instant settlement adoption rates as the inflection signal for real-time treasury infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | GraphQL protocol adoption enables sub-second latency for high-frequency payment operations. |
| Regulatory Passporting Expansion | BaFin and FCA license leverage unlocks pan-European service delivery without jurisdictional replication. |
| Strategic Partnership | Neobank volume-commitment contracts with fixed monthly fees displace transactional pricing models. |
| Acquisition of Specialist Firm | Zero-trust security engineering talent scarcity extends implementation timelines without targeted hiring. |
| Geographic Expansion | FedNow instant settlement infrastructure demand reshapes US treasury operations for cross-border providers. |
Study Parameters
Regulatory filings from the European Banking Authority, UK Financial Conduct Authority, and US Federal Reserve formed the secondary backbone, cross-referenced with SEC disclosures from publicly traded BaaS ecosystem participants. Primary interviews with API platform engineers, neobank procurement directors, embedded finance product managers, and banking license compliance officers validated technical and commercial assumptions. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Historical trendline analysis of API deployment velocity and embedded finance partnership formation informed the projection framework. Segmentation dimensions modeled include service type, deployment architecture, end-user category, and feature configuration. CAGRs derived from regression analysis of license-holder revenue trajectories and cloud-native infrastructure adoption curves. Forecast inputs incorporated PSD3 implementation timelines and FedNow settlement volume assumptions.
Underlying measurement precision varies by segment; payment processing and API integration carry tighter precision than emerging fraud detection modules. Forecasts reflect documented assumptions regarding regulatory timeline convergence and banking license availability. Competitive entry by hyperscaler cloud providers and divergent jurisdictional compliance requirements present specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Retail Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Mobile Banking Market
Banking
Global Chatbot for Banking Market
Banking
Machine Learning in Banking Market
Banking
Spain Data Analytics in Banking Market
Banking
Brazil Retail Banking Market
Banking
North America Challenger Banks Market
Banking
Global Retail Core Banking Systems Market
Banking
China Data Analytics in Banking Market
Banking
Global Neo and Challenger Bank Market
Banking
Latin America Banking As a Service Market
Banking
Letter of Credit Confirmation Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Germany Banking As a Service Market