
 Latin America Banking As a Service Market | 2026-2036
Latin America Banking As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Banking As a Service Market Foresight
API-based account management is repositioning how financial infrastructure reaches end users across Latin America. Nubank leverages its cloud-native stack to sustain rapid user acquisition in Brazil and Mexico. PagSeguro anchors merchant payment flows by embedding banking services directly into e-commerce checkout experiences. BBVA competes through its digital platform strategy, extending API access to third-party fintech developers across the region.
Banking as a Service denotes the provision of licensed banking infrastructure—account creation, payment rails, compliance screening, and ledger management—through modular APIs that non-bank entities integrate into their own applications. The architecture typically employs RESTful or GraphQL protocols with OAuth authentication, enabling real-time balance queries and transaction initiation without the client holding a banking charter. API-based delivery models lead structural deployment, as fintech companies and traditional banks both seek to avoid core system replacement costs while accelerating product launches. White label solutions capture concentrated margin pools where institutions rebrand full banking stacks under proprietary interfaces, particularly among credit unions and regional insurers building digital channels without in-house development.
Brazil's Banco Central governs open banking implementation through its phased Pix and Open Finance frameworks, while Mexico's CNBV enforces fintech institution licensing under the Ley Fintech. Data protection laws across Colombia and Chile impose cross-border data localization requirements that shape vendor selection and platform architecture. Stakeholders must monitor how evolving anti-money laundering policies interact with real-time payment volumes to determine compliance automation investments.
Market Dynamics
Pix instant payment rails in Brazil are compressing settlement timelines and forcing incumbent banks to expose core infrastructure through APIs, reshaping competitive economics across the region.
Growth Catalysts
- Brazil's Open Finance Framework:Mandatory data-sharing protocols unlock credit scoring innovation for fintech lenders and expand addressable borrower pools beyond traditional bureau coverage.
- Neobank User Acquisition:Digital-first challengers embed banking services into ride-hailing and food delivery apps, converting transactional relationships into deposit-taking accounts.
- Cloud-Native Core Systems:API-first ledger architectures reduce time-to-market for new financial products from months to weeks, lowering capital barriers for regional insurers and retailers entering banking.
Market Restraints
- Data Localization Mandates:Colombian and Chilean cross-border data restrictions force vendors to maintain separate regional infrastructure, raising fixed cost bases for platform providers.
- Core Banking Vendor Concentration:Three legacy technology suppliers dominate mainframe modernization contracts, limiting price competition for mid-tier credit unions.
- Compliance Automation Gaps:Real-time transaction monitoring systems struggle to scale with Pix volume growth, exposing BaaS providers to regulatory enforcement risk.
Strategic Opportunities
- Colombia's Underbanked Corridors:Remittance-heavy regions present white space for cross-border wallet integration with US and Venezuelan payment corridors.
- Embedded Lending Convergence:Point-of-sale credit APIs combined with merchant cash flow data enable revenue-based financing products for e-commerce sellers.
- CNBV Fintech Sandbox Expansion:Mexico's regulatory test environment accelerates licensing timelines for foreign BaaS entrants seeking local charter partnerships.
Industry Challenges
- API Talent Scarcity:Shortage of engineers experienced in OAuth 2.0 and financial-grade API security delays product launches for regional development teams.
- Legacy Core Integration Friction:SOAP-to-REST protocol translation creates latency and reconciliation errors when connecting modern BaaS layers to 1990s-era banking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Banking As a Service Market |
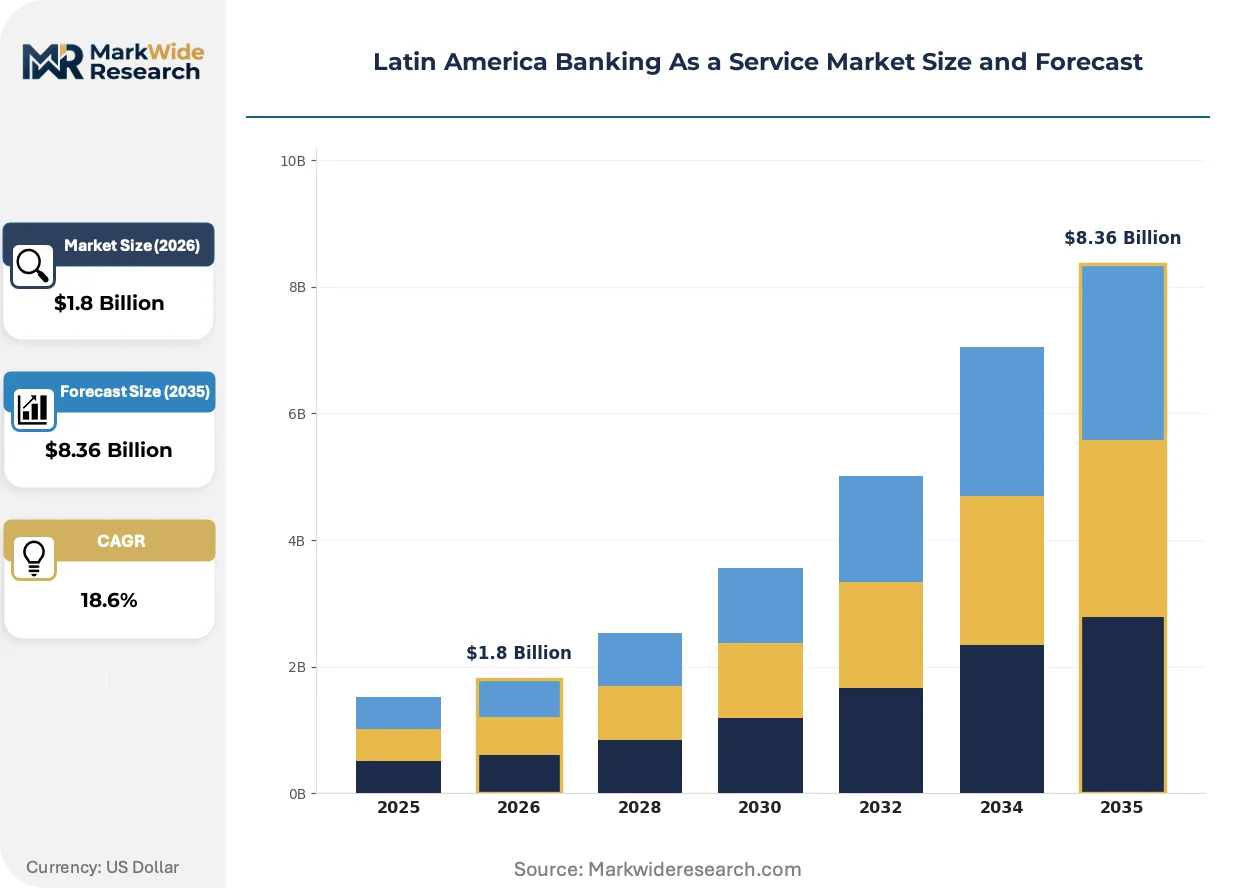
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Account Management, Compliance Solutions, Analytics Services Client Type: Fintech Companies, Traditional Banks, Credit Unions, Insurance Providers Delivery Model: API-Based, White Label Solutions, Direct Access Platforms, Cloud-Based Services Regulatory Framework: Fintech Regulations, Data Protection Laws, Anti-Money Laundering Policies, Consumer Protection Standards |
| Companies Covered | Nubank, Banco do Brasil, PagSeguro, BBVA, Albo, Uala, Klar, Banco Original SA, Mercado Pago, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Banking As a Service Market Shifts & Advancements
Real-time payment infrastructure and modular financial APIs are compressing product development cycles and enabling non-bank entities to offer regulated financial services without charter acquisition.
GraphQL query protocols are unifying account aggregation across multiple banking relationships into single API calls. Neobanks and wealthtech platforms in São Paulo and Mexico City are adopting this standard to reduce payload overhead. The technology is unifying previously fragmented balance and transaction data streams, enabling unified financial dashboards that displace manual spreadsheet reconciliation.
Brazil's Banco Central has phased mandatory open banking participation through its Fase 3 and Fase 4 implementation timelines. Financial institutions must now expose credit and insurance product data through standardized endpoints. Mid-tier banks with limited in-house development capacity are outsourcing API gateway management to specialized technology vendors.
Merchant acquirers are unbundling payment processing from deposit account origination, allowing e-commerce platforms to white-label full banking stacks. Latin American marketplace sellers now expect embedded working capital and FX hedging within their sales dashboards. This behavior shift is most visible in Brazilian cross-border e-commerce corridors serving Chinese supplier networks.
Latin America Banking As a Service Market Segmentation
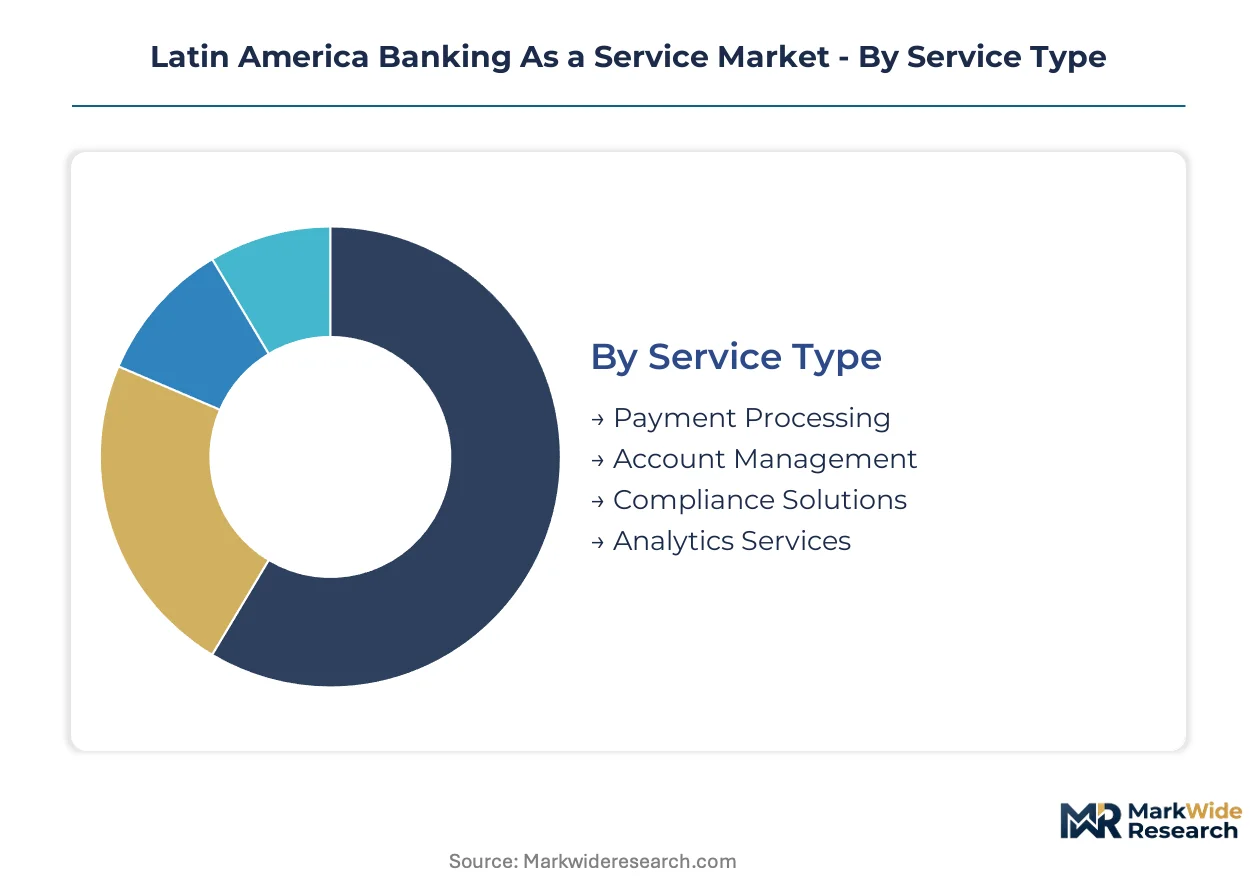
Banking as a Service architectures fragment across four distinct dimensions that determine vendor selection criteria and margin capture. Service type dictates compliance burden and infrastructure requirements. Client type shapes pricing power and contract duration. Delivery model governs speed-to-market versus customization depth. Regulatory framework alignment determines geographic addressability.
Service Type:
Capital intensity concentrates in compliance and payment infrastructure, where real-time settlement rails demand redundant systems and continuous regulatory auditing.
- Payment Processing:Real-time settlement protocols including Pix instant rails require 24/7 operational uptime and sub-second latency guarantees. Brazilian e-commerce platforms and Mexican marketplace sellers embed these APIs directly into checkout flows, compressing settlement timelines from T+2 to immediate.
- Account Management:Cloud-native ledger architectures provision virtual accounts with KYC orchestration and balance reconciliation. Neobanks in São Paulo and Mexico City leverage these APIs to onboard users without physical branch infrastructure.
- Compliance Solutions:Automated screening engines for AML and sanctions monitoring.
- Analytics Services:Transaction data aggregation for credit scoring and behavioral profiling.
Most installed capacity flows through Payment Processing. Expansion is steepest in Account Management.
Client Type:
Customer sophistication determines contract structure, with fintechs demanding usage-based pricing and incumbents preferring fixed-fee enterprise arrangements.
- Fintech Companies:Digital-native challengers embed banking services into ride-hailing, food delivery, and e-commerce applications. These clients prioritize API documentation quality and sandbox environments over white-glove implementation support.
- Traditional Banks:Incumbents expose legacy core systems through middleware layers to retain deposit relationships against neobank competition. BBVA and Itaú Unibanco deploy these partnerships to accelerate digital product launches without core replacement.
- Credit Unions:Member-owned cooperatives seeking digital channels without in-house development capacity.
- Insurance Providers:Carriers embedding premium collection and claims disbursement into policy management platforms.
Fintech Companies command the largest addressable spend pool. Traditional Banks are expanding their BaaS vendor rosters fastest.
Delivery Model:
Deployment architecture determines time-to-revenue and customization depth tradeoffs across the technology stack.
- API-Based:RESTful and GraphQL endpoints enable modular integration with existing application layers. São Paulo wealthtech platforms adopt GraphQL to unify multi-bank account aggregation into single query calls, reducing payload overhead and dashboard refresh latency.
- White Label Solutions:Fully rebrandable banking stacks including mobile interfaces, card programs, and customer support infrastructure. Regional insurers in Colombia and Chile deploy these to launch digital deposit products without charter acquisition.
- Direct Access Platforms:Proprietary interfaces with limited third-party integration flexibility.
- Cloud-Based Services:Multi-tenant infrastructure with shared security and compliance layers.
API-Based deployments carry the heaviest current installed base. White Label Solutions are climbing the fastest as non-bank entrants seek full-stack offerings.
Regulatory Framework:
Compliance alignment requirements vary sharply across jurisdictions, forcing vendors to maintain segmented product configurations.
- Fintech Regulations:Licensing frameworks including Brazil's Open Finance phases and Mexico's CNBV fintech charter requirements. Foreign BaaS providers partner with local institutions to satisfy these mandates without direct charter ownership.
- Data Protection Laws:Cross-border data localization requirements in Colombia and Chile impose infrastructure duplication costs. Vendors must maintain separate regional instances, raising fixed cost bases and complicating disaster recovery architectures.
- Anti-Money Laundering Policies:Real-time transaction monitoring and suspicious activity reporting automation.
- Consumer Protection Standards:Disclosure requirements and dispute resolution protocols for deposit and credit products.
Fintech Regulations absorb the greatest vendor attention. Data Protection Laws are expanding most quickly as additional jurisdictions draft localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Open Finance mandates and Mexico's fintech licensing regime have created divergent compliance costs that steer BaaS platform investment toward jurisdictions with clearer regulatory pathways and lower operational friction.
Brazil
Pix instant payment rails and Open Finance phases 3 and 4 drive API infrastructure demand. Banco Central mandates standardized data-sharing endpoints that force mid-tier banks to outsource gateway management. São Paulo anchors cloud-native development clusters where neobanks embed banking services into ride-hailing applications.
Mexico
CNBV fintech charter requirements and the Ley Fintech framework accelerate licensing timelines for foreign entrants. Mexico City concentrates API development talent for OAuth 2.0 implementations. The regulatory sandbox expansion enables faster charter partnerships for BaaS providers seeking local market access.
Colombia
Cross-border remittance corridors with Venezuelan and US payment networks create wallet integration opportunities. Data localization mandates force vendors to maintain separate regional infrastructure. Bogotá hosts development centers for white-label banking stacks targeting credit unions.
Chile
Strict data protection laws impose infrastructure duplication costs that raise fixed cost bases for platform providers. Santiago's fintech cluster focuses on compliance automation for AML screening. Regional insurers leverage BaaS APIs to embed premium collection into policy management platforms.
Argentina
Currency volatility and capital controls drive demand for dollar-denominated virtual accounts through BaaS APIs. Buenos Aires concentrates wealthtech platforms adopting GraphQL protocols for multi-bank aggregation. Regulatory uncertainty pushes providers toward partnership models with established regional banks.
Latin America Banking As a Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with API-first fintechs capturing usage-based contracts while incumbent banks defend deposit relationships through middleware partnerships. The vendor base concentrates around three strategic tiers: cloud-native challengers, legacy bank technology divisions, and specialized compliance infrastructure providers. Dominant competitive moves include strategic partnerships with ride-hailing and e-commerce platforms and geographic expansion through regulatory sandbox entry.
Within the cloud-native challenger tier, Nubank and PagSeguro exemplify API-first architectures that compress product launch timelines. BBVA represents the incumbent-bank pivot toward open platform strategies. These three entities anchor distinct competitive positions without overlapping core value propositions.
| Leading Market Players |
|---|
| Nubank |
| Banco do Brasil |
| PagSeguro |
| BBVA |
| Albo |
| Uala |
| Klar |
| Banco Original SA |
| Mercado Pago |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spot pricing indices cascade through BaaS provider cost structures, compressing margin buffers for mid-tier platforms while amplifying pricing power for vertically integrated stacks with captive data center capacity across São Paulo and Mexico City.
Pricing Analysis
API call volume discounts anchor the dominant pricing model, with fintech clients securing tiered rates based on monthly transaction thresholds. Price differentiation rests on compliance automation depth and OAuth implementation certification levels. Pricing pressure intensifies as Pix instant rails commoditize payment processing, eroding per-transaction margins. Neobank challengers exhibit highest price sensitivity, while regional insurers prioritizing white-label speed-to-market absorb premium positioning.
Supply Chain Analysis
Brazilian data localization mandates reshape sourcing patterns, compelling foreign BaaS vendors to establish domestic cloud infrastructure partnerships rather than rely on cross-border server capacity. Core banking software development concentrates in Brazil, Mexico, and the United States. Critical inputs include cloud compute instances, financial-grade API security modules, and real-time fraud detection algorithms. Single-source vulnerability sits with legacy core banking vendor concentration for middleware integration. Distribution runs through direct enterprise sales teams and specialized fintech implementation consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's phased Open Finance mandates compound infrastructure demand, with Fase 4 requirements forcing mid-tier institutions into vendor relationships that reshape competitive economics across the region.
For Market Incumbents: Cement API gateway control by acquiring specialized OAuth implementation firms before neobank competitors capture fintech developer mindshare. Expand middleware capacity in Mexico City to serve CNBV-licensed charter partnerships. Prioritize compliance automation investments that scale with Pix transaction volume growth.
For New Entrants and Emerging Players: E-commerce marketplace integrators represent the most penetrable channel partner type for embedded lending APIs. Target Colombian credit unions seeking white-label deposit products without charter acquisition. Pursue regulatory sandbox entry through Bogotá development centers to accelerate licensing timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native challengers lack sufficient transaction scale to amortize compliance infrastructure costs. Five-to-ten-year viability favors platforms with multi-country regulatory coverage spanning Brazil, Mexico, and Colombia. Acquisition target archetype: regional compliance infrastructure providers with CNBV and Banco Central audit relationships. Monitor Pix volume growth rates as the critical inflection signal for platform scalability stress.
| Strategic Initiative | Industry Significance |
|---|---|
| API Gateway Acquisition | Captures developer ecosystem loyalty ahead of Open Finance Fase 4 mandates. |
| Regulatory Sandbox Entry | Accelerates CNBV licensing timelines for foreign BaaS charter partnerships. |
| White-Label Stack Launch | Enables Colombian insurers to offer deposit products without core system replacement. |
| Compliance Automation Scale-Up | Matches real-time AML screening capacity to Pix transaction volume expansion. |
| Cross-Border Infrastructure Expansion | Satisfies Chilean data localization requirements while serving Argentine dollar-account demand. |
Research Methodology
Bottom-up fintech embedding modeling reconciled against top-down cloud infrastructure tracking forms the analytical core of this study. Primary interviews with BaaS platform CTOs, neobank product directors, CNBV regulatory affairs leads, and Brazilian credit union digital officers combined with secondary validation from Banco Central open banking disclosures, CNBV fintech registry filings, and hyperscaler regional capex reports. Triangulation across these sources anchored segmentation splits and growth trajectory assumptions.
Input-output matrices mapped API call volume trajectories against regulatory milestone timelines across the projection horizon. Segmentation dimensions modeled include service type, client archetype, delivery architecture, and regulatory framework alignment. CAGRs derived from compound growth pathway analysis incorporating Pix adoption curves and open banking phase implementation schedules. Industry-specific forecast inputs encompass fintech charter licensing velocity and cloud-native core system migration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AML policy evolution and cross-border data localization expansion. The analysis reflects assumptions regarding regulatory implementation timelines and infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Payment Bank Solutions Market
Banking
Retail Banking Market
Banking
API Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Bank Guarantee Market
Banking
Canada Data Analytics in Banking Market
Banking
Middle East Data Analytics in Banking Market
Banking
Cloud Computing Banking Market
Banking
Banking Wearable Devices Market
Banking
Singapore Neobanking Market
Banking
North America Data Analytics in Banking Market
Banking
Merchant Banking Services Market
Banking
Virtual Teller Machine (VTM) Market
Banking
North America Challenger Banks Market
Banking
Biometric Banking Wristband Market
Banking
Banking Credit Analytics Market