
 Global Neo and Challenger Bank Market | 2026-2036
Global Neo and Challenger Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neo and Challenger Bank Market Outlook
PCI DSS Level 1 certification is bifurcating the competitive landscape into qualified infrastructure operators and peripheral service vendors. Nubank leverages its Brazil-first architecture to sustain unit economics across Latin American markets. Revolut dominates multi-currency corridors and extends its banking license footprint across European Economic Area jurisdictions. Starling Bank anchors UK SME lending with proprietary payment rails and controls primary deposit flows through vertical integration.
Neo and challenger banks are technology-native financial institutions operating without physical branch networks, delivering retail and commercial banking services through mobile-first interfaces with real-time transaction processing and cloud-native core banking systems. Their primary purpose is to disaggregate traditional banking value chains by unbundling payments, lending, and wealth management into modular, API-accessible services. The digital-only banking model leads operational efficiency metrics while hybrid architectures capture margin pools from customers requiring occasional human touchpoints. AI-driven analytics represents the fastest-growing technology segment as institutions deploy machine learning for credit underwriting and fraud detection. Payment solutions remain the most mature service category with compressed margins, whereas investment services concentrate emerging profit opportunities.
The European Banking Authority enforces open banking standards through PSD2 and PSD3 mandates, compelling incumbents to share customer data with licensed challengers and reshaping competitive dynamics around API reliability. The US Office of the Comptroller of the Currency and the Federal Deposit Insurance Corporation maintain divergent charter pathways that fragment market access requirements across American jurisdictions. Brazil's Banco Central pioneered instant payment infrastructure through Pix, creating regulatory templates now replicated by central banks in Mexico and Colombia. Stakeholders must monitor how divergent national approaches to digital banking licensing and deposit insurance will determine which operating models achieve cross-border scalability.
Market Dynamics
Open banking API mandates are dismantling incumbent data monopolies and forcing traditional banks to expose customer data to licensed challengers, fundamentally restructuring competitive positioning around data portability and third-party integration capabilities.
Growth Catalysts
- PSD2 and PSD3 mandates:The European Banking Authority's open banking standards compel legacy institutions to share customer data through standardized APIs, lowering barriers for challenger market entry and enabling real-time payment initiation services.
- Instant payment infrastructure:Brazil's Pix system validates real-time settlement models across Latin America, with central banks in Mexico and Colombia replicating this regulatory template to accelerate financial inclusion.
- Cloud-native core banking:Microservices architecture and containerized deployment reduce capital requirements for new entrants, allowing challengers to scale processing capacity without legacy mainframe dependencies.
Market Restraints
- Deposit insurance fragmentation:Divergent national approaches to digital banking licensing and deposit guarantee schemes create cross-border scalability barriers, particularly between US state and federal charter pathways.
- Core banking vendor concentration:Reliance on a limited set of cloud infrastructure providers for critical payment processing creates systemic operational risk and vendor lock-in for scaling challengers.
- Unit economics compression:Payment solutions as a service category face margin erosion from interchange fee regulations and competitive pricing pressure on transaction processing.
Strategic Opportunities
- SME embedded finance:Underpenetrated small business banking among freelancers and micro-enterprises creates white space for vertical-specific lending and cash flow management tools.
- Wealth management modularization:Investment services represent emerging profit pools as challengers unbundle brokerage, robo-advisory, and cryptocurrency custody into API-accessible components.
- AI-driven credit underwriting:Machine learning convergence with alternative data sources enables real-time risk assessment for thin-file borrowers previously excluded from traditional scoring models.
Industry Challenges
- PCI DSS Level 1 certification timelines:The rigorous audit process for top-tier payment security standards delays product launches and consumes engineering resources that could accelerate feature development.
- Legacy system integration friction:Challengers seeking banking partnerships or charter acquisitions face technical debt from decades-old core banking platforms that resist API-based interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neo and Challenger Bank Market |
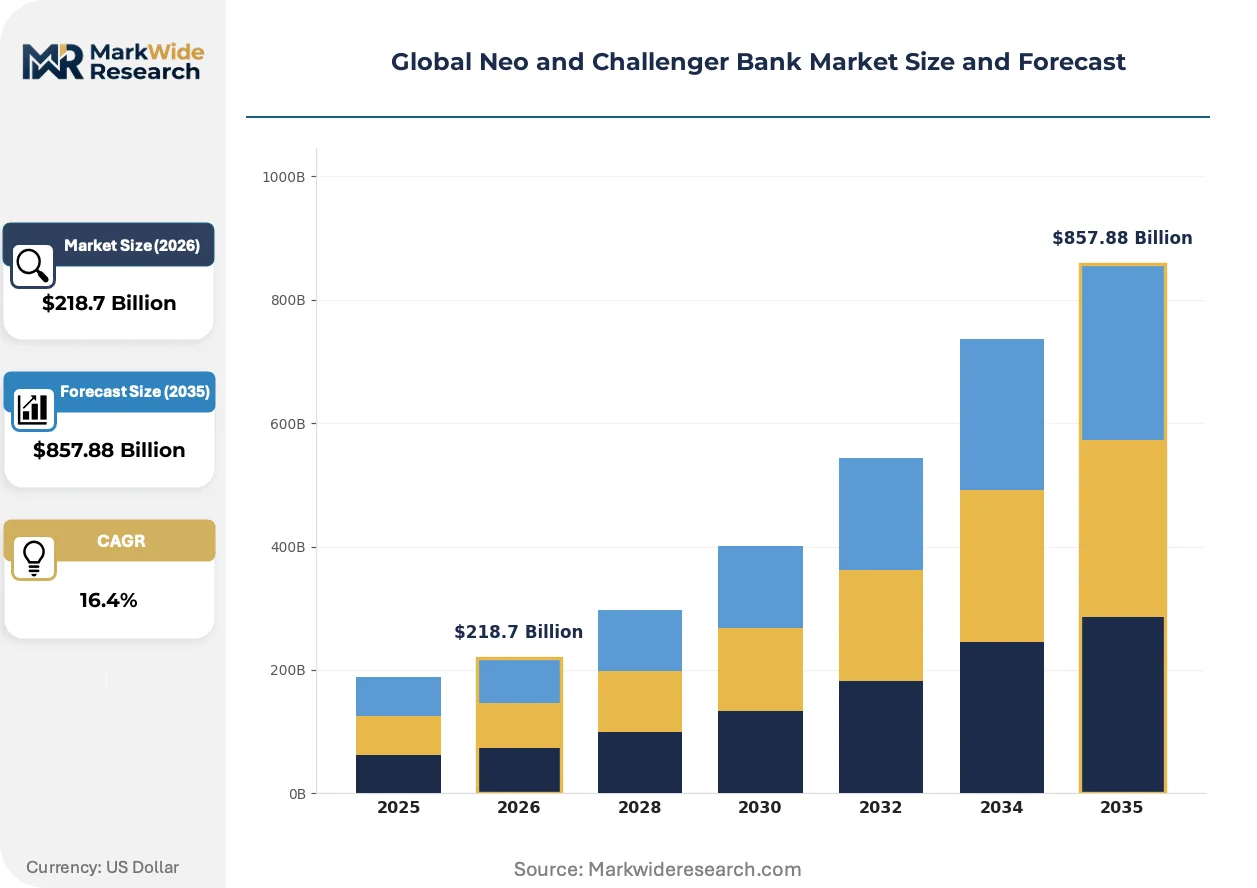
| Market Size in 2026 | $218.7 Billion |
| Market Size in 2035 | $857.88 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Banking Model: Digital-Only, Hybrid, Community, International Target Customer: Millennials, Gen Z, Freelancers, Small Businesses Service Type: Payment Solutions, Savings Accounts, Investment Services, Loans Technology: Mobile Banking, AI-Driven Analytics, Blockchain, API Integration |
| Companies Covered | Revolut, Nubank, Chime, N26, Monzo Bank, Starling Bank, Atom Bank, WeBank, Kakao Bank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neo and Challenger Bank Market Strategic Shifts
Embedded finance architectures are reshaping how banking services penetrate non-financial customer journeys, dissolving traditional boundaries between commerce and financial services through invisible, context-integrated product delivery.
Banking-as-a-Service platforms are miniaturizing full-stack financial infrastructure into composable API modules. E-commerce marketplaces and payroll software providers embed lending, payments, and accounts directly into their workflows. This compression of the value chain eliminates standalone banking app dependencies for routine transactions.
The EU AI Act imposes algorithmic transparency requirements on automated credit decisions. Financial institutions must document machine learning model logic and enable human review pathways for adverse determinations. Challenger banks with natively digital audit trails adapt faster than legacy competitors burdened by manual compliance processes.
Freelancer and gig-worker segments are abandoning traditional account-based relationships in favor of income-smoothing tools and instant earnings access. Digital staffing platforms now bundle financial services as retention mechanisms, displacing conventional payroll deposit relationships. Brazil and India demonstrate the strongest migration velocity toward platform-embedded banking.
Global Neo and Challenger Bank Market Segmentation
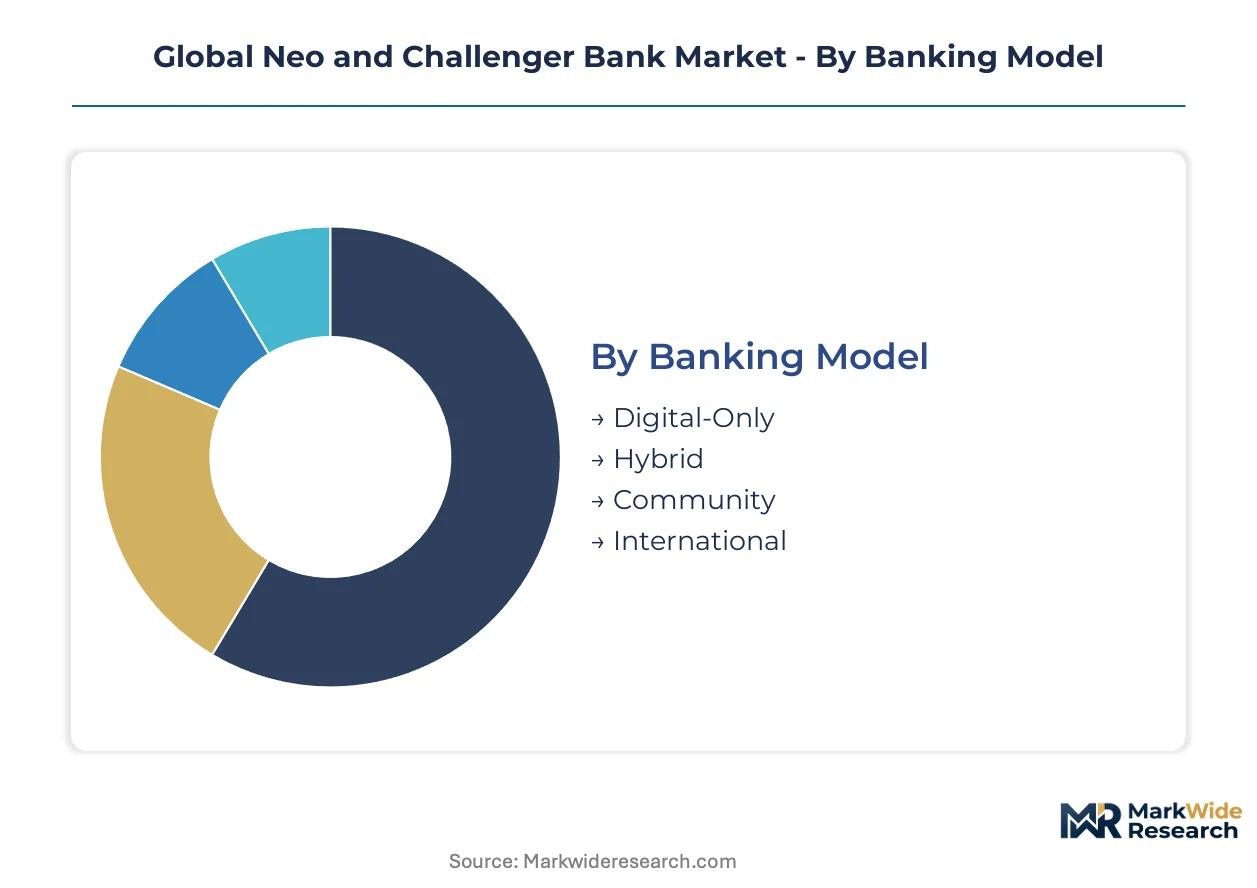
Neo and challenger bank segmentation reveals how operating model choices determine addressable market scope and regulatory burden. Each dimension carries distinct substitution pressures from fintech specialists, incumbent digital arms, and embedded finance providers.
Banking Model:
Digital-only challengers face the most acute substitution threat from Big Tech payment wallets and buy-now-pay-later platforms that bypass banking licenses entirely.
- Digital-Only:Branchless institutions deploy cloud-native core systems with sub-50 millisecond transaction latency. Demand concentrates among urban Millennials in Brazil and India where smartphone penetration exceeds traditional banking access. Pix integration in Brazil and UPI rails in India accelerate customer acquisition velocity.
- Hybrid:Models blend digital interfaces with limited physical presence through partnerships or owned lounges. Small business owners in Germany and the UK require occasional human consultation for complex lending decisions. Regulatory arbitrage between digital and branch-based capital requirements shapes profitability.
- Community:Regionally focused challengers target underbanked postal codes with culturally tailored products. Ethnic banking corridors in Canada and Australia demonstrate deposit stickiness through relationship-driven onboarding.
- International:Cross-border licensed entities exploit passporting regimes to serve diaspora and expatriate segments. Multi-currency corridors between UK, Singapore, and UAE generate interchange revenue from frequent travelers.
Digital-only models anchor the volume base while hybrid architectures gain share at the steepest rate as customer acquisition costs rise.
Target Customer:
Cost tier differentiation separates mass-market acquisition plays from premium relationship banking with divergent unit economics.
- Millennials:First-generation digital natives demand instant account opening and real-time spending analytics. Salary-linked customers in Mexico and Indonesia exhibit highest lifetime value through cross-sell penetration.
- Gen Z:Students and early-career professionals prioritize cryptocurrency access and carbon footprint tracking. Educational institutions in South Korea and Australia partner with challengers for campus banking programs.
- Freelancers:Irregular income patterns require tax withholding tools and invoice financing. Platform workers in Brazil and Nigeria drive demand for instant payout functionality.
- Small Businesses:Micro-enterprises seek integrated accounting, payroll, and expense management. Sole proprietors in Italy and Spain face acute working capital gaps that traditional banks underserve.
Millennial segments deliver the highest current revenue contribution while freelancer banking climbs fastest as gig economy participation expands.
Service Type:
Application maturity creates margin dispersion between commoditized payments and emerging wealth management profit pools.
- Payment Solutions:Real-time peer-to-peer transfers and multi-currency cards face interchange fee compression. QR-code penetration in Thailand and Vietnam displaces card-based revenue models.
- Savings Accounts:High-yield deposits compete directly with money market funds for customer liquidity. Rate-sensitive savers in Poland and Turkey migrate between challengers based on promotional offers.
- Investment Services:Fractional share trading and robo-advisory generate fee income with minimal balance sheet risk. Retail investors in Sweden and the Netherlands demonstrate strongest adoption of automated portfolio construction.
- Loans:Alternative credit scoring enables thin-file lending previously excluded from traditional underwriting. Micro-lending in Kenya and the Philippines leverages mobile money repayment history.
Payment solutions dominate transaction volume while investment services deliver the steepest margin expansion trajectory.
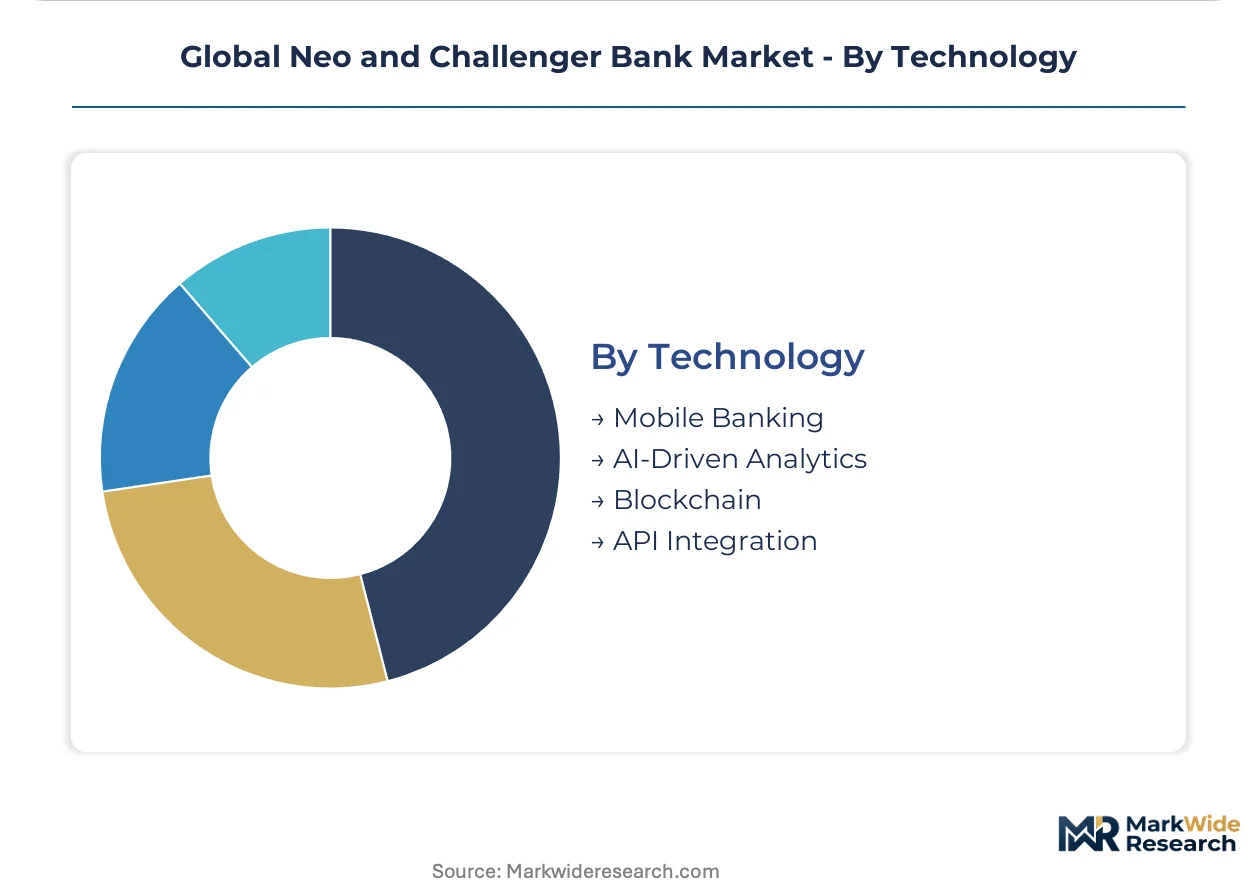
Technology:
Supply concentration in cloud infrastructure creates vendor lock-in risks that differentiate proprietary stack operators from platform-dependent challengers.
- Mobile Banking:Native iOS and Android applications with biometric authentication represent baseline market entry requirements. Super-app integration in Indonesia and Malaysia reduces standalone app dependency.
- AI-Driven Analytics:Machine learning models power real-time fraud detection and personalized product recommendations. The EU AI Act mandates algorithmic transparency for automated credit decisions.
- Blockchain:Distributed ledger technology enables cross-border settlement and digital asset custody. Regulatory clarity gaps in the US and UK delay institutional deployment.
- API Integration:Open banking connectivity allows third-party financial data aggregation and payment initiation. PSD2 compliance in the European Economic Area creates standardized interoperability.
Mobile banking underpins customer acquisition while AI-driven analytics expands most quickly as regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pix instant payment infrastructure in Brazil has triggered regulatory replication across Latin America, while PSD2 and PSD3 mandates in Europe force data-sharing frameworks that lower challenger entry barriers. Divergent charter pathways in the United States fragment market access, and Asia-Pacific markets accelerate through super-app integration models.
Brazil
Central Bank of Brazil's Pix system processes billions of real-time transactions monthly, validating instant settlement infrastructure that Mexico and Colombia now replicate. Banco Central pioneered open finance regulations through Fase 4 mandates requiring transactional data sharing. São Paulo anchors fintech density with Nubank's headquarters driving talent concentration and venture deployment across Latin America.
United Kingdom
Open Banking Implementation Entity enforces API standards that compel nine major banks to share current account data with licensed challengers. Financial Conduct Authority and Prudential Regulation Authority maintain divergent capital requirements between e-money institutions and full banks. London's Square Mile and Tech City cluster host Starling Bank and Monzo Bank engineering centers alongside regulatory technology consultancies.
Germany
BaFin licensing requirements for payment institutions and credit institutions create tiered regulatory pathways with divergent passporting rights across the European Economic Area. Federal Financial Supervisory Authority enforces anti-money laundering protocols that delay new entrant authorization timelines. Berlin and Munich concentrate challenger development with N26 maintaining headquarters operations and technical infrastructure.
United States
Office of the Comptroller of the Currency and state banking regulators maintain competing charter pathways that fragment deposit insurance access and interstate operational permissions. Federal Deposit Insurance Corporation coverage thresholds determine customer acquisition economics for digital-only institutions. San Francisco and New York metro areas concentrate venture-backed challenger engineering teams alongside established payment processor partnerships.
India
Reserve Bank of India licenses small finance banks and payments banks with restricted balance sheet activities that shape operating model economics. Unified Payments Interface rails process real-time peer-to-peer and merchant transactions with zero interchange, compressing payment revenue models. Mumbai and Bangalore cluster digital banking development with WeBank technology partnerships and local fintech accelerators driving regional innovation.
Global Neo and Challenger Bank Market Competitive Environment
Player mix skews toward technology-native challengers with banking licenses and digital-only fintechs operating under e-money regimes. Market structure concentrates around three strategic archetypes: full-stack licensed banks with proprietary core systems, platform-embedded financial service providers, and Banking-as-a-Service infrastructure operators. Competitive dynamics center on geographic license passporting and API reliability metrics rather than branch network scale. M&A activity targets specialized lending algorithms and regional charter acquisitions.
Among European-licensed challengers, Revolut and N26 occupy positions exemplifying multi-jurisdictional passporting strategies. Revolut represents the archetype of cross-border financial super-apps with multi-currency infrastructure. N26 sits within the premium digital banking tier with European Economic Area license coverage. Nubank anchors Latin American challenger development with Brazil-first architecture now extending across Colombian and Mexican markets.
| Leading Market Players |
|---|
| Revolut |
| Nubank |
| Chime |
| N26 |
| Monzo Bank |
| Starling Bank |
| Atom Bank |
| WeBank |
| Kakao Bank |
| Others |
Value Chain & Pricing Dynamics
Cloud-native core banking platforms substituting for legacy mainframe infrastructure simultaneously redistribute vendor geography toward AWS-GCP-Azure concentration zones and compress capital expenditure requirements for new entrants. This substitution dynamic weakens pricing power among incumbent core banking software vendors while amplifying margin pressure on challengers locked into proprietary data center architectures.
Pricing Analysis
Certification level (PCI DSS Level 1 versus lower tiers) creates the primary spread between qualified infrastructure operators and peripheral service vendors. The dominant pricing structure stratifies across SaaS-tiered subscription models with transaction volume overlays. Price differentiation rests on API reliability guarantees and deposit insurance coverage breadth, with full-license challengers commanding premiums over e-money institutions. Pricing pressure stems from interchange fee regulations in Brazil and the European Union compressing payment margins. Freelancer and micro-enterprise segments exhibit highest price sensitivity, while SME banking clients prioritize feature depth over cost minimization.
Supply Chain Analysis
Amazon Web Services us-east and eu-west availability zones underwrite critical processing capacity for scaling challengers. Geographic supply concentration clusters in the United States, Ireland, and Singapore for hyperscale cloud infrastructure. Raw material dependencies center on semiconductor chips for payment card manufacturing, optical fiber for data transmission, and lithium for backup power systems. Supply chain risk manifests as single-source vulnerability where three providers control ninety percent of global cloud capacity. Distribution runs through API-first developer portals and direct enterprise sales teams targeting CFOs and treasury departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Neo and Challenger Bank Market sits in early-cycle expansion validated by accelerating freelancer banking adoption across Brazil, India, and Nigeria. Platform-embedded financial services penetration remains below fifteen percent in most jurisdictions, leaving substantial runway for licensed challengers.
For Market Incumbents: Shield core deposit relationships by accelerating API interoperability investments before open finance mandates harden competitive disadvantage. Incumbents must backward integrate into instant payment infrastructure and acquire specialized lending algorithms to counter fintech specialists. Regulatory technology spending represents the critical defensive lever as PSD3 and Fase 4 compliance timelines compress.
For New Entrants and Emerging Players: Lead with vertical-specific cash flow tools targeting sole proprietors in Italy and Spain where traditional banks underserve working capital gaps. The most penetrable white space concentrates in SME embedded finance and invoice financing for platform workers. A partnership-first go-to-market angle with digital staffing platforms accelerates customer acquisition without standalone app marketing burdens.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed challengers holding e-money licenses seeking full banking charter upgrades. Long-term viability over a five-to-ten year window favors institutions with proprietary core systems and multi-jurisdictional passporting coverage. The signal to watch is central bank instant payment infrastructure deployment velocity as an indicator of addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Banking License Acquisition | Full charter coverage unlocks deposit insurance and lending authority across EEA jurisdictions. |
| API Reliability Investment | Sub-50 millisecond latency guarantees differentiate infrastructure operators in PSD2-mandated markets. |
| Vertical Lending Algorithm Development | Machine learning models for thin-file borrowers capture margin pools excluded from traditional scoring. |
| Cloud Infrastructure Diversification | Multi-provider deployment reduces systemic vendor lock-in risks from AWS-GCP-Azure concentration. |
| Regulatory Technology Automation | Native digital audit trails accelerate EU AI Act compliance for automated credit decisions. |
Study Parameters
Operator-level perspectives from chief technology officers at challenger banks, central bank fintech sandbox administrators, core banking platform engineers, and SME treasury managers anchored the qualitative base. Primary interviews combined with secondary validation from Banco Central do Brasil open finance disclosures, European Banking Authority PSD2 implementation reports, UK Financial Conduct Authority authorization statistics, and Reserve Bank of India payments bank licensing records. Bottom-up transaction volume modeling and top-down macroeconomic triangulation ensured cross-verification of market sizing.
Sensitivity analysis tested forecast robustness across interchange fee regulation scenarios and cloud infrastructure cost trajectories throughout the projection horizon. The analytical framework modeled segmentation dimensions including banking model archetype, target customer cohort, service type maturity, and technology deployment pattern. CAGRs derived from historical license growth rates, deposit accumulation curves, and cross-sell penetration benchmarks. Industry-specific inputs incorporated Pix transaction velocity trends and UPI rail expansion metrics.
The analysis sits within stated boundaries; outcomes outside sustained open banking mandate enforcement and stable central bank instant payment infrastructure investment would require recalibration. Forecasts reflect documented assumptions about regulatory timeline adherence and challenger bank customer acquisition cost trajectories. Practitioners should keep alternative scenarios live as divergent national charter pathways and deposit insurance fragmentation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Neobanking Market
Banking
Europe Neobanking Market
Banking
Latin America Data Analytics in Banking Market
Banking
Biometric Banking Wristband Market
Banking
South America Challenger Banks Market
Banking
Canada Data Analytics in Banking Market
Banking
Spain Data Analytics in Banking Market
Banking
Machine Learning in Banking Market
Banking
Singapore Data Analytics in Banking Market
Banking
Digital LED Retail Banking Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Global Certificate of Deposit Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Bank Kiosk Market
Banking
Data Analytics in Banking Market
Banking
Virtual Teller Machine (VTM) Market