

Bank Regulatory & Governance Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Bank Regulatory & Governance Consulting Market Insights
London's Big Four advisory cohort is broadening its governance consulting bench ahead of anticipated regulatory tightening. Deloitte leverages its global risk methodology network to anchor complex cross-border compliance programs for systemic banks. PwC competes through specialized regulatory technology integration teams that embed directly into client second-line defense functions. KPMG sustains market presence via deep sectoral expertise in prudential capital modeling and stress-testing protocols.
Bank regulatory and governance consulting encompasses advisory services that translate prudential rules into operational frameworks, encompassing risk-weighted asset calculations, board accountability structures, and compliance control architectures designed to satisfy supervisory examinations. The primary commercial purpose centers on reducing regulatory penalty exposure while optimizing capital allocation under evolving supervisory expectations. Compliance auditing and regulatory reporting segments command the largest revenue pools due to their recurring mandate-driven nature and penalty-avoidance value proposition. Risk assessment and policy development segments exhibit faster expansion trajectories as banks confront climate risk disclosures and operational resilience requirements from multiple supervisors simultaneously.
The Federal Reserve, the European Banking Authority, and the Bank of England collectively shape demand through staggered implementation timelines for Basel III endgame rules, climate stress-testing, and operational resilience directives that force banks to rebuild governance infrastructure. The EU's Digital Operational Resilience Act and the UK's forthcoming Consumer Duty standards create overlapping compliance obligations requiring jurisdiction-specific advisory support. Stakeholders must monitor divergence between US prudential proposals and European final rules to anticipate where cross-border banks will concentrate restructuring spend.
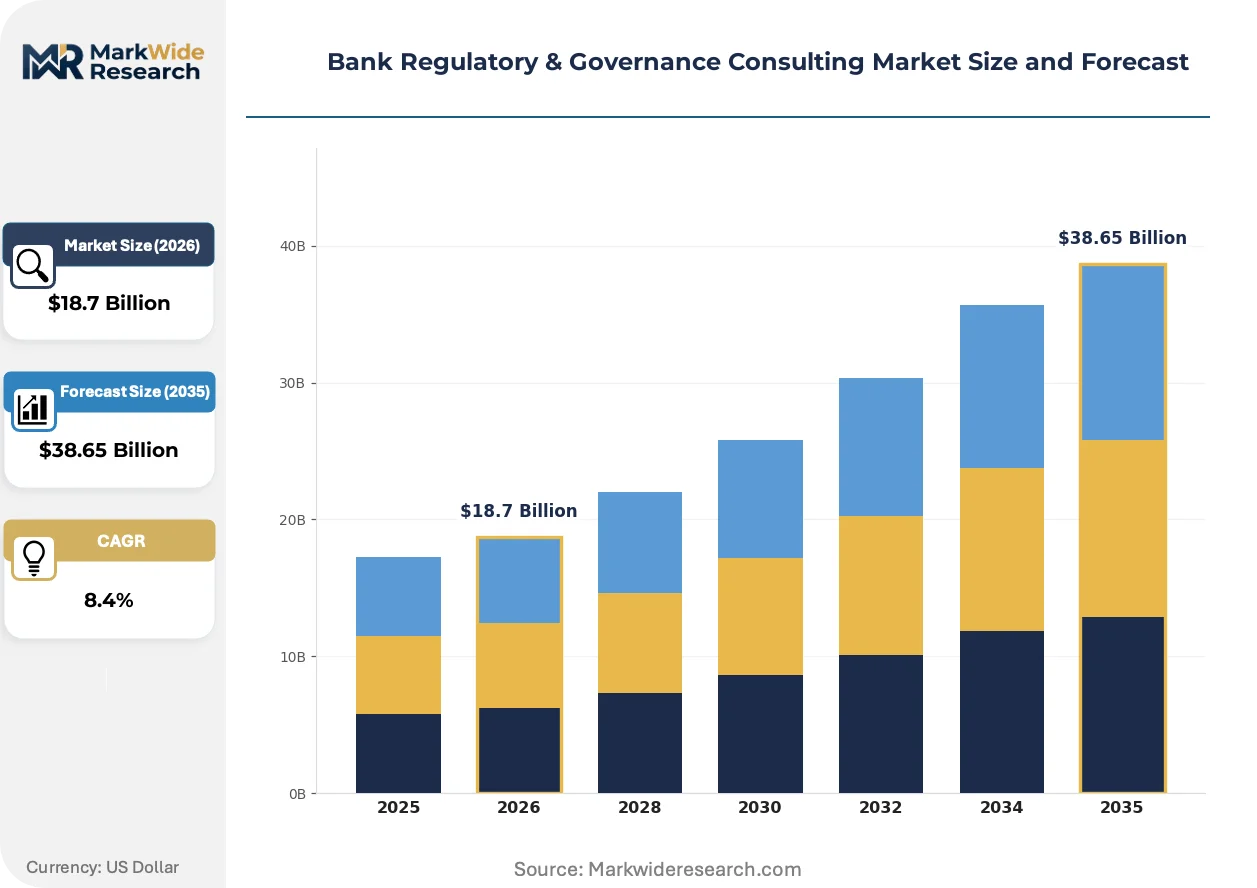
Market Dynamics
Regulatory divergence between the Federal Reserve, European Banking Authority, and Bank of England is fragmenting compliance frameworks and forcing banks to maintain multiple jurisdiction-specific governance infrastructures simultaneously.
Growth Catalysts
- Basel III endgame implementation:Staggered adoption timelines across the United States, European Union, and United Kingdom generate sustained demand for capital adequacy recalculation and liquidity risk framework redesign.
- Climate stress-testing mandates:The Bank of England's Biennial Exploratory Scenario and the ECB's economy-wide climate risk exercises require banks to build new data architectures and scenario modeling capabilities.
- Operational resilience directives:The EU's Digital Operational Resilience Act and the UK's operational resilience framework impose hard deadlines for critical service mapping and third-party risk management overhauls.
Market Restraints
- Talent scarcity in prudential modeling:Deep expertise in risk-weighted asset optimization and stress-testing protocols concentrates among senior practitioners at the Big Four, constraining advisory capacity expansion.
- Regulatory friction from rulebook divergence:Post-Brexit UK-EU regulatory misalignment forces cross-border banking groups to duplicate compliance spend rather than harmonize governance structures.
- Substitution by in-house regulatory technology:Large systemic banks are building captive compliance platforms using vendor software, reducing reliance on external advisory for recurring reporting obligations.
Strategic Opportunities
- Asia-Pacific regulatory convergence:Australia's APRA and Singapore's MAS are adopting Basel III frameworks with local modifications, creating demand for advisors who bridge Western prudential standards with Asian supervisory expectations.
- Consumer Duty advisory services:The UK's forthcoming Consumer Duty standards require banks to demonstrate fair value and behavioral outcomes, opening new advisory revenue pools in product governance and board accountability design.
- Regulatory technology integration:Convergence of artificial intelligence and supervisory data reporting is creating opportunities for advisors who can embed machine learning into second-line defense functions without triggering model risk management concerns.
Industry Challenges
- Multi-jurisdiction talent deployment:Advisory firms struggle to staff engagements requiring simultaneous expertise in US prudential rules, EU capital requirements regulation, and UK ring-fencing standards.
- Legacy system integration complexity:Banks' core banking platforms and risk data warehouses require expensive retrofitting to meet new climate disclosure and operational resilience data granularity requirements.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bank Regulatory & Governance Consulting Market Trends and Innovations
Advisory delivery models are pivoting from episodic project engagements toward embedded second-line defense partnerships, driven by supervisors' expectations of sustained compliance oversight rather than one-time framework design.
Regulatory technology platforms are absorbing an expanding share of routine compliance monitoring and reporting workflows previously executed by human advisory teams. Mid-tier banks in the United States and United Kingdom are adopting cloud-native governance tools to automate risk data aggregation and regulatory filing preparation. This technology absorption is compressing margins on traditional compliance auditing services while elevating demand for advisors who can configure and validate these platforms.
The European Banking Authority's finalization of Basel III standards is accelerating capital requirement recalculations across EU-headquartered banking groups. Banks must restate risk-weighted assets under revised standardized approaches and renegotiate internal model approvals with national competent authorities. The Netherlands and Germany host the most affected institutions, with Dutch banks facing particular pressure from recalibrated output floor calculations.
Chief risk officers are consolidating vendor relationships and demanding outcome-based advisory contracts with penalty clauses for regulatory examination failures. This procurement compression is displacing hourly-rate engagements in favor of fixed-fee transformation programs with defined compliance milestones. The shift is most visible among UK building societies and US regional banks with limited internal regulatory affairs capacity.
Bank Regulatory & Governance Consulting Market Segmentation
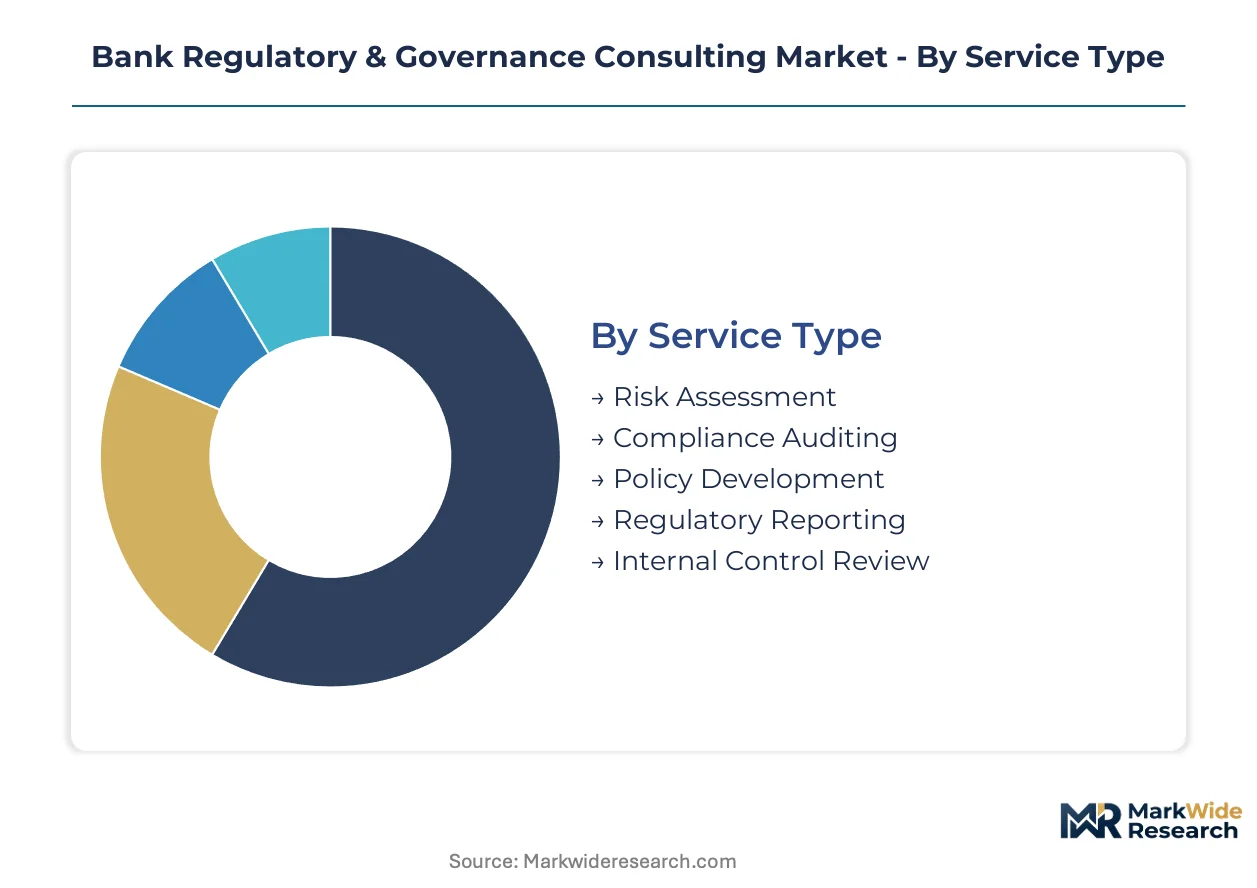
Advisory firms structure their service portfolios around distinct engagement rhythms and client sophistication levels. Segmentation reveals where recurring revenue concentrates versus where project-based margins erode.
Service Type:
Regulatory pressure intensity separates buyers seeking episodic framework design from those demanding continuous oversight integration.
- Compliance Auditing:Systematic examination of control environments against prudential standards, generating recurring mandate-driven engagements. United Kingdom retail banks sustain the heaviest audit volume as the Prudential Regulation Authority tightens supervisory scrutiny post-Brexit.
- Regulatory Reporting:Structured data aggregation and submission services satisfying capital adequacy and liquidity disclosure requirements. Dutch banking groups dominate demand following recalibrated output floor calculations under EU Basel III finalization.
- Risk Assessment:Quantitative evaluation of credit, market, and operational risk exposures against stress scenarios.
- Policy Development:Drafting board accountability charters and risk appetite frameworks aligned to jurisdiction-specific rulebooks.
- Internal Control Review:Testing segregation of duties and authorization workflows within three-line defense architectures.
Volume sits with Compliance Auditing; growth tilts toward Regulatory Reporting.
Engagement Type:
Procurement sophistication determines whether banks purchase discrete deliverables or embedded capability transfers.
- Advisory:Strategic guidance on regulatory interpretation and governance architecture without execution responsibility. United States regional banks under Federal Reserve enhanced prudential standards drive sustained advisory demand for capital planning.
- Implementation:Hands-on deployment of compliance frameworks, technology configurations, and control redesigns. German universal banks lead implementation spend as ECB climate stress-testing deadlines approach.
- Training & Development:Board and executive education on emerging supervisory expectations and examination protocols.
- Outsourcing:Transfer of recurring compliance monitoring and regulatory filing preparation to external specialists.
- Strategic Planning:Long-term regulatory roadmap development spanning multiple implementation cycles.
Advisory commands current spend; Implementation exhibits the steepest expansion trajectory.
Client Type:
Balance sheet complexity and supervisory intensity shape advisory procurement patterns across financial intermediaries.
- Retail Banks:Deposit-taking institutions with extensive branch networks facing consumer protection and operational resilience mandates. United Kingdom building societies concentrate demand for forthcoming Consumer Duty compliance preparation.
- Investment Firms:Broker-dealers and trading venues navigating market infrastructure regulations and clearing obligations.
- Credit Unions:Member-owned cooperatives with limited internal regulatory affairs capacity seeking external compliance support.
- Asset Managers:Collective investment undertakings confronting AIFMD and UCITS governance requirements.
- Microfinance Institutions:Small-scale lenders adapting to proportionate prudential standards in emerging jurisdictions.
Retail Banks anchor revenue; Investment Firms are gaining share fastest.
Delivery Model:
Supervisory expectations of sustained oversight presence are reshaping how advisory services reach client organizations.
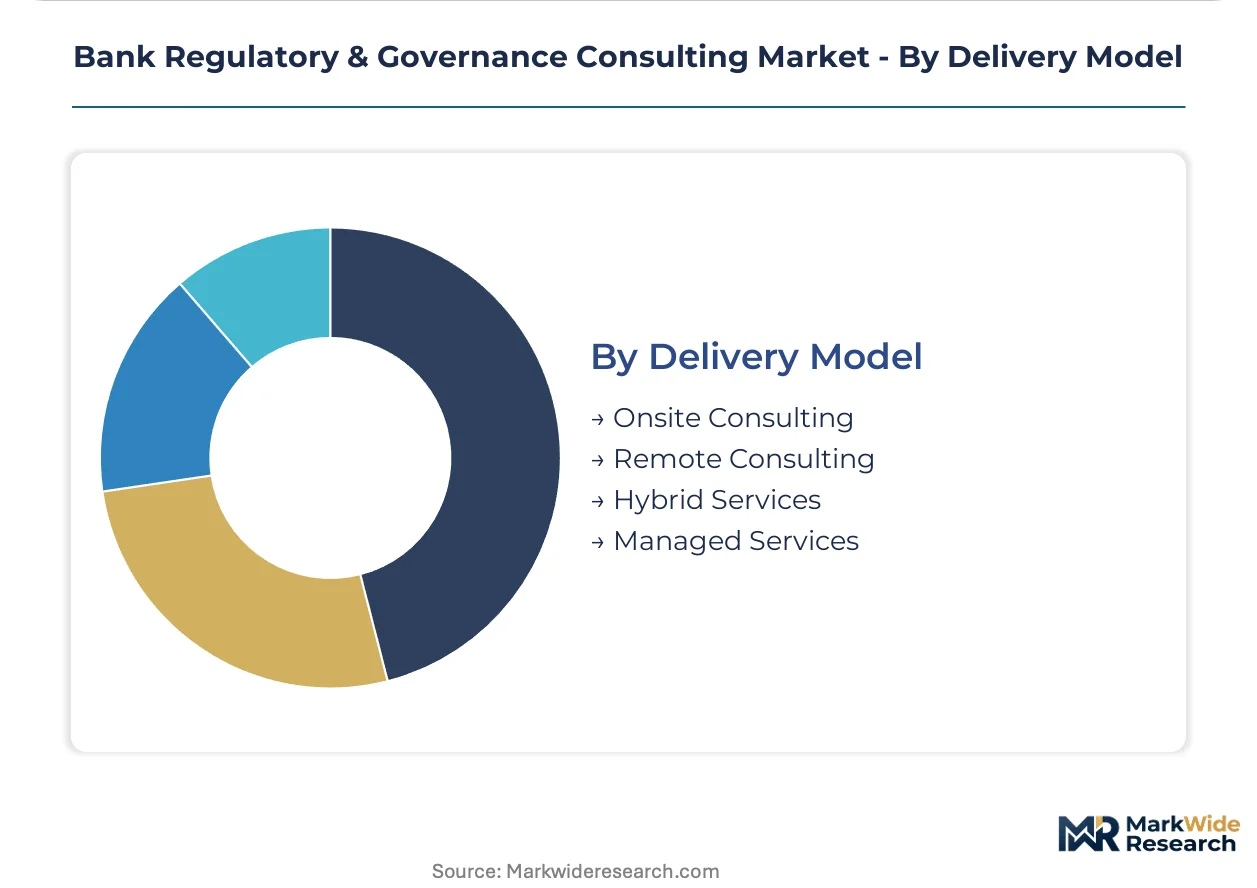
- Hybrid Services:Alternating onsite and remote delivery balancing relationship depth with cost efficiency. United States regional banks favor hybrid models for Federal Reserve examination preparation cycles.
- Managed Services:Continuous embedded advisory presence within second-line defense functions. Large EU banking groups adopt managed services for Digital Operational Resilience Act compliance monitoring.
- Onsite Consulting:Full-time physical presence for intensive transformation programs and examination readiness.
- Remote Consulting:Location-independent delivery leveraging regulatory technology platforms for routine monitoring.
Hybrid Services dominate current deployment; Managed Services show the strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's Square Mile anchors the advisory talent pool that banks draw upon for prudential compliance restructuring. Frankfurt's banking district houses the European Central Bank's supervisory arm, creating concentrated demand for capital adequacy specialists. Singapore's Marina Bay financial hub is emerging as the coordination point for Asia-Pacific regulatory convergence.
United States
Regional banks in the Midwest and Southeast are expanding compliance teams under Federal Reserve enhanced prudential standards. The Fed's staggered Basel III endgame implementation timeline forces institutions to recalculate risk-weighted assets. New York's financial district concentrates advisory demand from systemically important banks facing simultaneous SEC and Fed examinations.
United Kingdom
Post-Brexit regulatory divergence from EU rulebooks sustains advisory demand for cross-border banking groups. The Prudential Regulation Authority's tightening scrutiny of building societies drives recurring compliance audit volume. London's Big Four advisory cohort dominates governance consulting for systemic banks navigating ring-fencing standards.
Germany
Universal banks face pressure from ECB climate stress-testing deadlines approaching for 2025-2026 cycles. The Bundesbank's implementation of EU Basel III finalization rules forces output floor recalculations across Frankfurt-headquartered institutions. Munich and Hamburg host mid-tier Landesbanks seeking external capital modeling expertise.
Netherlands
Dutch banking groups confront recalibrated output floor calculations under EU Basel III finalization. ING and ABN AMRO anchor demand in Amsterdam for risk-weighted asset optimization advisory. The Dutch Central Bank's stringent internal model approval processes sustain implementation-focused consulting engagements.
Singapore
Monetary Authority of Singapore adoption of Basel III frameworks with local modifications creates bridging advisory demand. Wealth management subsidiaries of European and US banks require jurisdiction-specific governance infrastructure. Marina Bay and Raffles Place financial clusters concentrate compliance technology integration projects.
Bank Regulatory & Governance Consulting Market Competitive Landscape
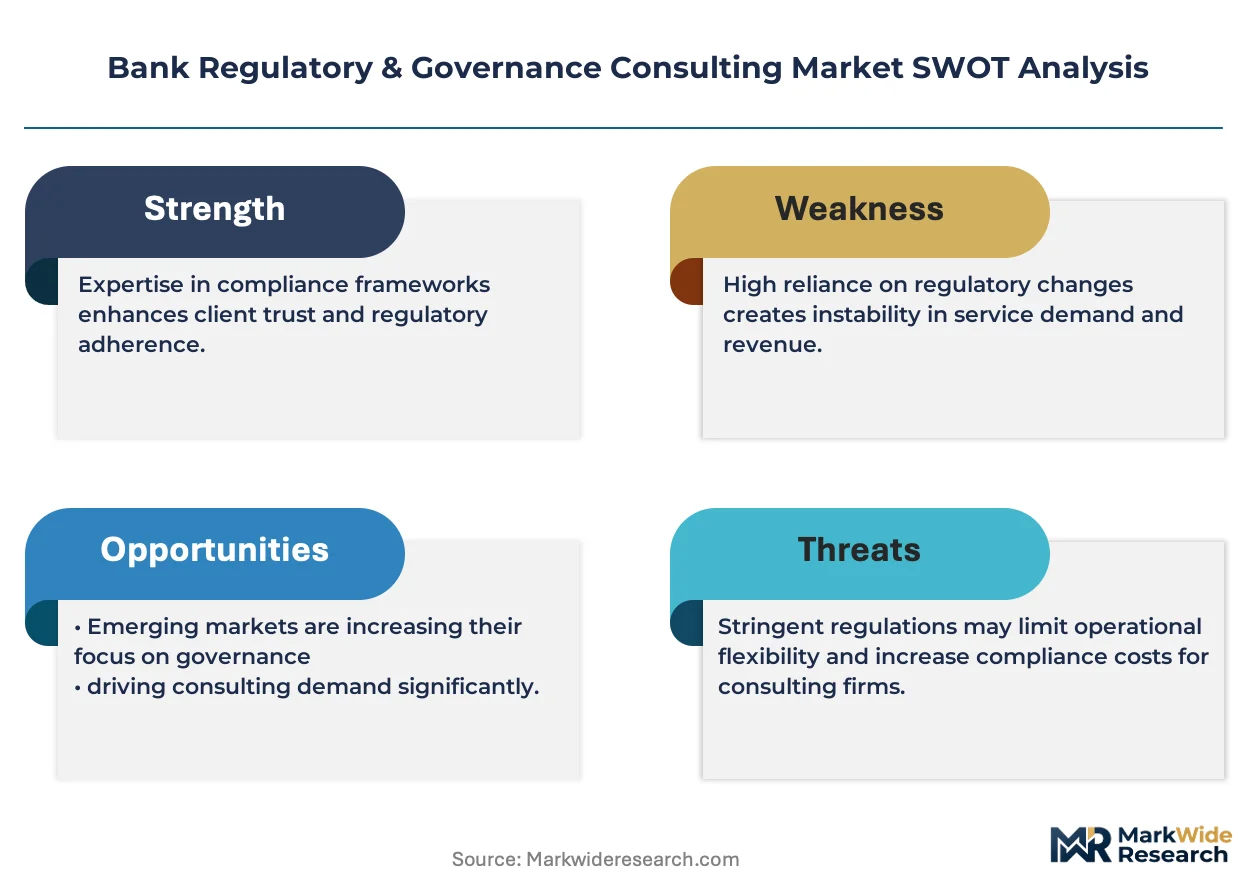
Global majors compete with regional champions across advisory methodology and regulatory technology integration capabilities. The market structure consolidates around four dominant professional services networks with deep prudential expertise, while mid-tier specialists carve positions in niche jurisdictions. Strategic archetypes separate methodology-led framework designers from technology-embedded implementation partners and sector-specialist boutiques. Competitive moves concentrate on acquiring regulatory technology capabilities and embedding advisory teams into client second-line defense functions.
Within the Big Four advisory tier, Deloitte, PwC, and KPMG occupy positions shaped by distinct capability emphases. Deloitte leverages its global risk methodology network for cross-border compliance programs. PwC anchors its presence through regulatory technology integration teams embedding in client defense functions. KPMG sits within the specialist tier for prudential capital modeling and stress-testing protocols.
| Leading Market Players |
|---|
| Deloitte |
| PwC |
| KPMG |
| EY |
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Accenture |
| BRG |
| Others |
Pricing and Supply Chain Analysis
Cross-border banking groups concentrated in London and Frankfurt anchor demand for advisory services, locking in project-based pricing models with outcome-based penalty clauses for regulatory examination failures. This buyer concentration forces advisory firms to bundle sustained second-line defense presence into fixed-fee transformation programs rather than unbundle hourly-rate engagements.
Pricing Analysis
Outcome-based warranty structures now bundle multi-year compliance monitoring with initial framework design, displacing unbundled hourly-rate engagements. Three-tier pricing structure across premium, standard, and economy levels separates Big Four methodology-led programs from mid-tier specialist boutiques and technology-embedded implementation partners. Cost compression in standard-tier compliance auditing is intensifying because regulatory technology platforms automate routine monitoring workflows. Mid-tier banks in the United States and United Kingdom exhibit the highest price sensitivity, while systemically important banks in New York and London prioritize penalty-avoidance value over unit cost.
Supply Chain Analysis
Senior prudential modeling expertise rests on a thin talent layer concentrated in London, New York, and Frankfurt, where Big Four partners with ECB and Federal Reserve examination experience command premium deployment rates. Advisory capacity draws from risk-weighted asset optimization specialists, climate stress-testing protocol designers, and operational resilience framework architects. Single-source vulnerability concentrates in prudential capital modeling, where deep expertise resides with senior practitioners approaching retirement. Distribution runs through embedded second-line defense partnerships rather than discrete project engagements, with advisory teams physically co-located within client governance functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bank regulatory and governance consulting sits in a technology-transition phase, with artificial intelligence and machine learning platforms displacing legacy manual compliance monitoring workflows. This shift compresses margins on traditional services while elevating demand for technology configuration and validation expertise.
For Market Incumbents: To counter in-house regulatory technology buildouts by large systemic banks, deepen captive advisory presence within client second-line defense functions and acquire specialized regulatory technology capabilities. Anchor methodology-led framework design with outcome-based contracts that embed penalty clauses for examination failures.
For New Entrants and Emerging Players: Mid-tier regional banks in the United States Midwest and Southeast represent an underserved buyer archetype with limited internal regulatory affairs capacity. Penetrate this segment through cloud-native governance tool implementation paired with fixed-fee transformation programs. Target white-space in Consumer Duty advisory services for UK building societies and climate risk disclosure preparation for German universal banks.
For Investors and Strategic Acquirers: The window for entry favors regulatory technology specialists with machine learning validation capabilities and prudential modeling boutiques with ECB or Federal Reserve alumni networks. Acquisition targets should demonstrate embedded client relationships and jurisdiction-specific expertise spanning multiple implementation cycles. Watch for divergence between US prudential proposals and European final rules as the inflection signal for where cross-border restructuring spend concentrates.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Acquisition | Absorbs automated compliance monitoring workflows previously executed by human advisory teams. |
| Embedded Second-Line Defense Partnership | Meets Bank of England and ECB expectations of sustained oversight presence within client organizations. |
| Climate Risk Disclosure Capability Buildout | Addresses ECB economy-wide climate stress-testing and Bank of England Biennial Exploratory Scenario mandates. |
| Asia-Pacific Regulatory Bridging Service | Captures demand from Singapore MAS and Australia APRA Basel III adoption with local modifications. |
| Consumer Duty Advisory Practice Launch | Opens revenue pools in UK product governance and board accountability design ahead of implementation deadlines. |
Research Methodology
Multi-period observation of Federal Reserve examination cycles, ECB supervisory review timelines, and Bank of England policy consultation periods anchored the trend analysis, supplemented by interviews with chief risk officers, regulatory affairs directors, compliance technology leads, and second-line defense function heads. Secondary validation drew from SEC 10-K disclosures, ECB supervisory statistics, PRA regulatory returns, and Basel Committee on Banking Supervision implementation reports. Bottom-up service line revenue estimates triangulated against top-down market sizing by geography and client type.
Segment-weighting across service type, engagement model, client category, and delivery mechanism shaped the analytical framework over the projection horizon. Modeled dimensions included compliance auditing versus regulatory reporting revenue splits, advisory versus implementation engagement mix, and hybrid versus managed service deployment patterns. CAGRs derived from trajectory analysis of regulatory implementation timelines and supervisory intensity indicators, with specific inputs from Basel III endgame adoption schedules and operational resilience directive deadlines.
Revisions become necessary when regulatory rulebook divergence accelerates beyond modeled scenarios, when large systemic banks accelerate in-house technology substitution, or when prudential modeling talent scarcity constrains advisory capacity expansion more severely than projected. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.