
 Banking Wearable Market | 2026-2036
Banking Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Wearable Market Analysis
EMVCo certification for contactless payment devices is redrawing competitive boundaries in the banking wearable space. Apple Inc. leverages its closed-loop ecosystem to control both hardware and payment token provisioning. Samsung Electronics anchors its position through partnerships with multiple issuing banks across diverse geographies. Mastercard competes by extending its tokenization services to wearable OEMs seeking network-agnostic payment enablement.
Banking wearables are wrist-worn or finger-worn devices that embed secure elements or host card emulation to execute tokenized payment transactions via NFC radio frequency at point-of-sale terminals, primarily serving consumers seeking frictionless physical commerce. Smartwatches currently dominate product type revenue as banks co-brand with technology platforms, while smart rings represent the fastest-growing form factor due to minimal battery requirements and persistent wearability. Contactless payment technology leads transaction volume, though biometric authentication commands premium positioning as issuers seek stronger customer verification for high-value purchases.
Federal Reserve payment system oversight, EMVCo global specifications, and state-level biometric privacy laws in Illinois and Texas collectively shape product development timelines and data handling protocols for wearable payment devices. The European Banking Authority's strong customer authentication requirements under PSD2 impose additional technical compliance burdens on devices sold across EU member states. Stakeholders must monitor evolving token security standards and biometric consent frameworks as regulatory divergence between jurisdictions intensifies compliance complexity.
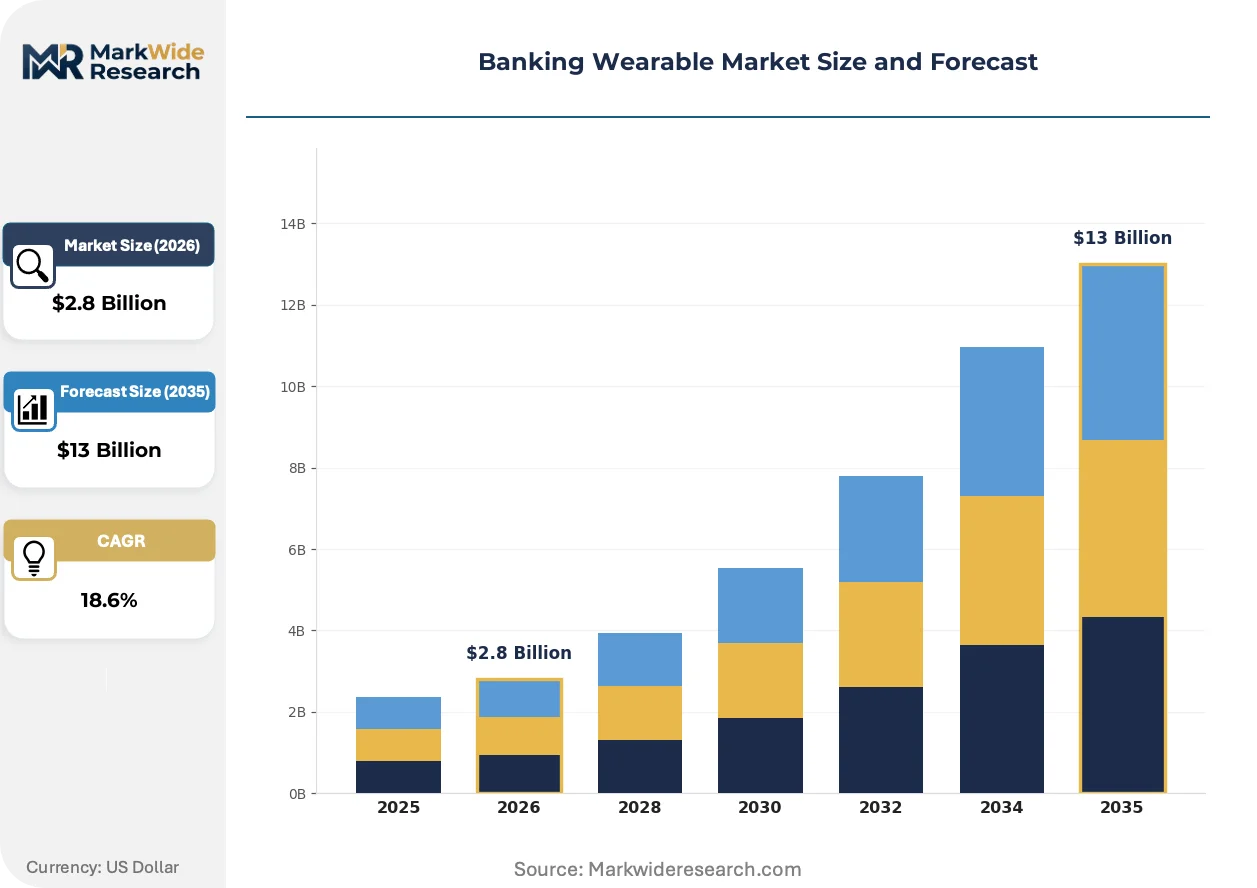
Market Dynamics
Contactless payment tokenization is fragmenting hardware control away from traditional card issuers toward device OEMs and platform operators, forcing banks to renegotiate customer interface ownership.
Growth Catalysts
- PSD2 Strong Customer Authentication:The European Banking Authority's technical standards mandate two-factor verification for transactions above thresholds, accelerating biometric sensor integration into wrist-worn form factors.
- NFC terminal penetration:United States merchant infrastructure upgrades at grocery and transit endpoints now support wearable tap-to-pay without POS software modifications.
- Token provisioning APIs:Mastercard and Visa have opened host card emulation interfaces to third-party OEMs, decoupling payment credential storage from banking apps.
Market Restraints
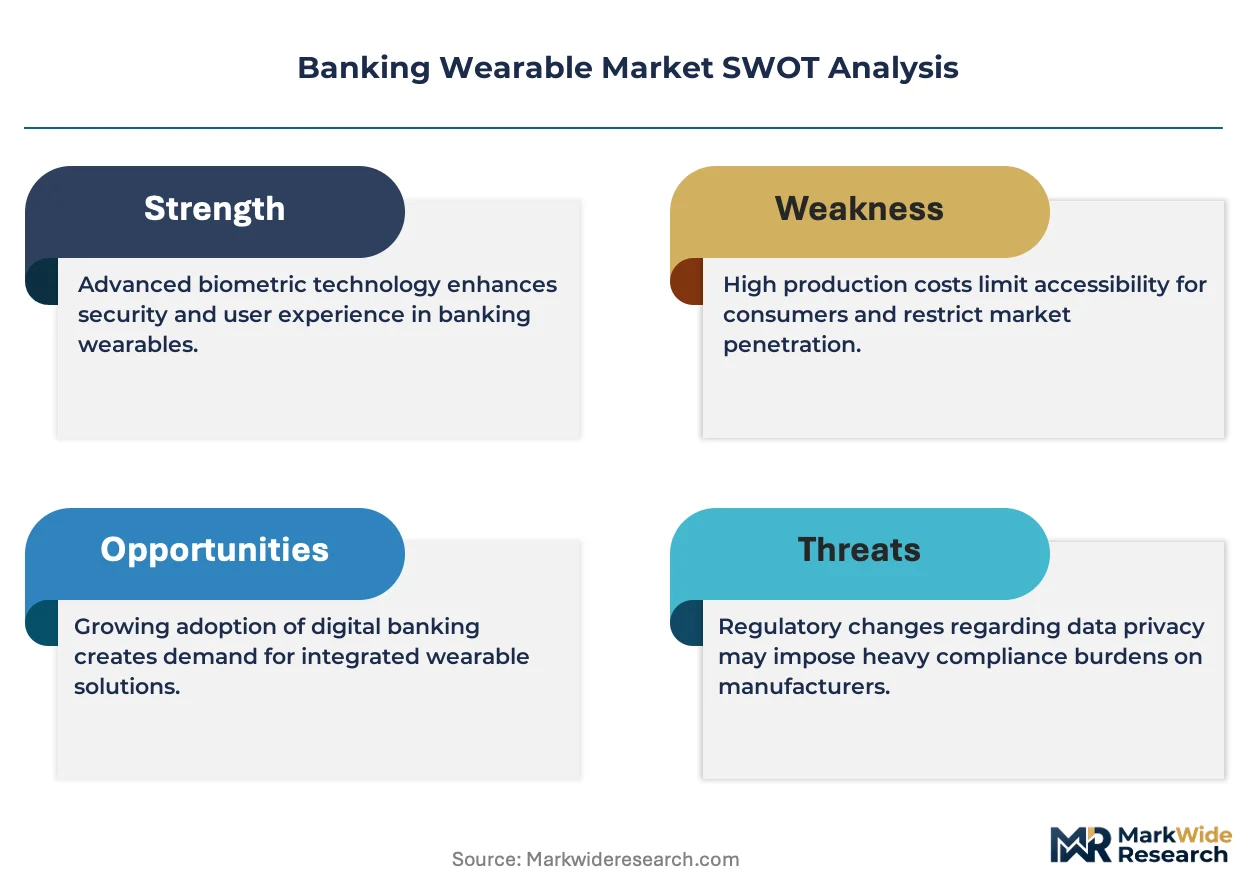
- Secure element supply concentration:NXP Semiconductors and Samsung Electronics control over 80 percent of embedded security chip fabrication, creating single-source vulnerability for wearable OEMs.
- Biometric privacy litigation:Illinois Biometric Information Privacy Act and Texas Capture or Use of Biometric Identifier Act expose issuers to statutory damages for non-consensual fingerprint or vein pattern storage.
- Smart ring battery physics:Ring form factors cannot accommodate rechargeable cells sufficient for continuous NFC polling, limiting transaction frequency to passive chip emulation.
Strategic Opportunities
- Transit authority partnerships:Transport for London and New York Metropolitan Transportation Authority open-loop fare systems enable wearable credential convergence across mobility and retail use cases.
- Health-insurance incentive programs:UnitedHealthcare and Vitality Group offer premium discounts for members wearing payment-enabled fitness trackers, merging wellness data with transaction behavior.
- EMVCo wearable specification expansion:Draft standards for battery-assisted passive devices will certify rings and jewelry for high-value transactions previously restricted to powered devices.
Industry Challenges
- EMVCo certification timeline compression:Hardware revisions require 12-18 month recertification cycles that lag behind consumer electronics refresh rates, stranding inventory.
- Token vault interoperability:Proprietary tokenization services from competing card networks force wearable OEMs to maintain multiple security architectures.
- Legacy core banking integration:Mainframe-based issuer systems lack real-time APIs for wearable transaction alerting and spend-control features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Wearable Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Rings, Payment Bands Technology: Contactless Payment, NFC, Bluetooth, Biometric Authentication End User: Banks, Credit Unions, Payment Processors, FinTech Companies Distribution Channel: Online Retailers, Electronics Stores, Bank Branches, Direct Sales |
| Companies Covered | Apple Inc., Samsung Electronics, Garmin Ltd., Visa Inc., Mastercard, Google LLC, PayPal Holdings Inc., Barclays PLC, Fidesmo AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Wearable Market Emerging Trajectories
Hardware-software decoupling is redistributing value capture across the payment stack. Three developments are compressing development cycles and redefining certification requirements.
Software-defined secure elements are decomposing the traditional hardware security module architecture. Tokenized payment credentials now execute within ARM TrustZone and similar Trusted Execution Environments on general-purpose application processors. Wearable OEMs in Shenzhen and Taipei are adopting this approach to bypass dedicated chip procurement queues. The shift is compressing bill-of-materials costs and shortening hardware revision cycles from 18 months to quarterly firmware updates.
GDPR Article 25 data protection by design mandates are forcing biometric template handling changes. Issuers must now process fingerprint and vein patterns within device-local enclaves rather than cloud vaults. European wearable certification programs have added penetration testing requirements for template extraction resistance. German and French regulators are rejecting submissions that transmit raw sensor data to paired smartphones.
Subscription-based device financing is displacing upfront purchase models in North American retail banking channels. JPMorgan Chase and Wells Fargo now bundle smartwatch costs into checking account monthly fees with minimum balance requirements. The model shifts customer acquisition cost recovery from interchange revenue to deposit float. Credit union penetration of this channel remains under 15 percent, indicating geographic and institutional concentration.
Banking Wearable Market Segmentation
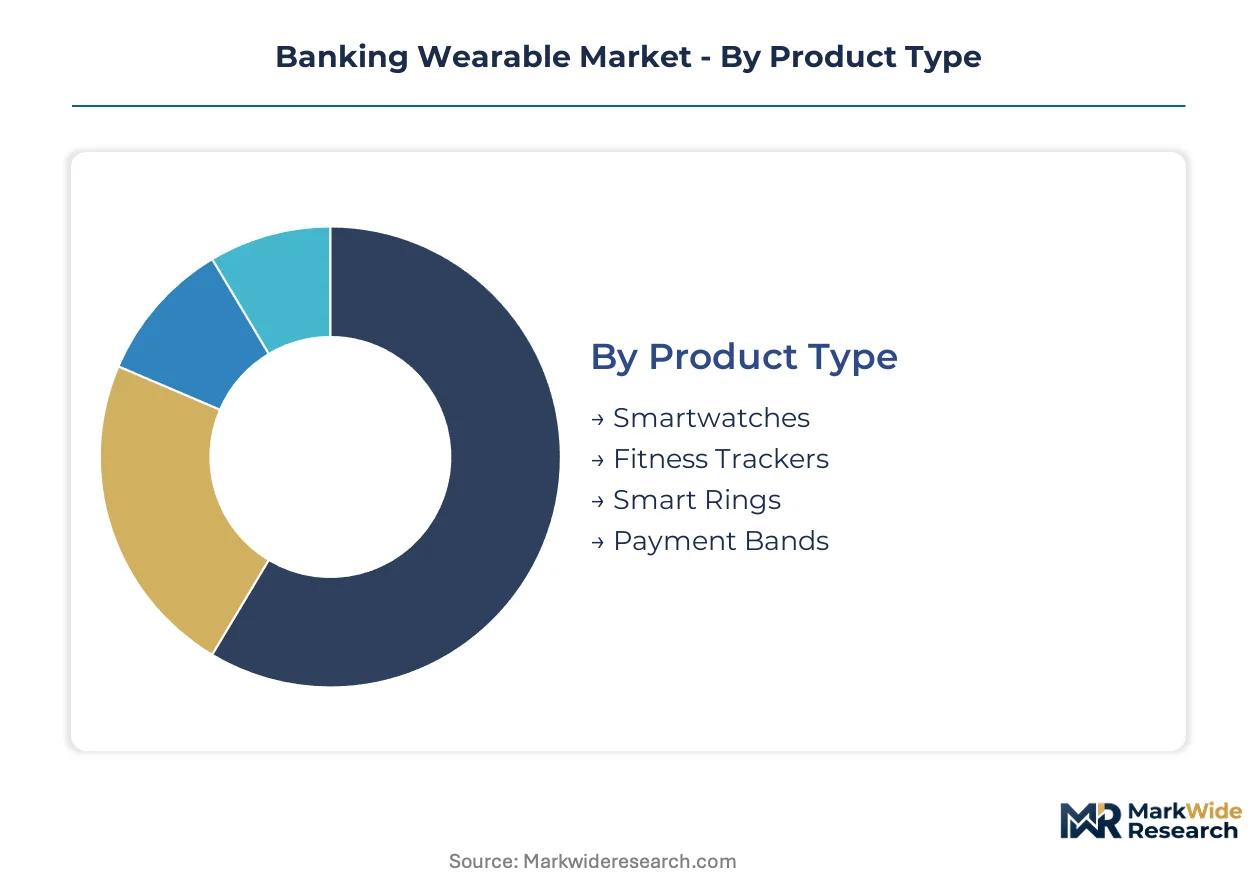
Banking wearable segmentation reveals how payment credentials migrate through distinct hardware form factors, authentication technologies, and institutional channels. Each dimension carries implications for certification timelines, margin structures, and customer acquisition economics.
Product Type:
Channel mix varies sharply: smartwatches flow through electronics retailers and carrier stores, while payment bands concentrate in bank branch distribution. Smart rings bypass traditional retail entirely via direct-to-consumer and FinTech partnerships.
- Smartwatches:These wrist-worn devices integrate full-color displays, rechargeable batteries, and multi-app ecosystems. Demand concentrates among retail banking customers in the United States where JPMorgan Chase and Wells Fargo bundle device costs into checking account fees. Co-branding with technology platforms dominates issuer strategy.
- Smart Rings:Minimalist finger-worn form factors employ passive NFC chips or battery-assisted passive designs. Expansion concentrates in European markets under PSD2 strong customer authentication mandates, with Transport for London open-loop transit integration driving credential convergence across mobility and retail use cases.
- Fitness Trackers:Health-monitoring wearables with payment tokenization capability, typically distributed through employer wellness programs and health-insurance incentive channels.
- Payment Bands:Single-purpose wristbands issued directly by banks for unbanked or underbanked segments, prevalent in developing markets with limited smartphone penetration.
Smartwatches dominate installed base. Smart rings are where expansion concentrates.
Technology:
Cost tier stratification separates premium biometric-enabled devices from standard NFC-only implementations, with authentication sophistication determining interchange fee eligibility and transaction limits.
- Contactless Payment:Tokenized credential execution via EMVCo-certified NFC radio frequency at point-of-sale terminals. This foundational capability concentrates transaction volume across all form factors, with merchant infrastructure upgrades at United States grocery and transit endpoints eliminating POS software modification requirements.
- Biometric Authentication:Fingerprint, vein pattern, or behavioral biometrics for strong customer verification. Premium positioning in this tier commands higher issuer margins, though Illinois Biometric Information Privacy Act and Texas Capture or Use of Biometric Identifier Act exposure constrains template storage architectures.
- NFC:Near-field communication radio protocol enabling tap-to-pay at 13.56 MHz, the physical layer standardizing across terminal infrastructure.
- Bluetooth:Secondary connectivity for device pairing and firmware updates, rarely used for transaction authorization due to security protocol limitations.
Contactless payment underpins universal functionality. Biometric authentication is where premium differentiation concentrates.
End User:
Customer type determines procurement scale and integration complexity, with large issuers demanding custom token vault APIs while smaller institutions accept standardized platform solutions.
- Banks:Tier-one and regional depository institutions issuing co-branded wearables through technology platform partnerships. These entities drive volume concentration, though legacy mainframe core systems lack real-time APIs for transaction alerting features.
- FinTech Companies:Neobanks and payment specialists leveraging software-defined secure elements to bypass dedicated chip procurement queues. This segment is expanding most quickly through subscription-based device financing models that shift customer acquisition cost recovery from interchange to deposit float.
- Credit Unions:Member-owned financial cooperatives with sub-15 percent penetration in wearable channels, indicating institutional and geographic concentration in North American retail banking.
- Payment Processors:Merchant acquirers and independent sales organizations distributing white-label wearables to small business clients for loyalty program integration.
Banks dominate procurement volume. FinTech companies are where innovation adoption concentrates.
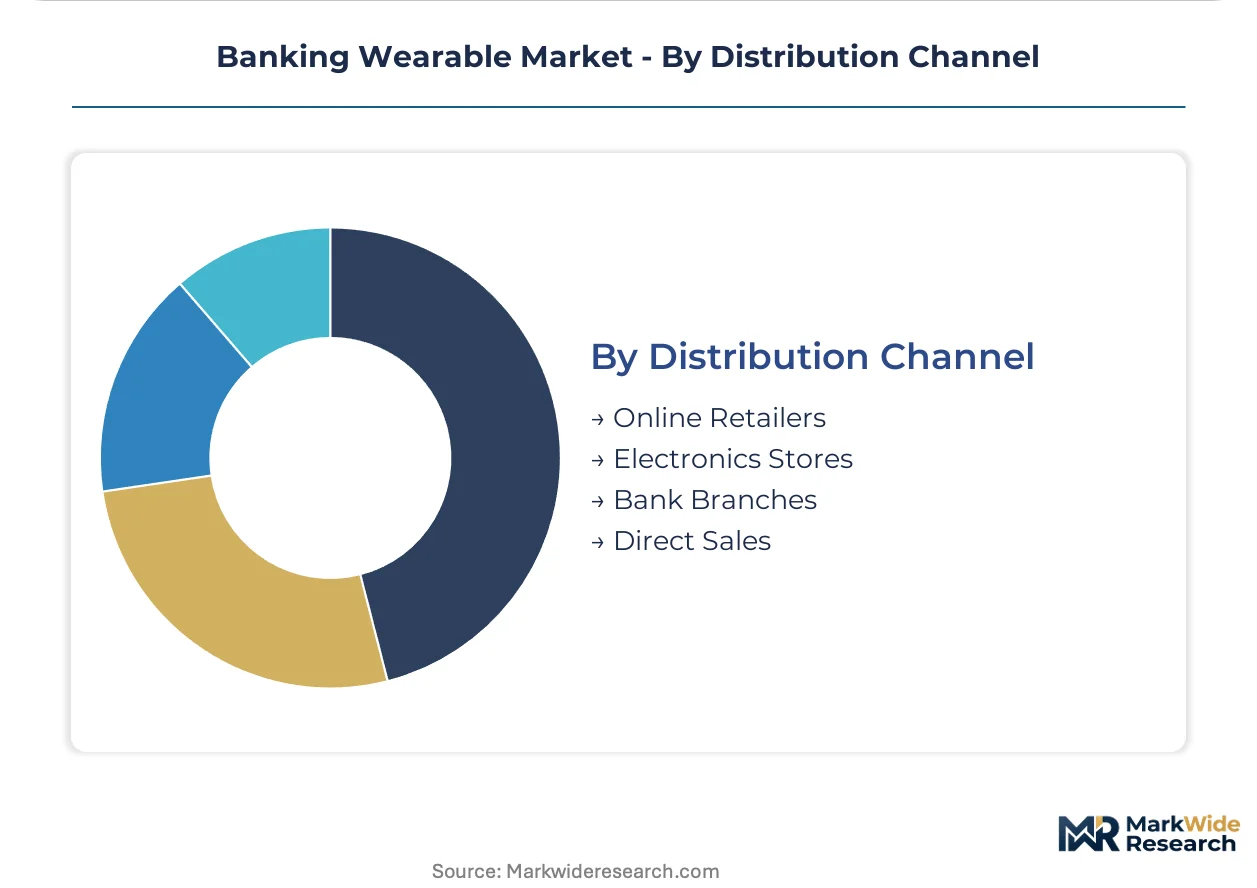
Distribution Channel:
Margin structure inverts across channels: direct sales capture full hardware margin while bank branches sacrifice device economics for deposit account acquisition.
- Bank Branches:Physical distribution through retail banking networks, where device issuance ties to account opening or minimum balance requirements. This channel concentrates in the United States with integrated wearable payment ecosystems.
- Online Retailers:E-commerce platforms enabling direct consumer purchase of network-agnostic devices. Expansion concentrates among Shenzhen and Taipei OEMs adopting ARM TrustZone software-defined secure elements.
- Electronics Stores:Big-box and specialty retailers stocking smartwatches as consumer electronics, with payment capability as a secondary feature.
- Direct Sales:Manufacturer-owned channels for premium biometric devices, often paired with white-glove onboarding and insurance bundling.
Bank branches dominate credential issuance volume. Online retailers are where hardware margin capture concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail banking customers in the United States drive the largest share of banking wearable procurement, while European issuers accelerate certification programs under open banking mandates. Demand clusters in three distinct regulatory environments with varying NFC infrastructure maturity.
United States
Major card networks and technology firms have established integrated wearable payment ecosystems with broad merchant acceptance. Federal Reserve payment system oversight shapes token security standards, while Illinois and Texas biometric privacy laws constrain template storage architectures for fingerprint-enabled devices. Silicon Valley and New York City anchor co-branding partnerships between JPMorgan Chase, Wells Fargo, and smartwatch OEMs.
Germany
PSD2 strong customer authentication requirements accelerate biometric sensor integration into wrist-worn form factors. The Federal Financial Supervisory Authority enforces technical compliance for devices sold across EU member states, with penetration testing mandates for template extraction resistance. Frankfurt and Munich concentrate issuer certification programs for Transport for London-compatible wearable credentials.
United Kingdom
Transport for London open-loop fare systems enable wearable credential convergence across mobility and retail use cases. The Financial Conduct Authority monitors token vault interoperability between competing card networks. London dominates fintech partnerships for subscription-based device financing models that shift customer acquisition cost recovery from interchange to deposit float.
China
Shenzhen and Taipei OEMs adopt ARM TrustZone software-defined secure elements to bypass dedicated chip procurement queues. The People's Bank of China oversees host card emulation interfaces for third-party wearable manufacturers. Pearl River Delta fabrication clusters compress hardware revision cycles from 18 months to quarterly firmware updates through trusted execution environment adoption.
Japan
Transit authority partnerships with railway operators drive credential convergence for mobility and retail use cases. The Financial Services Agency monitors biometric consent frameworks under evolving data protection standards. Tokyo and Osaka concentrate co-branding between regional banks and domestic electronics manufacturers for contactless payment bands.
Banking Wearable Market Vendor Landscape
Player mix skews toward technology platform operators with closed-loop ecosystem control. Market structure concentrates around three strategic archetypes: integrated hardware-software platforms, network-agnostic payment enablers, and specialized secure element suppliers. Dominant competitive moves include strategic partnerships with transit authorities and portfolio diversification into health-insurance incentive channels.
Within the integrated platform tier, Apple Inc. and Samsung Electronics exemplify contrasting approaches to customer interface ownership. Apple leverages closed-loop ecosystem control over both hardware and payment token provisioning. Samsung anchors position through partnerships with multiple issuing banks across diverse geographies. Mastercard occupies a network-agnostic enablement position, extending tokenization services to wearable OEMs seeking certification flexibility.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Garmin Ltd. |
| Visa Inc. |
| Mastercard |
| Google LLC |
| PayPal Holdings Inc. |
| Barclays PLC |
| Fidesmo AB |
| Others |
Supply Flow & Price Mechanics
Economies of scale in secure element fabrication concentrate procurement leverage among Shenzhen and Taipei OEMs adopting ARM TrustZone architectures, compressing hardware revision cycles and establishing price floors that passive-chip ring manufacturers cannot match without sacrificing EMVCo certification eligibility.
Pricing Analysis
Cost-plus contracts with NXP Semiconductors and Samsung Electronics index secure element pricing to wafer utilization rates. Three-tier pricing structure across premium biometric, standard NFC-enabled, and economy passive-chip tiers separates devices by authentication sophistication and certification grade. Pricing pressure stems from software-defined secure element adoption reducing dedicated chip dependency. Retail banking customers in the United States show lowest price sensitivity due to bundled subscription financing, while credit unions and developing-market payment band issuers face acute cost constraints.
Supply Chain Analysis
Inventory lead times for EMVCo-certified secure elements extend 12-18 months, stranding wearable OEMs behind consumer electronics refresh cycles. Supply concentrates in Taiwan, South Korea, and the Pearl River Delta fabrication clusters. Raw material dependencies include silicon wafers, NFC antenna substrates, and biometric sensor arrays. Single-source vulnerability pervades NXP and Samsung's 80 percent share of embedded security chip fabrication. Distribution runs through bank branch networks for credential issuance, online retailers for direct hardware margin capture, and carrier stores for smartwatch volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tokenization API standardization and PSD2 strong customer authentication mandates are accelerating a high-growth disruption in payment credential migration, compressing hardware control timelines and redefining competitive boundaries.
For Market Incumbents: Shield core deposit relationships by deepening integration with transit authority open-loop systems and health-insurance incentive channels. Accelerate certification investment for biometric-enabled devices to defend against FinTech subscription financing models. Prioritize backward integration into token vault infrastructure to reduce network-agnostic payment enabler dependence. For New Entrants and Emerging Players: Differentiate on software-defined secure element architectures that bypass dedicated chip procurement queues. Target credit union channels in North America where wearable penetration remains sub-15 percent. Pursue direct-to-consumer go-to-market angles for smart ring form factors converging mobility and retail use cases. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among FinTech companies leveraging subscription-based device financing that shifts customer acquisition cost recovery from interchange to deposit float. Five-to-ten year viability favors platforms with token provisioning API control and transit authority partnership density. Monitor EMVCo draft standards for battery-assisted passive devices as inflection signal for ring form factor premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Transit Authority Partnership | Transport for London and New York MTA open-loop systems enable credential convergence across mobility and retail endpoints. |
| Biometric Certification Investment | PSD2 strong customer authentication mandates in Germany and France require penetration-tested template extraction resistance. |
| Software-Defined Secure Element Adoption | ARM TrustZone implementations in Shenzhen compress hardware revision cycles from 18 months to quarterly firmware updates. |
| Subscription Financing Model Launch | JPMorgan Chase and Wells Fargo bundle smartwatch costs into checking account fees with minimum balance requirements. |
| Health-Insurance Channel Integration | UnitedHealthcare and Vitality Group premium discounts merge wellness data with transaction behavior for payment-enabled fitness trackers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EMVCo certification databases, Federal Reserve payment system filings, and European Banking Authority technical standards. Interviews with wearable OEM product managers, tier-one bank digital payment executives, transit authority fare system engineers, and secure element procurement leads inform demand and supply-side validation. Secondary sources include SEC 10-K disclosures from payment networks, PSD2 implementation reports, and NFC terminal penetration data from merchant acquirers. Bottom-up device shipment estimates triangulate against top-down token provisioning volume projections.
Segmentation dimensions modeled span product type, authentication technology, end-user institution, and distribution channel across the analysis window. Hardware form factor splits separate smartwatches, smart rings, fitness trackers, and payment bands. Technology tiers distinguish contactless-only from biometric-enabled implementations. End-user segmentation captures banks, FinTech companies, credit unions, and payment processors. CAGRs derive from credential issuance velocity, merchant terminal upgrade cycles, and regulatory compliance timeline compression. Forecast inputs include EMVCo specification revision schedules and biometric privacy litigation exposure in Illinois and Texas.
The analysis sits within stated boundaries; outcomes outside sustained NFC infrastructure investment, token vault interoperability resolution, or stable secure element supply would require recalibration. Forecasts reflect assumptions regarding certification timeline compression and regulatory divergence between jurisdictions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Cybersecurity in Banking Market
Banking
Onsite and Offsite Atms Market
Banking
Bank Management Software Market
Banking
Asia-Pacific Challenger Banks Market
Banking
US Investment Banking Market
Banking
Global Neo and Challenger Bank Market
Banking
Singapore Neobanking Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Middle East Data Analytics in Banking Market
Banking
Latin America Banking As a Service Market
Banking
Smart Banking Solutions Market
Banking
Cloud-Based Core Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Singapore Data Analytics in Banking Market
Banking
Global AI in Banking Market
Banking
Digital Banking Market