
 Dried Grapes Market | 2026-2036
Dried Grapes Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Grapes Market Analysis
Turkish sultana processors is recalibrating drying capacity after two consecutive seasons of lower Thompson Seedless yields in California's San Joaquin Valley. Sun-Maid Growers of California dominates branded retail shelf space through direct control of cooperative member vineyards. Olam International Limited navigates multi-origin procurement across Turkey, Iran, and Afghanistan to sustain year-round bulk supply to European food manufacturers.
Dried grapes are dehydrated Vitis vinifera berries with moisture content typically reduced below 16 percent through sun-drying, shade-drying, or mechanical dehydration methods, yielding shelf-stable fruit used in baking, confectionery, cereals, and direct consumption. Seedless raisins occupy the largest volume share due to universal compatibility with industrial food manufacturing lines, while sultanas command premium positioning in European bakery channels where lighter color and softer texture differentiate finished products. Retail pouches are gaining share against bulk bags as portion-controlled snacking formats expand in urban supermarkets.
EFSA maximum residue limits and the EU's Farm to Fork Strategy are tightening phytosanitary entry requirements for non-EU dried grape shipments, forcing exporters to adopt integrated pest management documentation. Turkey's national food regulator and Iran's agriculture ministry enforce parallel export certification protocols that shape competitive access to Middle Eastern and South Asian markets. Stakeholders must monitor evolving sulphur dioxide thresholds and organic conversion timelines to avoid disqualification from premium channel placement.
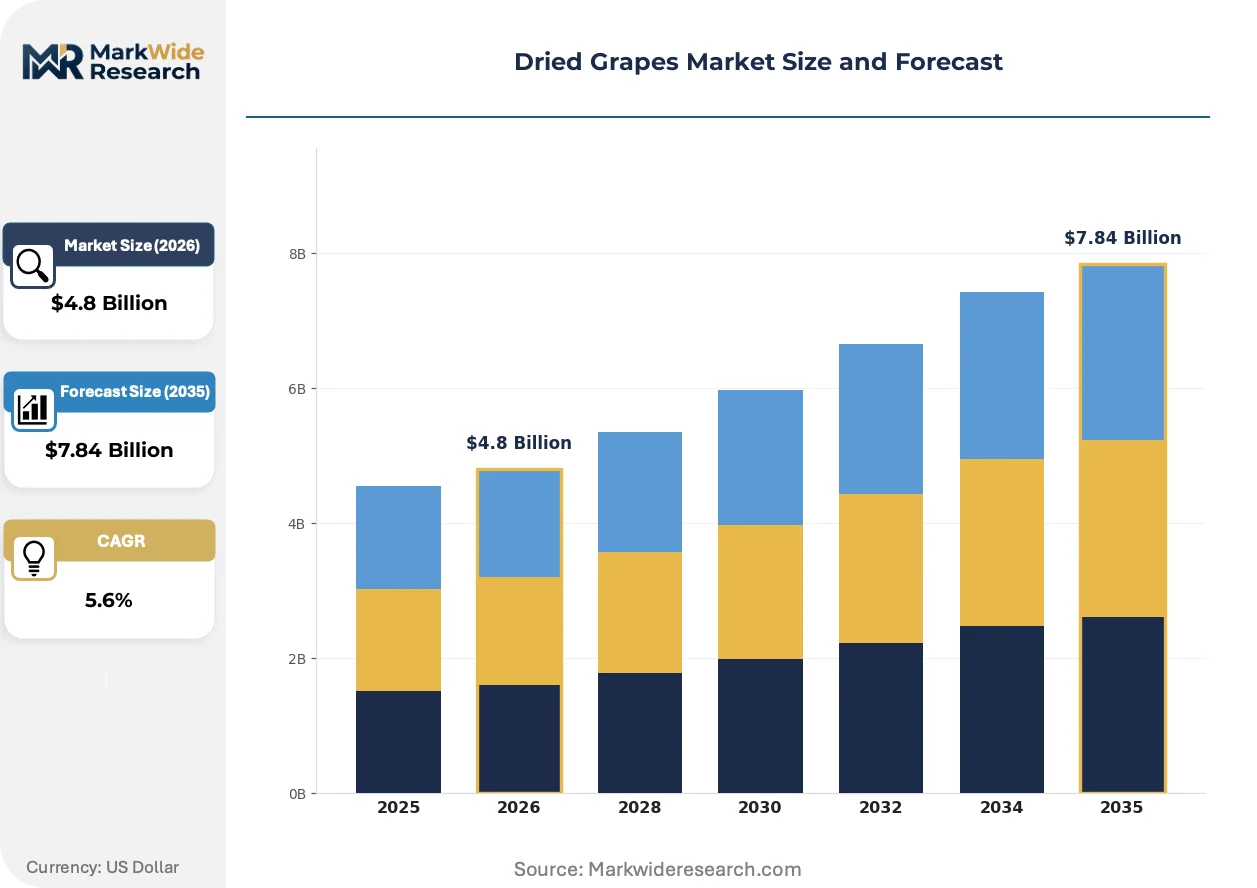
Market Dynamics
EFSA's tightening sulphur dioxide residue limits under the EU's Farm to Fork Strategy is forcing exporters to rebuild processing protocols and documentation systems from vineyard to port, compressing margins for non-compliant origins.
Growth Catalysts
- Clean-label bakery demand:European industrial bakers are reformulating recipes to eliminate artificial preservatives, pulling higher volumes of untreated sultanas into dough and filling applications.
- Mechanical dehydration:Forced-air tunnel dryers with precision humidity controls are reducing sun-drying dependency, stabilizing output quality across variable weather windows.
- Turkey's Aegean processing expansion:New controlled-atmosphere storage facilities in Manisa and Izmir provinces are extending the export shipping season by four months.
Market Restraints
- Thompson Seedless supply volatility:Two consecutive short harvests in California's San Joaquin Valley have tightened seedless raisin feedstock for Turkish reprocessors.
- Phytosanitary documentation burden:EFSA's integrated pest management certification requirements add 12-18 days to EU customs clearance for Afghan and Iranian shipments.
- Sulphur dioxide threshold compression:The EU's pending reduction to 10mg/kg for organic-labeled dried fruit threatens conventional processing economics.
Strategic Opportunities
- Urban snacking formats:Single-serve pouches in Middle Eastern convenience retail are capturing commuter and school-lunch demand previously served by loose bulk.
- Organic conversion timelines:Turkey's national organic certification program offers three-year transition subsidies covering 60% of compliance audit costs.
- Confectionery ingredient pivot:Chocolate enrobing lines in Belgium and Switzerland are substituting dried grapes for candied peel in premium praline fillings.
Industry Challenges
- Sensory grading expertise scarcity:Fewer than 200 certified sultana color graders operate across Turkey's Aegean region, creating bottlenecks at peak harvest intake.
- Legacy drying yard retrofit costs:Converting open-air sun-drying operations to polytunnel shade systems requires capital outlays that cooperative smallholders cannot access without state guarantee programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Grapes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seedless Raisins, Currants, Sultanas, Golden Raisins End User: Food Manufacturers, Retail Consumers, Bakeries, Snack Producers Packaging Type: Bulk Bags, Retail Packs, Tubs, Pouches Distribution Channel: Supermarkets, Online Retailers, Wholesale Distributors, Farmers' Markets |
| Companies Covered | Del Monte Pacific Limited, Stahmann Farms, Inc., Sunsweet Growers Inc., Dole Food Company, Sun-Maid Growers of California, Mariani Packing Company, National Raisin Company LLC, Aarav Agro Industries, Olam International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Grapes Market Emerging Trajectories
Processing technology and procurement patterns are diverging sharply between premium organic channels and commodity bulk supply, with digitization of traceability systems becoming the decisive competitive wedge.
Solar-assisted mechanical dehydration is electrifying smallholder operations previously dependent on unpredictable sun exposure. Turkish equipment suppliers are installing hybrid tunnel dryers powered by photovoltaic arrays and biomass burners. Boutique organic exporters in Afyon and Denizli provinces are capturing price premiums by guaranteeing 48-hour drying cycles regardless of weather.
EFSA's 2023 update to maximum residue limits for dried vine fruits is compressing the supplier base eligible for EU organic shelf placement. Non-EU exporters must now submit batch-level chromatography reports through the TRACES-NT portal. Iranian and Afghan processors lacking in-house laboratory capacity are losing direct access to German and Dutch importers.
Urban supermarkets are displacing traditional wholesale bazaar channels for household purchases across Middle Eastern and South Asian cities. Dubai's Lulu and Carrefour hypermarkets now stock 150g-250g stand-up pouches with resealable zippers. This format rotation favors processors with vertical bagging capability and branded packaging design resources over bulk exporters.
Dried Grapes Market Segmentation
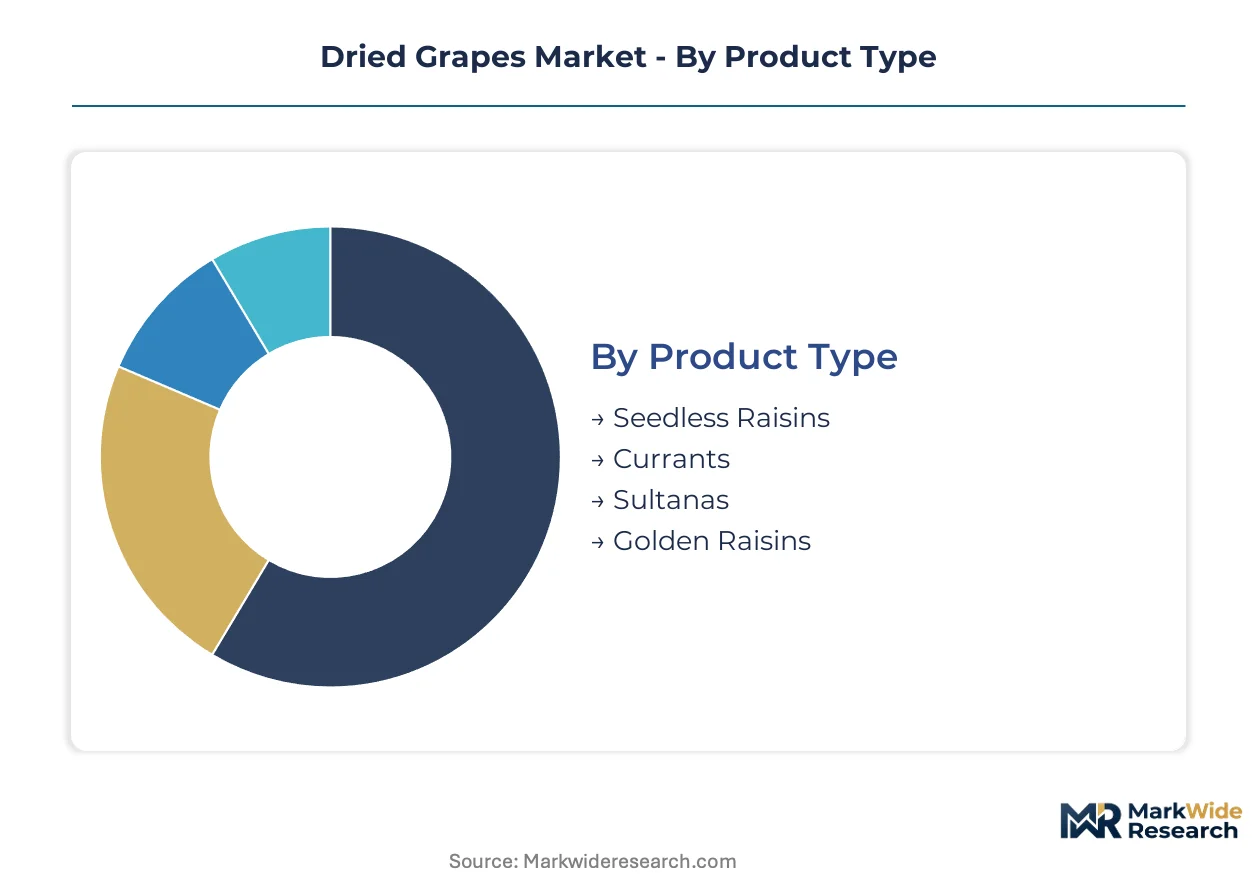
Segmentation in dried grapes reveals how processing specifications and packaging formats split procurement flows between industrial bulk buyers and branded retail channels. Each dimension carries distinct margin structures and regulatory exposure.
Product Type:
Supply concentration in Turkey's Aegean region shapes competitive dynamics across varietal categories.
- Seedless Raisins:Dehydrated Thompson Seedless berries with moisture below 16% and uniform berry size. California's San Joaquin Valley dominates feedstock supply, though Turkish reprocessors now absorb larger volumes for European industrial accounts seeking clean-label compatibility.
- Sultanas:Seedless white grapes dried to lighter amber color with softer texture profile. Manisa and Izmir processors command premium positioning in European bakery channels where color grading differentiates finished products; EFSA sulphur dioxide limits are compressing conventional processing economics.
- Currants:Small, dark, seedless Corinth variety dried to higher acidity. Greek Peloponnese and Aegean islands retain varietal specialization for UK and Nordic baking traditions.
- Golden Raisins:Sulfur-treated sultanas bleached to pale yellow appearance. Iranian and Afghan origins face phytosanitary documentation burdens at EU entry; demand concentrates in Middle Eastern confectionery applications.
Seedless raisins absorb the bulk of installed capacity; sultanas are expanding most quickly.
End User:
Customer type determines specification stringency and contract structure across the value chain.
- Food Manufacturers:Industrial buyers purchasing containerized bulk for cereal, dairy, and prepared meal integration. Olam International and similar traders sustain year-round supply through multi-origin procurement across Turkey, Iran, and Afghanistan.
- Bakeries:European industrial bakers drive clean-label reformulation, pulling untreated sultanas into dough and filling applications; residue documentation requirements intensify supplier qualification.
- Snack Producers:Trail mix and bar manufacturers favor portion-controlled formats with specified moisture and SO2 thresholds; organic certification premiums apply.
- Retail Consumers:Household purchasers shifting from wholesale bazaar channels to urban supermarkets in Middle Eastern and South Asian cities; resealable pouch formats displace loose bulk.
Food manufacturers absorb the bulk of installed capacity; retail consumers are expanding most quickly.
Packaging Type:
Format selection tracks channel evolution and shelf-life requirements.
- Bulk Bags:10-25kg woven polypropylene for industrial food manufacturing lines. Containerized shipments from Turkish Aegean ports dominate European import flows.
- Pouches:150-250g stand-up bags with resealable zippers for convenience retail. Dubai's Lulu and Carrefour hypermarkets favor this format; vertical bagging capability separates qualified processors from commodity exporters.
- Retail Packs:Pre-printed cardboard cartons and pillow bags for branded shelf placement. Sun-Maid Growers of California controls cooperative member supply for this channel.
- Tubs:Rigid plastic containers for food service and deli counters; limited volume share concentrated in North American and Australian markets.
Bulk bags absorb the bulk of installed capacity; pouches are expanding most quickly.
Distribution Channel:
Channel structure reflects urbanization patterns and regulatory proximity.
- Wholesale Distributors:Traditional import-export houses handling containerized bulk from Turkish, Iranian, and Afghan origins. EFSA's TRACES-NT portal requirements filter supplier eligibility.
- Supermarkets:Modern retail chains in Middle Eastern and South Asian cities displacing traditional bazaar channels; category management demands branded packaging and traceability documentation.
- Online Retailers:E-commerce platforms capturing subscription and bulk pantry demand; logistics favor shelf-stable, low-moisture products with extended ambient stability.
- Farmers' Markets:Direct producer sales of organic and heritage varieties; limited scale, concentrated in Mediterranean and California local food systems.
Wholesale distributors absorb the bulk of installed capacity; supermarkets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's San Joaquin Valley anchors global seedless raisin feedstock supply, though Turkish Aegean processors now absorb larger volumes for European industrial accounts. Manisa and Izmir provinces concentrate sultana processing capacity serving bakery channels across Germany, the Netherlands, and the United Kingdom.
United States
Fresno and Kern counties in California's Central Valley generate the bulk of Thompson Seedless raisin supply for domestic cereal and snack manufacturers. The USDA Agricultural Marketing Service administers federal marketing orders that stabilize handler inventories and grade standards. Sun-Maid Growers of California maintains cooperative control over member vineyards from Fresno north to Madera, securing branded retail shelf placement.
Turkey
Manisa and Izmir provinces in the Aegean region command premium sultana positioning in European bakery channels where lighter color and softer texture differentiate finished products. The Turkish Ministry of Agriculture and Forestry enforces export certification protocols that shape competitive access to Middle Eastern and South Asian markets. New controlled-atmosphere storage facilities in Salihli and Turgutlu are extending the export shipping season by four months.
Iran
Kashmar and Malayer districts specialize in golden raisin and sultana varieties for confectionery applications across the Gulf states and South Asia. The Iranian agriculture ministry mandates parallel export certification protocols that compete with Turkish documentation standards. EFSA's TRACES-NT portal requirements filter Iranian processor eligibility for direct German and Dutch importer relationships.
Germany
Industrial bakers in Bavaria and North Rhine-Westphalia drive clean-label reformulation, pulling untreated sultanas into dough and filling applications. The EU's Farm to Fork Strategy under EFSA oversight is tightening sulphur dioxide residue limits and reshaping import compliance requirements for Turkish and Iranian shipments. Hamburg and Rotterdam ports concentrate containerized bulk intake for redistribution to Central European food manufacturers.
United Kingdom
Currant demand for traditional baking applications sustains import flows from Greece's Peloponnese and Aegean islands. The UK Food Standards Agency applies retained EU maximum residue limits pending domestic regulatory divergence. London and Manchester distribution hubs handle wholesale redistribution to industrial bakeries and retail multiples.
Dried Grapes Market Vendor Landscape
Global majors compete with regional champions across procurement geography and processing scale. The vendor base fragments between California-based cooperatives controlling branded retail channels, Turkish Aegean processors dominating European bakery supply, and multi-origin traders sustaining year-round bulk availability. Three archetypes define competitive positioning: cooperative-integrated handlers with captive vineyard supply, specialist processors with varietal color-grading expertise, and diversified agri-traders with multi-origin procurement networks. Capacity expansion in controlled-atmosphere storage and backward integration into vineyard acquisition represent the dominant competitive moves.
Within the cooperative-integrated tier, Sun-Maid Growers of California exemplifies captive supply chain architecture through direct member vineyard control. Among multi-origin traders, Olam International Limited occupies a position spanning Turkish, Iranian, and Afghan procurement nodes to sustain European food manufacturer accounts. At the specialist processing end, National Raisin Company LLC represents varietal-specific expertise in seedless raisin handling for industrial bulk channels.
| Leading Market Players |
|---|
| Del Monte Pacific Limited |
| Stahmann Farms, Inc. |
| Sunsweet Growers Inc. |
| Dole Food Company |
| Sun-Maid Growers of California |
| Mariani Packing Company |
| National Raisin Company LLC |
| Aarav Agro Industries |
| Olam International Limited |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between organic-labeled sultanas and conventional seedless raisins manifests in both procurement premiums and supply chain traceability investments. EFSA's sulphur dioxide threshold compression forces exporters to maintain parallel processing lines and batch-level documentation systems, raising fixed cost absorption for premium tiers while commodity bulk channels compete on throughput scale.
Pricing Analysis
Documented residue testing and integrated pest management certification are bundled into organic-labeled sultana premiums, while conventional bulk shipments trade unbundled on spot markets. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA compliance depth, varietal color grading precision, and moisture specification stringency. Pricing pressure stems from California's consecutive short Thompson Seedless harvests tightening feedstock availability for Turkish reprocessors. Industrial food manufacturers exhibit highest price sensitivity due to volume contracting and multi-origin sourcing flexibility, while European artisanal bakers absorb premiums for untreated sultanas with verified provenance.
Supply Chain Analysis
Certified sultana color graders in Turkey's Manisa and Izmir provinces number fewer than two hundred, constraining peak-season intake capacity and forcing harvest scheduling around workforce availability. Supply concentrates in Turkey's Aegean region, California's San Joaquin Valley, and Iran's Kashmar district, with raw material flows drawing from Thompson Seedless vineyards, white grape varietals, and sulphur-treated golden raisin stocks. Single-source vulnerability runs through California's climate-exposed harvest cycles, which ripple through Turkish reprocessing economics. Distribution runs through Hamburg and Rotterdam port hubs for European industrial accounts, with Dubai's Lulu and Carrefour hypermarkets capturing Middle Eastern retail pouch demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's tightening residue documentation requirements are accelerating supplier base consolidation, eliminating smaller Iranian and Afghan processors lacking in-house laboratory capacity and forcing acquisition-driven scale plays among surviving competitors.
For Market Incumbents: Lock in multi-year procurement contracts with California cooperative members before Thompson Seedless supply volatility intensifies, while simultaneously retrofitting Aegean drying yards to polytunnel shade systems to secure organic conversion timelines. Backward integration into vineyard acquisition in Turkey's Afyon and Denizli provinces captures price premiums from boutique organic channels. For New Entrants and Emerging Players: Begin with single-serve pouch formats in Middle Eastern convenience retail, where urban supermarket displacement of traditional bazaar channels creates whitespace for vertical bagging capability investments. Target Dubai and Riyadh commuter snacking segments with 150g-250g stand-up pouches featuring resealable zippers, leveraging direct-to-hypermarket distribution partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with Aegean-based specialist processors possessing certified color-grading expertise and controlled-atmosphere storage infrastructure, given EFSA's TRACES-NT portal requirements filtering direct EU market access. Long-term viability over a five-to-ten-year window favors targets with organic conversion completion and backward vineyard integration. Monitor sulphur dioxide threshold reduction announcements as the decisive inflection signal for conventional processing economics collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Expansion | Manisa and Izmir facilities extend export shipping seasons by four months, capturing off-peak pricing premiums. |
| Organic Certification Conversion | Turkey's national subsidy program covering sixty percent of audit costs accelerates three-year transition timelines. |
| Multi-Origin Procurement Network | Traders sustaining year-round supply across Turkey, Iran, and Afghanistan hedge against California harvest volatility. |
| Vertical Bagging Capability Investment | Processors with in-house pouch production capture Middle Eastern retail format rotation from loose bulk. |
| Integrated Pest Management Documentation | Batch-level chromatography reporting through TRACES-NT secures German and Dutch importer direct relationships. |
Methodological Framework
Document review covered EFSA maximum residue limit updates, EU Farm to Fork Strategy implementation guidance, and Turkish Ministry of Agriculture export certification protocols, complemented by interviews with Aegean region sultana processors, California cooperative vineyard managers, and European industrial bakery procurement directors. Secondary validation drew from USDA Agricultural Marketing Service grade standards, customs trade data for containerized dried fruit flows, and hospital procurement databases for institutional food service accounts. Bottom-up volume modeling triangulated against top-down value estimates across the segmentation dimensions.
Segment-level outputs across product type, end user, packaging format, and distribution channel were generated through the analytical framework, with CAGRs derived from regression analysis of historical trade flows and elasticity-adjusted demand projections. Forecast inputs incorporated Thompson Seedless yield variance patterns, sulphur dioxide threshold compliance cost curves, and urban supermarket penetration rates in Middle Eastern and South Asian cities.
California drought recurrence, EFSA organic label threshold revision, and Turkish lira exchange volatility are the dominant revision risks to modeled projections. Material deviation in these triggers warrants pause and re-evaluation of capacity expansion timelines and procurement contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Global Fresh Berries Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Noni Fruit Powder Market