
 Cellulose Market | 2026-2036
Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Market Analysis
Pharmaceutical excipient demand is rebalancing the Cellulose Market end-use mix as oral solid dosage formulations expand. Lenzing AG anchors European supply through its dissolving wood pulp operations. Daicel Corporation specializes in cellulose acetate for cigarette filters and LCD optical films. Ashland competes in pharmaceutical-grade microcrystalline cellulose through controlled-release polymer technology.
Cellulose is a linear polysaccharide of β-1,4-linked D-glucose units with crystallinity ranging from 40% to 70% depending on source and processing, serving as a structural polymer in plants and a functional raw material across industrial applications. Microcrystalline cellulose dominates pharmaceutical-grade revenue owing to direct compressibility and inert excipient performance, while carboxymethyl cellulose captures expanding food and beverage thickening demand. Ethyl cellulose occupies the controlled-release coating niche with higher margin profiles than commodity grades.
FDA pharmaceutical excipient standards, EU REACH chemical registration requirements, and FAO/WHO food additive specifications collectively shape product purity thresholds and market access conditions across major demand centers. The EU Green Deal forest sourcing rules are tightening traceability requirements for wood-based cellulose feedstocks. Stakeholders must monitor regulatory divergence between pharmaceutical-grade certification regimes and emerging bioeconomy sustainability mandates to align capacity investments with compliant feedstock procurement.
Market Dynamics
Pharmaceutical-grade certification requirements and EU Green Deal forest traceability mandates are compressing supplier margins while redistributing value toward compliant dissolving pulp producers and excipient specialists.
Growth Catalysts
- Oral solid dosage expansion:Pharmaceutical manufacturers are scaling tablet and capsule production, pulling microcrystalline cellulose into higher-volume formulations.
- EU Green Deal sourcing rules:Mandatory chain-of-custody documentation for wood-based feedstocks is locking in certified suppliers and raising barriers for uncertified competitors.
- Food-grade hydrocolloid demand:Clean-label thickening applications in beverages and dairy are absorbing carboxymethyl cellulose at accelerated rates.
Market Restraints
- Dissolving pulp cost volatility:Hardwood and softwood pulp input prices swing with forestry harvest cycles and energy costs, squeezing derivative margins.
- REACH registration burdens:ECHA compliance costs for novel cellulose ethers block smaller chemical processors from European pharmaceutical supply chains.
- Synthetic polymer substitution:Polyvinylpyrrolidone and croscarmellose sodium alternatives threaten microcrystalline cellulose in certain tablet disintegration applications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO excipient registration pathways and PLI scheme incentives for active pharmaceutical ingredients create parallel demand for compliant cellulose grades.
- Controlled-release coating convergence:Ethyl cellulose paired with hot-melt extrusion equipment opens oncology and psychiatric drug delivery segments.
- Bioeconomy certification premiums:FSC and PEFC chain-of-custody documentation commands price premiums in EU and North American food packaging applications.
Industry Challenges
- Pharmaceutical-grade talent scarcity:Excipient formulation chemists with USP-NF and EP monograph expertise command premium wages and extended recruitment timelines.
- Multi-jurisdiction certification lag:Simultaneous FDA Drug Master File, EMA CEP, and CDSCO registration processes extend time-to-revenue by 18-24 months for new cellulose ether variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Market |
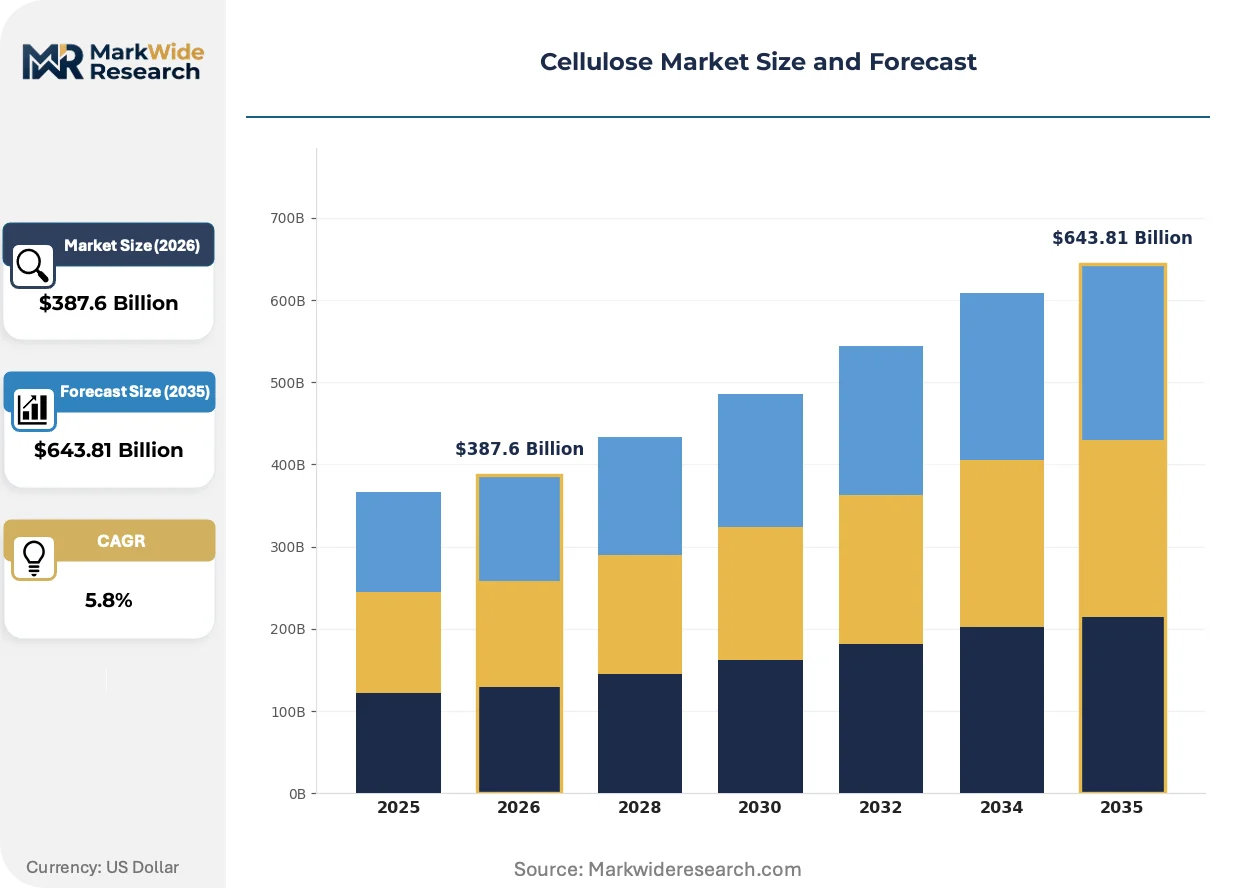
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcrystalline Cellulose, Filter Paper, Carboxymethyl Cellulose, Ethyl Cellulose End Use Industry: Pharmaceuticals, Food & Beverage, Textiles, Personal Care Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade Application: Thickening Agent, Stabilizer, Filler, Absorbent |
| Companies Covered | Shin-Etsu Chemical, Eastman Chemical Company, Dow, Daicel Corporation, Lenzing AG, Ashland, Borregaard, Aditya Birla Group, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Market Emerging Trajectories
Process intensification and sustainability verification are compressing traditional production economics while opening premium tiers for certified bio-based derivatives. Three forces are actively restructuring competitive positioning.
Regenerative solvent processing is absorbing energy and chemical inputs previously lost to conventional viscose and lyocell methods. Brazilian and Indonesian textile producers are piloting closed-loop N-methylmorpholine-N-oxide recovery systems at commercial scale. This technology is absorbing capital that would otherwise flow toward conventional kraft pulp expansion, tightening dissolving wood pulp availability for derivative markets.
REACH authorization requirements for formaldehyde-releasing crosslinkers are forcing reformulation of certain cellulose ether grades used in construction adhesives. German and French chemical distributors are accelerating substitution toward glyoxal-crosslinked alternatives ahead of 2026 sunset dates. Construction-grade methylcellulose and hydroxyethyl cellulose face the steepest compliance costs, with downstream mortar and tile adhesive manufacturers absorbing price increases or switching to starch-based thickeners.
Direct compressibility specifications from pharmaceutical contract manufacturers are tightening procurement criteria beyond basic USP-NF compliance. Indian and Chinese generic drug producers now require batch-to-batch dissolution variability below 3% for microcrystalline cellulose, a threshold only a subset of suppliers consistently meet. This specification creep is fragmenting the excipient vendor base into certified-tier and commodity-tier supply relationships, with purchasing consolidation around audited suppliers in Ahmedabad and Shanghai pharmaceutical manufacturing clusters.
Cellulose Market Segmentation
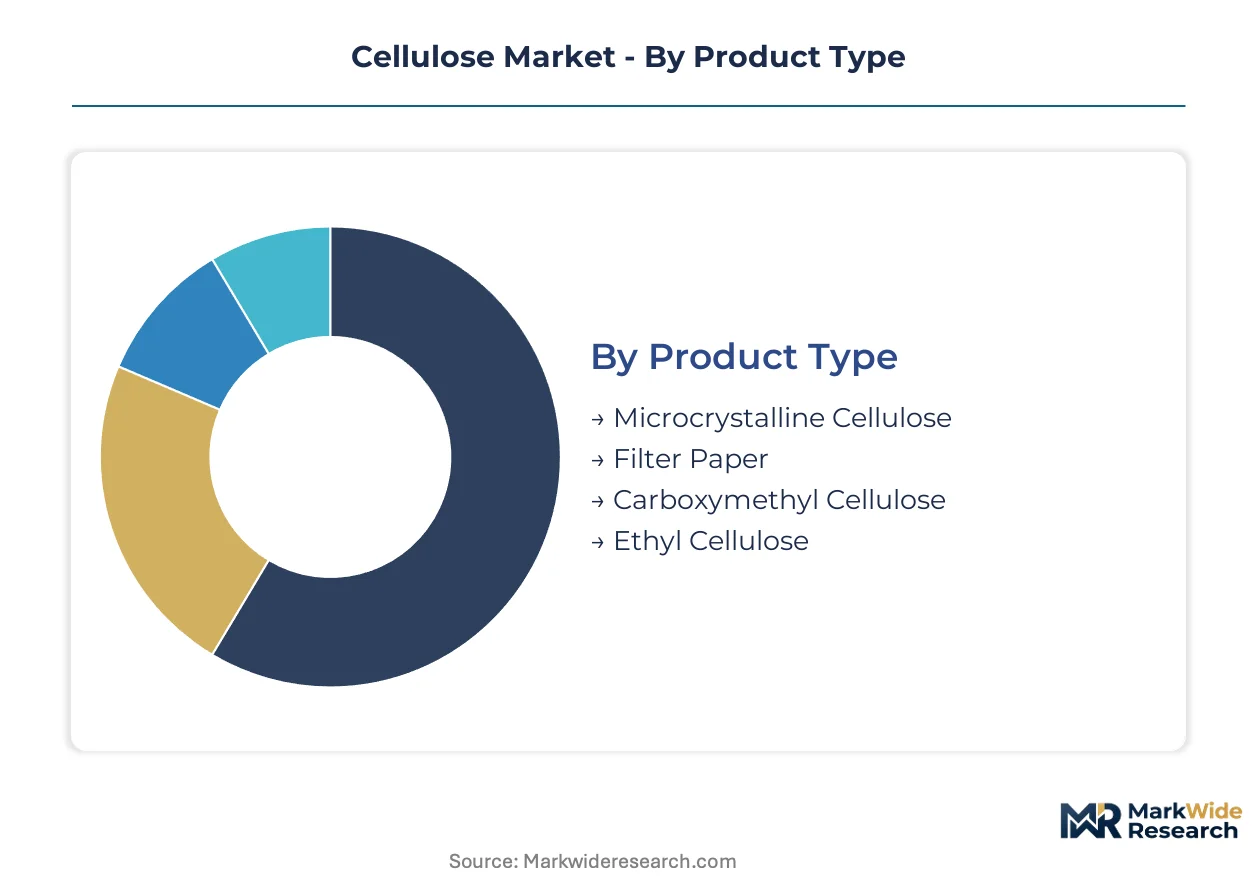
Cellulose derivatives exhibit divergent specification requirements across pharmaceutical, food, and industrial channels, with certification tiers and functional performance creating distinct procurement pools. Manufacturers must align production assets with grade-specific purity thresholds and end-use validation protocols to capture margin premiums.
Product Type:
Specification hierarchies separate pharmaceutical-grade excipients from commodity cellulose ethers based on crystallinity, particle size distribution, and substitution degree.
- Microcrystalline Cellulose:A depolymerized cellulose powder with 40-70% crystallinity and particle sizes of 20-100 microns, engineered for direct compressibility in tablet formulations. Demand concentrates in Indian and Chinese generic drug manufacturing clusters where CDSCO and NMPA registration requirements favor suppliers with USP-NF and EP monograph compliance. Batch-to-batch dissolution variability below 3% now functions as a procurement filter, fragmenting the vendor base.
- Carboxymethyl Cellulose:An anionic water-soluble ether with degree of substitution typically 0.7-1.2, delivering pseudoplastic rheology in food and beverage systems. Clean-label thickening applications in dairy alternatives and ready-to-drink beverages are absorbing volumes fastest in Brazil and Indonesia, where FSSAI and BPOM regulations align with EU food additive specifications.
- Filter Paper:High-purity alpha-cellulose sheets with controlled porosity for laboratory and industrial separation applications.
- Ethyl Cellulose:A thermoplastic ether with 44-50% ethoxyl content, forming moisture-barrier coatings for controlled-release pharmaceuticals.
Microcrystalline cellulose leads on scale; carboxymethyl cellulose leads on momentum.
End Use Industry:
Application-driven purity requirements create tiered pricing structures across regulated and unregulated demand channels.
- Pharmaceuticals:Oral solid dosage formulations require excipients meeting USP-NF, EP, and JP monograph standards with documented ICH Q3D elemental impurity profiles. FDA Drug Master File and EMA CEP registration processes extend supplier qualification timelines to 18-24 months, concentrating purchasing power among audited vendors in Ahmedabad, Shanghai, and Basel pharmaceutical manufacturing clusters.
- Food & Beverage:Hydrocolloid applications demand FAO/WHO JECFA-compliant grades with batch-level contaminant testing for heavy metals and microbial load. Clean-label positioning in European and North American markets is absorbing carboxymethyl cellulose and methylcellulose at accelerated rates as manufacturers replace modified starches and synthetic gums.
- Textiles:Viscose and lyocell fiber production consumes dissolving wood pulp with high alpha-cellulose content and controlled hemicellulose residuals.
- Personal Care:Microcrystalline cellulose functions as a physical exfoliant and rheology modifier in cosmetic formulations with less stringent purity requirements than pharmaceutical grades.
Pharmaceuticals commands the highest unit margins; food and beverage offers the steepest volume expansion trajectory.
Grade:
Certification depth determines market access and pricing power across regional regulatory regimes.
- Pharmaceutical Grade:Excipients manufactured under IPEC-PQG GMP guidelines with comprehensive elemental impurity testing and stability documentation. REACH registration through ECHA and CDSCO excipient master file requirements in India create compliance moats that sustain 40-60% price premiums over technical grades.
- Food Grade:Additives meeting FSSAI, FDA 21 CFR 182, and EFSA food additive specifications with HACCP-certified production. EU Green Deal forest sourcing rules are tightening chain-of-custody documentation requirements, locking in FSC and PEFC-certified suppliers.
- Industrial Grade:Construction and adhesive applications with performance-based specifications and minimal regulatory oversight.
- Technical Grade:Intermediate purities for chemical processing and non-food industrial uses where cost minimization dominates procurement criteria.
Pharmaceutical grade leads on margin; food grade leads on regulatory-driven sourcing consolidation.
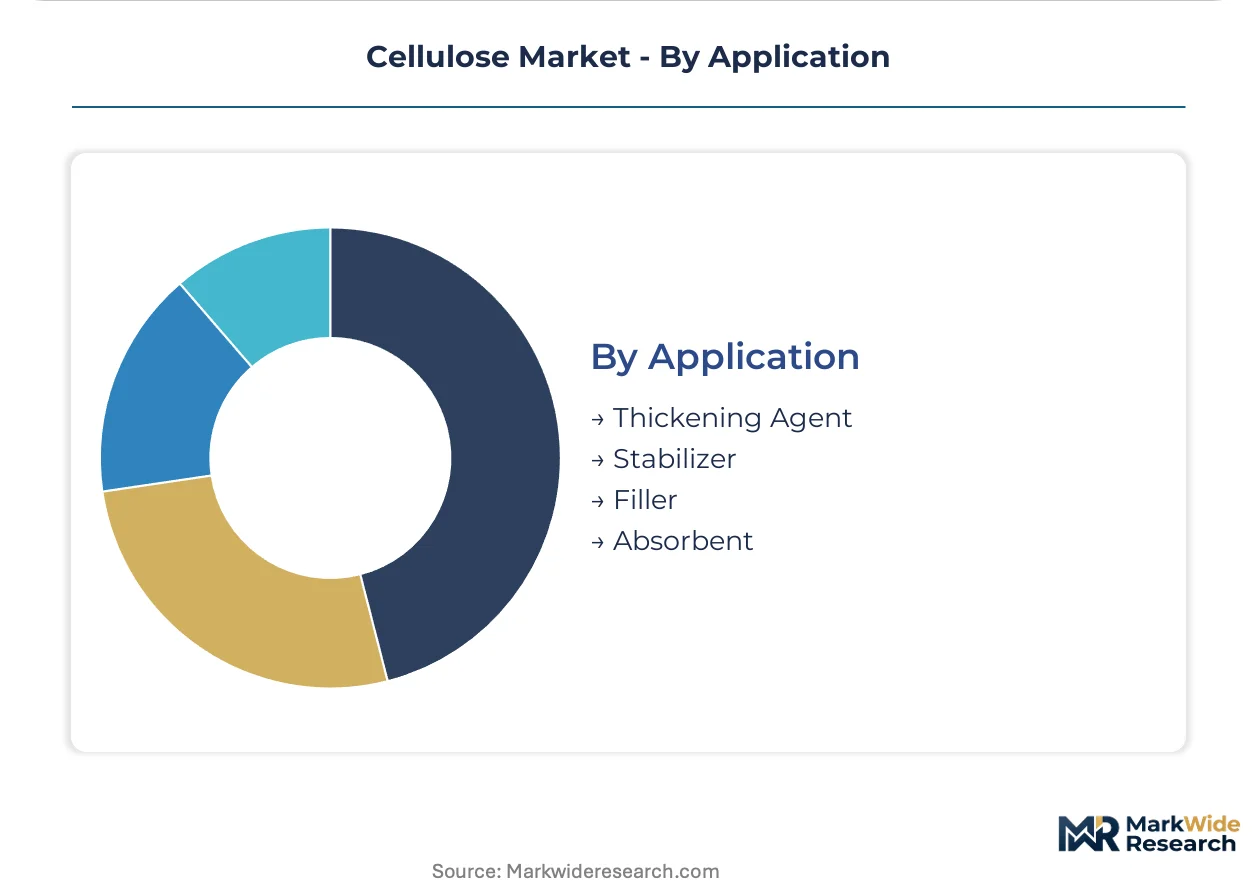
Application:
Functional performance requirements separate premium excipient positions from commodity chemical roles.
- Thickening Agent:Carboxymethyl cellulose and methylcellulose deliver shear-thinning viscosity in food, pharmaceutical, and industrial systems. Beverage and dairy applications in China and India are absorbing food-grade hydrocolloids as clean-label formulations displace xanthan gum and synthetic polymers.
- Stabilizer:Microcrystalline cellulose and cellulose ethers prevent phase separation in emulsions and suspensions through colloidal network formation.
- Filler:Inert bulking agents in tablet and capsule formulations where direct compressibility and flow properties determine processing economics.
- Absorbent:High-surface-area cellulose fibers in personal care, medical, and industrial spill-control applications with lower purity requirements than pharmaceutical channels.
Thickening agent applications are climbing the fastest; filler applications anchor current volume bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing cellulose derivative capacity toward jurisdictions with streamlined excipient registration pathways and lower compliance-cost structures. Producers are relocating pharmaceutical-grade manufacturing to India and China while maintaining EU-facing production in Austria and Germany to satisfy EU Green Deal traceability mandates.
China
Domestic pharmaceutical manufacturing expansion is absorbing microcrystalline cellulose at volumes that strain certified supplier capacity. NMPA excipient registration requirements now align with ICH Q3D elemental impurity standards, extending qualification timelines for imported grades. Shanghai and Jiangsu province pharmaceutical manufacturing clusters are consolidating purchasing around audited vendors with documented USP-NF compliance.
India
CDSCO excipient master file pathways and PLI scheme incentives for active pharmaceutical ingredients are creating parallel demand for compliant cellulose grades. Ahmedabad and Hyderabad pharmaceutical manufacturing hubs now require batch-to-batch dissolution variability below 3% for microcrystalline cellulose, fragmenting the vendor base into certified-tier and commodity-tier supply relationships.
Germany
EU REACH authorization requirements for formaldehyde-releasing crosslinkers are forcing construction-grade cellulose ether reformulation ahead of 2026 sunset dates. ECHA compliance costs for novel cellulose ethers block smaller chemical processors from pharmaceutical supply chains. Baden-Württemberg and North Rhine-Westphalia chemical distributors are accelerating substitution toward glyoxal-crosslinked alternatives.
United States
FDA Drug Master File registration processes extend supplier qualification timelines to 18-24 months, concentrating purchasing power among audited vendors. EPA oversight of forestry feedstock sourcing intersects with state-level procurement preferences for FSC-certified materials. New Jersey and Massachusetts pharmaceutical manufacturing clusters are locking in certified dissolving pulp suppliers to secure compliant cellulose derivative supply chains.
Brazil
Clean-label thickening applications in dairy alternatives and ready-to-drink beverages are absorbing carboxymethyl cellulose at accelerated rates. ANVISA regulations align with FAO/WHO JECFA specifications for food-grade hydrocolloids. São Paulo state food and beverage manufacturers are displacing modified starches and synthetic gums with cellulose-based alternatives to capture export market access.
Cellulose Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification creating tiered supply relationships that favor audited vendors over commodity producers. The vendor base concentrates around dissolving pulp producers with captive cellulose derivative capacity and independent excipient specialists with documented regulatory compliance. Three archetypes dominate: integrated forest-products conglomerates with backward control over wood pulp supply, pharmaceutical-grade excipient specialists with multi-jurisdiction registration portfolios, and regional chemical processors serving construction and food-grade applications. Capacity expansion and strategic partnerships represent the dominant competitive moves, as producers seek to secure compliant feedstock access and accelerate time-to-revenue for new product registrations.
Within the integrated forest-products tier, Lenzing AG and Borregaard exemplify producers with captive dissolving pulp operations and downstream cellulose derivative manufacturing. Among pharmaceutical-grade specialists, Ashland and Daicel Corporation occupy positions defined by USP-NF and EP monograph compliance with documented ICH Q3D elemental impurity profiles. These named entities represent archetypal competitive positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Shin-Etsu Chemical |
| Eastman Chemical Company |
| Dow |
| Daicel Corporation |
| Lenzing AG |
| Ashland |
| Borregaard |
| Aditya Birla Group |
| Celanese Corporation |
| Others |
Supply Flow & Price Mechanics
Excipient formulation chemists with USP-NF and EP monograph expertise concentrate in Basel and Baden-Württemberg, where labor-cost differentials of 40-60% separate pharmaceutical-grade premium tiers from technical-grade commodity supply. This workforce geography compresses margins for uncertified producers while amplifying pricing power for audited vendors with documented ICH Q3D compliance.
Pricing Analysis
Distributor margins on pharmaceutical-grade microcrystalline cellulose run 15-25% above technical-grade channels, with three-tier pricing structure across premium, standard, and economy levels anchored by certification depth rather than volume scale. Price differentiation rests on FDA Drug Master File registration status and EU REACH authorization completeness, with CDSCO-registered grades commanding intermediates between USP-NF and uncertified technical supply. Pricing pressure stems from synthetic polymer substitution in tablet disintegration applications, where croscarmellose sodium and polyvinylpyrrolidone erode share in cost-sensitive generic drug manufacturing. Construction-grade methylcellulose buyers exhibit highest price sensitivity, while oncology-focused ethyl cellulose purchasers prioritize batch-to-batch dissolution consistency over unit cost.
Supply Chain Analysis
Workforce availability for closed-loop N-methylmorpholine-N-oxide recovery systems concentrates in São Paulo state and East Java province, where Brazilian and Indonesian textile producers pilot commercial-scale lyocell operations. Geographic supply concentration centers on Austria, Germany, and China for dissolving wood pulp, with India and Brazil expanding derivative manufacturing capacity. Raw material dependencies include hardwood and softwood pulp, formaldehyde and glyoxal crosslinkers, and acetic anhydride for cellulose acetate production. Supply chain risk manifests in EU Green Deal forest traceability mandates, which threaten feedstock access for uncertified processors. Distribution runs through pharmaceutical manufacturing clusters in Ahmedabad, Shanghai, and New Jersey, where audited vendor consolidation limits channel access for new entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cellulose derivatives hinges on certification-premium capture and dissolving pulp cost compression through captive supply integration. Clean-label positioning and controlled-release coating convergence create parallel premium-tier shifts across food and pharmaceutical channels.
For Market Incumbents: Deepen backward integration into FSC-certified dissolving pulp operations to secure EU Green Deal-compliant feedstock access ahead of 2026 traceability enforcement. Expand ethyl cellulose capacity for oncology drug delivery partnerships, where hot-melt extrusion equipment convergence locks in multi-year supply agreements. Prioritize CDSCO excipient master file maintenance in India to defend against emerging regional chemical processors with lower compliance-cost structures.
For New Entrants and Emerging Players: Begin with carboxymethyl cellulose supply to Brazilian and Indonesian clean-label beverage manufacturers, where FSSAI and BPOM alignment with EU specifications creates certification arbitrage opportunities. Target construction-grade hydroxyethyl cellulose substitution demand in Germany and France, where REACH authorization deadlines for formaldehyde-releasing crosslinkers force reformulation ahead of sunset dates. Pursue toll manufacturing partnerships with established dissolving pulp producers to bypass capital-intensive captive pulp requirements.
For Investors and Strategic Acquirers: Integrated forest-products conglomerates with captive dissolving pulp operations are the most active acquirer in this space, seeking pharmaceutical-grade excipient specialists to complete vertical coverage. Long-term viability favors producers with multi-jurisdiction registration portfolios spanning FDA, EMA, and CDSCO pathways, as generic drug manufacturing expansion in India and China sustains compliant-grade demand. Monitor glyoxal-crosslinked cellulose ether adoption rates in European construction adhesives as inflection indicator for formaldehyde-free formulation transition speed.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Dissolving Pulp | EU Green Deal traceability mandates lock in FSC and PEFC feedstock access for derivative manufacturers. |
| CDSCO Excipient Master File Registration | PLI scheme incentives for active pharmaceutical ingredients create parallel demand for compliant cellulose grades in India. |
| Glyoxal-Crosslinked Ether Capacity Expansion | REACH authorization deadlines for formaldehyde-releasing crosslinkers force construction adhesive reformulation in Germany. |
| Hot-Melt Extrusion Equipment Partnerships | Ethyl cellulose paired with controlled-release coating technology opens oncology and psychiatric drug delivery segments. |
| Closed-Loop NMMO Recovery System Deployment | Brazilian and Indonesian textile producers absorb capital previously directed toward conventional kraft pulp expansion. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with excipient formulation chemists, pharmaceutical procurement managers at CDSCO-registered manufacturers, dissolving pulp operations directors, and construction adhesive R&D leads with secondary validation. Trade data from customs authorities, SEC filings from listed chemical producers, ECHA REACH registration databases, and FAO/WHO JECFA food additive specifications anchored supply-side assessment. Bottom-up capacity modeling and top-down demand triangulation from pharmaceutical and food formulation trends converged on segment-level projections.
Segment-weighting across product type, end-use industry, grade certification tier, and application function drove analytical framework construction over the projection horizon. Microcrystalline cellulose, carboxymethyl cellulose, and ethyl cellulose volumes were modeled separately against oral solid dosage expansion, clean-label hydrocolloid absorption, and controlled-release coating convergence. CAGRs derived from regression against historical pharmaceutical production indices and food additive registration trajectories, with dissolving pulp cost volatility and synthetic polymer substitution risk incorporated as scenario variables.
Several conditions sit outside the modeled scope, including abrupt REACH authorization timeline acceleration, catastrophic forestry supply disruption from climate events, and breakthrough synthetic excipient technologies displacing cellulose in core applications. Forecasts reflect assumptions about regulatory stability and certification pathway continuity. Material deviation in EU Green Deal enforcement intensity or CDSCO registration pathway streamlining warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Down and Feather Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Jute Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Silk Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Modal Fiber Market