
 Digital Camlock Market | 2026-2036
Digital Camlock Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Camlock Market Insights
A shift from single-source mechanical supply to multi-source electronic procurement is decoupling traditional vendor relationships across industrial security. ASSA ABLOY leverages its transatlantic manufacturing footprint to sustain bulk contract positions. Southco anchors aerospace and transportation verticals with specialized latching know-how. EMKA competes through modular platform architectures that reduce client integration costs.
Digital camlocks are electromechanical fastening devices that integrate motorized bolt actuation with credential verification, typically rated for IP65 environmental sealing and cycle counts exceeding 100,000 operations, serving industries requiring remote access audit trails and tamper-evident sealing. Smart locks lead product type expansion as facility managers prioritize mobile credentialing and real-time monitoring, while RFID technology claims the deepest installed base among credential formats due to its reliability in metal-rich industrial environments. Wireless locks represent the fastest-growing technology segment, though margin pools remain concentrated in biometric-enabled units for high-security government applications.
FDA facility security requirements, IEC 62443 industrial cybersecurity standards, and NIST SP 800-53 access control frameworks collectively shape product certification roadmaps and procurement eligibility for digital camlock vendors. The EU Cyber Resilience Act adds conformity obligations for connected locking devices sold into European industrial infrastructure. Stakeholders must weigh credential interoperability against the fragmentation of regional compliance regimes when selecting platform architectures.
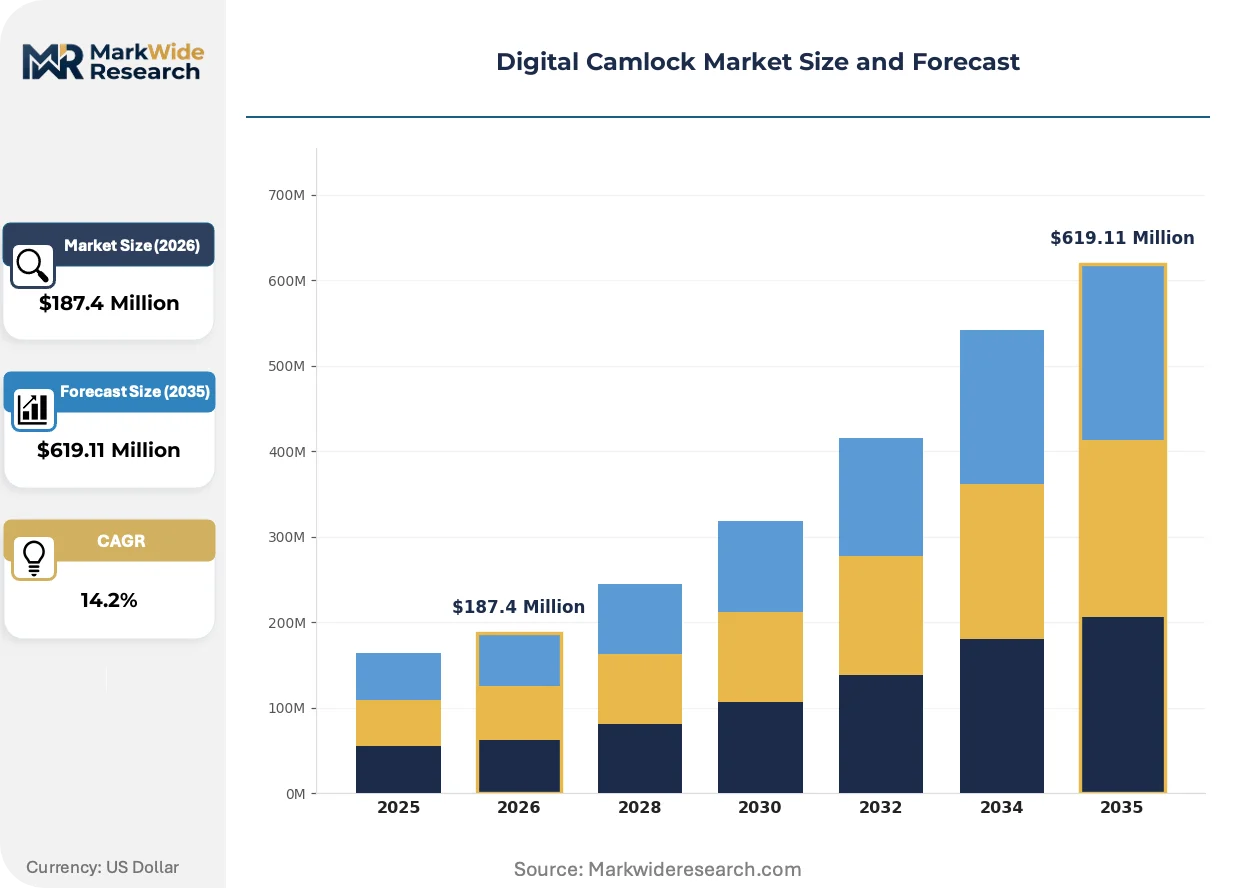
Market Dynamics
The transition from mechanical to electromechanical access control is restructuring vendor relationships and procurement patterns across industrial security infrastructure, with cybersecurity certification requirements now filtering supplier eligibility before price negotiation begins.
Growth Catalysts
- IEC 62443 compliance mandates:Industrial facilities in Germany and the Netherlands now require certified electronic locking for critical infrastructure access, forcing hardware replacement cycles that favor digital camlock vendors with pre-certified platforms.
- Mobile credentialing adoption:Facility managers in chemical processing and oil terminal operations are prioritizing smartphone-based access over physical key distribution, reducing administrative overhead and enabling real-time credential revocation.
- Tamper-evident sealing requirements:FDA facility security guidelines for pharmaceutical manufacturing are driving demand for audit-trail-capable locking systems that log every access event with cryptographic verification.
Market Restraints
- Semiconductor supply concentration:Motor driver ICs and secure microcontrollers for electromechanical actuation remain concentrated among Taiwanese and South Korean foundries, exposing lead time volatility for camlock manufacturers.
- Legacy mechanical installed base:Decades of standardized mechanical camlock deployment in rail and marine applications creates path dependency, with capital allocation committees reluctant to fund wholesale electronic retrofits without regulatory pressure.
- RFID credential cost structure:Metal-rich industrial environments require ruggedized RFID tags at price points that erode margin pools for mid-volume deployments, compressing achievable pricing in transportation verticals.
Strategic Opportunities
- EU Cyber Resilience Act tailwinds:Connected locking devices sold into European industrial infrastructure face new conformity obligations that favor vendors with pre-established cybersecurity documentation, creating barriers for late entrants.
- Biometric-credential convergence:Fingerprint and palm-vein modules are dropping below cost thresholds that enable their integration into camlock housings previously limited to card or token formats, opening high-security government applications.
- Wireless retrofit channels:Battery-powered wireless locks with Wi-Fi or Bluetooth backhaul are penetrating brownfield facilities through distributor networks that bypass traditional mechanical locksmith relationships, reshaping go-to-market economics.
Industry Challenges
- Cybersecurity engineering talent scarcity:Firmware development for secure boot and encrypted credential storage requires specialized embedded security expertise that competes with broader IoT and automotive hiring pools.
- Multi-standard certification timelines:Simultaneous pursuit of NIST SP 800-53, IEC 62443, and CE marking creates documentation burdens that extend product launch cycles by twelve to eighteen months.
- Legacy system integration complexity:Digital camlocks must interface with incumbent building management systems and physical access control platforms through proprietary protocols, requiring custom middleware development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Camlock Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Locks, Electronic Locks, Smart Locks, Wireless Locks Application: Industrial Equipment, Security Systems, Transportation, Residential Security End User: Manufacturers, Security Service Providers, Government Facilities, Homeowners Technology: Biometric, RFID, Bluetooth, Wi-Fi |
| Companies Covered | ASSA ABLOY, Southco, EMKA, Lowe & Fletcher, Dirak, Kerong, Wangtong Locks, Sinox, Make, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Camlock Market Trends and Innovations
Electromechanical locking is absorbing capabilities from adjacent security and automation domains, compressing the traditional boundary between physical access control and industrial cybersecurity infrastructure.
Biometric authentication modules are embedding directly into camlock housings, eliminating separate credential readers and reducing installation footprint. Pharmaceutical manufacturers and defense contractors are piloting fingerprint-enabled units for cleanroom and classified facility access. This hardware integration is converging with mobile credentialing platforms, compressing the distinction between something-you-have and something-you-are verification methods.
NIST SP 800-53 revision cycles are tightening access control requirements for federal facilities and their contractors, mandating multifactor authentication for all high-security areas. Industrial vendors serving government-adjacent markets must now document supply chain provenance and firmware update mechanisms to maintain procurement eligibility. Defense and aerospace segments are responding by pre-qualifying platforms with FedRAMP-adjacent documentation before competitive bidding begins.
Buying committees are unbundling hardware procurement from installation and maintenance contracts, treating digital camlocks as standardized commodities rather than integrated security solutions. Industrial distributors are capturing margin previously held by systems integrators by offering direct-to-facility configuration services. This pattern is most visible in German manufacturing clusters, where automation density supports in-house security engineering teams that specify and install hardware without external integration support.
Digital Camlock Market Segmentation
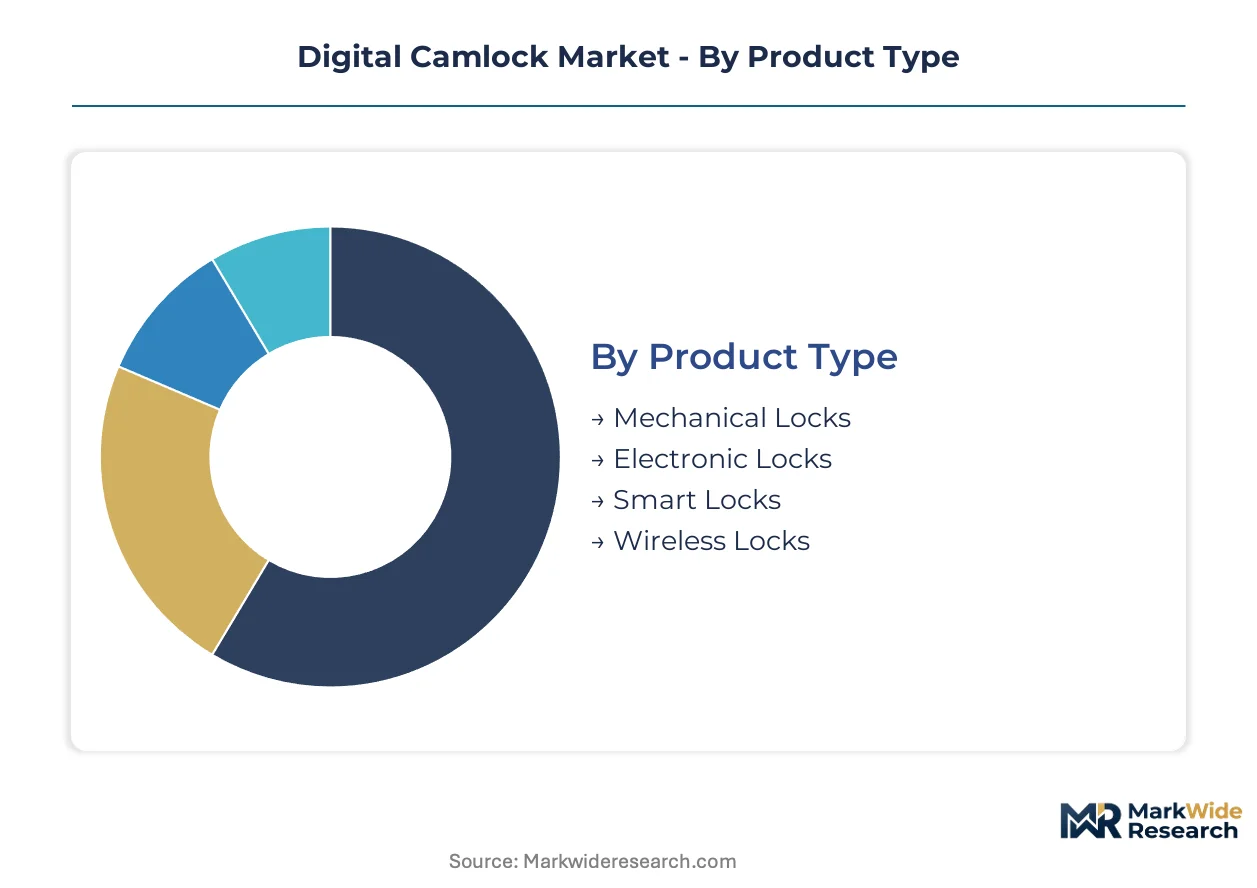
Digital camlock segmentation reveals divergent margin profiles across electromechanical complexity tiers. Procurement committees weight credential interoperability against retrofit feasibility when allocating capital across product categories.
Product Type:
Volume concentration sits with legacy mechanical units, while premium capture belongs to credential-enabled electronic platforms.
- Smart Locks:Smartphone-native credentialing with Bluetooth or NFC backhaul enables real-time revocation and audit logging. Pharmaceutical manufacturers in Germany prioritize these for FDA-compliant facility access where cryptographic verification is mandatory.
- Electronic Locks:Motorized bolt actuation paired with RFID or keypad entry, typically IP65-rated for industrial environments. Oil terminal operators in the Netherlands specify these for IEC 62443-compliant critical infrastructure access.
- Wireless Locks:Battery-powered units with Wi-Fi mesh backhaul penetrating brownfield facilities through distributor retrofit channels.
- Mechanical Locks:Legacy cam-and-tumbler designs dominating rail and marine installed bases where capital committees resist electronic conversion without regulatory pressure.
Mature deployment sits with Mechanical Locks. Newer deployment is concentrated in Smart Locks.
Application:
Margin pools cluster where tamper-evident sealing intersects with regulatory audit requirements.
- Industrial Equipment:Electromechanical fastening for enclosures, panels, and machinery guarding requiring 100,000+ cycle durability. Chemical processing plants drive specification for IP-rated sealing and remote monitoring integration.
- Security Systems:Perimeter and interior access points demanding credential verification with centralized logging. Government contractors prioritize these for NIST SP 800-53 multifactor compliance.
- Transportation:Fleet vehicle compartments and cargo containers where ruggedized RFID tags withstand vibration and temperature extremes.
- Residential Security:Consumer-grade smart home integration with mobile app control, representing the lowest ASP tier.
Revenue concentration favors Industrial Equipment. Steepest expansion trajectory belongs to Security Systems.
End User:
Procurement authority separates specification-heavy industrial buyers from price-sensitive residential consumers.
- Government Facilities:Federal and defense installations requiring FedRAMP-adjacent documentation, supply chain provenance, and firmware update mechanisms. NIST revision cycles mandate multifactor authentication for high-security zones.
- Manufacturers:Industrial automation clusters with in-house security engineering teams that self-install hardware without integrator support, particularly dense in German manufacturing regions.
- Security Service Providers:Systems integrators losing margin to distributor direct-to-facility configuration services as buying committees unbundle hardware from installation contracts.
- Homeowners:Retail-channel purchasers prioritizing smartphone compatibility over industrial-grade durability.
Specification authority rests with Government Facilities. Volume scaling occurs through Manufacturers.
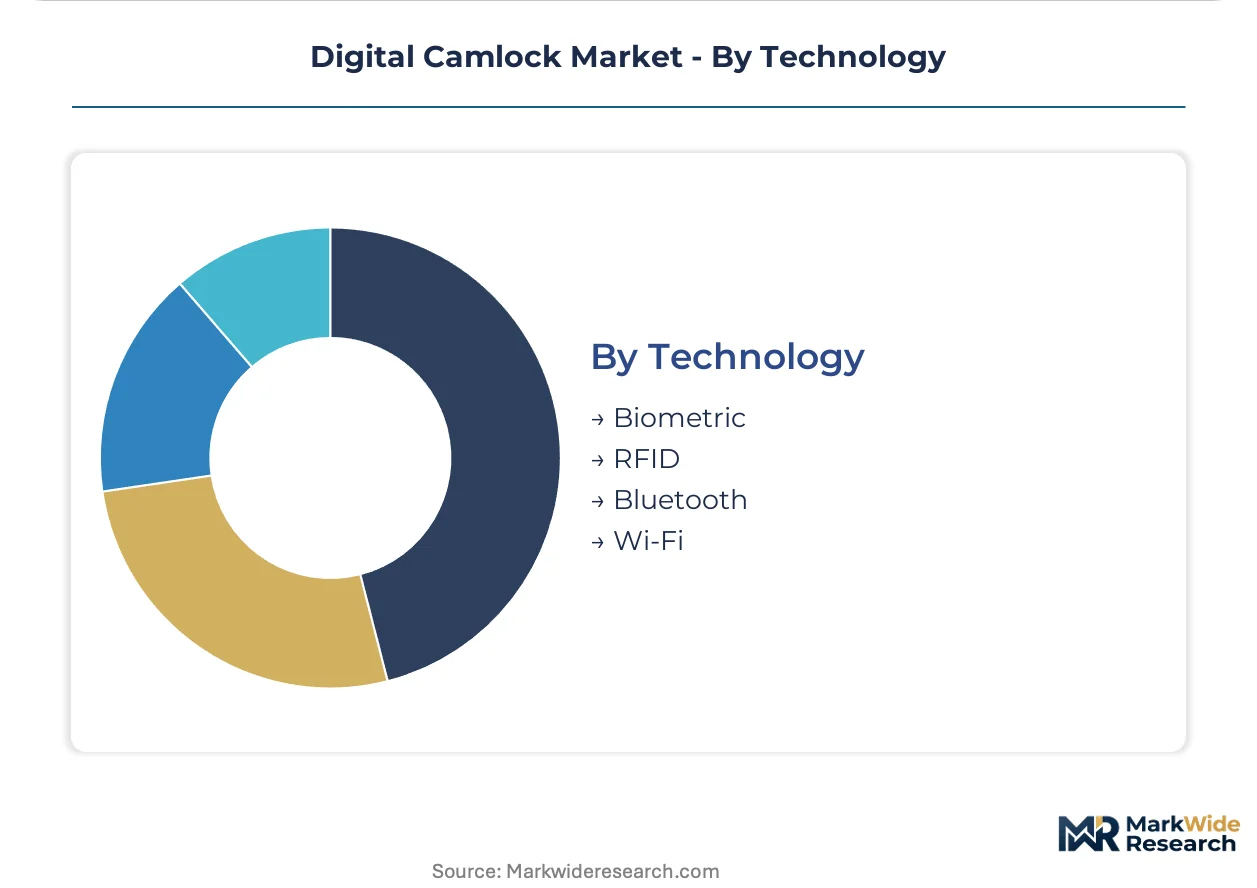
Technology:
Credential format selection trades interoperability breadth against metal-environment reliability.
- RFID:Contactless proximity cards and tokens with proven performance in metal-rich industrial environments. Holds the deepest installed base among credential formats due to electromagnetic interference tolerance.
- Biometric:Fingerprint and palm-vein modules dropping below cost thresholds for camlock housing integration. Defense contractors pilot these for classified facility access where token loss is unacceptable.
- Bluetooth:Low-energy beacon protocols enabling smartphone credentialing with reduced power consumption versus Wi-Fi alternatives.
- Wi-Fi:Direct network backhaul eliminating gateway dependencies but demanding higher battery capacity and cybersecurity hardening.
Installed base dominance belongs to RFID. Emerging specification favors Biometric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and semiconductor feedstock localities in Taiwan and South Korea anchor electromechanical component supply for digital camlock manufacturing. Industrial automation density in Germany and chemical processing infrastructure in the Netherlands drive premium hardware procurement. Regulatory pressure from IEC 62443 and FDA facility security requirements is accelerating replacement cycles across North American and European industrial clusters.
Germany
Industrial automation density in Bavaria and Baden-Württemberg supports premium digital locking adoption for machinery guarding and enclosure access. IEC 62443 compliance mandates from the country's federal cybersecurity framework force hardware replacement cycles in critical infrastructure. Stuttgart's manufacturing cluster exhibits strong specification authority for electromechanical fastening systems with remote audit capabilities.
United States
FDA facility security requirements for pharmaceutical manufacturing drive demand for tamper-evident sealing with cryptographic verification. NIST SP 800-53 revision cycles mandate multifactor authentication for federal contractors and high-security zones. Houston's oil terminal operators and New Jersey's chemical processing corridor prioritize mobile credentialing over physical key distribution.
Netherlands
Rotterdam's port infrastructure and chemical processing plants require IEC 62443-certified electronic locking for critical infrastructure access points. The country's national cybersecurity authority enforces conformity assessment for connected industrial devices. Eindhoven's high-tech manufacturing cluster sources pre-certified platforms that reduce procurement qualification timelines.
China
GB standards for industrial cybersecurity and smart manufacturing infrastructure shape domestic certification roadmaps for electromechanical access control. MIIT guidelines on connected device security create compliance obligations for facility automation vendors. Yangtze River Delta manufacturing clusters integrate digital camlocks into brownfield retrofit programs for machinery modernization.
Japan
METI industrial cybersecurity guidelines and JIS standards for factory automation equipment influence product specifications for electromechanical locking. Pharmaceutical manufacturers in Kansai pilot biometric-enabled units for cleanroom access where token loss is unacceptable. Nagoya's automotive component suppliers specify IP65-rated hardware with 100,000+ cycle durability for production line enclosures.
Digital Camlock Market Competitive Landscape
Global majors compete with regional champions across certification depth and industrial vertical specialization. The vendor base stratifies between transatlantic manufacturing footprints, modular platform architectures, and aerospace-specific latching expertise. Three archetypes dominate: electromechanical generalists with pre-certified cybersecurity documentation, vertical specialists with transportation or defense credentials, and Asian fabricators with cost-optimized wireless retrofit offerings. Competitive moves concentrate on strategic partnerships for middleware development and geographic expansion through distributor retrofit channels.
Within the electromechanical generalist tier, ASSA ABLOY and EMKA exemplify divergent approaches to platform standardization. ASSA ABLOY leverages its transatlantic manufacturing footprint to sustain bulk contract positions across pharmaceutical and oil terminal verticals. EMKA competes through modular platform architectures that reduce client integration costs and accelerate deployment timelines. Southco anchors the aerospace and transportation specialist archetype, occupying a position where specialized latching know-how commands premium positioning in fleet vehicle and cargo container applications.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Southco |
| EMKA |
| Lowe & Fletcher |
| Dirak |
| Kerong |
| Wangtong Locks |
| Sinox |
| Make |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Germany and the Netherlands anchor premium pricing discipline through long-term service contracts that bundle firmware updates with hardware procurement, insulating certified platforms from commodity erosion while Taiwanese and South Korean foundry concentration in motor driver ICs creates asymmetric cost pressure on unintegrated assemblers.
Pricing Analysis
Warranty and service-bundling separates three-tier pricing structure across premium, standard, and economy levels, with IEC 62443-certified units commanding sustained premiums against uncertified alternatives while customization for pharmaceutical cleanroom applications drives price differentiation through validation documentation and cryptographic audit-trail capabilities. Cost compression in economy-tier mechanical retrofits is intensifying because distributor direct-to-facility channels bypass traditional integrator markups. Government facilities exhibit least price sensitivity due to FedRAMP-adjacent compliance requirements, while residential homeowners demonstrate highest elasticity.
Supply Chain Analysis
Motor driver IC supply rests on Taiwanese and South Korean foundries, with secure microcontroller production similarly concentrated in East Asian semiconductor fabrication, creating single-source vulnerability exposure for European and North American camlock assemblers lacking captive wafer capacity. Hardened steel for electromechanical housings sources from German and Japanese specialty mills, while IP65-rated sealing gaskets draw from Chinese polymer processors. Distribution runs through industrial automation distributors in Germany and safety equipment channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as multi-standard certification timelines extending twelve to eighteen months force capital-constrained regional assemblers toward exit, creating acquisition opportunities for platforms with pre-established NIST and IEC documentation.
For Market Incumbents: Cement certification moats by accelerating FedRAMP-adjacent documentation for defense-adjacent verticals before competitive bidding cycles commence, while acquiring distressed wireless retrofit specialists in the Netherlands to capture brownfield distributor channels. Biometric-credential convergence from Chinese module suppliers threatens premium positioning unless firmware update mechanisms demonstrate supply chain provenance. For New Entrants and Emerging Players: Industrial automation distributors in Germany's Baden-Württemberg cluster offer the most penetrable channel for battery-powered wireless locks with Wi-Fi mesh backhaul, bypassing entrenched mechanical locksmith relationships. Target pharmaceutical manufacturers seeking FDA-compliant tamper-evident sealing with cryptographic verification, positioning against legacy electronic lock vendors through simplified middleware integration and smartphone-native credentialing. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular platform architects with pre-certified cybersecurity documentation in German industrial clusters, where automation density supports in-house security engineering teams that self-install hardware without integrator support. Watch for IEC 62443 enforcement acceleration in Dutch chemical processing infrastructure as the inflection indicator for premium hardware procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | Pre-certification to IEC 62443 and NIST SP 800-53 secures procurement eligibility before price negotiation begins in federal and pharmaceutical verticals. |
| Biometric Module Integration | Fingerprint and palm-vein embedding into camlock housings opens high-security government applications where token loss is operationally unacceptable. |
| Wireless Retrofit Channel Development | Battery-powered Wi-Fi and Bluetooth locks penetrate brownfield facilities through distributor networks that displace traditional mechanical locksmith relationships. |
| Modular Platform Architecture | Standardized middleware interfaces reduce client integration costs and accelerate deployment timelines for chemical processing and oil terminal operators. |
| Regional Manufacturing Footprint Expansion | Transatlantic production capacity sustains bulk contract positions across pharmaceutical clusters in New Jersey and oil terminals in Houston. |
Research Methodology
Independent corroboration across facility security directors at pharmaceutical manufacturers, procurement leads at Dutch chemical processing plants, and channel managers at German industrial automation distributors underwrites the qualitative findings, with secondary validation drawing from FDA facility security guideline revisions, IEC 62443 certification registries, and NIST SP 800-53 access control framework updates. Bottom-up demand modeling from end-user specification patterns triangulates against top-down supply-side capacity assessments across Taiwanese foundries and German steel mills.
Comparable-period anchoring to historical hardware replacement cycles in rail and marine mechanical installed bases establishes baseline elasticity assumptions across the projection horizon, with segmentation modeling spanning smart lock, electronic lock, wireless lock, and mechanical lock product types alongside RFID, biometric, Bluetooth, and Wi-Fi credential technologies. CAGRs derive from installed base penetration rates and regulatory compliance mandate acceleration, incorporating motor driver IC lead time volatility and cybersecurity engineering talent scarcity as industry-specific forecast inputs.
Caveats apply where semiconductor supply concentration in Taiwanese and South Korean foundries or accelerated NIST revision cycles could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market