
 China Protective Clothing Market | 2026-2036
China Protective Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
China Protective Clothing Market Insights
Multi-source procurement is restructuring supply relationships across China's protective clothing sector as buyers diversify beyond single-factory dependence. 3M China leverages its filtration material expertise to anchor premium industrial coverall lines. Honeywell (China) Co., Ltd. sustains dominance in flame-resistant apparel through captive aramid supply chains. Ningbo Toprise Security Products Co., Ltd. competes on cost-efficient chemical protection garments for Southeast Asian re-export markets.
China protective clothing encompasses engineered garments designed to shield wearers from chemical, thermal, biological, and mechanical hazards, typically constructed from woven or non-woven fabrics with specified breakthrough resistance and tensile strength parameters. Coveralls manufactured from aramid blends such as Nomex dominate thermal protection for steel and petrochemical workers, while polypropylene spunbond-meltblown-spunbond laminates anchor disposable biological safety applications in hospital settings. The material segment shows polyethylene gaining share in wet weather gear as coastal construction activity expands, though cotton-blend lab coats retain stable demand from pharmaceutical quality control facilities.
SAMR enforces GB standards for industrial protective clothing, while NMPA regulates medical-grade gowns under device classification rules that mandate biocompatibility testing and facility licensing. The dual carbon goals policy from MEE is forcing textile converters to adopt waterless dyeing and recycled fiber inputs, reshaping cost structures for domestic manufacturers. Stakeholders must monitor how provincial environmental enforcement in Zhejiang and Shandong affects small-lot converter viability and whether centralized procurement platforms for state-owned oil and gas operators consolidate supplier tiers.
Market Dynamics
China's protective clothing sector is experiencing structural compression from the dual carbon goals policy, which forces textile converters in Zhejiang and Shandong to abandon water-intensive dyeing processes and absorb higher recycled fiber input costs.
Growth Catalysts
- Hospital infrastructure mandates:Post-pandemic procurement directives from the National Health Commission require expanded surgical and isolation gown stockpiles across tertiary care facilities.
- GB 19082 standard tightening:SAMR enforcement of upgraded medical protective clothing benchmarks is disqualifying low-grade imports and elevating domestic manufacturer qualification thresholds.
- Aramid fiber localization:Captive para-aramid production in Jiangsu province is reducing import dependency for flame-resistant coveralls serving steel and petrochemical operators.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene price swings compress margins for disposable gown manufacturers in the Yangtze River Delta.
- Concentrated converter geography:Small-lot textile processors in Shaoxing and Keqiao face shutdown risk from intensified MEE environmental inspections.
- Technical limitation in breathability:Current SMS laminate constructions trade moisture vapor transmission for viral barrier performance, limiting extended-wear applications.
Strategic Opportunities
- Centralized procurement platforms:State-owned oil and gas operators are consolidating supplier tiers, creating volume contracts for qualified domestic coverall manufacturers.
- Smart PPE convergence:Integration of temperature-monitoring sensors with aramid thermal garments is opening premium positioning for steelworker protection.
- Wet weather expansion:Coastal infrastructure projects in Fujian and Guangdong are pulling polyethylene-based rain gear demand beyond traditional seasonal patterns.
Industry Challenges
- Biocompatibility testing backlog:NMPA device classification rules for medical gowns create 14-18 month certification queues that freeze product launches.
- Legacy dyeing asset stranding:Waterless supercritical CO2 dyeing equipment requires 8-12 million RMB capital commitments that mid-tier converters cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Protective Clothing Market |
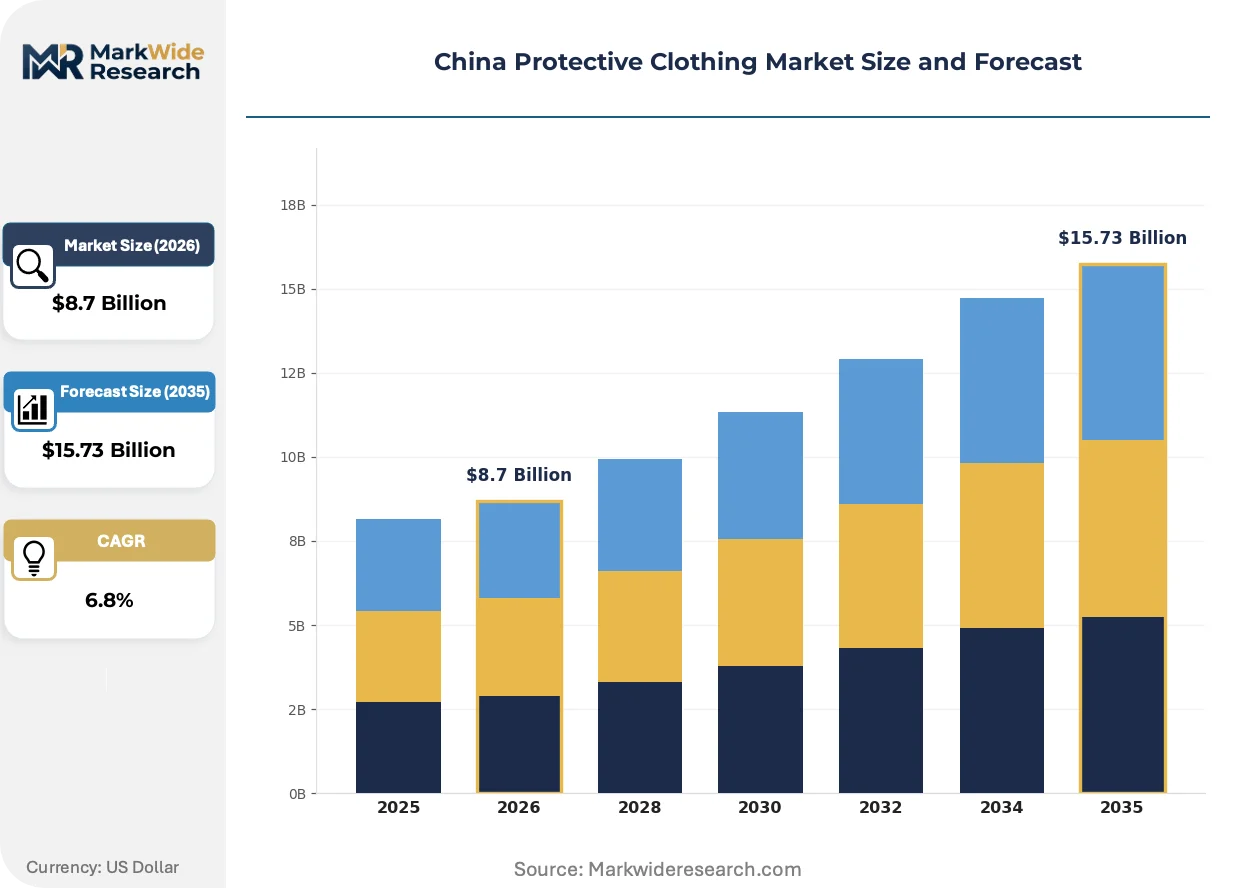
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Jackets, Trousers, Lab Coats Material: Nomex, Polypropylene, Polyethylene, Cotton End User: Manufacturing, Healthcare, Construction, Oil & Gas Application: Chemical Protection, Thermal Protection, Biological Safety, Wet Weather |
| Companies Covered | 3M China, Honeywell (China) Co., Ltd., Ningbo Toprise Security Products Co., Ltd., Winner Medical Co., Ltd., Beijing ANHENG Safety Protective Equipment Co., Ltd., Baymro Safety China, ANBU SAFETY INDUSTRIAL CO., LIMITED, Haiyuan, Jihua Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Protective Clothing Market Trends and Innovations
Material science advances and regulatory enforcement are compressing product lifecycles while elevating performance thresholds across China's protective clothing value chain.
Aramid-Nomex blend fabrics is expanding into multi-hazard protection for chemical-petrochemical complexes where thermal and splash risks coexist. Sinopec and private refinery operators in Zhejiang province are piloting these garments at 15-20% volume premiums over single-hazard alternatives. The technology is expanding into adjacent industrial segments previously served by separate thermal and chemical garment inventories.
MEE dual carbon goals enforcement is mandating waterless dyeing adoption and recycled fiber minimums for textile converters above designated emission thresholds. Facility licensing in Jiangsu and Shandong now requires verified carbon intensity reporting for protective clothing export eligibility. Premium domestic brands are responding by marketing verified recycled content to state-owned enterprise procurement officers.
Multi-source supplier qualification is displacing single-factory dependence among hospital systems and industrial buyers. Shanghai-based distributors now maintain approved vendor lists spanning 4-6 manufacturing sites to mitigate concentration risk. This pattern is most visible in pharmaceutical quality control facilities where cotton-blend lab coat specifications require redundant sourcing across Anhui and Henan provinces.
China Protective Clothing Market Segmentation
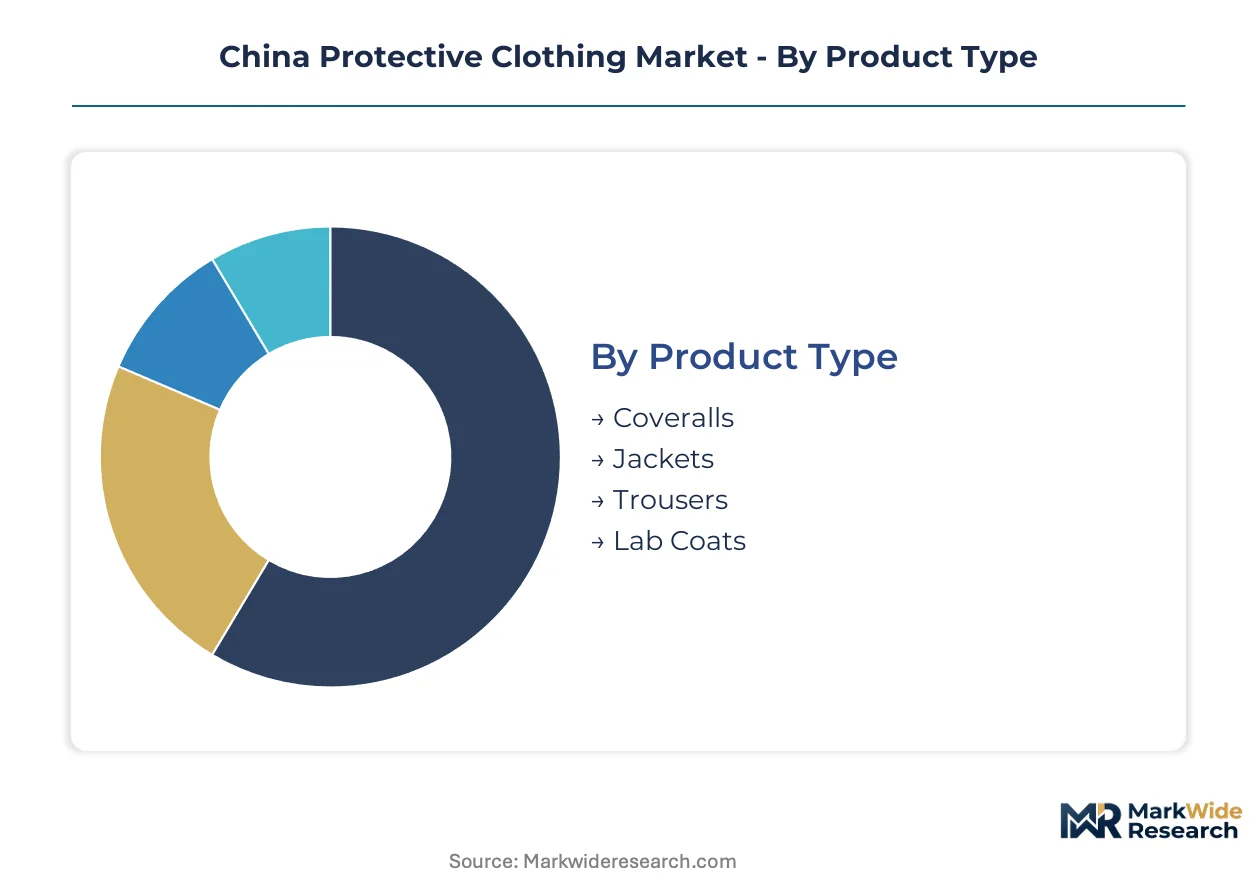
China's protective clothing market fragments across four critical dimensions that determine procurement priorities and supplier qualification thresholds. Material selection and end-use application dominate buyer decision frameworks, while product form and hazard type shape manufacturing specialization and distribution channel requirements.
Product Type:
Industrial buyers prioritize coverage completeness and mobility constraints when specifying garment architecture for hazard-specific work environments.
- Coveralls:One-piece engineered garments dominate steel, petrochemical, and chemical processing facilities where full-body splash and thermal protection is mandatory. Aramid-Nomex blends from Jiangsu province converters anchor premium thermal lines for Sinopec refinery operators.
- Jackets:Upper-body protection concentrates in construction and logistics segments where mobility and climate adaptability outweigh full coverage needs. Shanghai distributors stock multi-pocket designs with reflective striping for port and highway maintenance crews.
- Trousers:Lower-body garments serve welding and grinding applications where upper-body flexibility matters. Keqiao textile clusters produce cotton-blend and leather-reinforced variants for metal fabrication shops.
- Lab Coats:Knee-length cotton or polyester-cotton garments anchor pharmaceutical quality control and research laboratory procurement. Anhui and Henan province manufacturers maintain redundant capacity for hospital system multi-source qualification.
Volume sits with coveralls; growth tilts toward lab coats.
Material:
Performance specifications and cost tier determine fiber selection, with localization trends reshaping supply security calculations for industrial procurement officers.
- Nomex:Meta-aramid fiber delivers inherent flame resistance without chemical treatment degradation. Captive para-aramid production in Jiangsu province is displacing imported DuPont supply for steelworker and refinery thermal protection lines.
- Polypropylene:Spunbond-meltblown-spunbond laminates form disposable surgical and isolation gowns under GB 19082 medical standards. Yangtze River Delta converters face margin compression from petrochemical input price volatility.
- Polyethylene:Film and non-woven constructions serve wet weather gear for coastal infrastructure projects. Fujian and Guangdong construction activity is pulling demand beyond traditional seasonal procurement patterns.
- Cotton:Natural fiber retains stable demand from pharmaceutical QC facilities requiring lint-free, breathable lab coat specifications. Waterless dyeing mandates under MEE dual carbon goals are elevating processing costs for domestic spinners.
Nomex commands premium positioning; polyethylene is climbing the fastest.
End User:
Sector-specific hazard profiles and regulatory exposure drive divergent procurement volumes and certification requirements across industrial and institutional buyers.
- Manufacturing:Metal fabrication, electronics assembly, and automotive plants require multi-hazard protection combining cut resistance with chemical splash barriers. Zhejiang province automotive clusters source aramid-blend garments from qualified domestic suppliers.
- Healthcare:Tertiary care facilities expanded surgical and isolation gown stockpiles following National Health Commission post-pandemic infrastructure mandates. NMPA device classification rules create 14-18 month biocompatibility testing queues for new market entrants.
- Construction:Coastal and highway projects in Fujian, Guangdong, and Jiangsu provinces drive polyethylene rain gear and high-visibility coverall demand. MEE environmental inspections in Shaoxing threaten small-lot converter supply continuity.
- Oil & Gas:State-owned operators consolidate supplier tiers through centralized procurement platforms, creating volume contract opportunities for qualified domestic coverall manufacturers meeting flame-resistant and chemical protection specifications.
Healthcare holds installed base volume; oil and gas procurement consolidation offers expansion trajectory.
Application:
Hazard type determines material engineering priorities and certification complexity, with multi-hazard convergence creating premium positioning opportunities.
- Chemical Protection:Permeation-resistant laminates and encapsulated designs serve pesticide formulation, battery manufacturing, and chemical processing. Ningbo-based exporters target Southeast Asian re-export markets with cost-optimized garment lines.
- Thermal Protection:Aramid and carbon-felt constructions protect steelworkers, foundry operators, and refinery maintenance crews. Smart PPE integration with temperature-monitoring sensors is opening premium positioning at 15-20% volume premiums.
- Biological Safety:Viral barrier SMS laminates anchor hospital surgical and isolation gown procurement under SAMR-enforced GB standards. Current constructions trade moisture vapor transmission for barrier performance, limiting extended-wear comfort.
- Wet Weather:Polyethylene and PVC-coated fabrics serve coastal construction and port maintenance applications. Infrastructure investment in southern provinces is sustaining year-round procurement beyond traditional seasonal patterns.
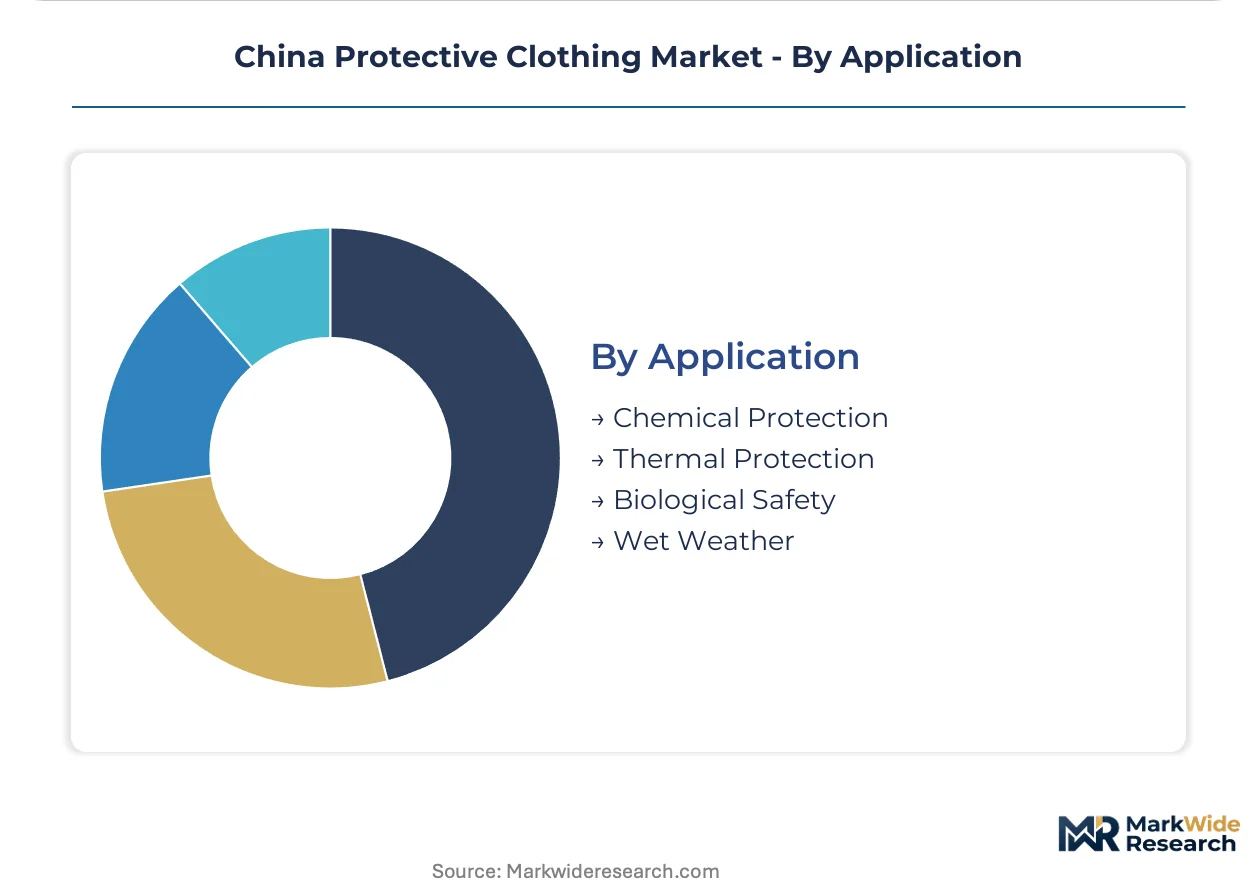
Chemical protection maintains revenue concentration; biological safety faces technical limitation constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for protective clothing in China concentrates in coastal manufacturing belts where textile converters cluster near export ports and heavy industry zones. Provincial environmental enforcement and state procurement centralization are redrawing competitive boundaries across sub-regional markets.
Yangtze River Delta
Shanghai and Jiangsu province host dense clusters of textile converters serving both domestic hospital systems and overseas PPE buyers. SAMR enforcement of GB 19082 medical protective clothing standards has elevated qualification thresholds for manufacturers in Suzhou and Nantong. Captive para-aramid fiber production in Jiangsu is reducing import dependency for flame-resistant coveralls.
Pearl River Delta
Guangdong province drives polyethylene-based wet weather gear demand from coastal infrastructure projects in Fujian and Guangdong. MEE dual carbon goals enforcement has forced small-lot processors in Shaoxing to abandon water-intensive dyeing. Shenzhen and Guangzhou distributors maintain multi-source vendor lists spanning 4-6 manufacturing sites.
Beijing-Tianjin-Hebei
The northern corridor concentrates state-owned oil and gas operator headquarters consolidating supplier tiers through centralized procurement platforms. NMPA device classification rules for medical gowns create 14-18 month biocompatibility testing queues affecting Tianjin-based entrants. Hebei province textile mills supply cotton-blend lab coats to pharmaceutical quality control facilities.
Shandong Peninsula
Shandong province converters face intensified MEE environmental inspections threatening small-lot processor viability. Waterless supercritical CO2 dyeing equipment requirements of 8-12 million RMB strain mid-tier manufacturer capital access. Qingdao and Yantai ports serve as export hubs for chemical protection garments targeting Southeast Asian re-export markets.
Sichuan-Chongqing
The western hub supports steel and petrochemical worker protection demand from inland refinery and metal fabrication operations. Smart PPE integration with temperature-monitoring sensors is opening premium positioning for thermal garment suppliers. Chongqing distributors are qualifying redundant sourcing capacity to serve pharmaceutical lab coat procurement west of the Yangtze.
China Protective Clothing Market Competitive Landscape
Multi-source supplier qualification dominates the current landscape as buyers abandon single-factory dependence. The market structures around three tiers: multinational filtration and safety specialists with captive material supply, domestic scale players with state procurement relationships, and regional converters competing on cost-efficient garment lines. Strategic archetypes include aramid fiber localizers, SMS laminate disposable gown manufacturers, and chemical protection exporters. Competitive moves concentrate on vertical integration into fiber production and geographic diversification of manufacturing footprints.
Among multinational specialists with Chinese operations, 3M China and Honeywell (China) Co., Ltd. exemplify the premium industrial tier anchored by filtration material expertise and captive aramid supply chains. Ningbo Toprise Security Products Co., Ltd. occupies a position within the export-focused chemical protection segment serving Southeast Asian re-export markets. These three represent distinct competitive positions: technology-driven premium positioning, integrated flame-resistant apparel dominance, and cost-optimized regional export specialization.
| Leading Market Players |
|---|
| 3M China |
| Honeywell (China) Co., Ltd. |
| Ningbo Toprise Security Products Co., Ltd. |
| Winner Medical Co., Ltd. |
| Beijing ANHENG Safety Protective Equipment Co., Ltd. |
| Baymro Safety China |
| ANBU SAFETY INDUSTRIAL CO., LIMITED |
| Haiyuan |
| Jihua Group |
| Others |
Pricing and Supply Chain Analysis
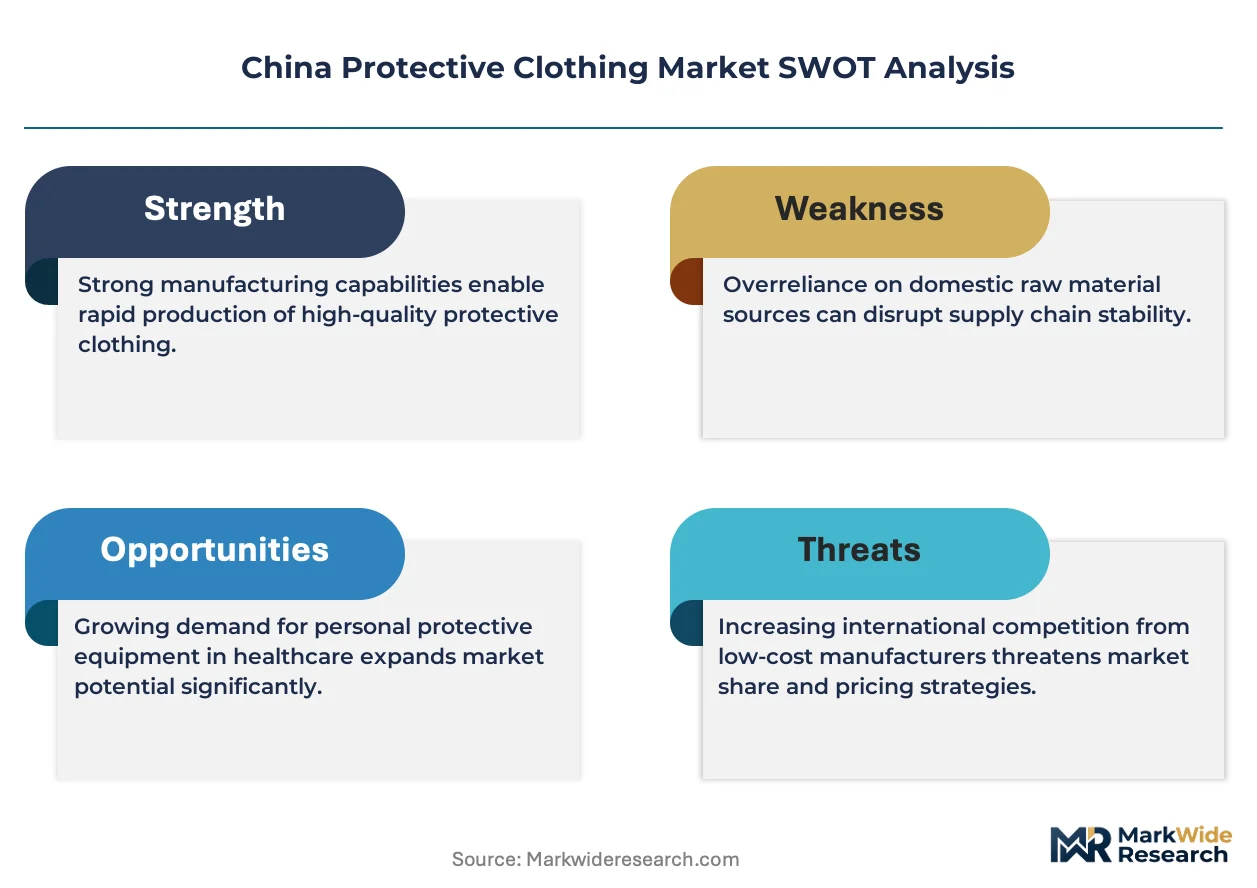
Polypropylene resin price volatility on the Dalian Commodity Exchange cascades through Yangtze River Delta converters, compressing margins for disposable gown manufacturers while amplifying pricing power for aramid-integrated domestic producers serving state-owned oil and gas procurement platforms.
Pricing Analysis
Volume concentration in polypropylene SMS laminates runs at thin margins, while aramid-blend thermal garments capture premium positioning. Pricing stratifies across GB 19082-certified medical tiers, NMPA device-classified surgical lines, and uncertified industrial economy alternatives. Cost compression in disposable segments is intensifying because petrochemical input swings absorb converter working capital. Hospital systems show highest price sensitivity in isolation gown procurement, whereas Sinopec refinery operators accept 15-20% premiums for multi-hazard aramid-Nomex constructions.
Supply Chain Analysis
Freight cost differentials between coastal ports and inland steel corridors determine converter location strategy for thermal garment distribution. Raw material supply concentrates in Jiangsu province for captive para-aramid fiber, the Yangtze River Delta for polypropylene spunbond-meltblown-spunbond laminates, and Shandong for cotton spinning. Input dependencies rest on Sinopec petrochemical feedstocks, imported DuPont meta-aramid for premium tiers, and Xinjiang long-staple cotton for pharmaceutical lab coats. Single-source vulnerability pervades medical-grade SMS laminate supply to tertiary hospitals. Distribution runs through Shanghai-based distributors maintaining 4-6 site vendor lists for multi-source qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SAMR enforcement of GB 19082 standards and NMPA device classification rules erect 14-18 month certification barriers that freeze out undercapitalized entrants while rewarding qualified incumbents with state procurement platform access.
For Market Incumbents: Anchor defensive positioning through backward integration into Jiangsu para-aramid fiber production and redundant manufacturing footprints across Anhui and Henan provinces. Threats from MEE environmental inspections in Shaoxing and Keqiao threaten small-lot converter supply continuity, creating acquisition opportunities for compliant scale players. Certification investment in waterless supercritical CO2 dyeing equipment, despite 8-12 million RMB capital requirements, secures export eligibility under dual carbon goals enforcement. For New Entrants and Emerging Players: Regional distributors in Chongqing and Sichuan represent the most penetrable channel partner type for pharmaceutical lab coat qualification west of the Yangtze. White-space targets include smart PPE integration for steelworker thermal garments and wet weather gear for Fujian coastal infrastructure. A go-to-market angle through state-owned enterprise centralized procurement platforms, bypassing hospital system multi-source complexity, offers faster revenue traction. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier converters with stranded water-intensive dyeing assets in Shandong and Zhejiang provinces facing MEE enforcement shutdown risk. Long-term viability over a multi-year horizon rests on identifying targets with verified GB 19082 compliance and existing relationships with Shanghai-based export distributors. The signal to monitor is provincial environmental enforcement intensity in Shaoxing and Keqiao, which determines forced seller volume and qualified asset scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber | Jiangsu province captive para-aramid production reduces import dependency for flame-resistant coverall lines. |
| Waterless Dyeing Technology Adoption | Supercritical CO2 equipment investments secure MEE dual carbon goals compliance for export eligibility. |
| Smart PPE Sensor Integration | Temperature-monitoring aramid garments command 15-20% premiums from Sinopec refinery operators. |
| Multi-Source Vendor Qualification | Shanghai distributors maintaining 4-6 site lists mitigate concentration risk for hospital procurement. |
| Southeast Asian Export Channel Development | Ningbo-based chemical protection garments access re-export markets through cost-optimized positioning. |
Research Methodology
Multi-period observation of GB standard revision timelines, NMPA certification queue lengths, and MEE enforcement intensity indicators anchored the trend analysis, supplemented by interviews with textile converter operations managers, hospital procurement directors, state-owned oil and gas safety equipment officers, Shanghai-based distributor principals, and SAMR regulatory affairs specialists. Secondary validation drew from SAMR GB standard filings, NMPA device registration databases, Yangtze River Delta customs export records, Sinopec procurement disclosure documents, and provincial MEE environmental inspection reports. Bottom-up manufacturing capacity surveys triangulated against top-down end-use demand estimates from hospital infrastructure mandate disclosures and refinery maintenance scheduling data.
The input-output matrix framed demand modeling across material type, product architecture, hazard application, and end-user sector dimensions throughout the forecast period. CAGRs derived from segment-level growth rate convergence analysis incorporating aramid fiber localization trajectories, petrochemical input price elasticity assumptions, and regulatory enforcement intensity scenarios. Industry-specific forecast inputs included dual carbon goals compliance cost curves for textile converters and centralized procurement platform adoption rates among state-owned enterprises.
Caveats apply where NMPA biocompatibility testing backlog durations, MEE provincial enforcement heterogeneity, or polypropylene resin price spike persistence could materially shift the outlook. Forecasts reflect documented assumptions about regulatory timeline stability and raw material supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market