
 Dates Market | 2026-2036
Dates Market Size, Share, and Industry Trends Forecast 2026-2036
Dates Market Analysis
Supermarket distribution across Gulf Cooperation Council states is fragmenting as specialty shops and direct-to-hotel procurement channels capture premium Medjool and Barhi volumes. Al Foah Company leverages its integrated groves-to-retail infrastructure across the UAE. Hadiklaim Date Growers Cooperative sustains its position through controlled supply of Deglet Noor to European retail chains. Bateel International differentiates via boutique retail formats targeting gift and luxury hospitality segments.
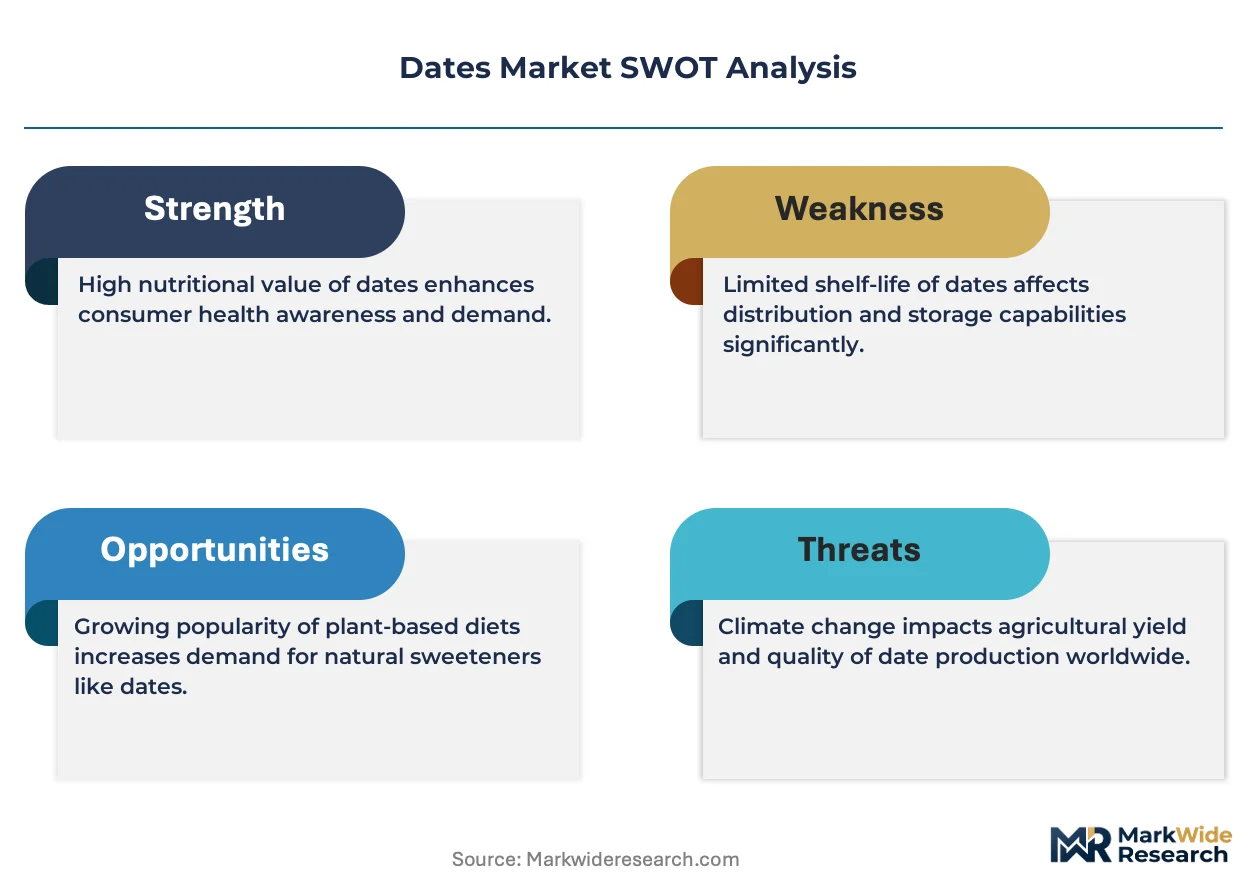
Dates are the stone fruit of Phoenix dactylifera, containing 60–70% sugars by dry weight, with moisture content ranging from 10% in dried grades to 30% in fresh Barhi, and serve as natural sweeteners, shelf-stable ingredients, and cultural staples across Islamic markets. Medjool commands the dominant margin pool due to its large size and premium positioning in North American and European retail. Bakery and confectionery end-use is expanding fastest as manufacturers substitute refined sugars with date paste and syrup in clean-label formulations.
Saudi Arabia's SASO and the UAE's Ministry of Climate Change and Environment enforce pesticide residue limits and halal certification protocols that determine export eligibility into Gulf markets. The EU's EFSA and REACH frameworks govern maximum contaminant thresholds for date imports entering European retail channels. Stakeholders must monitor evolving organic certification requirements and water-use regulations across North African origin countries as climate stress intensifies.
Market Dynamics
Supermarket distribution across Gulf Cooperation Council states is fragmenting as specialty shops and direct-to-hotel procurement channels capture premium Medjool and Barhi volumes. Al Foah Company leverages its integrated groves-to-retail infrastructure across the UAE. Hadiklaim Date Growers Cooperative sustains its position through controlled supply of Deglet Noor to European retail chains. Bateel International differentiates via boutique retail formats targeting gift and luxury hospitality segments.
Growth Catalysts
- Clean-label sugar substitution:Bakery and confectionery manufacturers are replacing refined sugars with date paste and syrup to meet consumer demand for natural sweeteners in processed foods.
- SASO residue mandates:Saudi Arabia's tightening traceability requirements are forcing supply chain upgrades that improve export quality credentials for Gulf-origin dates entering premium channels.
- Fresh Barhi season extension:Controlled-atmosphere storage technology is extending the availability window for high-moisture varieties traditionally limited to harvest periods.
Market Restraints
- Water cost volatility:Phoenix dactylifera cultivation requires substantial irrigation inputs, and groundwater depletion across North African origin zones is raising production cost baselines.
- Single-origin concentration:Premium Medjool supply concentrates in the Jordan Valley and Coachella Valley, creating geographic vulnerability to climate shocks and trade disruptions.
- EU contaminant thresholds:EFSA and REACH frameworks impose strict maximum residue limits that disqualify non-compliant shipments from European retail access.
Strategic Opportunities
- North American foodservice penetration:Institutional buyers in the United States and Canada remain underdeveloped for date-based menu applications beyond Middle Eastern cuisine segments.
- Organic certification tailwinds:Evolving organic standards across Tunisia and Algeria open premium positioning for producers achieving EU-equivalent certification status.
- E-commerce direct channels:Subscription models and specialty food platforms are bypassing traditional wholesale layers to reach health-conscious consumers in urban markets.
Industry Challenges
- Post-harvest skill scarcity:Sorting, grading, and packaging operations require trained labor that is migrating to higher-wage sectors across origin countries.
- Halal certification complexity:Multi-jurisdictional approval processes across SASO, MOHAP, and importing-country Islamic authorities create documentation bottlenecks and timeline uncertainty.
- Legacy cold chain gaps:Temperature-controlled logistics infrastructure remains inconsistent between rural groves and export consolidation points in North African supply zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dates Market |
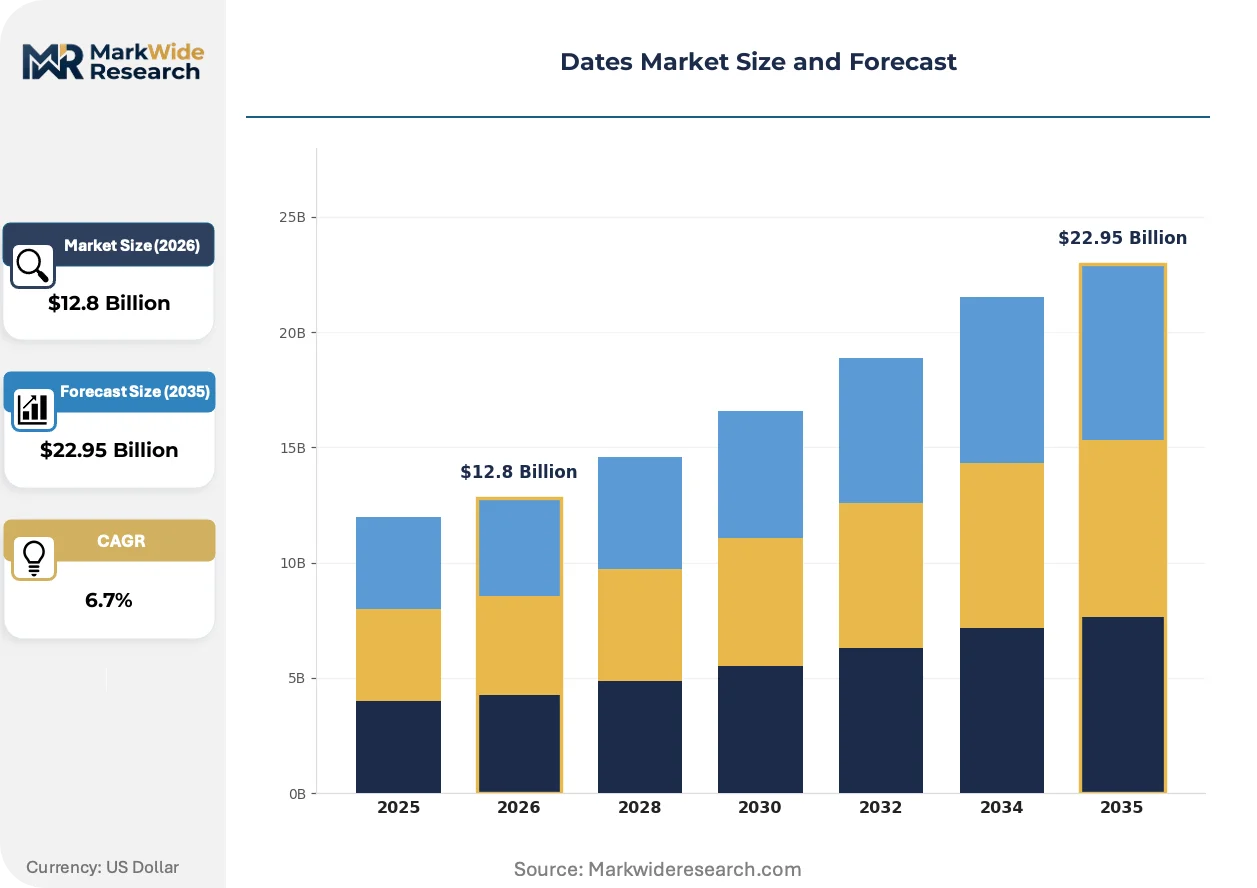
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medjool, Deglet Noor, Barhi, Khadrawy End User: Retail, Food Service, Bakery, Confectionery Packaging Type: Bulk, Retail Packs, Organic Packs, Dried Options Distribution Channel: Supermarkets, Online Stores, Specialty Shops, Wholesale |
| Companies Covered | Atul Rajasthan Date Palm Ltd., Al Foah Company, Natural Delights, Hadiklaim Date Growers Cooperative, Bateel International, Bayara Saudi Arabia Ltd., Ithmar Taiba Dates Company, National Agricultural Development Company, Al Barakah Dates Factory LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dates Market Emerging Trajectories
Digital traceability systems and precision agriculture tools are transforming how date producers manage quality consistency and regulatory compliance across dispersed growing regions. These technologies compress information asymmetries between origin farms and destination buyers.
Blockchain-based provenance tracking is virtualizing the traditional paper-based certificate chain that accompanies date shipments from grove to retail shelf. European supermarket chains are mandating pilot implementations for organic and premium-grade lines. This virtualization is compressing audit timelines and reducing fraud exposure in multi-handler supply chains.
REACH and EFSA frameworks are tightening maximum contaminant thresholds for pesticide residues and mycotoxins in dried fruit imports entering European retail channels. Exporters must upgrade laboratory testing protocols and pre-shipment verification procedures. North African cooperatives are responding by consolidating around certified testing facilities to maintain market access.
Buyer concentration in UAE hospitality procurement is displacing fragmented supermarket purchasing as the volume determinant for premium varietals. Hotel groups and airline catering operations are negotiating direct contracts with integrated producers, bypassing traditional wholesale intermediaries. This pattern is most visible in Dubai and Abu Dhabi, where five-star property development continues to outpace retail square footage growth.
Dates Market Segmentation
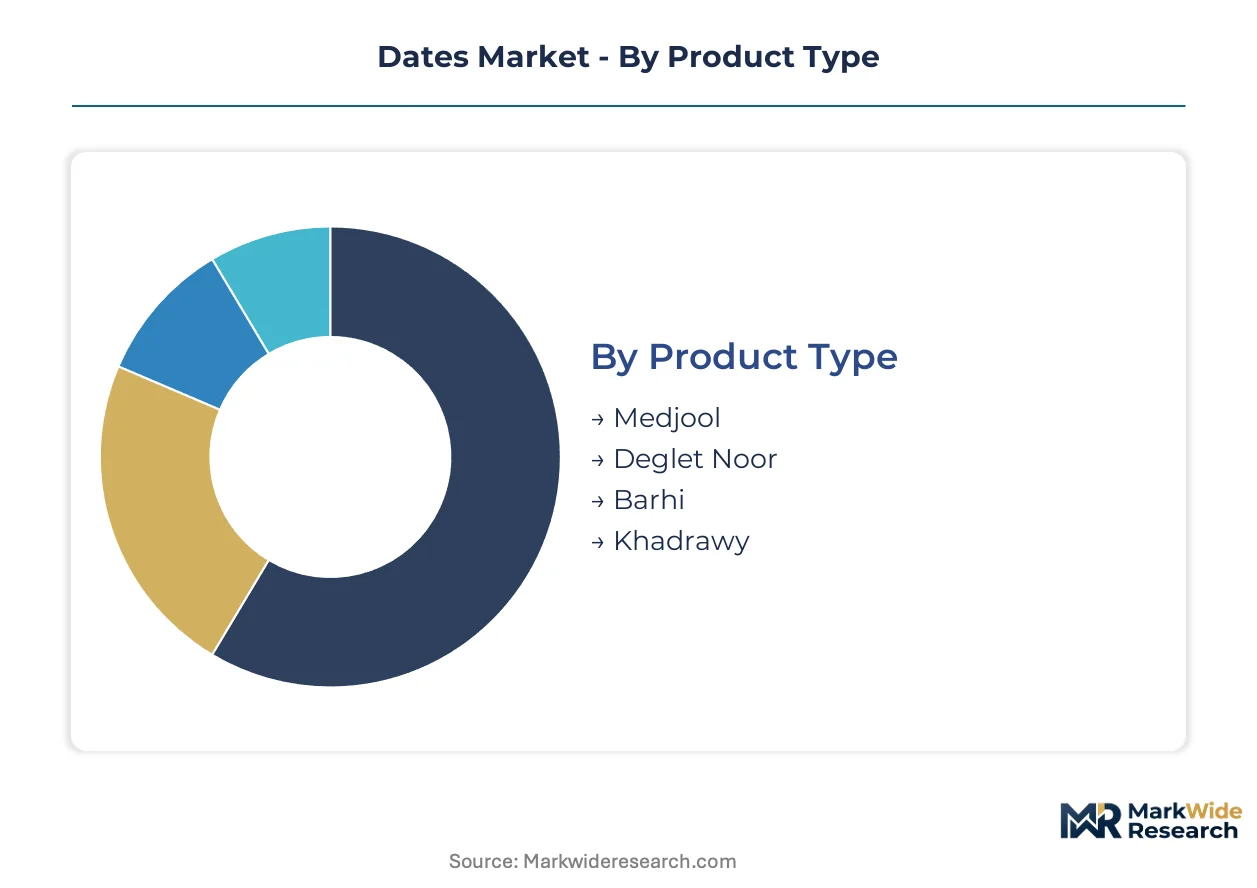
Date varietals, end-use applications, and distribution configurations each carry distinct margin profiles and regulatory requirements. Understanding how these dimensions intersect clarifies where procurement investments and compliance resources generate the strongest returns.
Product Type:
Cost tier differentiation separates commodity grades from premium positioning based on fruit size, moisture content, and labor-intensive cultivation requirements.
- Medjool:Large fruit with 60-70% sugar content and soft texture commands premium shelf placement in North American and European retail. Five-star hotel procurement in Dubai and Abu Dhabi concentrates demand for jumbo-grade specimens with uniform caramel coloring.
- Deglet Noor:Semi-dry texture and translucent flesh define this variety's technical profile. European supermarket chains source controlled volumes through Israeli and Tunisian cooperatives, with EFSA residue compliance determining eligibility.
- Barhi:Fresh consumption at 25-30% moisture requires rapid cold chain transit from Jordan Valley groves.
- Khadrawy:Soft date with shorter shelf life serves regional Middle Eastern markets.
Medjool commands the established base. The steepest expansion runs through Barhi as controlled-atmosphere storage extends seasonal availability.
End User:
Application context determines specification stringency, from bulk ingredient standards to gift-grade presentation requirements.
- Retail:Packaged SKUs face SASO and EFSA labeling mandates alongside halal certification. UAE supermarket buyers negotiate direct with integrated producers, bypassing traditional import layers for premium lines.
- Food Service:Institutional procurement in Saudi Arabia's hotel and airline catering sectors specifies uniform sizing and moisture parameters. Direct contracts with Al Foah and Bateel displace wholesale intermediaries in volume determination.
- Bakery:Date paste and syrup substitution for refined sugars accelerates with clean-label formulation trends.
- Confectionery:Chocolate-coated and stuffed date products target gift segments in Gulf Cooperation Council states.
Retail absorbs the volume foundation. Bakery applications are climbing the fastest as manufacturers reformulate around natural sweetener positioning.
Packaging Type:
Customer type and certification tier shape procurement specifications across institutional, consumer, and premium gift segments.
- Bulk:Industrial-scale containers serve food manufacturers and reprocessors with minimal handling requirements. REACH documentation accompanies shipments entering EU processing facilities.
- Retail Packs:Consumer-facing formats carry bilingual labeling for Gulf markets and nutritional disclosure for North American import compliance.
- Organic Packs:EU-equivalent certification from Tunisia and Algeria opens premium positioning. Blockchain traceability pilots accompany selected organic lines into European supermarket channels.
- Dried Options:Extended shelf life at 10-15% moisture reduces cold chain dependency for export to secondary markets.
Bulk shipments anchor industrial supply. Organic packs are gaining share fastest as certification infrastructure matures across North African origins.
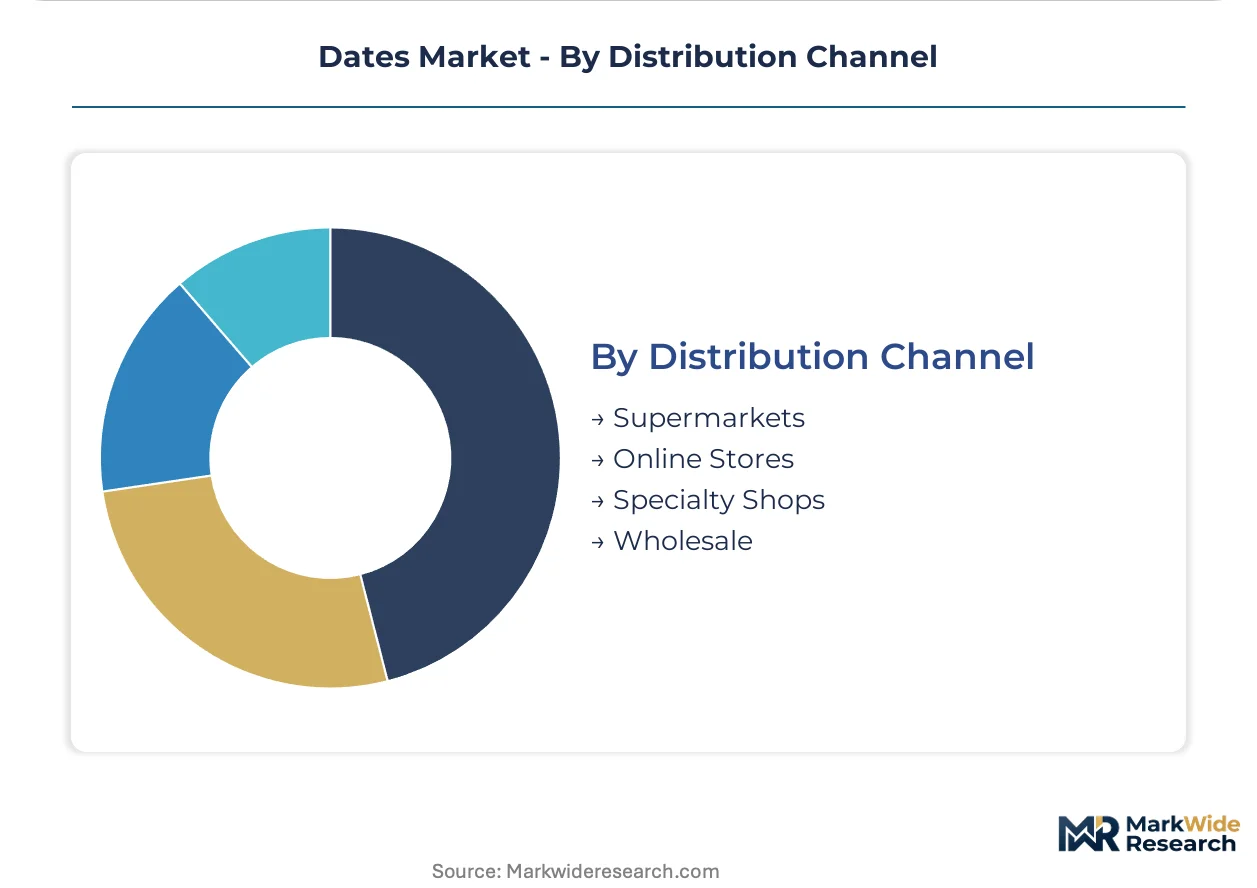
Distribution Channel:
Supply concentration and buyer consolidation patterns fragment traditional wholesale structures across Gulf and European markets.
- Supermarkets:Carrefour and Lulu hypermarkets in UAE and Saudi Arabia maintain category management for standard grades. Shelf space allocation favors private-label and established regional brands over imported premium lines.
- Online Stores:Subscription platforms and specialty food marketplaces bypass traditional wholesale markups to reach health-conscious consumers in London, Toronto, and New York metropolitan areas.
- Specialty Shops:Bateel's boutique network and comparable luxury formats target gift procurement with premium packaging and seasonal assortments.
- Wholesale:Traditional importers and redistribution points face margin compression as direct sourcing intensifies.
Supermarkets retain the volume foundation. Online stores are expanding most quickly as logistics platforms reduce delivery friction for perishables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO residue mandates and halal certification protocols anchor Saudi Arabia's regulatory framework, establishing quality baselines that cascade across Gulf supply chains. The analysis traces demand concentration through five countries where date cultivation, processing, and premium procurement intersect.
Saudi Arabia
Hotel and airline catering procurement in Riyadh and Jeddah specifies uniform sizing for premium varietals. SASO's tightening traceability requirements force supply chain upgrades among exporters targeting domestic retail. The Eastern Province's Al-Ahsa oasis cluster supplies Deglet Noor and Khalas grades to food service distributors under direct contract arrangements.
United Arab Emirates
Dubai's five-star property development outpaces retail square footage growth, displacing fragmented supermarket purchasing with consolidated hospitality procurement. MOHAP enforces pesticide residue limits parallel to SASO standards. Abu Dhabi's integrated groves-to-retail infrastructure captures premium Medjool volumes through direct sourcing relationships with hotel groups.
Israel
Jordan Valley cultivation concentrates Medjool and Barhi supply for European export channels. Hadiklaim's cooperative structure controls Deglet Noor flows to EFSA-compliant retail chains. Controlled-atmosphere storage facilities near Beit She'an extend fresh Barhi availability beyond traditional harvest windows.
Tunisia
Deglet Noor production in the Kebili region faces EU-equivalent organic certification requirements for premium positioning. EFSA maximum residue limits determine eligibility for French and German supermarket listings. Consolidation around certified testing facilities in Gabès maintains REACH documentation compliance for export consolidation.
United States
Coachella Valley cultivation anchors North American Medjool supply with concentrated exposure to climate volatility. FDA food safety modernization act requirements govern domestic distribution. California's date packers supply natural sweetener ingredients to bakery manufacturers reformulating around clean-label positioning.
Dates Market Vendor Landscape
Integrated groves-to-retail operators and cooperative export structures split the market between captive supply control and pooled quality standardization. Concentration remains moderate with tiered differentiation across commodity bulk, premium retail, and luxury gift segments. Two strategic archetypes dominate: vertically integrated national champions leveraging origin infrastructure, and specialty cooperatives aggregating smallholder output for certified export. Competitive moves center on direct procurement contracts with hospitality buyers and blockchain traceability pilots for organic lines.
Within the integrated operator tier, Al Foah Company exemplifies groves-to-retail infrastructure deployment across UAE Emirates, while Bateel International occupies the luxury gift archetype through boutique retail formats. Hadiklaim Date Growers Cooperative represents the cooperative export model, pooling Israeli cultivation for controlled European supply. These three anchors illustrate how strategic positioning diverges across infrastructure control, brand premiumization, and collective quality assurance.
| Leading Market Players |
|---|
| Atul Rajasthan Date Palm Ltd. |
| Al Foah Company |
| Natural Delights |
| Hadiklaim Date Growers Cooperative |
| Bateel International |
| Bayara Saudi Arabia Ltd. |
| Ithmar Taiba Dates Company |
| National Agricultural Development Company |
| Al Barakah Dates Factory LLC. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Tunisia's Deglet Noor packing facilities is compressing export margins and forcing cooperatives to absorb logistics costs previously passed to buyers, reshaping supplier pricing power across Mediterranean origin zones.
Pricing Analysis
Geographic price spreads between Jordan Valley Medjool and Coachella Valley equivalents have widened as water cost differentials and labor availability diverge. Three-tier pricing structure across premium jumbo-grade, standard retail, and economy processing grades dominates contract negotiations, with EFSA certification tier and cold chain reliability as primary differentiation drivers. Pricing pressure stems from groundwater depletion raising irrigation input costs across North African origins. Food manufacturers reformulating with date paste exhibit highest price sensitivity, while five-star hotel procurement in Dubai shows lowest sensitivity to per-kilogram differentials.
Supply Chain Analysis
Extended payment terms from European supermarket chains are straining working capital for Tunisian and Algerian cooperatives, accelerating consolidation around integrated packers with supply-chain finance facilities. Geographic supply concentrates in Saudi Arabia, Israel, and Tunisia, with secondary flows from Algeria and the United States. Cultivation draws from groundwater reserves, phosphate fertilizers, and controlled-atmosphere storage infrastructure as critical inputs. Single-origin concentration in the Jordan Valley creates climate-shock vulnerability for fresh Barhi availability. Distribution runs through direct-to-hotel procurement channels and specialty retail networks, bypassing traditional wholesale layers in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled post-harvest labor for sorting and grading operations is migrating to higher-wage sectors across origin countries, creating a capability bottleneck that advantages operators with in-house training academies or automated grading infrastructure.
For Market Incumbents: Insulate premium positioning by securing controlled-atmosphere storage capacity in Jordan Valley and Coachella Valley clusters, and accelerate blockchain traceability pilots for organic lines to preempt EFSA documentation requirements. Threats from fresh Barhi season extension technology and new entrant cooperatives in Algeria require defensive certification investments. For New Entrants and Emerging Players: Build out direct e-commerce subscription channels targeting health-conscious consumers in London, Toronto, and New York metropolitan areas, where traditional wholesale markups create white-space pricing advantages. North American foodservice penetration remains underdeveloped beyond Middle Eastern cuisine segments, offering the most penetrable application frontier. Go-to-market positioning should emphasize clean-label sugar substitution credentials for bakery manufacturer procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-atmosphere storage and blockchain traceability infrastructure, favoring scaled operators with existing balance sheet capacity. Long-term viability across the analysis window rests on backward integration into grove ownership rather than merchant trading models. Acquisition targets should display integrated groves-to-retail infrastructure with established SASO or EFSA compliance records. The signal to watch is consolidation pace among Tunisian cooperatives around certified testing facilities as REACH enforcement tightens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grove Ownership | Captive supply control reduces exposure to water cost volatility and climate shocks in concentrated origin zones. |
| Blockchain Traceability Implementation | Virtualized provenance documentation compresses EFSA audit timelines for organic premium lines entering European retail. |
| Controlled-Atmosphere Storage Expansion | Fresh Barhi season extension technology captures margin expansion beyond traditional harvest windows. |
| Direct-to-Hotel Procurement Contracts | Bypassing wholesale intermediaries aligns volume determination with Dubai and Abu Dhabi five-star property development. |
| EU-Equivalent Organic Certification | Tunisia and Algeria certification infrastructure opens premium positioning as EFSA residue mandates tighten. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SASO regulatory filings, EFSA maximum residue limit databases, and UAE Ministry of Climate Change and Environment halal certification records. Primary interviews engaged date cooperative managers, hotel procurement directors in Riyadh and Dubai, bakery manufacturer R&D leads, and cold chain logistics operators across North African export corridors. Secondary validation drew from customs trade data, agricultural ministry production statistics, and REACH documentation requirements. Bottom-up volume modeling triangulated against top-down demand aggregation across retail, food service, and industrial application segments.
Forecast inputs incorporate varietal supply concentration, certification infrastructure maturity, and hospitality procurement contract visibility across the projection horizon. Segmentation dimensions modeled include product type, end-use application, packaging configuration, and distribution channel, with regulatory compliance tier as an industry-specific overlay. CAGRs were derived from trend extrapolation of clean-label substitution rates, SASO enforcement trajectory, and controlled-atmosphere storage adoption curves.
Stress conditions across groundwater availability, EFSA residue threshold revision, and fresh Barhi cold chain reliability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline standardization and hospitality sector recovery patterns. Macroeconomic deviation, regulatory acceleration, or technological disruption in precision agriculture would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Goji Berries Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market