
 Fresh Pumpkin Market | 2026-2036
Fresh Pumpkin Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Pumpkin Market Foresight
The gap between premium heirloom and commodity-grade pumpkins is expanding in both pricing and distribution channels. Libby's sustains dominance in processed pumpkin supply through backward integration into Midwest growing operations. Indiana Pumpkin Growers Cooperative differentiates via direct-to-retail distribution networks that bypass conventional wholesale auctions. Panama Fresh Produce Exporters navigates seasonal counter-cyclical harvesting to serve North American markets during domestic off-peak windows.
Fresh pumpkin denotes the harvested fruit of Cucurbita species, typically containing 6-10% sugars and 1-2% fiber by fresh weight, sold raw for culinary processing or decorative display. Sugar pumpkins concentrate margin pools due to their dual utility in pie manufacturing and upscale restaurant applications. The Horeca sector represents the fastest-growing end user, as chefs source specific cultivars for menu differentiation. Whole pumpkin form still occupies the largest volume share, though pureed and pre-cut formats are gaining traction among time-constrained retail consumers.
The USDA and FDA jointly govern fresh pumpkin through produce safety rules and labeling standards that affect interstate commerce. Organic certification under USDA National Organic Program creates tiered market access premiums that reshape grower planting decisions. State-level agricultural extensions in Michigan and Pennsylvania enforce additional variety registration and pest management protocols. Stakeholders must monitor evolving FDA traceability requirements and climate-driven harvest volatility to secure supply continuity.
Market Dynamics
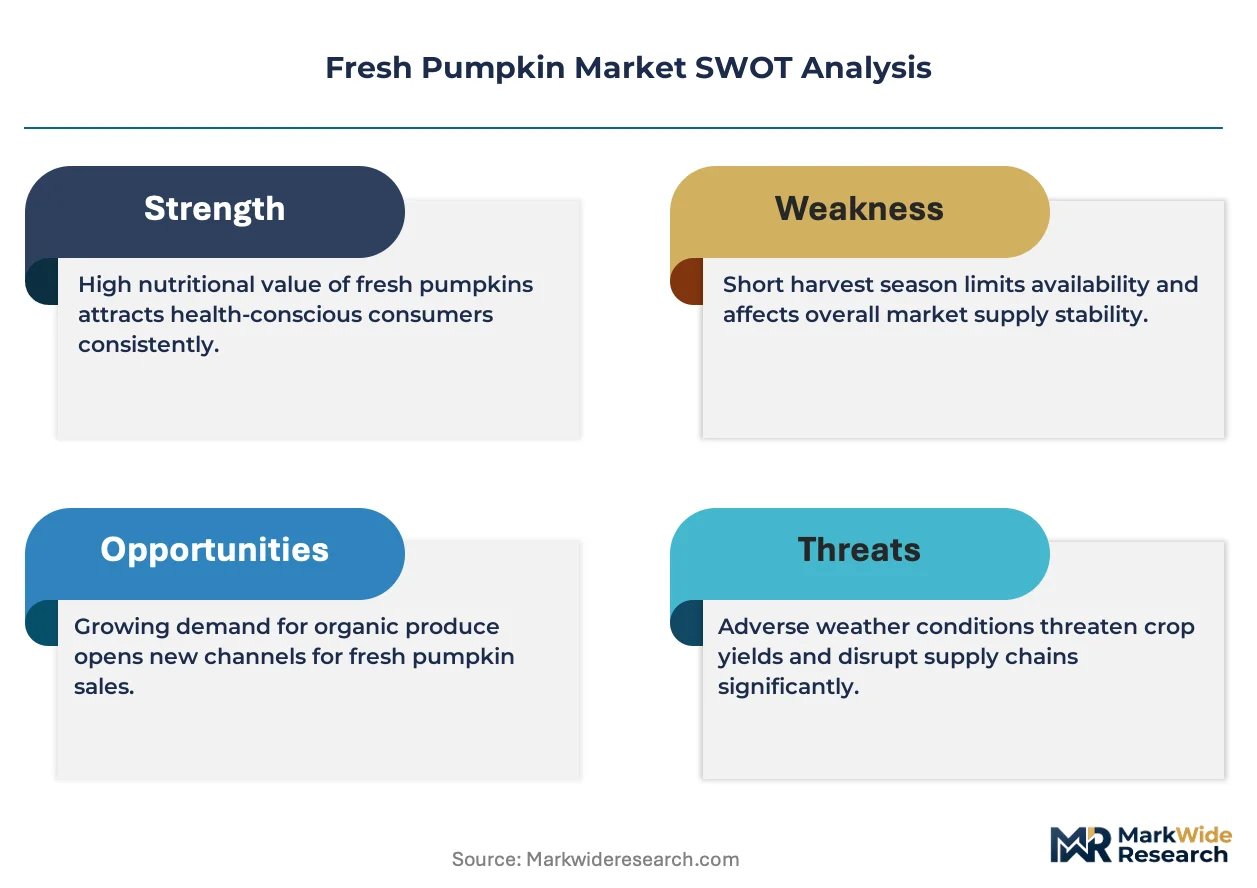
The USDA organic certification framework is concentrating supply among certified growers while displacing conventional operations from premium channels. This regulatory pressure intersects with climate-driven harvest volatility to reshape procurement security calculations across food processing and retail segments.
Growth Catalysts
- Clean-Label Ingredient Mandates:Food manufacturers reformulate with recognizable pumpkin derivatives to meet retailer ingredient policies. This pulls additional acreage into contract growing arrangements.
- India:The FSSAI's fortification guidelines for functional foods create import demand for nutrient-dense pumpkin varieties in dietary supplement applications.
- Sugar Pumpkin Cultivation:Dual-use cultivars serving both pie manufacturing and upscale restaurant channels command margin premiums that justify specialized agronomic investment.
Market Restraints
- Input Cost Volatility:Nitrogen fertilizer price swings directly compress grower margins in Illinois and Indiana production clusters.
- Supply Concentration Risk:Midwest growing operations dominate processed pumpkin supply, creating geographic vulnerability to localized weather events.
- Butternut Squash Substitution:Food service operators substitute alternative Cucurbita species when pumpkin supply tightens, capping price elasticity.
Strategic Opportunities
- Panama Counter-Cyclical Harvesting:Seasonal supply windows from Central American exporters fill North American off-peak demand gaps.
- Horeca Direct Sourcing:Chefs in metropolitan restaurant clusters increasingly contract specific heirloom cultivars bypassing wholesale auctions.
- Pre-Cut Retail Formats:Time-constrained consumers in suburban grocery channels drive value-added processing expansion.
Industry Challenges
- Organic Certification Timeline:The USDA National Organic Program's three-year transition requirement locks conventional acreage out of premium pricing tiers.
- Traceability System Integration:FDA produce safety rules mandate lot-tracking infrastructure that smaller growers struggle to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Pumpkin Market |
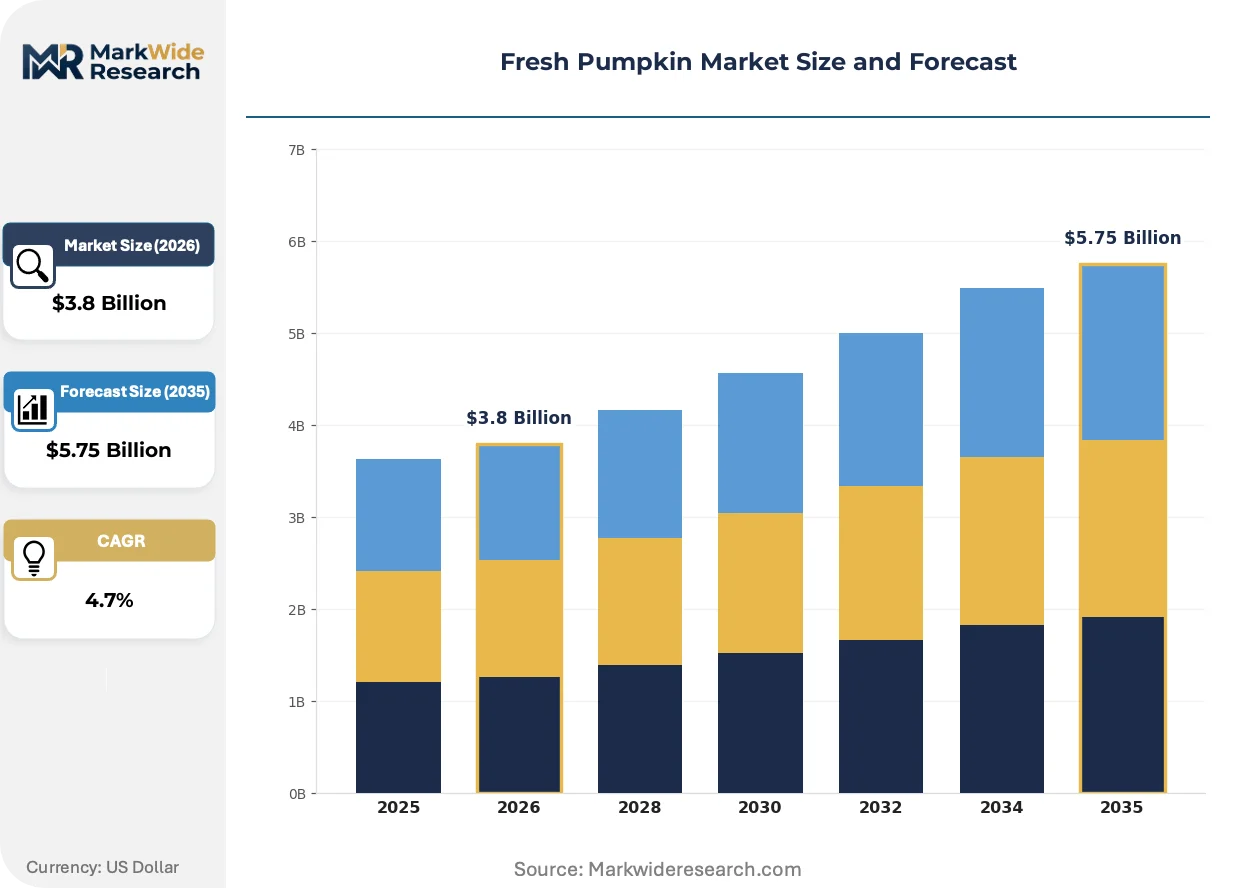
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Giant Pumpkin, Miniature Pumpkin, Sugar Pumpkin, White Pumpkin, Heirloom Pumpkin Form: Whole Pumpkin, Sliced Pumpkin, Diced Pumpkin, Pureed Pumpkin, Roasted Pumpkin Application: Cooking Ingredients, Decorative Uses, Functional Foods, Animal Feed, Cosmetics End User: Food Processing Companies, Retail Outlets, Horeca Sector, Cosmetic Manufacturers, Pet Food Producers |
| Companies Covered | Indiana Pumpkin Growers Cooperative, Pennsylvania Pumpkin Growers Association, Libby's, Washington Fresh Pumpkin Producers, Michigan Pumpkin Growers Association, Pumpkin Patch Fundraisers Inc., California Giant Berry Farms, Panama Fresh Produce Exporters, Libby, McNeill & Libby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Pumpkin Market Shifts & Advancements
Processing technology and distribution models are converging to compress supply chains and unlock value-added formats. These shifts favor operations with capital deployment capacity and direct channel access.
Controlled-atmosphere storage technology is electrifying post-harvest handling by extending marketable shelf life from weeks to months. Large-scale distributors in Michigan and Pennsylvania deploy these systems to smooth seasonal price curves. The capital barrier is electrifying consolidation among handlers capable of infrastructure investment.
The FDA's updated traceability requirements under the Food Safety Modernization Act impose record-keeping burdens on interstate shipments. Growers must now maintain digital lot records from field to first receiver. Medium-scale cooperatives in Indiana face the steepest compliance cost relative to revenue base.
Chef-driven cultivar specification is fragmenting procurement patterns away from commodity grades. Upscale restaurants in Chicago and New York now contract discrete pumpkin varieties by Brix content and fiber profile. This specification trend concentrates in coastal metropolitan markets with menu differentiation pressure.
Fresh Pumpkin Market Segmentation
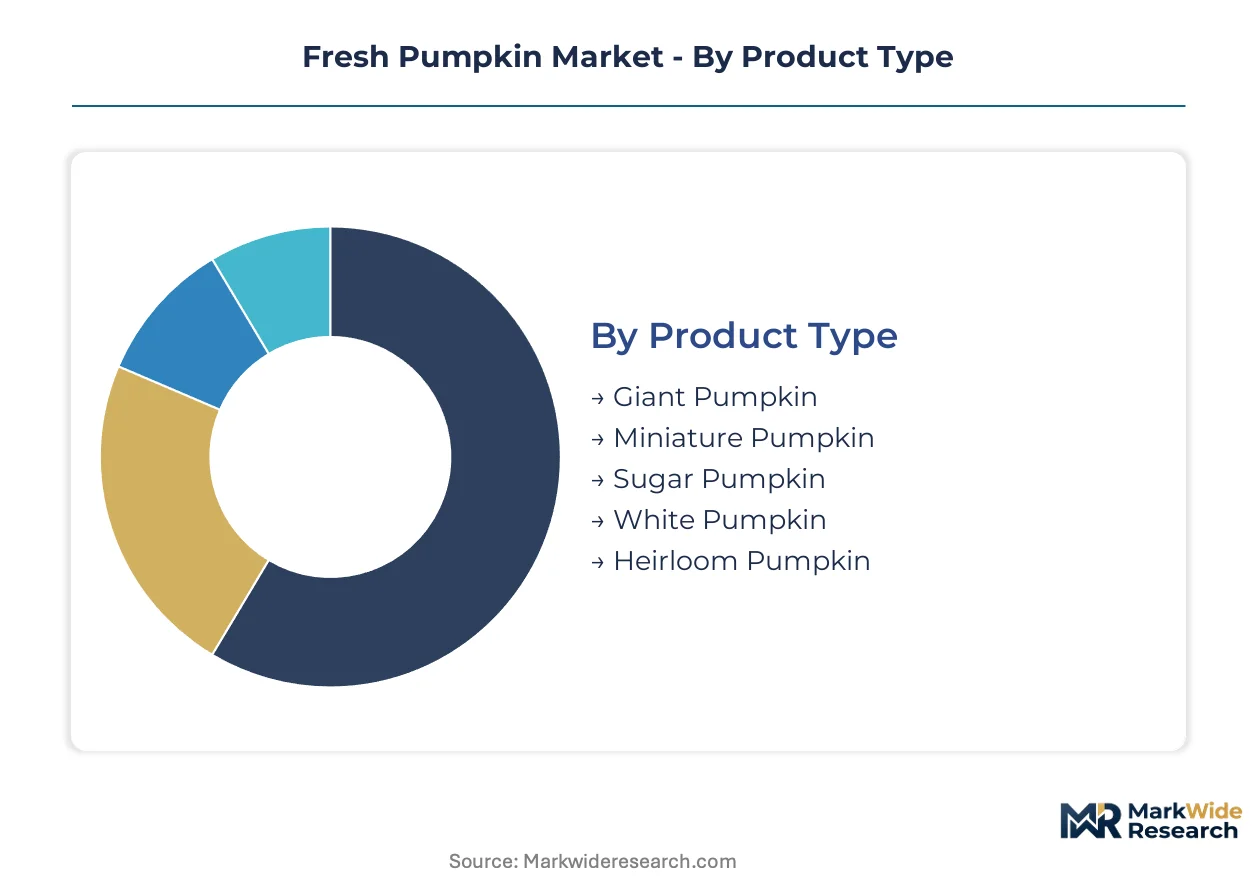
Fresh pumpkin segmentation reveals distinct margin architectures across product grades and processing intensities. Each dimension carries specific supply chain requirements that reshape procurement security and pricing power for growers and distributors.
Product Type:
Replacement cycles in pumpkin cultivation accelerate as chefs and processors demand specific cultivar characteristics for differentiated outputs.
- Sugar Pumpkin:Contains 6-10% sugars and dense flesh texture optimized for pie manufacturing and restaurant applications. Demand concentrates in Midwest food processing contracts and upscale Chicago dining establishments seeking consistent Brix content for menu standardization.
- Heirloom Pumpkin:Heritage cultivars with variable coloration and flavor profiles command direct-to-restaurant premiums. Metropolitan Horeca clusters in New York and San Francisco contract specific varieties by fiber profile and visual distinction.
- Giant Pumpkin:Exhibition-grade specimens exceeding 100 pounds serve agritourism and competitive weigh-off events.
- Miniature Pumpkin:Decorative table varieties under 5 pounds dominate autumn retail ornamental displays.
- White Pumpkin:Albino-skinned cultivars target wedding and event design markets seeking neutral color palettes.
Volume placements concentrate in Sugar Pumpkin; the faster expansion belongs to Heirloom Pumpkin.
Form:
Processing depth determines shelf-life extension and channel access, with capital-intensive formats capturing suburban grocery premiums.
- Whole Pumpkin:Unprocessed fruit retains 2-3 month storage viability under controlled atmosphere. Retail chains in Michigan and Pennsylvania deploy these systems to smooth seasonal price curves across Thanksgiving demand windows.
- Pureed Pumpkin:Thermally processed and aseptically packed for industrial baking and baby food applications. Libby's backward integration into Illinois growing operations secures captive supply for this high-volume format.
- Sliced Pumpkin:Fresh-cut rings for roasting applications in meal-kit distribution.
- Diced Pumpkin:Pre-cubed formats reduce preparation time for soup manufacturers and food service.
- Roasted Pumpkin:Value-added ready-to-eat products for deli and prepared food sections.
Whole Pumpkin maintains dominant volume share; Pureed Pumpkin climbs the fastest as time-constrained consumers trade preparation labor for convenience.
Application:
Functional positioning drives ingredient specification divergence between commodity food manufacturing and premium wellness channels.
- Functional Foods:Nutraceutical formulations leverage pumpkin seed protein and beta-carotene concentrates. India's FSSAI fortification guidelines pull import demand for nutrient-dense varieties in dietary supplement applications.
- Cooking Ingredients:Standardized puree and fresh segments supply pie manufacturing and soup bases. USDA organic certification requirements reshape grower planting decisions for this volume-dominant category.
- Decorative Uses:Ornamental sales spike during Halloween retail windows with minimal quality grading.
- Animal Feed:Cull-grade pumpkins and processing residuals enter livestock nutrition channels.
- Cosmetics:Seed oil extraction for skincare formulations targets clean-label beauty positioning.
Cooking Ingredients anchor volume throughput; Functional Foods gain share fastest on clean-label ingredient mandates from food manufacturers.
End User:
Customer scale and specification intensity fragment procurement patterns from commodity auctions to direct cultivar contracts.
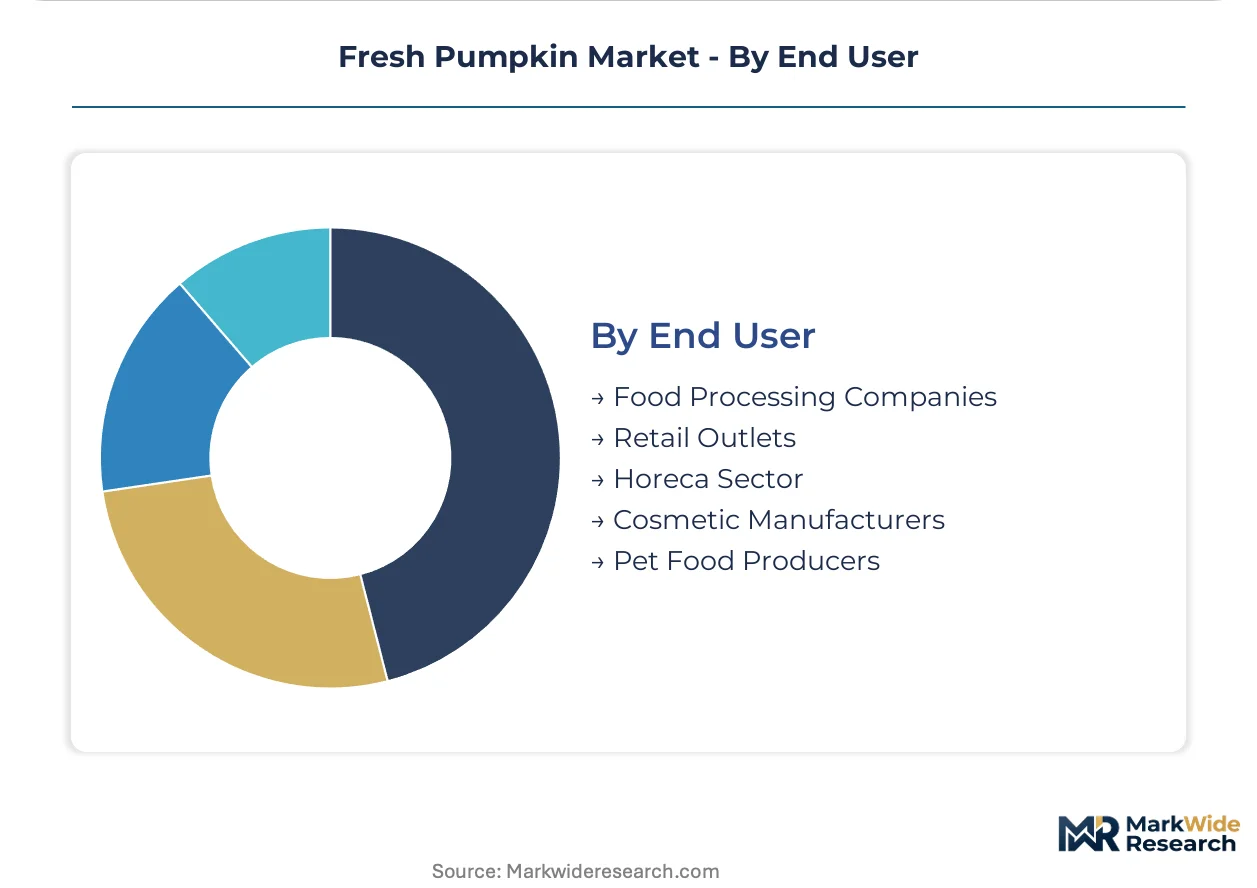
- Horeca Sector:Restaurants and institutional kitchens source discrete varieties by sugar content and texture profile. Chef-driven specification in Chicago and New York metropolitan clusters bypasses wholesale auctions for direct grower relationships.
- Food Processing Companies:Industrial canners and frozen food manufacturers contract acreage through backward integration or cooperative arrangements. Indiana Pumpkin Growers Cooperative differentiates via direct-to-processor distribution networks.
- Retail Outlets:Supermarket chains and farm stands handle seasonal ornamental and culinary grades.
- Cosmetic Manufacturers:Seed oil processors require specific cultivars with high lipid content.
- Pet Food Producers:Fiber-rich varieties enter premium pet nutrition formulations.
Food Processing Companies command largest volume contracts; Horeca Sector expands most quickly on menu differentiation pressure in coastal metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American fresh pumpkin procurement through its concentration of food processing contracts and upscale restaurant sourcing clusters that specification-grade cultivars.
United States
Seasonal retail volumes and food processing contracts anchor procurement patterns across Midwest growing operations. The USDA National Organic Program creates tiered market access premiums that reshape grower planting decisions in Illinois and Indiana. Michigan distributors deploy controlled-atmosphere storage systems to smooth seasonal price curves across Thanksgiving demand windows.
Canada
Cross-border supply agreements with US processors sustain import demand for sugar pumpkin varieties in Ontario and Quebec pie manufacturing. Health Canada and the Canadian Food Inspection Agency enforce produce safety rules that align with FDA traceability requirements for interstate shipments. British Columbia's agritourism sector drives demand for heirloom and decorative cultivars in the Pacific Northwest cluster.
Mexico
Counter-cyclical harvesting from Central American exporters fills North American off-peak demand gaps during domestic winter months. Mexico's national agricultural authority SADER oversees phytosanitary certification for fresh produce exports to US markets. The Bajío Region's irrigated farming operations concentrate contract growing for US food service distributors seeking year-round supply continuity.
India
The FSSAI's fortification guidelines for functional foods create import demand for nutrient-dense pumpkin varieties in dietary supplement applications. India's Food Safety and Standards Authority mandates label declarations for fortified food products that specify beta-carotene content thresholds. Maharashtra's food processing corridor in the Mumbai-Pune belt concentrates contract manufacturing for nutraceutical formulations leveraging pumpkin seed protein.
Panama
Seasonal supply windows from Central American exporters exploit hemispheric growing season inversion to serve North American markets during domestic off-peak windows. Panama's Ministry of Agricultural Development regulates export phytosanitary certification under bilateral trade agreements with the United States. The Chiriquí Highlands production zone specializes in cultivar selection optimized for extended shipping durability to Miami distribution hubs.
Fresh Pumpkin Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and distribution channel control. The market structures around backward-integrated processors, cooperative direct-to-retail networks, and counter-cyclical importers. Three archetypes dominate: USDA-certified organic specialists commanding retail premiums, Midwest-based food processing contractors securing captive supply, and Central American exporters exploiting seasonal arbitrage. Competitive moves concentrate on direct sourcing relationships with Horeca clusters and infrastructure investment in controlled-atmosphere storage capacity.
Within the cooperative archetype, Indiana Pumpkin Growers Cooperative and Pennsylvania Pumpkin Growers Association represent member-owned structures that bypass conventional wholesale auctions through direct-to-retail distribution networks. Libby's occupies a position exemplifying backward integration into Midwest growing operations that secures captive supply for high-volume processed formats. Panama Fresh Produce Exporters anchors the counter-cyclical import tier, leveraging seasonal harvesting inversion to serve North American off-peak demand gaps.
| Leading Market Players |
|---|
| Indiana Pumpkin Growers Cooperative |
| Pennsylvania Pumpkin Growers Association |
| Libby's |
| Washington Fresh Pumpkin Producers |
| Michigan Pumpkin Growers Association |
| Pumpkin Patch Fundraisers Inc. |
| California Giant Berry Farms |
| Panama Fresh Produce Exporters |
| Libby, McNeill & Libby |
| Others |
Supply & Pricing Matrix
Chef-driven cultivar specification in Chicago and New York metropolitan clusters forces supply response toward discrete variety contracts, compressing commodity auction volumes and amplifying price premiums for Brix-standardized sugar pumpkins.
Pricing Analysis
Outcome-based pricing anchored to consistent sugar content and fiber profile separates USDA-certified organic sugar pumpkins from conventional grades. Three-tier pricing structure across premium heirloom, standard processing, and economy feed-grade levels reflects certification investment and channel control. Cost compression in commodity tiers intensifies as nitrogen fertilizer volatility erodes Illinois and Indiana grower margins. Food processing companies exhibit lowest price sensitivity due to backward integration, while ornamental retail channels face highest elasticity during off-peak windows.
Supply Chain Analysis
Post-harvest cull recovery and seed oil extraction flows extend value capture from processing residuals into livestock feed and cosmetics channels. Geographic concentration in the United States, Mexico, and Panama creates hemispheric sourcing anchored to seasonal inversion. Input dependencies rest on nitrogen fertilizers, controlled-atmosphere storage infrastructure, and phytosanitary certification capacity. Single-source vulnerability concentrates in Midwest processing clusters exposed to localized weather events. Distribution runs through cooperative direct-to-retail networks, backward-integrated processor contracts, and counter-cyclical import channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-atmosphere storage technology is displacing conventional post-harvest handling, rewarding capital-deploying handlers with extended marketable shelf life and smoothed seasonal price curves.
For Market Incumbents: Deepen backward integration into Illinois and Indiana growing operations to secure captive supply against Panama Fresh Produce Exporters' counter-cyclical import threat. Expand controlled-atmosphere storage capacity in Michigan distribution hubs. Pursue USDA organic certification across contract acreage to defend premium channel access as clean-label mandates tighten retailer procurement policies. For New Entrants and Emerging Players: The mid-tier price gap between heirloom direct-to-restaurant premiums and commodity processing contracts offers white-space entry through specialized sugar pumpkin cultivation for regional Horeca clusters. Target Indiana and Pennsylvania cooperative-adjacent geographies with direct sourcing relationships. Launch via chef-specific cultivar specification bypassing wholesale auction infrastructure. For Investors and Strategic Acquirers: The window for entry favors handlers with controlled-atmosphere storage infrastructure and USDA-certified organic acreage positions. Long-term viability centers on climate-resilient sourcing diversification and traceability system integration. Monitor FDA produce safety rule enforcement intensity as inflection signal for compliance cost barriers affecting smaller grower cooperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Growing Operations | Libby's Illinois acreage control secures captive supply for high-volume pureed formats. |
| Controlled-Atmosphere Storage Expansion | Michigan distributors deploy CA systems to extend marketable shelf life across Thanksgiving demand windows. |
| USDA Organic Certification Investment | Three-year transition requirement locks conventional acreage out of premium retail pricing tiers. |
| Direct-to-Horeca Channel Development | Chicago and New York chef contracts bypass wholesale auctions for specification-grade cultivars. |
| Counter-Cyclical Import Positioning | Panama Fresh Produce Exporters exploits hemispheric season inversion to fill North American off-peak gaps. |
Research Methodology
USDA National Agricultural Statistics Service, FDA produce safety guidance documents, and state-level agricultural extension reports formed the secondary backbone, supplemented by customs records and cooperative financial disclosures. Primary interviews with pumpkin growers, food processing procurement managers, Horeca chefs, and controlled-atmosphere storage operators were combined with secondary validation. Bottom-up and top-down triangulation anchored volume estimates to acreage surveys and processing capacity utilization rates.
Bottom-up modeling of cultivar-specific planting decisions and top-down demand aggregation across end-use segments structured the analytical framework. Segmentation dimensions included product type, processing form, application category, and end-user archetype across the projection horizon. CAGRs were derived from trend extrapolation of acreage shifts and price premium persistence. Forecast inputs incorporated climate volatility patterns and organic certification transition timelines.
Inputs from USDA crop reports and FDA traceability guidance were available through the study window; gaps in real-time Horeca procurement contract terms introduce uncertainty bands around direct-to-restaurant volume estimates. Forecasts reflect assumptions regarding clean-label mandate persistence and nitrogen fertilizer price stabilization. Practitioners should monitor FDA Food Safety Modernization Act enforcement intensity and FSSAI fortification guideline revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
South Africa Fruits and Vegetables Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Spain Lime Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Aegle Marmelos Market