
 Europe Freeze-Dried Fruits and Vegetable Market | 2026-2036
Europe Freeze-Dried Fruits and Vegetable Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Freeze-Dried Fruits and Vegetable Market Foresight
Supermarket private-label sourcing is fragmenting across multiple specialized suppliers rather than consolidating under single vendors. European Freeze Dry leverages its UK manufacturing base to supply major retail chains with own-brand freeze-dried fruit lines. Van Drunen Farms anchors its position through backward integration into raw fruit cultivation in the Netherlands and Poland. Chaucer Foods Ltd differentiates via R&D intensity in customized ingredient blends for bakery and confectionery clients.
Freeze-dried fruits and vegetables undergo sublimation dehydration at pressures below 611 pascals and temperatures typically ranging from minus 40 to minus 10 degrees Celsius, preserving cellular structure, color, and nutrient density for shelf-stable food applications. The fruits segment dominates current volume as berry and tropical varieties command premium placement in breakfast and snack categories. Online distribution channels represent the fastest-growing structural avenue, though bulk suppliers still occupy the deepest margin pools through long-term contracts with industrial food manufacturers.
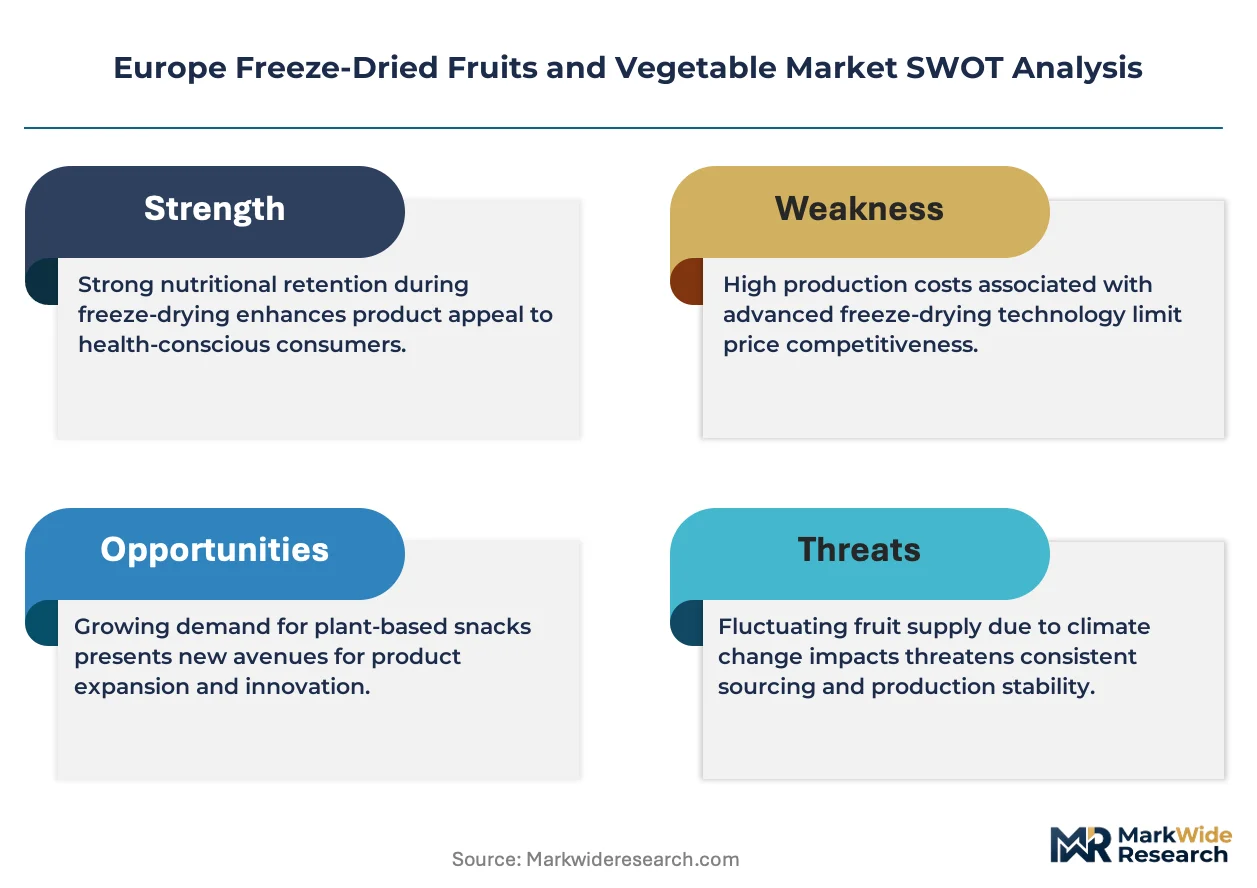
EFSA nutritional labeling requirements and EU Green Deal sustainability benchmarks shape product formulation and energy disclosure obligations for processors across member states. REACH compliance for packaging materials and the F-Gas Regulation governing refrigeration systems in lyophilization equipment add layered compliance costs that favor scaled operators with dedicated regulatory teams. Stakeholders must monitor how proposed amendments to the EU Packaging and Packaging Waste Regulation will alter permissible formats for single-serve freeze-dried snack portions.
Market Dynamics
The EU Green Deal is compressing energy-intensive lyophilization margins while food service procurement contracts consolidate around suppliers with verified low-carbon processing footprints. German industrial buyers now require ESG-linked sourcing documentation for freeze-dried inputs.
Growth Catalysts
- EU Green Deal energy benchmarks:Manufacturers investing in renewable-powered lyophilization equipment qualify for accelerated permitting and green financing instruments.
- Ready-meal formulation demand:Food service operators across France and Italy are expanding freeze-dried vegetable inclusions in shelf-stable prepared dishes.
- Berry cultivation clusters:Polish and Dutch fruit growers are securing long-term supply agreements with processors through cooperative backward integration models.
Market Restraints
- Natural gas price volatility:Sublimation dehydration requires sustained thermal energy input, exposing processors to input cost swings that erode contract margins.
- Equipment supply concentration:Lyophilization machinery production concentrates among German and Swiss engineering firms, creating procurement bottlenecks for capacity expansion.
- Spray-dried substitutes:Lower-cost dehydrated fruit powders from drum-drying operations compete for inclusion in mass-market bakery and confectionery applications.
Strategic Opportunities
- Portuguese and Spanish procurement:Iberian food manufacturers currently source limited freeze-dried volumes, presenting first-mover expansion potential for established processors.
- Plant-based meat analogues:Freeze-dried vegetable texturizers are penetrating European alt-protein formulations as clean-label binding agents.
- Online direct-to-consumer channels:Specialty snack brands are building subscription models around single-serve freeze-dried fruit packs, bypassing traditional retail slotting fees.
Industry Challenges
- Lyophilization technician scarcity:Specialized operators capable of managing vacuum pressure calibration and sublimation cycle optimization command premium wages amid limited training pipelines.
- REACH packaging compliance timelines:Material safety dossiers for novel biodegradable snack pouches extend certification cycles, delaying product launches.
- Legacy ERP integration:Batch tracking systems for EU traceability mandates require costly middleware development to interface with existing manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Freeze-Dried Fruits and Vegetable Market |
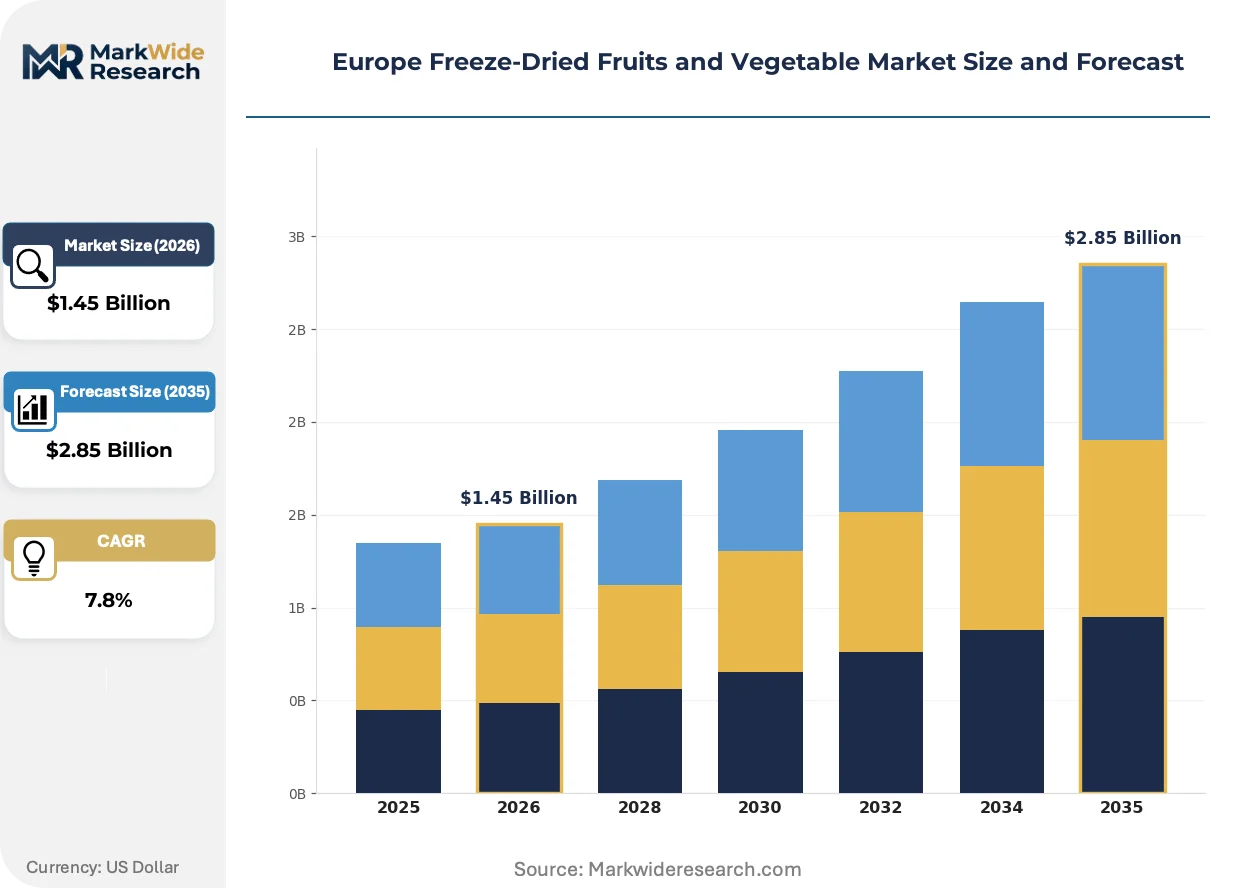
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Mixed, Snacks End User: Food Manufacturers, Retailers, Food Service, Households Distribution Channel: Online, Supermarkets, Specialty Stores, Bulk Suppliers Packaging Type: Bags, Jars, Pouches, Vacuum Sealed |
| Companies Covered | Chaucer Foods Ltd, European Freeze Dry, Van Drunen Farms, Paradise Fruits Solutions, Döhler GmbH, Berrifine A/S, GreenField Sp. z o.o., Binder International, Freeze-Dry Foods GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Freeze-Dried Fruits and Vegetable Market Shifts & Advancements
Energy recovery systems and alternative refrigeration architectures are disrupting conventional lyophilization economics. Processors are reengineering thermal loops to capture waste heat and reduce carbon intensity per kilogram of finished product.
Heat pump-assisted lyophilization is migrating from pilot installations to commercial-scale fruit processing lines in the Netherlands. Dutch ingredient suppliers are retrofitting existing vacuum chambers with closed-loop refrigerant systems that cut electricity consumption per batch. This technology is compressing the operating cost gap between European and lower-labor-cost production regions.
REACH amendments on persistent organic pollutants are tightening purity thresholds for freeze-dried fruit imports entering EU customs territory. Processors must now submit expanded contaminant screening data for berry concentrates sourced from non-EU cultivation zones. German and French border inspection posts are deploying enhanced chromatography testing protocols, extending clearance times for bulk shipments.
Industrial procurement teams are consolidating supplier rosters around vertically integrated processors with captive raw material supply. Bakery and confectionery manufacturers in Belgium and Austria are reducing their approved vendor lists from twelve to four qualified sources. This concentration is most visible in Germany, where Müller and Rewe Group affiliates now mandate single-source contracts for private-label freeze-dried strawberry inclusions.
Europe Freeze-Dried Fruits and Vegetable Market Segmentation
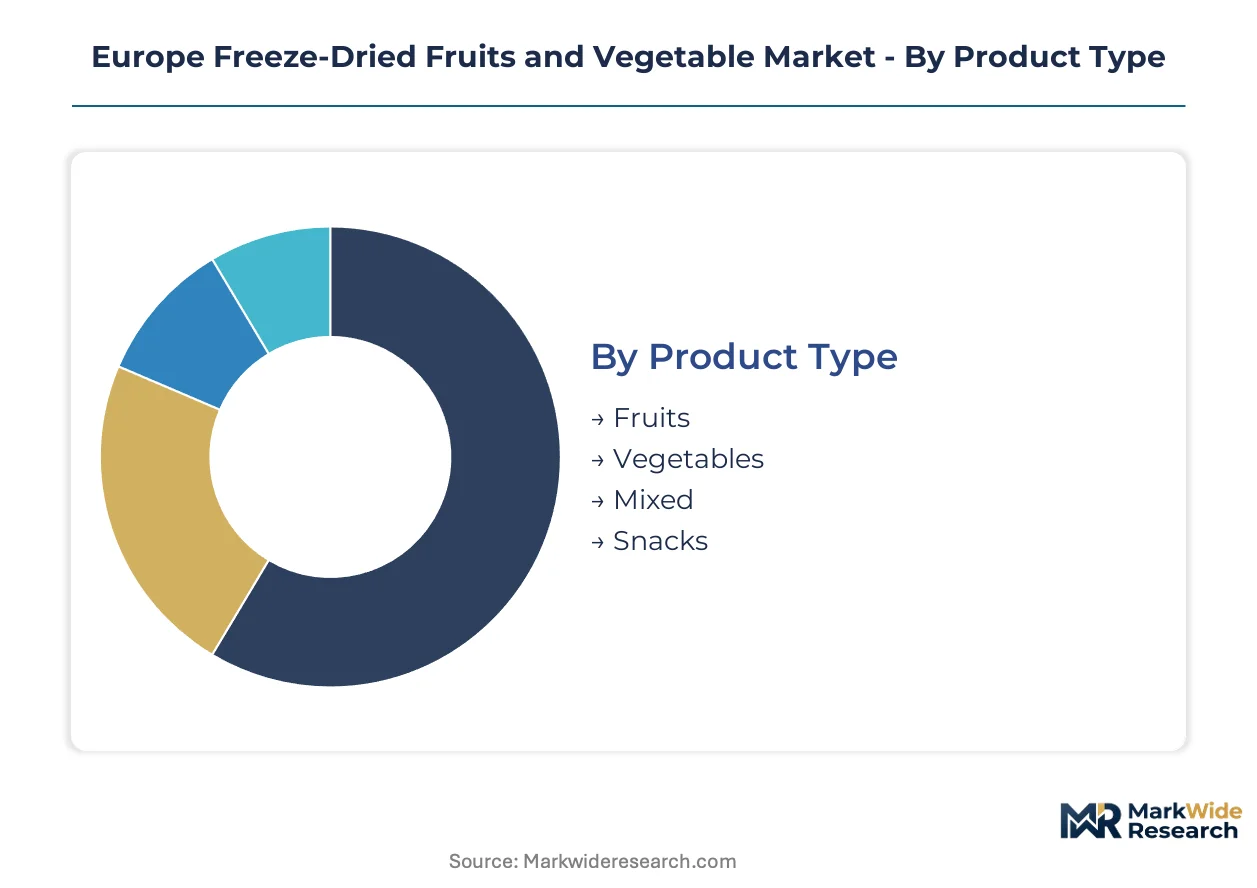
Freeze-dried fruit and vegetable procurement patterns diverge sharply across buyer types, with industrial formulators prioritizing bulk consistency while snack brands chase single-serve novelty. Packaging and channel choices increasingly reflect ESG compliance burdens rather than pure cost optimization.
Product Type:
Formulators select from distinct cellular preservation levels depending on end-use texture requirements and rehydration protocols.
- Fruits:Berry and tropical varieties dominate breakfast cereal and confectionery inclusions across German and French manufacturing lines. Müller and Rewe Group affiliates now mandate single-source contracts for private-label freeze-dried strawberry inputs, compressing supplier rosters.
- Vegetables:Shelf-stable vegetable pieces penetrate ready-meal formulations in France and Italy as clean-label texturizers. Food service operators expanding freeze-dried vegetable inclusions face EU Green Deal energy disclosure obligations for processed ingredients.
- Mixed:Blended fruit-vegetable formats target smoothie and nutrition bar applications with standardized rehydration ratios.
- Snacks:Single-serve packs bypass traditional retail slotting fees through direct-to-consumer subscription models.
Established volume favors Fruits; emerging adoption favors Snacks.
End User:
Procurement scale and technical specification intensity separate industrial buyers from fragmented household demand.
- Food Manufacturers:Bakery and confectionery producers in Belgium and Austria reduced approved vendor lists from twelve to four qualified sources. Belgian chocolate processors specify particle size distributions below 2mm for freeze-dried raspberry inclusions.
- Food Service:Ready-meal formulators in France and Italy require ESG-linked sourcing documentation under German industrial buyer pressure.
- Retailers:Supermarket private-label sourcing fragments across specialized suppliers rather than consolidating under single vendors.
- Households:Online subscription models for specialty snack packs gain traction among urban consumers seeking portable nutrition formats.
Contract concentration favors Food Manufacturers; channel experimentation favors Households.
Distribution Channel:
Margin depth and buyer relationship durability vary inversely across direct-to-consumer and bulk contract pathways.
- Bulk Suppliers:Long-term contracts with industrial food manufacturers occupy the deepest margin pools. German engineering firms concentrate lyophilization machinery production, creating procurement bottlenecks for capacity expansion.
- Online:Specialty snack brands build subscription models around single-serve freeze-dried fruit packs. EFSA nutritional labeling requirements shape product formulation for direct-to-consumer shipments.
- Supermarkets:European Freeze Dry leverages its UK manufacturing base to supply major retail chains with own-brand freeze-dried fruit lines.
- Specialty Stores:Premium positioning targets health-conscious consumers seeking organic certification and origin transparency.
Margin stability favors Bulk Suppliers; expansion velocity favors Online.
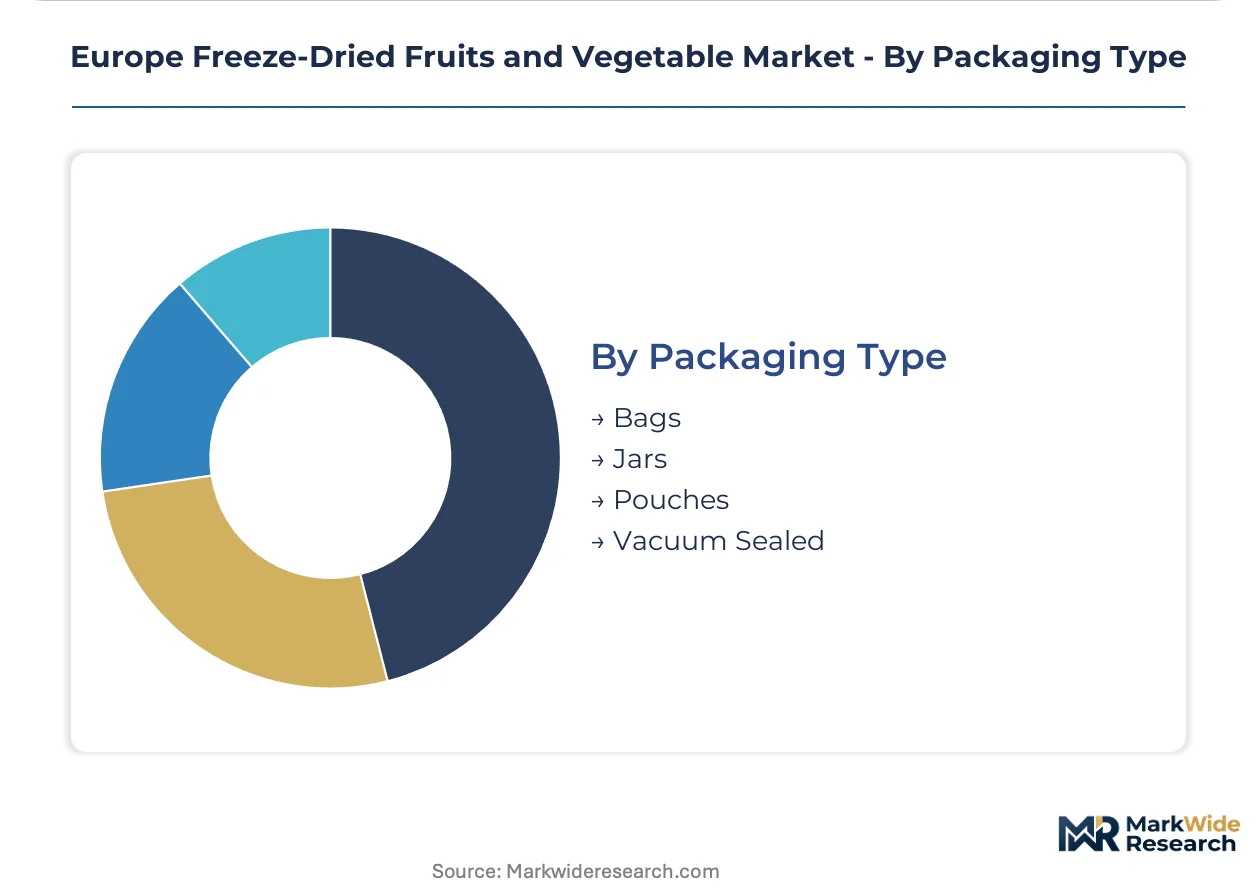
Packaging Type:
REACH compliance timelines and EU Packaging and Packaging Waste Regulation amendments reshape permissible formats.
- Pouches:Novel biodegradable snack pouches face extended material safety dossier certification cycles. REACH amendments on persistent organic pollutants tighten purity thresholds for imported berry concentrates.
- Bags:Standard flexible packaging dominates breakfast cereal ingredient shipments to industrial formulators.
- Jars:Premium retail positioning for whole freeze-dried strawberries and tropical fruit medleys in German and Austrian specialty outlets.
- Vacuum Sealed:Extended shelf-life protocols for emergency food supply and military procurement contracts.
Regulatory headwinds concentrate on Pouches; incumbent volume rests with Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial buyers extract favorable contract terms through volume concentration, while Polish processors compete on cultivation proximity and cooperative supply structures. This pricing-power asymmetry shapes procurement patterns across the continent.
Germany
Müller and Rewe Group affiliates mandate single-source contracts for private-label freeze-dried strawberry inputs, compressing supplier rosters to four qualified sources. The EU Green Deal's energy benchmarks accelerate permitting for renewable-powered lyophilization investments. Bavarian engineering firms concentrate lyophilization machinery production, creating procurement bottlenecks for capacity expansion across Europe.
Netherlands
Van Drunen Farms anchors its position through backward integration into raw fruit cultivation, securing long-term supply agreements with processors. EFSA nutritional labeling requirements shape product formulation for retail-bound shipments. Dutch ingredient suppliers in the Eindhoven region retrofit vacuum chambers with closed-loop refrigerant systems that cut electricity consumption per batch.
Poland
Berry cultivation clusters secure cooperative backward integration models with processors seeking cultivation proximity. REACH compliance for packaging materials adds layered costs that favor scaled operators with dedicated regulatory teams. Warsaw-based cooperatives supply German industrial buyers who now require ESG-linked sourcing documentation for freeze-dried inputs.
France
Ready-meal formulators expand freeze-dried vegetable inclusions in shelf-stable prepared dishes under food service operator pressure. The EU Packaging and Packaging Waste Regulation amendments alter permissible formats for single-serve snack portions. Lyon and Paris manufacturing corridors concentrate bakery and confectionery procurement teams reducing approved vendor lists from twelve sources.
United Kingdom
European Freeze Dry leverages its UK manufacturing base to supply major retail chains with own-brand freeze-dried fruit lines. The F-Gas Regulation governing refrigeration systems in lyophilization equipment adds compliance costs favoring scaled operators. London-headquartered supermarket private-label sourcing fragments across multiple specialized suppliers rather than consolidating under single vendors.
Europe Freeze-Dried Fruits and Vegetable Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, capturing margin through cultivation control and equipment differentiation. The vendor base organizes around three strategic tiers: vertically integrated processors with captive raw material supply, specialized ingredient blenders serving bakery and confectionery channels, and regional fabricators competing on logistics proximity. Consolidation pressures concentrate procurement rosters, while technology licensing and capacity expansion emerge as dominant competitive moves.
Within the vertically integrated tier, Van Drunen Farms and European Freeze Dry exemplify archetypes of cultivation-backed processing and retail-facing manufacturing respectively. Chaucer Foods Ltd occupies a position among R&D-intensive specialists customizing ingredient blends for specific end-use applications. These three anchors illustrate how competitive positioning stratifies between upstream supply control and downstream formulation expertise.
| Leading Market Players |
|---|
| Chaucer Foods Ltd |
| European Freeze Dry |
| Van Drunen Farms |
| Paradise Fruits Solutions |
| Döhler GmbH |
| Berrifine A/S |
| GreenField Sp. z o.o. |
| Binder International |
| Freeze-Dry Foods GmbH |
| Others |
Supply & Pricing Matrix
Natural gas price volatility determines both pricing tier spreads and supply chain shape across European freeze-dried fruit and vegetable processing. Sustained thermal energy requirements for sublimation dehydration expose contract margins to input cost swings, compressing the gap between standard bulk formulations and premium customized blends while forcing procurement teams toward suppliers with renewable-powered capacity.
Pricing Analysis
The customization-premium spread separates standard berry and tropical fruit inputs from configured-to-order particle specifications and proprietary blend formulations. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and volume scale, with Belgian chocolate processors paying premiums for sub-2mm raspberry inclusions. Pricing pressure stems from spray-dried substitutes competing for mass-market bakery applications. Industrial food manufacturers exhibit lowest price sensitivity due to long-term contract structures, while direct-to-consumer snack brands face acute margin compression from retail slotting fee avoidance.
Supply Chain Analysis
Contract-manufacturing concentration rests with German and Swiss engineering firms controlling lyophilization machinery production, creating procurement bottlenecks for capacity expansion. Raw material supply draws from Polish and Dutch berry cultivation clusters, German strawberry cooperatives, and tropical fruit import channels. Single-source vulnerability concentrates in vacuum chamber equipment and specialized technician labor pools. Distribution runs through bulk supplier long-term contracts with industrial manufacturers, supplemented by online direct-to-consumer subscription channels for specialty snack formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Freeze-Dried Fruits and Vegetable Market functions as a service-attach opportunity where energy recovery system retrofits and sublimation cycle optimization consulting expand faster than base ingredient volumes. Recurring-revenue layers from technical service contracts and ESG compliance documentation outpace commodity margin growth.
For Market Incumbents: Entrench position through captive renewable energy installations and dedicated regulatory affairs teams capable of navigating REACH packaging amendments and F-Gas refrigeration compliance. Defend against heat pump-assisted lyophilization disruptors by locking in multi-year German industrial buyer contracts with ESG-linked sourcing documentation. Prioritize backward integration into Polish and Dutch berry cultivation to secure raw material control. For New Entrants and Emerging Players: Build out presence in Iberian markets where Portuguese and Spanish food manufacturers currently source limited freeze-dried volumes. Plant-based meat analogue applications offer the most penetrable segment for clean-label vegetable texturizers. Establish go-to-market positioning through direct-to-consumer subscription models bypassing traditional retail slotting fees, leveraging EFSA nutritional labeling expertise as a differentiation anchor. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation amendments reshape the acquisition landscape toward processors with biodegradable pouch certification capabilities and closed-loop refrigerant infrastructure. Long-term viability centers on vertically integrated operators with captive cultivation supply and renewable-powered capacity. The signal to watch is German supermarket private-label consolidation toward single-source contracts, indicating preferred supplier status premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable-Powered Capacity Expansion | EU Green Deal accelerated permitting unlocks green financing for Dutch and German retrofit installations. |
| Backward Integration into Cultivation | Polish and Dutch cooperative supply structures secure long-term raw material agreements with processors. |
| Heat Pump Retrofit Deployment | Eindhoven-region closed-loop refrigerant systems cut electricity consumption per sublimation batch. |
| Direct-to-Consumer Channel Launch | Online subscription models bypass Rewe and Müller affiliate slotting fees for specialty snack brands. |
| ESG Documentation Service Layer | German industrial buyer mandates for verified low-carbon processing footprints create recurring compliance revenue. |
Research Methodology
A standing panel of lyophilization equipment engineers, procurement leads at German and French industrial food manufacturers, Dutch cooperative cultivation managers, and EFSA regulatory affairs specialists provided ongoing calibration. Primary interviews with bakery and confectionery formulators, food service ready-meal developers, and supermarket private-label buyers combined with secondary validation from EU customs trade data, ECHA REACH dossier filings, SEC disclosures by listed ingredient suppliers, and energy consumption reports from Dutch processing clusters. Bottom-up volume modeling and top-down value triangulation anchored projections.
Scenario-bracketing framed analytical development across conservative, baseline, and expansion pathways over the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and packaging format alongside energy intensity tier and ESG certification status. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated natural gas price volatility scenarios and lyophilization machinery lead time fluctuations.
Sensitivities concentrate around EU Green Deal energy benchmark amendments, REACH packaging material purity threshold revisions, and F-Gas refrigeration system phase-out schedules. Forecasts reflect documented assumptions regarding cooperative supply structure stability and German industrial buyer contract concentration trends. Quarterly review of ECHA regulatory proposal timelines and Iberian food manufacturer procurement expansion indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Fresh Berries Market
Fruits and Vegetables
Passion Fruit Extract Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
Cucumber and Gherkins Market
Fruits and Vegetables
Dried Apple Peel Market