
 In-Cabin Monitoring System (ICMS) Market | 2026-2036
In-Cabin Monitoring System (ICMS) Market Size, Share, and Industry Trends Forecast 2026-2036
In-Cabin Monitoring System (ICMS) Market Insights
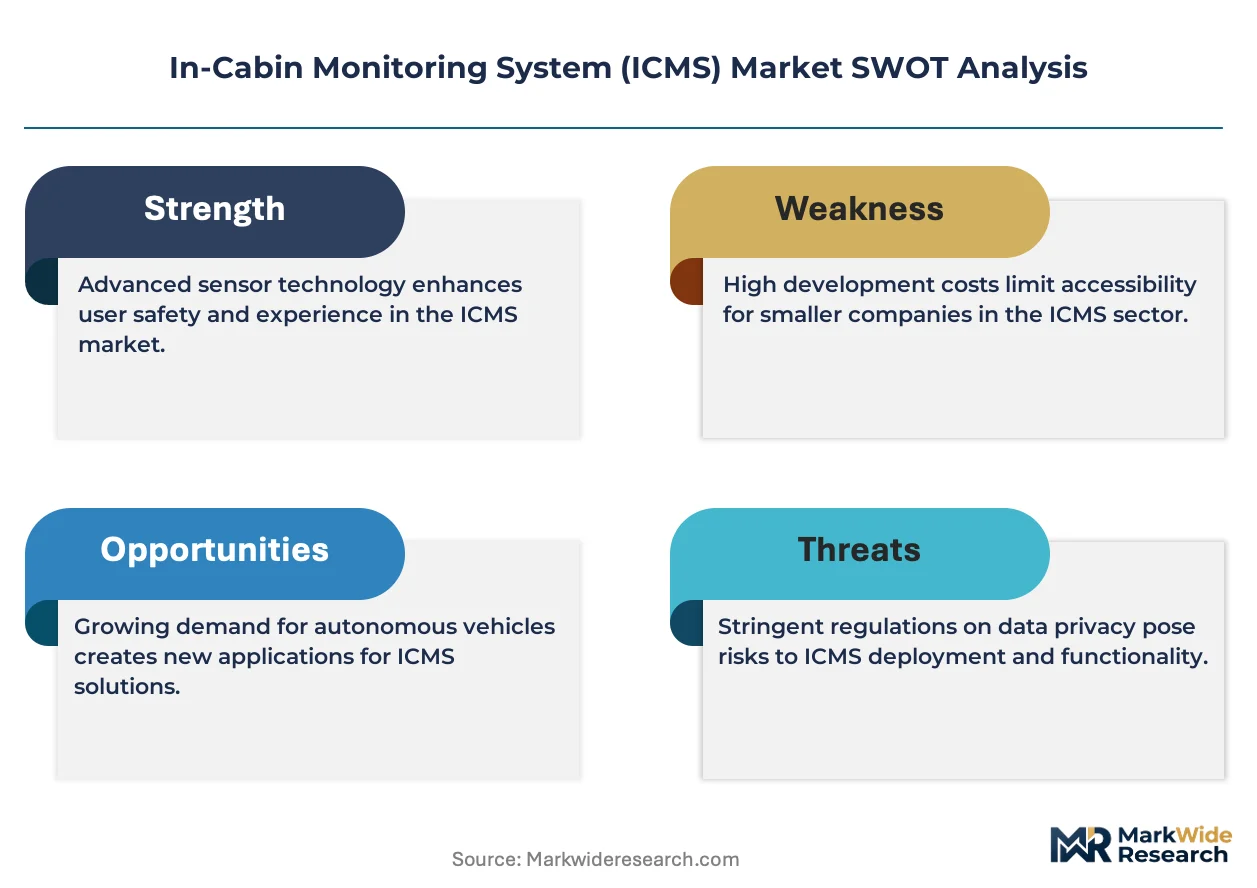
Subscription-based hardware-as-a-service leasing for ICMS sensor suites is rewriting competitive entry barriers for tier-two suppliers. Bosch leverages captive semiconductor fabrication to sustain cost advantages across radar-based cabin sensing modules. Continental anchors European OEM relationships through integrated camera-radar fusion platforms. Vayyar competes on software-defined imaging radar that eliminates dedicated optical components in cost-sensitive vehicle segments.
An In-Cabin Monitoring System integrates multimodal sensors—typically near-infrared cameras operating at 940 nm wavelength, millimeter-wave radar, and capacitive proximity detectors—to track occupant position, gaze direction, biometric state, and gesture inputs in real time. These systems serve the primary commercial purpose of preventing distracted driving fatalities, enabling adaptive airbag deployment, and supporting conditional automation handback protocols. Camera-based technology dominates current installations due to mature computer vision pipelines and established automotive supply chains, while radar segments capture fastest-growing interest where privacy regulations restrict optical imaging in shared mobility contexts. OEM end users represent the deepest margin pool as factory-integrated systems command higher ASPs and longer contract durations than aftermarket retrofits.
The European New Car Assessment Programme mandates child presence detection and driver drowsiness monitoring for maximum safety ratings, compelling OEMs to source certified ICMS architectures. NHTSA in the United States advances rulemaking on distraction mitigation systems, while China's MIIT integrates cabin sensing requirements into intelligent vehicle standards. Stakeholders must monitor divergence between privacy-first radar deployments in European markets and camera-dominant configurations in Asian regulatory environments.
Market Dynamics
Euro NCAP's revised safety assessment protocols now mandate occupant status sensing for five-star ratings, forcing OEMs to redesign vehicle electrical architectures around multi-sensor ICMS integration rather than treating cabin monitoring as optional equipment.
Growth Catalysts
- Regulatory mandates:Euro NCAP protocols require child presence detection and driver drowsiness monitoring for maximum safety ratings, compelling factory installation of certified ICMS architectures across European vehicle lineups.
- Electric vehicle platforms:Battery-electric vehicle architectures provide cleaner power and data backbone integration for multi-modal sensor suites compared to legacy internal combustion electrical systems.
- Conditional automation:SAE Level 2+ and Level 3 systems require reliable driver state monitoring for safe handback protocols, embedding ICMS as functional safety-critical components rather than comfort features.
Market Restraints
- Semiconductor supply concentration:Specialized near-infrared image sensors and millimeter-wave radar front-ends depend on concentrated Asian foundry capacity, exposing OEMs to allocation volatility.
- Privacy regulatory friction:GDPR and emerging biometric data frameworks in European jurisdictions impose strict consent and data minimization requirements that complicate camera-based cabin monitoring deployments.
- Cost structure pressure:Multi-sensor fusion architectures with dedicated ECUs and wiring harness modifications add substantial bill-of-materials burden to mass-market vehicle segments.
Strategic Opportunities
- Software-defined radar imaging:4D imaging radar platforms eliminate dedicated optical components while maintaining occupant detection accuracy, opening shared mobility and fleet vehicle segments where privacy concerns restrict camera deployment.
- Hardware-as-a-service leasing:Subscription-based sensor suite provisioning reduces upfront capital requirements for tier-two suppliers seeking OEM qualification.
- Aftermarket retrofit channels:Aging vehicle parc in North American and European markets creates demand for standalone child-left-behind alert systems that integrate through OBD-II or dedicated power connections.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-B and ASIL-C qualification for occupant detection algorithms extends development cycles and requires specialized verification engineering capacity.
- Sensor calibration complexity:Multi-modal fusion demands precise spatial and temporal alignment between camera, radar, and capacitive proximity channels, complicating manufacturing line integration and field service procedures.
- Legacy platform electrical constraints:Older vehicle architectures lack sufficient power distribution and high-speed data backbone capacity to support full ICMS functionality without substantial harness redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Cabin Monitoring System (ICMS) Market |
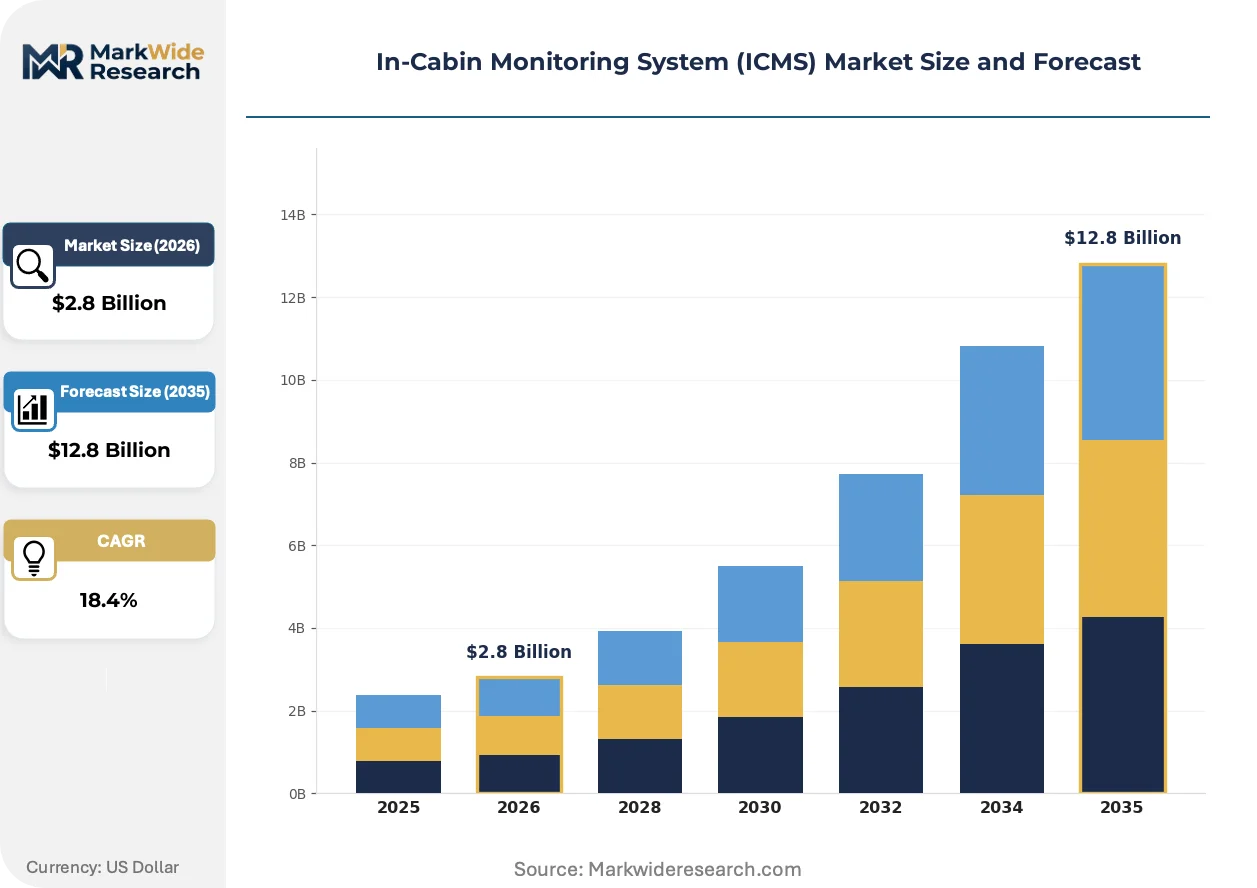
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera-Based, Radar, Lidar, Ultrasonic Application: Driver Monitoring, Passenger Monitoring, Safety Alerts, Gesture Recognition End User: OEMs, Fleet Operators, Aftermarket Providers, Ride-Sharing Companies Deployment Model: On-Premises, Cloud-Based, Hybrid, Standalone |
| Companies Covered | Continental, Bosch, Infineon Technologies, Vayyar, Aptiv, Seeing Machines, Cipia, LG Electronics, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Cabin Monitoring System (ICMS) Market Trends and Innovations
Sensor fusion architectures are actively displacing single-modality cabin monitoring as OEMs pursue redundancy for functional safety compliance and regulatory certification. Three developments dominate current engineering investment.
Near-infrared camera systems operating at 940 nm wavelength are hybridizing with millimeter-wave radar front-ends to create redundant occupant detection pipelines. Premium electric vehicle platforms from German OEMs are adopting these fused architectures first, driven by Euro NCAP timeline pressure. This hybridizing approach compresses the market opportunity for standalone optical-only suppliers while elevating software integration capabilities as the primary competitive differentiator.
The European Union AI Act establishes risk classification frameworks for biometric identification systems deployed in vehicles, categorizing real-time emotion recognition and driver identification as high-risk applications. Industrial consequence includes mandatory conformity assessment procedures and human oversight requirements that extend product development timelines. Camera-dominant ICMS configurations face the most acute compliance burden, accelerating radar-first design pivots among suppliers serving European OEM programs.
Fleet operators and mobility-as-a-service providers are unbundling ICMS hardware procurement from long-term data analytics subscriptions. This purchasing pattern shift disrupts traditional component supply relationships and elevates software platform vendors who can demonstrate recurring revenue models. The transformation is most visible in German and French urban mobility deployments where municipal procurement guidelines favor operational expenditure structures over capital-intensive vehicle specification.
In-Cabin Monitoring System (ICMS) Market Segmentation
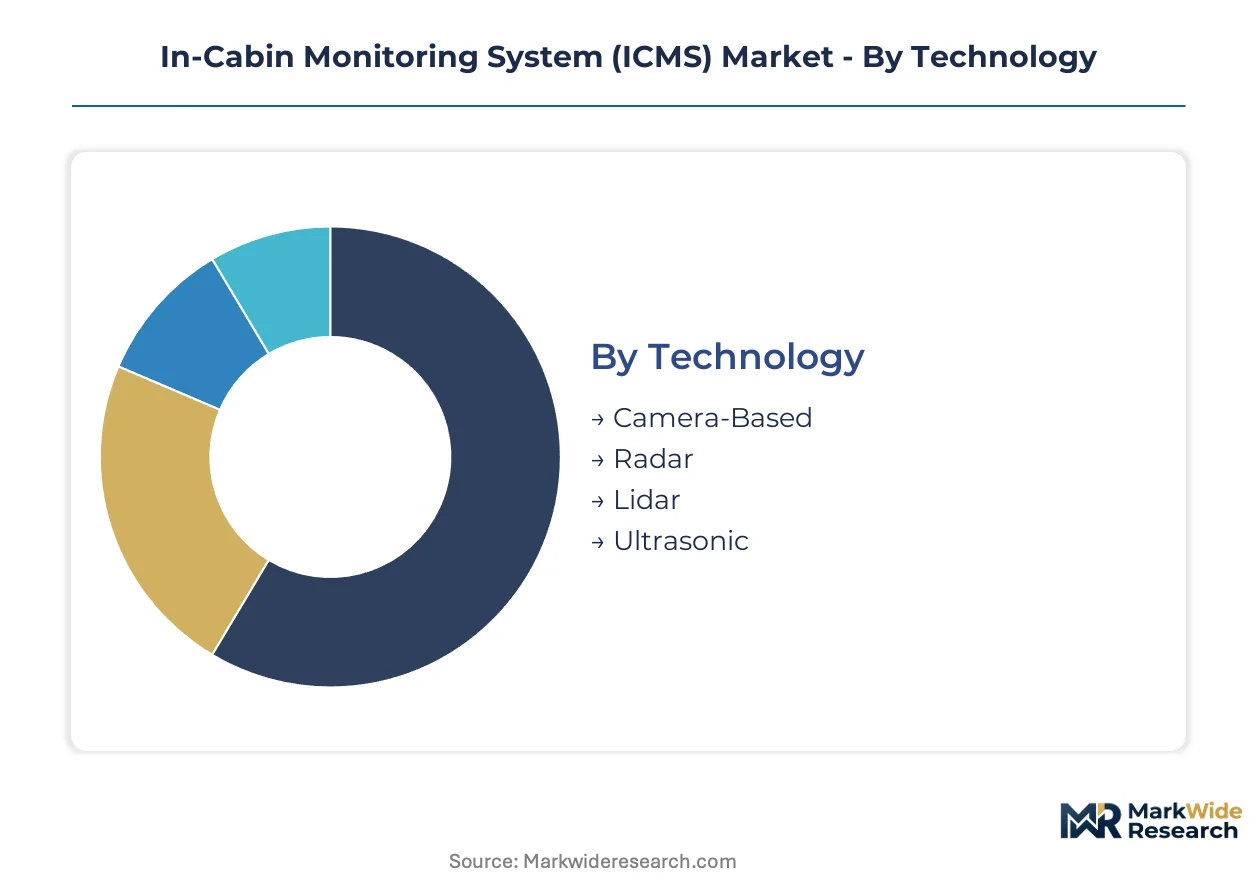
ICMS architectures fragment across sensing modalities, functional applications, and procurement channels. Each dimension carries distinct margin profiles, certification requirements, and competitive intensity that shape supplier positioning.
Technology:
Cost tier separates mature optical pipelines from emerging radio-frequency alternatives with divergent privacy compliance burdens.
- Camera-Based:Near-infrared imagers at 940 nm wavelength leverage established automotive vision pipelines. German premium OEMs concentrate procurement for Euro NCAP-compliant driver state monitoring, though GDPR biometric restrictions constrain deployment flexibility.
- Radar:Millimeter-wave and 4D imaging radar eliminate optical privacy exposure while maintaining occupant detection accuracy. Shared mobility operators in France and Germany prioritize this modality for fleet vehicles where passenger consent management proves operationally prohibitive.
- Lidar:Solid-state and scanning laser systems deliver precise cabin volumetric mapping for advanced airbag deployment optimization.
- Ultrasonic:Low-cost proximity detection for basic child-left-behind alerts in aftermarket retrofit applications.
Camera-Based holds installed capacity. Radar is rotating up the share rankings.
Application:
Functional purpose determines sensor fusion complexity and regulatory certification stringency.
- Driver Monitoring:Gaze tracking, head pose estimation, and drowsiness classification demand sub-100ms latency pipelines. Euro NCAP mandates drive factory integration across European vehicle lineups, with German OEMs specifying multi-sensor redundancy for Level 2+ automation handback protocols.
- Safety Alerts:Child presence detection and forgotten occupant warnings trigger immediate cabin climate intervention. Regulatory mandates in Germany, France, and Italy accelerate deployment, though thermal runaway protection in electric vehicles adds electrical architecture constraints.
- Passenger Monitoring:Seat occupancy classification and position tracking for adaptive restraint deployment.
- Gesture Recognition:Touchless HMI control for infotainment and climate functions, primarily in premium segments.
Driver Monitoring commands certification resources. Safety Alerts is gaining share fastest.
End User:
Customer type dictates contract structure, volume predictability, and software monetization potential.
- OEMs:Factory-integrated systems with ASIL-B/ASIL-C functional safety requirements command longest contract durations and deepest engineering collaboration. BMW, Mercedes-Benz, and Volkswagen anchor European demand through multi-sensor architectures specified at vehicle platform inception.
- Fleet Operators:Municipal and commercial vehicle pools in Germany and France unbundle hardware procurement from analytics subscriptions, favoring operational expenditure models over capital-intensive specification.
- Aftermarket Providers:Standalone child-left-behind systems targeting aging vehicle parc through OBD-II integration.
- Ride-Sharing Companies:Privacy-first radar configurations for passenger monitoring without biometric data retention liability.
OEMs anchor volume commitments. Fleet Operators are climbing the fastest.
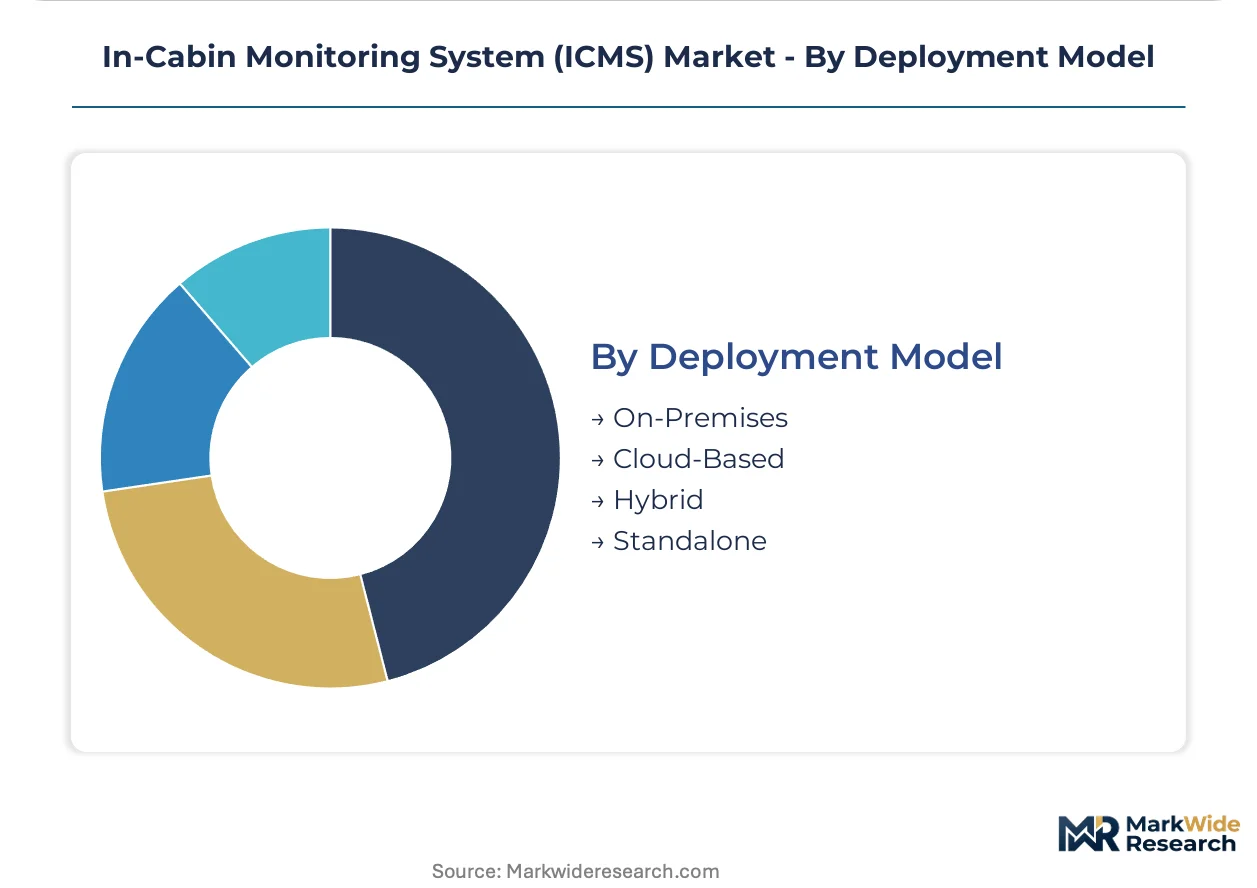
Deployment Model:
Architecture choice balances real-time processing requirements against update flexibility and data sovereignty constraints.
- On-Premises:Dedicated ECU processing with deterministic latency for safety-critical functions. German OEMs specify this architecture for driver monitoring to satisfy ISO 26262 timing requirements and minimize cybersecurity attack surface.
- Hybrid:Edge preprocessing with cloud analytics for fleet-wide pattern recognition and model refinement. French mobility operators deploy this structure to satisfy CNIL data localization guidance while enabling centralized safety monitoring.
- Cloud-Based:Full sensor data transmission for centralized AI inference, constrained by bandwidth cost and privacy regulation.
- Standalone:Self-contained units without vehicle network integration, typical of aftermarket retrofits.
On-Premises holds safety-critical certification. Hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial trade surplus in ICMS components, exporting radar modules and camera systems to assembly plants across Eastern Europe and North America while importing specialized near-infrared sensors from Asian foundries. China runs a structural deficit in automotive-grade millimeter-wave radar front-ends, relying on German and Japanese suppliers despite aggressive domestic capacity expansion. The United States exhibits balanced flows in software IP and cloud analytics platforms, importing hardware while exporting algorithm licensing to European OEMs.
Germany
BMW, Mercedes-Benz, and Volkswagen drive procurement of multi-sensor fusion architectures across premium and mass-market electric vehicle platforms. KBA vehicle type approval requirements mandate certified child presence detection systems for new registrations from 2025 onward. Stuttgart and Munich anchor development activity where Bosch and Continental operate integrated design centers for ASIL-B qualified driver monitoring pipelines.
United States
NHTSA rulemaking on distraction mitigation systems compels domestic OEMs to source compliant ICMS architectures ahead of anticipated mandate timelines. California's privacy regulations impose biometric consent frameworks that favor radar-first deployments in fleet vehicles serving Los Angeles and San Francisco metropolitan areas. Detroit-based engineering centers coordinate Tier 1 supplier qualification for integrated camera-radar platforms targeting Level 2+ automation handback protocols.
China
MIIT intelligent vehicle standards integrate cabin sensing requirements into national connected car certification frameworks, driving domestic OEM adoption of driver fatigue detection systems. BYD, NIO, and XPeng specify multi-modal occupant monitoring for new energy vehicle platforms manufactured in Shenzhen and Hefei production complexes. Yangtze River Delta concentration of automotive electronics manufacturing supports rapid iteration in 940 nm camera module production for cost-sensitive vehicle segments.
Japan
METI automotive safety technology roadmaps prioritize occupant status sensing for aging driver support systems, creating procurement pull from Toyota, Honda, and Nissan. JIS standards development for in-cabin biometric measurement establishes technical foundations for export-oriented supplier certification. Nagoya and Tokyo metropolitan areas concentrate Tier 2 engineering capacity for capacitive proximity sensor integration into compact vehicle architectures.
South Korea
Hyundai Motor Group and Kia embed ICMS functionality into Genesis luxury and mass-market electric vehicle lineups manufactured in Ulsan and Asan complexes. MFDS medical device crossover regulations influence biometric sensor calibration requirements for heart rate and stress monitoring applications. Seoul Capital Area hosts LG Electronics and Samsung component divisions supplying camera modules and radar front-ends to domestic and export OEM programs.
In-Cabin Monitoring System (ICMS) Market Competitive Landscape
On the supply side, the industry is consolidating around multi-sensor fusion capabilities as single-modality suppliers face margin compression from integrated platform sourcing. Tier 1 automotive suppliers with captive semiconductor fabrication and software stacks command premium positioning against modular component vendors. Two strategic archetypes dominate: diversified industrial conglomerates leveraging vertical manufacturing control, and software-defined imaging specialists competing on algorithmic differentiation. Competitive dynamics center on ASIL functional safety certification speed and long-term service contract structures rather than hardware unit pricing alone.
Within the diversified Tier 1 tier, Continental and Bosch exemplify integrated platform providers with established European OEM relationships spanning multi-year vehicle program cycles. Vayyar occupies a distinct position as a software-defined radar specialist competing on privacy-compliant imaging without optical components. Seeing Machines and Cipia represent pure-play driver monitoring software vendors seeking to anchor recurring revenue through fleet analytics subscriptions rather than one-time hardware sales. These three archetypes—integrated conglomerates, radar imaging specialists, and software-centric analytics providers—collectively define competitive positioning across premium and mass-market vehicle segments.
| Leading Market Players |
|---|
| Continental |
| Bosch |
| Infineon Technologies |
| Vayyar |
| Aptiv |
| Seeing Machines |
| Cipia |
| LG Electronics |
| Valeo |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Taiwanese and South Korean foundry capacity for automotive-grade near-infrared image sensors compresses both tier spreads and supplier bargaining power across ICMS procurement channels. OEMs face asymmetric exposure where concentrated semiconductor supply determines whether multi-sensor fusion architectures remain premium-limited or penetrate mass-market vehicle segments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by ASIL certification grade and volume commitment scale. ASIL-C qualified driver monitoring systems with deterministic latency guarantees command substantial premiums over ASIL-B configurations for Level 2+ handback protocols. Pricing pressure stems from tier-two suppliers offering hardware-as-a-service leasing that deflates upfront capital barriers for fleet operators. Aftermarket retrofit providers exhibit highest price sensitivity due to OBD-II integration constraints and consumer discretionary purchase patterns.
Supply Chain Analysis
Extended payment terms from German OEMs strain working capital for tier-two radar module suppliers competing on software-defined imaging platforms. Geographic supply concentrates in Taiwan for specialized near-infrared sensors, South Korea for millimeter-wave radar front-ends, and Germany for ASIL-qualified ECU integration. Raw material dependencies include silicon carbide substrates, gallium arsenide wafers, and automotive-grade resin housings. Single-source vulnerability around 940 nm wavelength sensor fabrication creates allocation risk exposure. Distribution runs through Tier 1 system integrators with captive OEM relationships rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional safety engineering capacity—specifically ISO 26262 ASIL-B/ASIL-C verification expertise—represents the binding constraint separating qualified suppliers from commodity component vendors. OEM procurement teams prioritize suppliers with proven certification velocity over hardware cost optimization.
For Market Incumbents: Insulate ASIL-qualified driver monitoring pipelines from margin erosion by deepening software platform stickiness through recurring analytics subscriptions rather than transactional hardware sales. Threat exposure centers on radar-first entrants eliminating optical components in privacy-sensitive European fleet deployments. Priority lever rests on backward integration into captive semiconductor fabrication for near-infrared sensor supply security. For New Entrants and Emerging Players: Pursue aftermarket child-left-behind alert systems for aging North American vehicle parc as the most penetrable white-space segment. Target OBD-II integrated standalone units where regulatory mandates create demand pull without OEM qualification barriers. Go-to-market angle emphasizes municipal fleet procurement guidelines favoring operational expenditure structures over capital-intensive vehicle specification. For Investors and Strategic Acquirers: Software-defined radar imaging specialists with proven 4D occupancy detection algorithms represent the highest-conviction acquisition archetype. Long-term viability frames around ten-year regulatory tailwinds from Euro NCAP mandate expansion and NHTSA rulemaking convergence. Signal to watch: OEM program awards for privacy-first cabin sensing in shared mobility contracts.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-C Certification Investment | Accelerates OEM qualification timelines for Level 2+ automation handback protocols. |
| Software-Defined Radar Platform Launch | Eliminates optical privacy exposure while maintaining occupant detection accuracy for European fleet operators. |
| Hardware-as-a-Service Leasing Model | Reduces upfront capital barriers for tier-two suppliers seeking OEM program entry. |
| Multi-Sensor Fusion Partnership | Combines Continental's camera-radar integration with Vayyar's imaging radar for premium electric vehicle platforms. |
| Aftermarket OBD-II Distribution Expansion | Captures aging vehicle parc demand for standalone child-left-behind alert systems in North America. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution channel heads, and functional safety certification specialists. Secondary validation drew from KBA vehicle type approval databases, Euro NCAP safety protocol documentation, MIIT intelligent vehicle standards filings, and NHTSA rulemaking dockets. Bottom-up triangulation across sensor shipment volumes and top-down reconciliation against vehicle production forecasts anchored market size estimation.
Calibration against historical ASIL certification timelines and OEM program award patterns informed growth trajectory modeling across the projection horizon. Segmentation dimensions included sensing modality, functional application, end-user archetype, and deployment architecture. CAGRs derived from regression analysis of regulatory mandate phase-in schedules and electric vehicle platform adoption curves. Industry-specific inputs encompassed Euro NCAP timeline pressure and GDPR biometric compliance burden divergence between European and Asian regulatory environments.
Sensitivities concentrate around foundry allocation volatility for specialized automotive sensors and divergence between privacy-first radar deployments and camera-dominant configurations. Forecasts reflect documented assumptions regarding regulatory mandate enforcement consistency and semiconductor supply normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Avalanche Airbags Market
Automotive Safety and Security Systems
Highway Crash Cushion Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Driving Helmet Market