
 Ethanol Vehicle Market | 2026-2036
Ethanol Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Ethanol Vehicle Market Analysis
Capital-intensity divergence between integrated automakers and component-dependent rivals is collapsing as ethanol powertrain development demands captive fuel-system engineering. Ford Motor Company leverages its Brazilian flex-fuel manufacturing base to sustain cost leadership in E85-compatible platforms. General Motors Company anchors its ethanol strategy through modified engine architectures that dominate North American light-truck segments.
An ethanol vehicle is an automobile engineered to operate on ethanol-blended fuels, with flex-fuel variants incorporating elastomer-sealed fuel systems, corrosion-resistant injectors, and engine control modules calibrated for variable alcohol concentrations between 51% and 83%. These vehicles serve commercial and consumer markets seeking petroleum displacement through domestically produced biofuels. The fuel-type dimension shows E85 commanding the value pool due to its maximum petroleum substitution, while E10 maintains volume dominance through regulatory blending floors in conventional gasoline markets. Vehicle-type segmentation reveals flex-fuel vehicles as the fastest-expanding category, though passenger cars still occupy the largest installed base across ethanol-mandate jurisdictions.
The US EPA administers Renewable Fuel Standard volume obligations that mandate escalating ethanol incorporation into transportation fuel pools, while Brazil's ANP enforces RenovaBio carbon-intensity targets that channel investment toward sugarcane ethanol supply chains. These frameworks shape demand by penalizing non-compliant fuel marketers and rewarding low-carbon ethanol production pathways. Stakeholders must monitor regulatory recalibration of blend-wall thresholds and carbon-accounting methodologies to anticipate powertrain allocation decisions across regional manufacturing networks.
Market Dynamics
The ethanol vehicle market is consolidating around flex-fuel powertrain engineering as regulatory mandates in Brazil and the United States harden blend-floor requirements and carbon-intensity benchmarks, forcing automakers to internalize fuel-system development rather than outsource to tiered suppliers.
Growth Catalysts
- Brazil's RenovaBio carbon targets:The ANP-enforced framework channels investment toward sugarcane ethanol supply chains, creating guaranteed offtake for flex-fuel vehicle production.
- Fleet electrification hedging:Commercial operators in São Paulo state are expanding flex-fuel procurement as a transitional compliance pathway while battery infrastructure remains uneven.
- Elastomer-sealed fuel systems:Advances in corrosion-resistant injector materials enable engine control modules to calibrate across variable alcohol concentrations without hardware swaps.
Market Restraints
- Sugarcane input volatility:Brazilian ethanol production concentrates in Center-South agricultural zones, exposing supply chains to climate-driven harvest fluctuations.
- Gasoline price arbitrage compression:When petroleum benchmarks drop below regional ethanol price floors, consumer fuel-switching economics deteriorate rapidly.
- US blend-wall constraints:The EPA's Renewable Fuel Standard volume obligations face infrastructure limits near E10 saturation in legacy vehicle fleets.
Strategic Opportunities
- Midwest US retail network expansion:E85 pump installations lag vehicle compatibility in Iowa and Nebraska, creating first-mover advantages for infrastructure investors.
- Second-generation cellulosic pathways:Agricultural residue feedstocks promise lower carbon intensity scores under ANP and EPA accounting methodologies.
- Engine downsizing convergence:Turbocharged direct-injection architectures paired with high-octane ethanol enable compression-ratio optimization without knock penalties.
Industry Challenges
- Fuel-system calibration talent scarcity:Engine control module programming for variable alcohol concentrations requires specialized combustion engineering expertise concentrated among Brazilian and US Midwest technical centers.
- Certification timeline compression:Dual-homologation requirements for gasoline and ethanol operating modes extend vehicle-type approval cycles in both EPA and ANP jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethanol Vehicle Market |
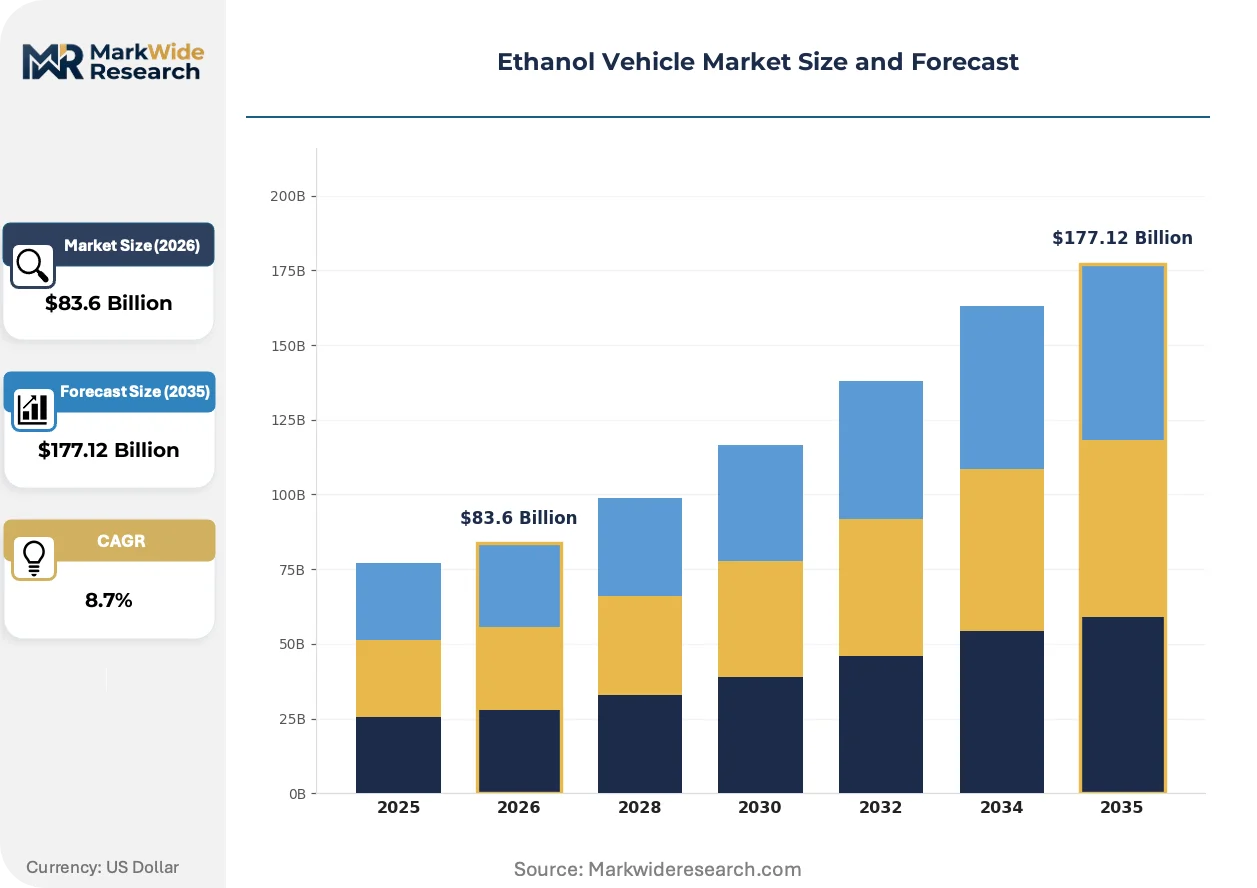
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $177.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: E85, E10, E15, E20 Vehicle Type: Passenger Cars, Trucks, Buses, Flex-Fuel Vehicles Engine Technology: Standard Engines, Modified Engines, Advanced Combustion, Hybrid Systems Market Channel: Direct Sales, Online Retail, Dealerships, Fleet Sales |
| Companies Covered | Ford Motor Company, General Motors Company, Toyota Motor Corporation, Volkswagen AG, Honda Motor Co Ltd, BMW AG, Daimler AG, Nissan Motor Co Ltd, AB Volvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethanol Vehicle Market Emerging Trajectories
Powertrain engineering is pivoting from single-fuel optimization toward adaptive combustion architectures. Three developments are compressing competitive timelines and reshaping how ethanol-compatible vehicles reach end-users.
Adaptive engine control software is fragmenting the traditional hardware-centric approach to flex-fuel compatibility. Tier-1 suppliers are deploying machine-learning-based calibration tools that adjust ignition timing and fuel injection in real-time based on ethanol concentration sensors. São Paulo-based engineering centers are adopting these platforms fastest, enabling automakers to reduce dedicated hardware variants while maintaining emissions compliance across Brazil's variable fuel blends.
The US EPA is recalibrating Renewable Fuel Standard volume obligations through nested compliance categories that reward cellulosic and advanced biofuel pathways over conventional corn ethanol. This regulatory restructuring redirects capital toward agricultural residue processing technologies and penalizes fuel marketers relying on grandfathered production assets. Midwest refiners are responding by retrofitting facilities for enzymatic hydrolysis capabilities to capture premium renewable identification numbers.
Fleet procurement contracts are unbundling fuel-supply agreements from vehicle acquisition decisions, forcing OEMs to demonstrate total-cost-of-ownership advantages independent of pump-price volatility. Large commercial operators in Brazil's agribusiness corridor are negotiating indexed fuel contracts directly with mill operators, bypassing traditional retail channels. This disintermediation concentrates purchasing power among São Paulo-state fleet managers and compresses margin capture for conventional dealership networks.
Ethanol Vehicle Market Segmentation
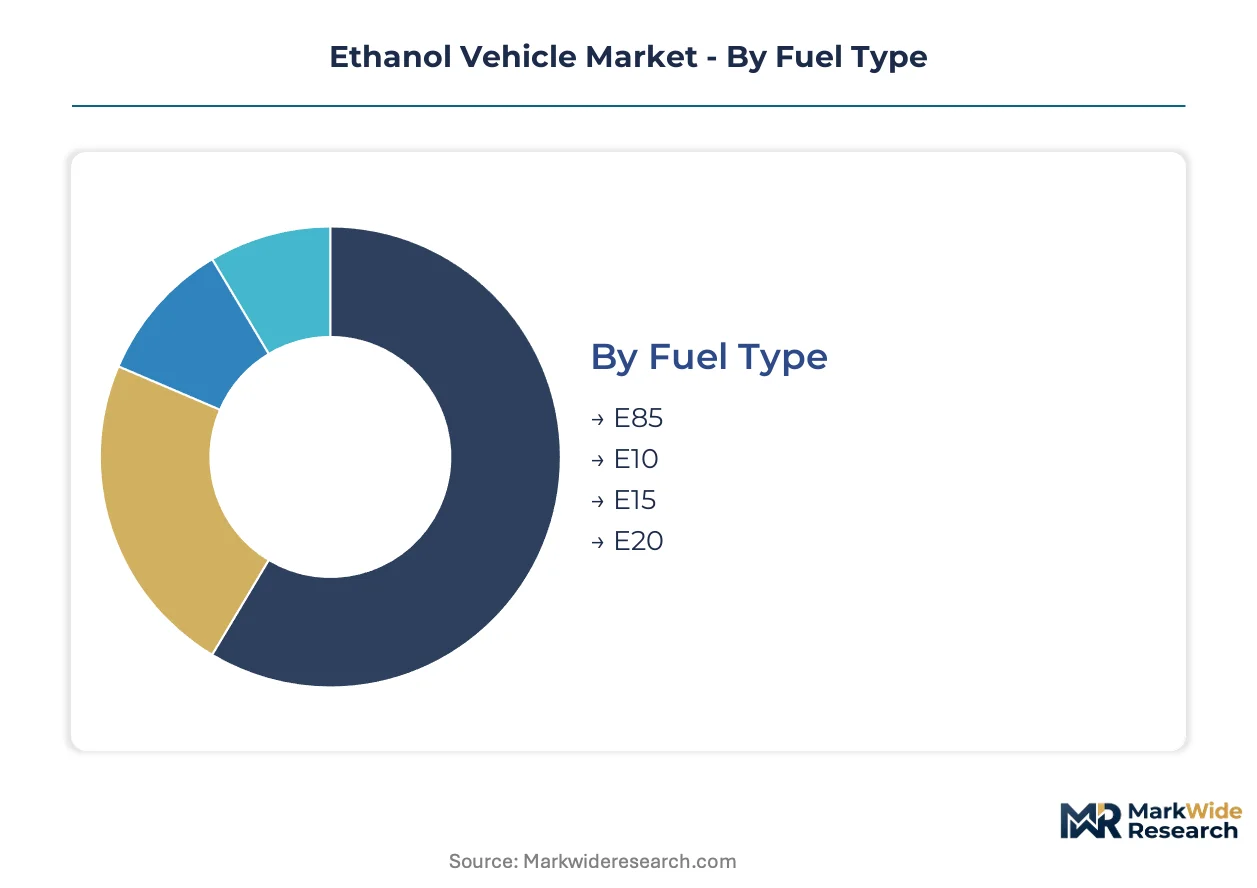
Ethanol vehicle segmentation reflects divergent regulatory pathways across Brazil and the United States, where blend-floor mandates and carbon-intensity frameworks reshape powertrain allocation decisions. Automakers calibrate product portfolios to match regional fuel-system requirements rather than pursuing uniform global architectures.
Fuel Type:
EPA Renewable Fuel Standard volume obligations and Brazil's ANP blend mandates create distinct demand profiles for each ethanol concentration tier.
- E85:High-concentration ethanol blends between 51% and 83% alcohol content require elastomer-sealed fuel systems and corrosion-resistant injectors calibrated for variable alcohol detection. São Paulo state fleet operators are expanding E85 procurement as RenovaBio carbon targets tighten, though gasoline price arbitrage compresses consumer economics during petroleum benchmark dips.
- E10:Regulatory blending floors in conventional gasoline markets sustain volume dominance through legacy vehicle compatibility without hardware modifications. Midwest US retail networks maintain E10 saturation near blend-wall constraints, limiting infrastructure expansion incentives for higher-concentration alternatives.
- E15:Intermediate blends face patchwork regulatory approval across US state jurisdictions, constraining geographic rollout despite EPA waivers for light-duty vehicles.
- E20:Brazilian ANP specifications for mid-range ethanol content support sugarcane ethanol supply chain optimization without full flex-fuel system costs.
Established volume favors E10; emerging adoption favors E85.
Vehicle Type:
Cost tier differentiation separates mass-market passenger applications from commercial fleet procurement patterns.
- Flex-Fuel Vehicles:Adaptive engine control modules with real-time alcohol concentration sensing enable seamless fuel switching between gasoline and ethanol blends. São Paulo-based manufacturing clusters achieve unmatched production density for these platforms, while US Midwest fleet operators deploy them as electrification hedges during battery infrastructure gaps.
- Passenger Cars:Light-duty platforms dominate installed base across ethanol-mandate jurisdictions through consumer familiarity and lower acquisition premiums. Brazilian OEMs leverage flex-fuel architectures developed for passenger segments to sustain cost leadership in E85-compatible powertrains.
- Trucks:Modified engine architectures in North American light-truck segments anchor ethanol strategies through towing-capacity retention and torque calibration for high-alcohol blends.
- Buses:Municipal transit procurement in Brazil's agribusiness corridor concentrates demand for dedicated ethanol powertrains with indexed fuel contracts bypassing retail channels.
Consumer familiarity stabilizes passenger car demand; commercial fleet hedging accelerates flex-fuel vehicle expansion.
Engine Technology:
Application-specific performance requirements dictate hardware investment levels across combustion architectures.
- Modified Engines:Hardware alterations including hardened valve seats, ethanol-compatible fuel pumps, and recalibrated engine control modules enable existing gasoline architectures to tolerate elevated alcohol concentrations. General Motors deploys these architectures across North American light-truck segments to dominate ethanol-compatible market share without clean-sheet redesign costs.
- Advanced Combustion:Turbocharged direct-injection systems paired with high-octane ethanol enable compression-ratio optimization and knock-free operation at elevated thermal efficiencies. Engine downsizing convergence around these architectures promises petroleum displacement without displacement penalties.
- Standard Engines:Unmodified gasoline powertrains operate exclusively on low-concentration ethanol blends through regulatory E10 compatibility mandates.
- Hybrid Systems:Dual-powertrain configurations combining ethanol combustion with electric assist remain nascent, constrained by control-system complexity and dual-homologation timelines.
Near-term deployment centers on modified engines; advanced combustion architectures claim the steepest expansion trajectory.
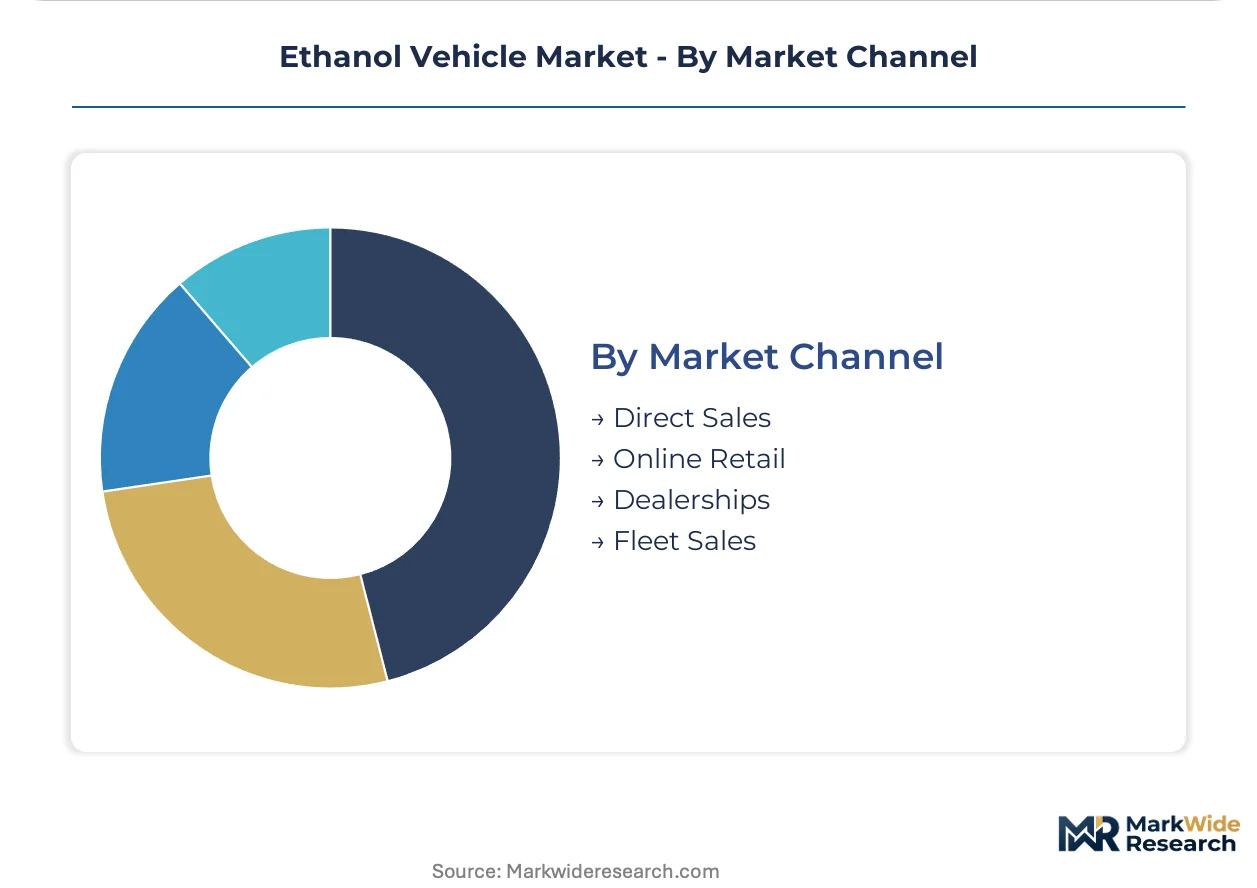
Market Channel:
Customer type concentration shapes margin capture and purchasing power distribution across distribution pathways.
- Fleet Sales:Large commercial operators negotiate unbundled fuel-supply agreements directly with mill operators, disintermediating traditional retail channels and compressing dealership margins. São Paulo-state agribusiness fleet managers concentrate purchasing power through indexed ethanol contracts tied to sugarcane harvest cycles.
- Dealerships:Franchise networks in Brazil's Center-South region maintain ethanol vehicle volume through flex-fuel model availability and consumer financing tied to fuel-price volatility hedges.
- Direct Sales:Commercial fleet procurement bypassing dealer networks accelerates in US Midwest states with E85 infrastructure gaps.
- Online Retail:Digital channels remain marginal for ethanol vehicle transactions due to fuel-system calibration requirements and regional homologation complexity.
Traditional dealership networks retain consumer segment control; fleet sales channels gain commercial procurement share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing leverage through sugarcane ethanol density, while the United States struggles with E85 infrastructure gaps that compress Midwest retail margins. This asymmetry shapes powertrain allocation decisions across both markets. Fleet operators in São Paulo state negotiate indexed fuel contracts that bypass volatile pump economics entirely.
Brazil
São Paulo state fleet operators dominate flex-fuel procurement as RenovaBio carbon targets tighten. ANP enforcement channels investment toward Center-South sugarcane supply chains. The São Paulo metropolitan manufacturing cluster achieves unmatched production density for elastomer-sealed fuel systems.
United States
Midwest corn ethanol refiners face EPA Renewable Fuel Standard volume obligations near E10 blend-wall constraints. Iowa and Nebraska retail networks lag E85 pump installations behind vehicle compatibility. Detroit-based engineering centers anchor modified engine architecture development for light-truck segments.
Canada
Prairie Provinces agricultural operators evaluate flex-fuel platforms as grain-handling fleet replacements. Health Canada and Environment Canada coordinate biofuel blending mandates with provincial clean fuel standards. The Saskatchewan- Manitoba corridor concentrates ethanol-compatible vehicle testing for cold-start calibration.
Germany
Bavarian automakers balance E10 regulatory floors against diesel transition pressures in passenger segments. KBA type-approval requirements extend dual-homologation timelines for ethanol-gasoline operating modes. Stuttgart engineering consultancies supply combustion calibration expertise to Brazilian OEM partnerships.
India
Maharashtra and Uttar Pradesh sugar cooperatives pilot E20 distribution through modified retail networks. BIS standards for ethanol-blended gasoline accelerate flex-fuel engine testing at Pune technical centers. The Delhi-NCR corridor faces particulate matter regulations that complicate high-alcohol blend combustion strategies.
Ethanol Vehicle Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the ethanol vehicle market. Integrated automakers with captive Brazilian manufacturing bases sustain cost advantages in flex-fuel platform production, while component-dependent rivals outsource fuel-system engineering to tiered suppliers. Three archetypes dominate: full-line OEMs with regional ethanol specialization, powertrain engineering houses with combustion calibration expertise, and flex-fuel component specialists. Competitive moves center on backward integration into fuel-system manufacturing and strategic partnerships with sugarcane ethanol mill operators for fleet contract security.
Within the full-line OEM tier, Ford Motor Company and General Motors Company exemplify divergent regional strategies. Ford leverages its São Paulo manufacturing base to anchor Latin American flex-fuel volume. General Motors occupies a position in North American light-truck ethanol compatibility through modified engine architectures. Toyota Motor Corporation represents the hybrid-architecture approach, balancing ethanol combustion with electric assist development. These three players illustrate how geographic manufacturing footprints and regulatory exposure shape competitive positioning without requiring uniform global ethanol strategies.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors Company |
| Toyota Motor Corporation |
| Volkswagen AG |
| Honda Motor Co Ltd |
| BMW AG |
| Daimler AG |
| Nissan Motor Co Ltd |
| AB Volvo |
| Others |
Supply Flow & Price Mechanics
Ninety-day fuel-system component lead times concentrate pricing power among São Paulo-based elastomer suppliers and Brazilian engine control module manufacturers, compressing margin capture for component-dependent rivals while rewarding integrated automakers with captive supply chains.
Pricing Analysis
The customization-premium spread between fleet-configured flex-fuel platforms and standard passenger variants widens as ethanol concentration calibration demands specialized engine control module programming. Contract-based long-term offtake dominates fleet procurement, with price differentiation resting on certification tier under EPA and ANP homologation standards and after-sales service bundling. Cost compression in mid-range passenger segments intensifies because gasoline-ethanol price arbitrage erodes consumer willingness to pay acquisition premiums. Fleet operators exhibit lowest price sensitivity due to indexed fuel contracts, while individual consumers in volatile pump-price markets show highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate elastomer-sealed fuel system production, though strategic stockpiling of sugarcane ethanol feedstock persists among São Paulo mill operators facing climate-driven harvest volatility. Supply concentrates in Brazil, the United States, and Germany, with raw material dependencies centering on sugarcane ethanol, corrosion-resistant injector alloys, and ethanol-compatible fuel pump polymers. Single-source vulnerability in Brazilian Center-South agricultural zones exposes downstream automakers to harvest fluctuation risk. Distribution runs through OEM captive manufacturing networks in São Paulo and Detroit engineering centers, with fleet sales channels bypassing traditional dealership intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RenovaBio carbon-intensity recalibration and EPA nested compliance categories for cellulosic pathways signal a regulatory inflection that rewards low-carbon ethanol production and adaptive powertrain engineering.
For Market Incumbents: Consolidate backward integration into fuel-system component manufacturing to defend against tiered supplier margin compression, while expanding São Paulo manufacturing density to capture RenovaBio-compliant fleet contracts. Certification investment in dual-homologation capabilities under ANP and EPA jurisdictions anchors competitive positioning against emerging powertrain engineering houses. For New Entrants and Emerging Players: Fleet fuel-supply agreement unbundling creates service-layer white space where incumbents under-serve, particularly in Midwest US E85 infrastructure gaps and Canadian Prairie Provinces grain-handling fleet replacements. Target direct procurement channels with mill-operator partnership models, leveraging indexed ethanol contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting infrastructure play because regulatory methodologies for low-carbon fuel pathways determine capital allocation toward cellulosic processing and adaptive combustion technologies. Acquisition candidates include flex-fuel component specialists with ANP-certified calibration capabilities and agricultural residue processing technology developers. Watch EPA volume obligation recalibration and ANP carbon-intensity threshold adjustments as primary inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuel-System Manufacturing | Captive production of elastomer-sealed components reduces tiered supplier dependency and compresses procurement costs for flex-fuel platforms. |
| Dual-Homologation Certification Investment | ANP and EPA concurrent approval accelerates vehicle-type release cycles across Brazil and US Midwest fleet markets. |
| Mill-Operator Fleet Partnership | Indexed ethanol contracts with São Paulo sugarcane producers bypass retail pump-price volatility for commercial operators. |
| Cellulosic Pathway Technology Licensing | Agricultural residue processing capabilities capture premium renewable identification numbers under EPA nested compliance categories. |
| Adaptive Engine Control Software Deployment | Machine-learning calibration platforms reduce hardware variant requirements while maintaining emissions compliance across variable fuel blends. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and ANP regulatory filings anchors the qualitative findings, combining primary interviews with flex-fuel powertrain directors, ethanol mill procurement managers, and fleet operations executives with secondary validation through EPA volume obligation reports, vehicle production databases, and sugarcane harvest statistics. Bottom-up segmentation triangulation across fuel type, vehicle class, and engine technology dimensions reconciles with top-down market sizing from regulatory mandate trajectories.
Sensitivity analysis across blend-wall threshold assumptions and carbon-intensity scoring methodologies shapes the analytical framework, with segmentation modeling covering fuel concentration tiers, vehicle architectures, combustion technologies, and regional production clusters throughout the forecast period. CAGRs derive from installed base evolution and replacement cycle analysis, incorporating fleet electrification hedging behavior and infrastructure deployment gaps as ethanol vehicle-specific forecast inputs.
Underlying assumptions cover regulatory mandate continuity and sugarcane ethanol supply stability, with deviation risk concentrated in petroleum benchmark volatility and cellulosic pathway commercialization timelines. Revision becomes warranted when EPA volume obligation recalibration or ANP carbon-accounting methodology changes cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market