
 Frameless Motor Market | 2026-2036
Frameless Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Frameless Motor Market Insights
A shortage of mechatronics engineers fluent in direct-drive torque design is unwinding the pace at which smaller OEMs can adopt frameless architectures. Kollmorgen Corporation leverages decades of servo motor integration to anchor North American supply relationships for surgical robot builders. Maxon sustains its reputation through extreme miniaturization expertise that dominates portable medical device applications. Moog Inc. competes on defense-aerospace qualification depth that few rivals can replicate.
A frameless motor is a direct-drive rotary or linear electromagnetic actuator supplied as rotor-stator subassemblies without integrated housings, bearings, or feedback devices, typically achieving torque densities above 5 Nm/kg through concentrated winding topologies and high-grade neodymium magnet arrays. These components embed directly into host machine structures to eliminate backlash, reduce part count, and raise system stiffness in precision positioning equipment. DC Brushless architectures occupy the dominant share of unit volume due to mature controller ecosystems and proven thermal performance in continuous-duty automation cells. Medical Devices applications are pulling fastest on specialized low-cogging variants for imaging gantries and surgical instruments where smooth motion at low speed is non-negotiable. Robotics demand concentrates margin pools in custom torque-density configurations that machine builders cannot source from standard catalog motors.
The EU Machinery Directive and CE marking requirements enforce functional safety validation for integrated motion systems, compelling frameless suppliers to pre-certify stator-rotor pairings with SIL-2 or SIL-3 compatibility documentation. FDA device regulations in the United States impose electromagnetic compatibility and biocompatibility constraints on motors destined for surgical and diagnostic platforms, lengthening qualification cycles but raising barriers against unqualified entrants. China's GB standards for industrial robot safety and MIIT directives on high-end manufacturing equipment localization are redirecting procurement toward domestic-qualified suppliers in advanced automation sectors. Stakeholders must monitor how regional certification divergence affects platform standardization strategies across multinational robot OEMs.
Market Dynamics
EU Machinery Directive safety mandates are forcing surgical robot OEMs to redesign motion architectures around pre-certified SIL-2 torque modules, compressing vendor qualification timelines and concentrating procurement among qualified suppliers.
Growth Catalysts
- CE marking pre-certification:EU Machinery Directive compliance requirements push frameless motor vendors to bundle SIL documentation with stator-rotor pairings, accelerating OEM time-to-market for collaborative robotics.
- Surgical robotics torque density:Medical device builders demand custom torque configurations exceeding 8 Nm/kg for compact instrument arms, pulling specialized winding topologies from qualified suppliers.
- Shenzhen-Suzhou precision corridor:China's advanced manufacturing localization policies under MIIT directives concentrate demand for domestic-qualified frameless motors in semiconductor and battery assembly automation.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing capacity clusters in China's Inner Mongolia region, exposing motor builders to export quota volatility and forced supply chain redundancy.
- FDA electromagnetic compatibility timelines:Surgical motor qualification cycles extend 18-24 months under 21 CFR Part 820 quality system regulations, freezing smaller vendors from medical revenue pools.
- Conventional geared servo substitution:Harmonic drive-actuated joint modules retain cost advantages below 50 Nm continuous torque, capping frameless penetration in price-sensitive cobot joints.
Strategic Opportunities
- India PLI scheme for industrial automation:Production-linked incentives for advanced manufacturing equipment create localized assembly opportunities for torque motor suppliers serving automotive and electronics sectors.
- Digital twin-embedded control convergence:Real-time thermal modeling fused with frameless motor windings enables predictive maintenance contracts in semiconductor wafer handling equipment.
- Modular stator kit distribution:Direct-to-machine-builder component sales through industrial automation distributors bypass traditional system integrator markups in European mid-market robotics.
Industry Challenges
- Mechatronics integration expertise gap:Direct-drive torque design fluency remains scarce among regional automation integrators, delaying smaller OEM adoption timelines and forcing vendor field engineering support.
- SIL-3 functional safety certification complexity:Surgical robot builders demand fault-tolerant motion documentation that exceeds standard industrial servo qualifications, requiring dedicated safety engineering headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frameless Motor Market |
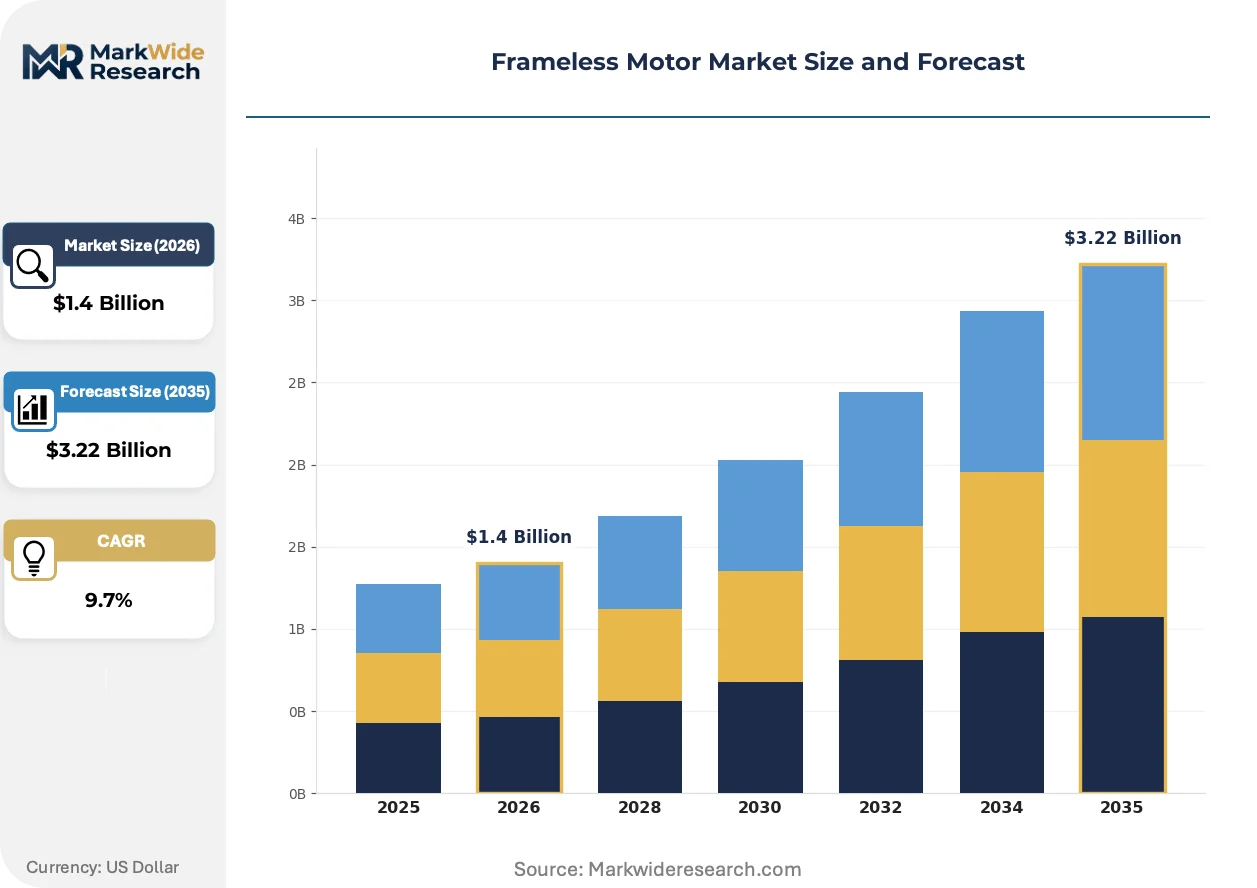
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Brushless, Stepper, AC Servo, Linear Motor Application: Robotics, Automation, Medical Devices, Consumer Electronics End User: Aerospace, Automotive OEMs, Manufacturing, Healthcare Technology: Electromechanical, Embedded Systems, Microprocessors, Digital Control |
| Companies Covered | Kollmorgen Corporation, Parker Hannifin Corporation, Nidec Corporation, Maxon, Moog Inc., Faulhaber, TQ-Group, Aerotech Inc., Allied Motion Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frameless Motor Market Trends and Innovations
Embedded thermal sensing and real-time impedance monitoring are dissolving the boundary between motor hardware and control firmware, enabling predictive maintenance architectures that redefine aftermarket value capture.
Concentrated fractional-slot winding topologies with segmented stator laminations are decomposing the traditional trade-off between torque ripple and copper fill factor. Medical imaging gantry builders at Siemens Healthineers and Canon Medical Systems have adopted these configurations for sub-arcminute positioning stability. The technology is compressing vendor R&D cycles toward application-specific electromagnetic designs rather than catalog motor selection.
EU AI Act risk classification rules for machinery safety systems are extending documentation burdens to motion subassemblies with embedded diagnostic algorithms. Frameless suppliers must now maintain algorithmic transparency logs for torque ripple compensation routines deployed in collaborative robot joints. German integrators KUKA and Franka Emika have responded by demanding pre-validated software bills of materials from motor vendors.
Machine builders are consolidating frameless motor procurement around qualified supplier lists that bundle electromagnetic design, thermal validation, and safety certification documentation. This behavior concentrates purchasing authority at original equipment manufacturers and marginalizes independent distributor channels in high-specification medical and aerospace segments. The shift is most visible in Swiss and German precision equipment manufacturing, where procurement teams now mandate single-source accountability for motion subsystem performance.
Frameless Motor Market Segmentation
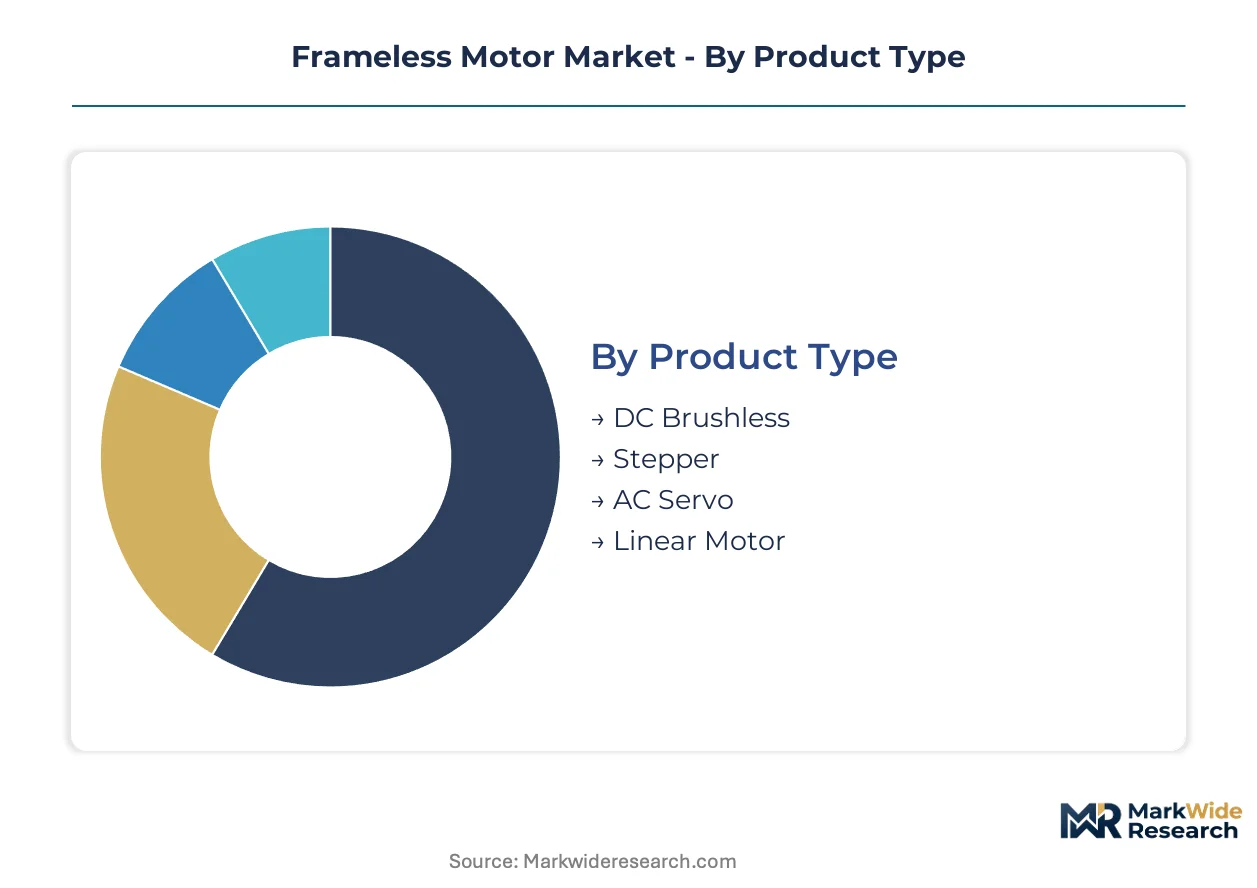
Frameless motor architectures vary dramatically in torque density, thermal management, and integration complexity. Procurement decisions pivot on whether the application demands continuous-duty servo precision or intermittent positioning accuracy.
Product Type:
Margin pools concentrate in configurations that eliminate gearbox maintenance and backlash in precision positioning equipment.
- DC Brushless:Concentrated winding topologies paired with high-grade neodymium magnet arrays achieve torque densities above 5 Nm/kg. Demand clusters in China's Shenzhen-Suzhou precision manufacturing corridor for semiconductor and battery assembly automation where continuous-duty thermal performance is mandatory.
- AC Servo:Field-oriented control architectures enable sub-arcminute positioning stability for medical imaging gantries. Siemens Healthineers and Canon Medical Systems have adopted these configurations for surgical instrument arms where smooth motion at low speed is non-negotiable.
- Stepper:Open-loop simplicity suits cost-sensitive positioning stages in light industrial automation.
- Linear Motor:Direct-drive elimination of rotary-to-linear conversion serves high-acceleration gantry systems in electronics assembly.
DC Brushless holds installed capacity. AC Servo is rotating up the share rankings.
Application:
Volume distribution tracks directly to machinery safety certification requirements and localization policy intensity.
- Robotics:Custom torque-density configurations exceeding 8 Nm/kg dominate collaborative arm designs. KUKA and Franka Emika in Germany demand pre-validated software bills of materials for torque ripple compensation routines under EU AI Act documentation burdens.
- Medical Devices:Low-cogging variants for imaging gantries and surgical instruments face FDA electromagnetic compatibility timelines extending 18-24 months under 21 CFR Part 820 quality system regulations.
- Automation:General-purpose frameless integration serves precision manufacturing cells across automotive and electronics sectors.
- Consumer Electronics:Miniaturized direct-drive actuators enable compact haptic feedback and camera stabilization systems.
Robotics commands current procurement volume. Medical Devices is climbing the fastest as surgical platform builders redesign motion architectures around pre-certified SIL-2 torque modules.
End User:
Customer concentration follows defense-aerospace qualification depth and automotive electrification investment cycles.
- Aerospace:Defense-aerospace qualification requirements for fault-tolerant motion documentation exceed standard industrial servo certifications, requiring dedicated safety engineering headcount that few suppliers can sustain.
- Healthcare:Surgical robot OEMs concentrate purchasing authority around qualified supplier lists that bundle electromagnetic design, thermal validation, and safety certification documentation.
- Automotive OEMs:Battery assembly automation and electric powertrain testing equipment pull frameless torque motors for precision positioning.
- Manufacturing:General industrial automation serves as the volume foundation for catalog motor variants.
Aerospace maintains the highest margin tier. Healthcare is gaining share fastest as procurement teams mandate single-source accountability for motion subsystem performance.
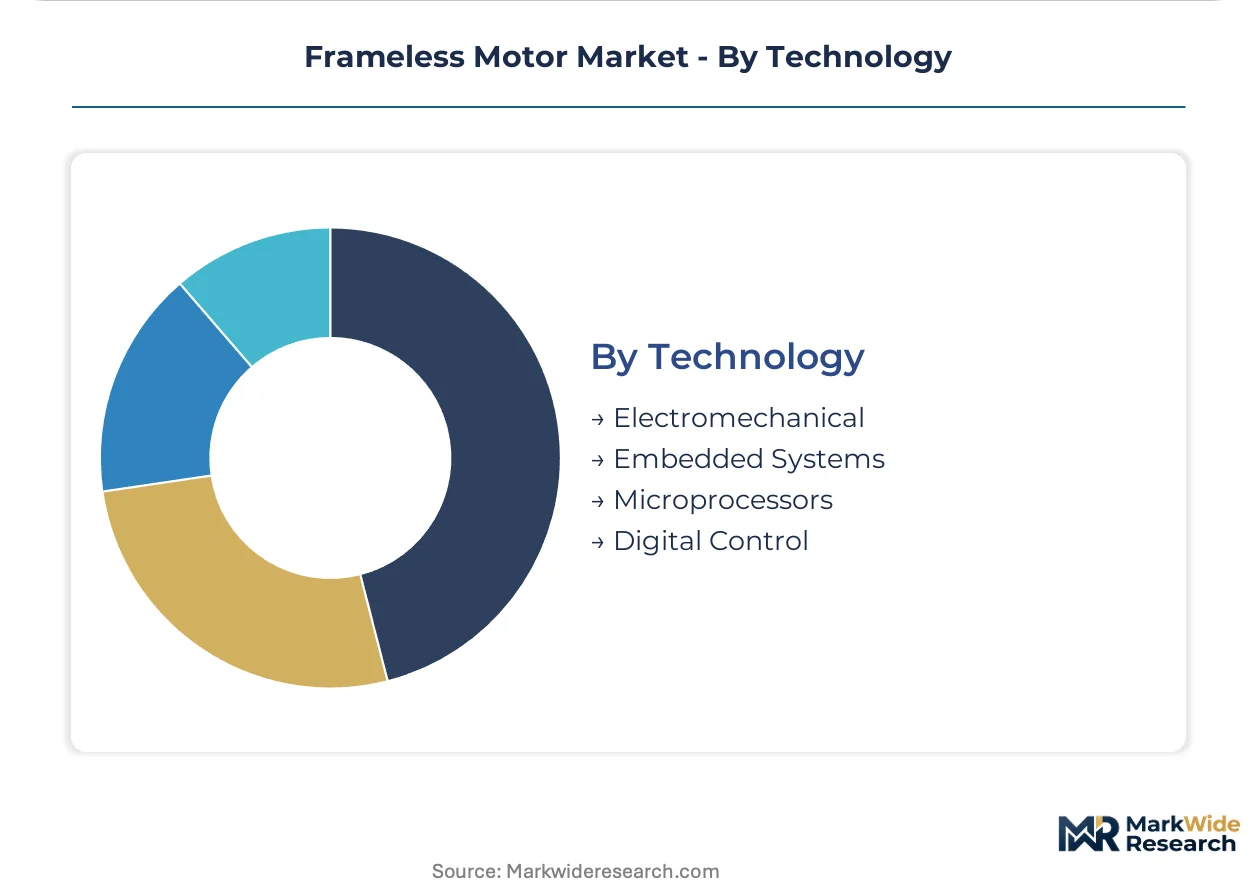
Technology:
Control architecture sophistication determines aftermarket value capture through predictive maintenance contracts.
- Embedded Systems:Real-time thermal modeling fused with frameless motor windings enables predictive maintenance architectures in semiconductor wafer handling equipment.
- Digital Control:Algorithmic transparency logs for torque ripple compensation routines are becoming mandatory under EU AI Act risk classification rules for machinery safety systems.
- Electromechanical:Traditional stator-rotor pairings without integrated sensing serve cost-sensitive applications.
- Microprocessors:Edge computing integration supports adaptive commutation and condition monitoring.
Embedded Systems anchors current platform designs. Digital Control is expanding most quickly as German integrators demand pre-certified SIL documentation bundled with stator-rotor pairings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT directives on high-end manufacturing equipment localization anchor procurement patterns in China's precision manufacturing corridor. Robotics integrators in Germany and Japan are expanding frameless torque motor procurement for collaborative arm designs. Tightening machinery safety standards under the EU Machinery Directive and rising embedded digital control architectures are redirecting vendor development priorities across multiple geographies.
China
Domestic-qualified suppliers capture procurement share under MIIT localization mandates for industrial robot safety and high-end manufacturing equipment. GB standards enforcement accelerates certification timelines for semiconductor and battery assembly automation vendors. The Shenzhen-Suzhou precision manufacturing corridor concentrates demand for frameless motors in electronics assembly and electric vehicle component production.
Germany
KUKA and Franka Emika demand pre-validated software bills of materials for torque ripple compensation routines under EU AI Act documentation requirements. CE marking and SIL-2 pre-certification compress OEM time-to-market for collaborative robotics platforms. Bavarian precision equipment manufacturers mandate single-source accountability for motion subsystem performance in surgical robot builds.
United States
FDA electromagnetic compatibility timelines extending 18-24 months under 21 CFR Part 820 quality system regulations filter smaller vendors from medical device revenue pools. Surgical robot OEMs redesign motion architectures around pre-certified SIL-2 torque modules. Greater Boston and Silicon Valley clusters anchor surgical robotics and semiconductor equipment demand respectively.
Japan
METI industrial automation policies and JIS standards alignment shape procurement for collaborative robot joint modules. Robotics integrators expand frameless torque motor adoption for compact arm designs requiring sub-arcminute positioning stability. The Nagoya-Tokyo manufacturing belt concentrates precision machinery builders integrating direct-drive architectures.
Switzerland
Swissmedic medical device regulations intersect with EU Machinery Directive safety mandates for surgical platform motion systems. Procurement teams in precision equipment manufacturing mandate bundled electromagnetic design, thermal validation, and safety certification documentation. The Swiss-German border region clusters medical imaging gantry builders adopting low-cogging frameless variants.
Frameless Motor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the frameless motor supplier base. The market structure tiers around defense-aerospace qualification depth, extreme miniaturization expertise, and servo motor integration heritage. Three strategic archetypes dominate: qualified medical-aerospace specialists, precision miniaturization masters, and broad industrial automation integrators. Competitive moves concentrate on pre-certification bundling for safety-critical applications and predictive maintenance service contracts enabled by embedded thermal sensing.
Within the qualified medical-aerospace tier, Kollmorgen Corporation, Moog Inc., and Maxon occupy positions defined by certification depth and application-specific torque density capabilities. Kollmorgen anchors North American supply relationships through servo integration heritage. Moog exemplifies defense-aerospace qualification depth that few rivals replicate. Maxon represents extreme miniaturization expertise dominating portable medical device applications. These three entities illustrate how vendor selection in surgical robotics and imaging equipment concentrates around documented safety engineering capabilities rather than catalog motor specifications.
| Leading Market Players |
|---|
| Kollmorgen Corporation |
| Parker Hannifin Corporation |
| Nidec Corporation |
| Maxon |
| Moog Inc. |
| Faulhaber |
| TQ-Group |
| Aerotech Inc. |
| Allied Motion Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
CE marking and SIL-2 pre-certification under the EU Machinery Directive simultaneously gate supplier qualification and stratify price tiers, forcing OEMs to pay premiums for bundled safety documentation while excluding uncertified vendors from surgical robotics procurement pools.
Pricing Analysis
Price spreads between German and Chinese suppliers exceed 40% for equivalent torque-density configurations, reflecting certification-grade differentiation. Three-tier pricing structure across medical-aerospace certified, industrial-automation standard, and economy catalog tiers dominates, with FDA electromagnetic compatibility timelines extending qualification costs that compress margins for smaller builders. Pricing pressure stems from neodymium magnet cost volatility and harmonic drive substitution in cobot joints below 50 Nm. Automotive battery assembly OEMs exhibit highest price sensitivity; surgical robot builders prioritize single-source accountability over unit cost.
Supply Chain Analysis
China and Japan anchor rare earth magnet processing and precision lamination stamping respectively, with Germany specializing in safety-certified stator-rotor integration. Neodymium magnet arrays, segmented silicon steel laminations, and high-temperature winding insulation constitute critical input dependencies. Single-source vulnerability concentrates in Inner Mongolia rare earth processing capacity exposed to export quota volatility. Distribution runs through qualified supplier lists that bundle electromagnetic design, thermal validation, and safety certification documentation, marginalizing independent distributor channels in medical and aerospace segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts enabled by embedded thermal sensing are expanding faster than hardware unit sales, converting frameless motor procurement from capital expenditure to service-attach relationships with recurring revenue streams.
For Market Incumbents: Shield medical-aerospace margin tiers by deepening SIL-3 functional safety engineering headcount against emerging modular stator kit distributors. Backward integration into rare earth magnet sourcing mitigates Inner Mongolia quota volatility, while captive thermal modeling software development locks in semiconductor wafer handling aftermarket contracts.
For New Entrants and Emerging Players: Predictive maintenance service gaps in India's PLI-supported automotive automation corridor offer white-space entry where incumbents under-serve with hardware-only catalogs. Target domestic-qualified positioning in Shenzhen-Suzhou battery assembly automation through MIIT-aligned certification investment, leveraging direct-to-machine-builder component sales to bypass European system integrator markups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision miniaturization specialists holding FDA electromagnetic compatibility dossiers but lacking predictive maintenance software capabilities. Five-to-ten year viability hinges on converting hardware margins to service-attach revenue; monitor embedded control architecture patent filings as inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-certified SIL-2 Module Bundling | Compresses OEM time-to-market for KUKA and Franka Emika collaborative robotics platforms. |
| Predictive Maintenance Platform Launch | Enables recurring revenue capture in Applied Materials and Lam Research wafer handling equipment. |
| Rare Earth Magnet Backward Integration | Reduces exposure to China's Inner Mongolia export quota volatility for torque motor builders. |
| India PLI Localization Investment | Captures production-linked incentive flows in automotive and electronics automation sectors. |
| Digital Twin Control Convergence | Fuses real-time thermal modeling with Siemens Healthineers imaging gantry architectures. |
Research Methodology
A standing panel of surgical robotics procurement directors, semiconductor equipment maintenance heads, and automotive automation plant engineers provided ongoing calibration across the study period. Primary fieldwork with frameless motor application engineers and GPO contracts managers at Swiss and German precision equipment manufacturers combined with secondary validation from FDA 510(k) filings, MIIT high-end manufacturing equipment directives, EU Machinery Directive guidance documents, and SEC 10-K supply chain disclosures. Bottom-up torque density and thermal performance specifications triangulated against top-down regional procurement pattern analysis.
Consistency checks validated volume and value outputs against customs trade data for neodymium magnet imports and semiconductor equipment capital expenditure disclosures. The analytical framework modeled product type, application, end user, and technology dimensions across the projection horizon, with CAGRs derived from segment-level adoption curve analysis and qualification timeline compression factors. Industry-specific inputs included SIL certification penetration rates and embedded control architecture deployment in collaborative robotics joints.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820 quality system regulations and EU Machinery Directive safety mandates; material policy shifts would require re-modeling. Neodymium supply disruption, surgical robotics platform consolidation, and AI Act algorithmic transparency enforcement constitute primary revision triggers. Recalibration cycles align with material shifts in rare earth export policy and embedded thermal sensing patent grant velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Motor Gear Unit Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Traction Motors Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Automotive Torque Actuator Motor Market