
 UAE Electric Motor Market | 2026-2036
UAE Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Electric Motor Market Intelligence
Asset-light leasing models for high-efficiency motor fleets is rewriting competitive entry barriers for mid-sized industrial contractors. Siemens AG leverages its regional service network to sustain long-term maintenance contracts across Emirates steel plants. ABB Ltd anchors its position through permanent magnet motor technology leadership in oil and gas applications. CG Power and Industrial Solutions competes on cost-optimized asynchronous motor variants for construction sector buyers.
An electric motor converts electrical energy into mechanical rotation through electromagnetic induction between stator windings and a rotor assembly, with rated power outputs spanning fractional horsepower to multi-megawatt industrial units, and serves as the prime mover for pumps, compressors, conveyors, and automated machinery. AC Motors dominate installed base volumes across UAE petrochemical and desalination facilities due to grid compatibility and mature servicing infrastructure. Brushless technology variants capture expanding share in robotics and precision HVAC applications where reduced maintenance intervals justify premium positioning.
ESMA mandates IE3 minimum efficiency classes for motors above specified power thresholds, while Dubai Municipality enforces green building codes that specify premium motor efficiency in commercial HVAC Systems installations. The UAE's net-zero pathway pressures end users to retire legacy brushed motor inventories ahead of regulatory phase-outs. Stakeholders must weigh retrofit timing against evolving efficiency tier requirements and localized service capabilities.
Market Dynamics
ESMA's tightening IE3 efficiency mandates are forcing systematic motor fleet turnover across UAE industrial zones, compressing replacement cycles and rewiring supplier-buyer contracting structures.
Growth Catalysts
- Industrial automation:Manufacturing facilities across Dubai's industrial corridor deploy servo-controlled motor systems to upgrade legacy production lines. Demand concentrates in precision assembly and material handling operations.
- ESMA efficiency regulations:Mandatory IE3 minimums for motors above specified power ratings eliminate lower-tier imports. Compliance deadlines accelerate capital deployment timelines.
- Desalination capacity expansion:Abu Dhabi's utility operators specify premium-efficiency motors for reverse osmosis plants. Saltwater corrosion resistance drives material specification upgrades.
Market Restraints
- Copper price volatility:Stator winding material costs swing with London Metal Exchange pricing. Motor manufacturers absorb margin compression or pass through via indexed contracts.
- European component concentration:High-grade magnetic steel and insulated winding wire originate from specialized German and Austrian mills. Supply disruption risk elevates safety stock requirements.
- Legacy motor interoperability:Existing VFD installations limit retrofit options to dimensionally compatible frame sizes. Technical lock-in extends replacement timelines.
Strategic Opportunities
- Ras Al Khaimah manufacturing zone:Greenfield industrial parks attract food processing and ceramics producers with subsidized utility infrastructure. First-motor-supplier positioning yields long-term maintenance lock-in.
- Permanent magnet integration:Neodymium-iron-boron rotor assemblies converge with advanced thermal management for oil and gas compressor duty. Premium positioning justifies 40% efficiency gains over induction alternatives.
- Dubai Municipality green building codes:Commercial HVAC specifications mandate IE4-equivalent motor performance for new construction permits. Regulatory tailwind accelerates premium product penetration.
Industry Challenges
- Field service technician scarcity:VFD commissioning and predictive maintenance diagnostics require specialized training. Local technical institutes lag industrial demand curves.
- IE4 certification timelines:ESMA testing protocols for ultra-premium efficiency classes extend product launch schedules by 8-14 months. Compliance documentation burdens smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Electric Motor Market |
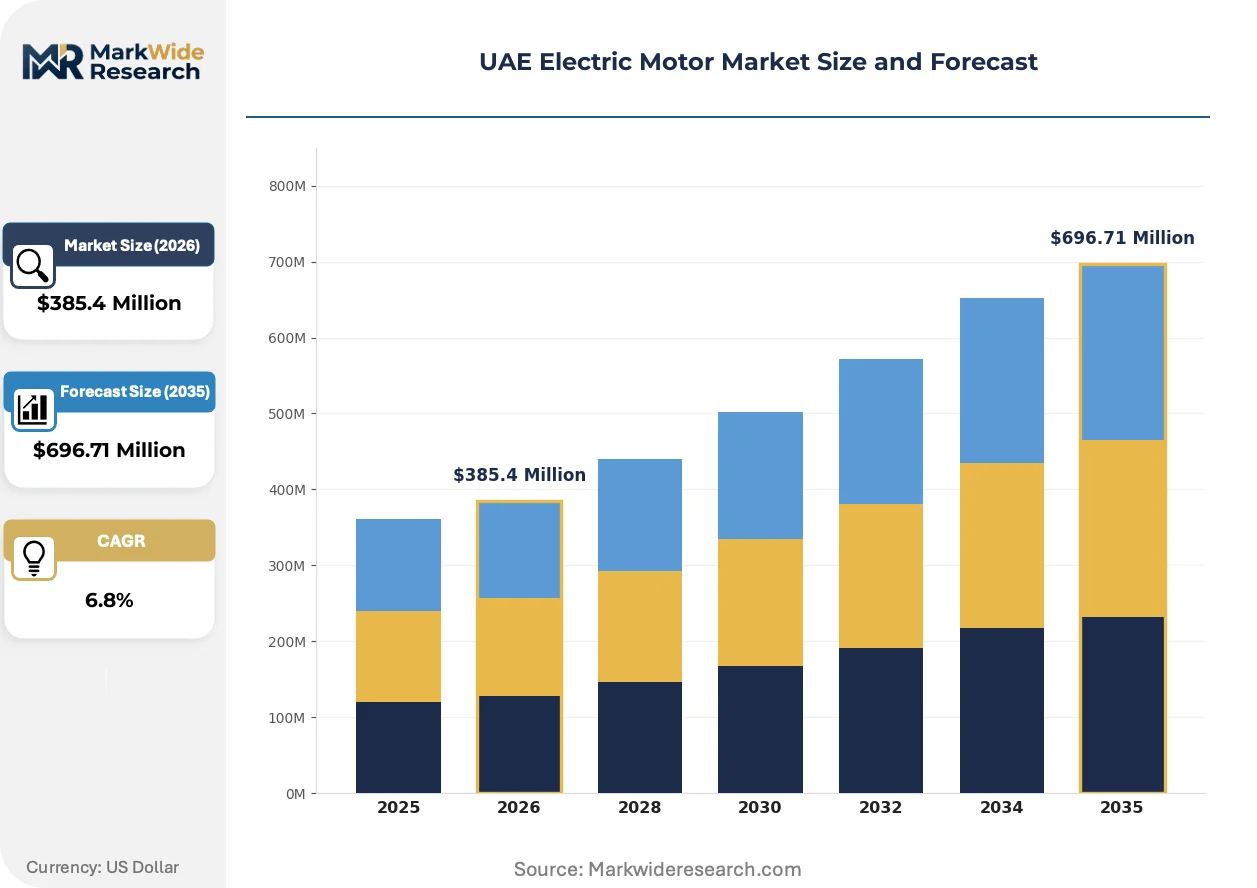
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors End User: Automotive OEMs, Construction, Manufacturing, Textiles Technology: Brushless, Brushed, Synchronous, Asynchronous Application: HVAC Systems, Robotics, Transportation, Industrial Automation |
| Companies Covered | WEG Industries, CG Power and Industrial Solutions, ABB Ltd, General Electric, Bharat Heavy Electricals Limited, Siemens AG, Regal Rexnord Corporation, Tesla Inc., Nidec Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Electric Motor Market Strategic Shifts & Innovations
Permanent magnet synchronous motor technology is collapsing the efficiency-performance tradeoff that historically constrained oil and gas applications, while regulatory tier compression and procurement model fragmentation simultaneously reshape competitive access.
Switched reluctance motor architectures eliminate rotor conductors entirely, replacing copper windings with laminated steel salient poles. Offshore platform operators in Abu Dhabi adopt these systems for pump and compressor duties where explosive atmosphere certification limits conventional motor options. The technology is collapsing maintenance intervals and spare parts inventory requirements across remote installations.
ESMA's phased IE3-to-IE4 efficiency trajectory tightens allowable losses in 0.75-375 kW motor classes annually through 2030. Manufacturers redesign stator slot geometries and magnetic steel grades to meet tightening watt-loss thresholds. Oil and gas end-users in Ruwais and Jebel Ali face accelerated depreciation of IE2 inventories ahead of 2027 import restrictions.
Asset-light leasing structures displace capital purchase for high-efficiency motor fleets among mid-sized contractors. Dubai-based equipment lessors bundle installation, monitoring, and predictive maintenance into per-operating-hour contracts. Construction sector buyers in Sharjah and Ajman shift balance sheet treatment while transferring obsolescence risk to lessors.
UAE Electric Motor Market Segmentation
Motor fleet lifecycle economics diverge sharply across segment boundaries in the UAE market. After-sales service intensity shapes supplier profitability and customer switching costs more than initial equipment margins.
Product Type:
Service contract attach rates and spare parts velocity vary dramatically by motor architecture, rewiring competitive economics across the supplier base.
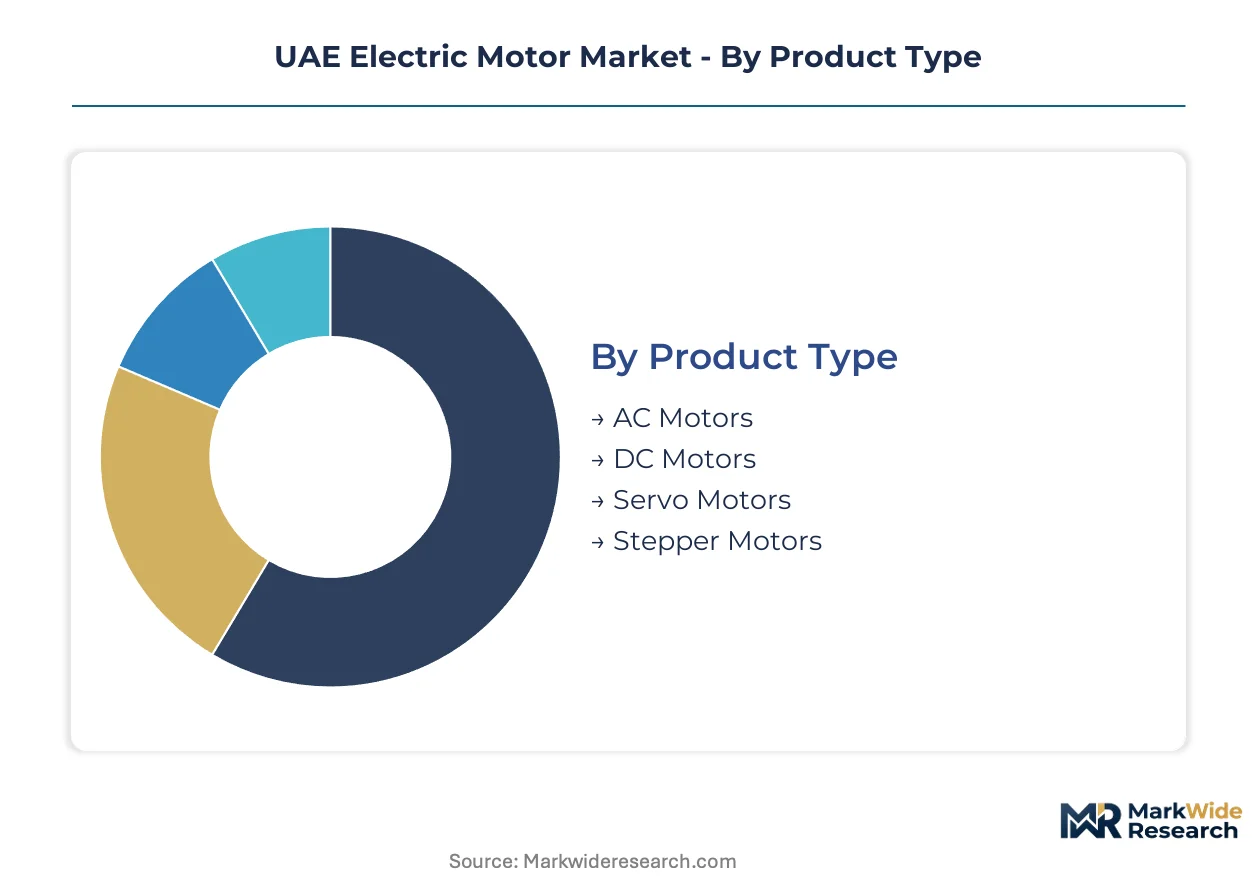
- AC Motors:Three-phase induction designs with squirrel-cage or wound rotors dominate installed base volumes across UAE petrochemical corridors. Dubai's desalination plants and Abu Dhabi's Ruwais industrial zone specify these units for pump and compressor duties where grid synchronization and mature technician training reduce commissioning risk.
- DC Motors:Brushed and brushless variants with wound-field or permanent magnet excitation retain niche positions in crane hoists and rolling mill drives. Sharjah's metal fabrication clusters and Ajman's port logistics facilities specify DC systems for high-torque low-speed applications where precise speed control outweighs maintenance burden.
- Servo Motors:Closed-loop position control systems with encoder feedback enable precision motion in robotics and CNC machining centers.
- Stepper Motors:Open-loop incremental positioning drives suit lower-cost automation in packaging and material handling equipment.
By volume, AC Motors leads. By growth pace, Servo Motors is ahead.
End User:
Capital deployment cycles and specification authority concentration create distinct selling motions across buyer categories.
- Automotive OEMs:Tier-1 suppliers in Dubai's Jebel Ali automotive zone specify high-precision servo and brushless DC systems for welding robots and paint shop conveyors. Production line uptime requirements drive premium motor selections with predictive maintenance integration.
- Construction:Mid-sized contractors in Sharjah and Ras Al Khaimah favor cost-optimized asynchronous motors for concrete batching and material handling. Equipment leasing penetration is highest here, shifting procurement toward operating-expense treatment.
- Manufacturing:Food processing and ceramics producers in greenfield Ras Al Khaimah zones specify IE3-compliant motors with corrosion-resistant enclosures.
- Textiles:Spinning and weaving operations in Dubai Industrial City deploy variable-speed drives with specialized torque characteristics.
Manufacturing commands the largest equipment spend. Automotive OEMs show the steepest specification upgrade trajectory.
Technology:
Rotor construction and commutation method determine efficiency ceiling, maintenance interval, and regulatory compliance pathway.
- Brushless:Electronic commutation eliminates mechanical wear components, extending service intervals in HVAC and precision motion applications. Dubai Municipality green building codes accelerate penetration in commercial chiller specifications.
- Brushed:Mechanical commutation with carbon brush contact faces accelerated phase-out under ESMA efficiency mandates. Legacy inventories in small industrial facilities face compressed replacement timelines.
- Synchronous:Rotor locks to stator field frequency, enabling precise speed holding for compressor and generator duties. Permanent magnet variants capture share in oil and gas applications.
- Asynchronous:Slip between rotor and field enables inherent torque cushioning for pump and fan loads. Induction designs retain cost advantage in volume-sensitive construction procurement.
Synchronous technology gains specification share fastest. Asynchronous designs retain volume dominance through installed base inertia.
Application:
Operating environment severity and duty cycle predictability segment motor performance requirements and supplier selection criteria.
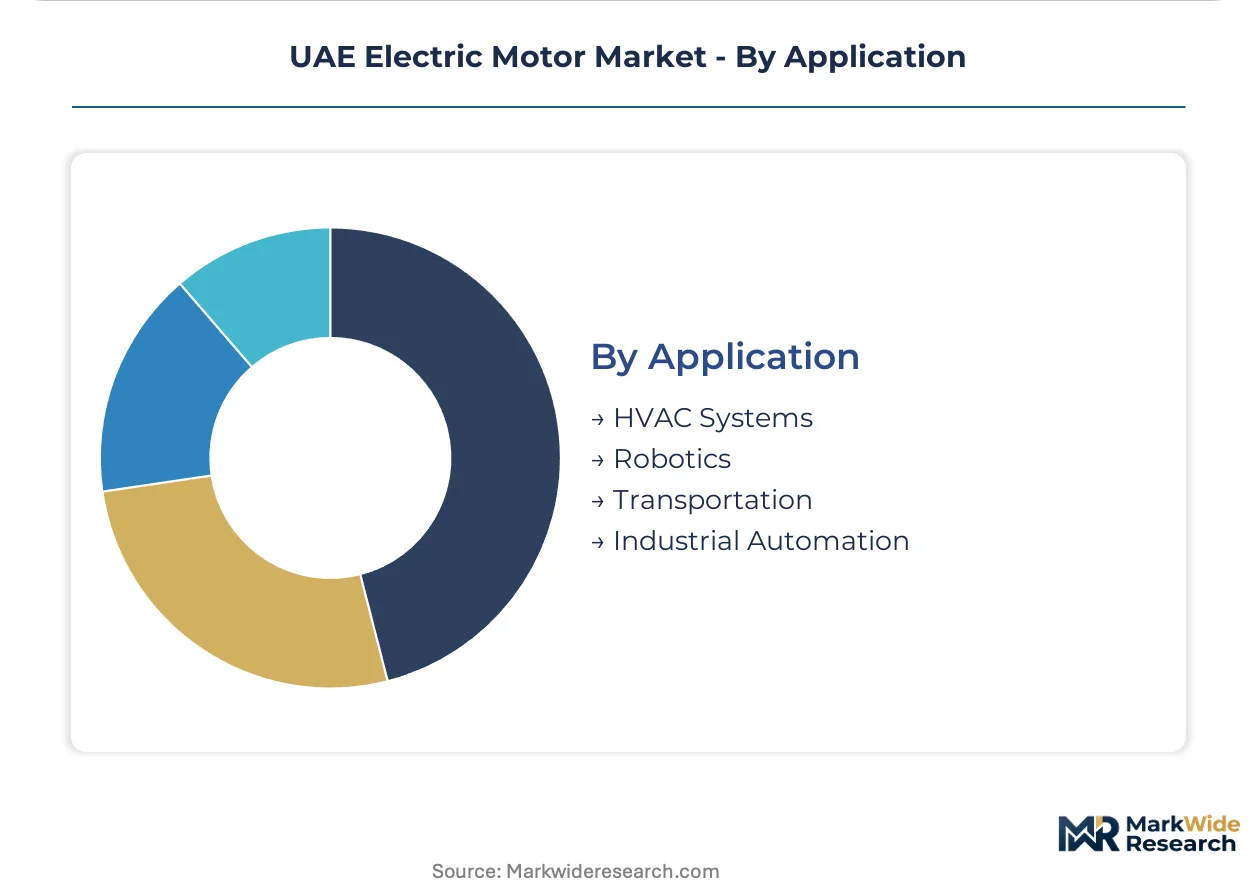
- HVAC Systems:Centrifugal chiller and air handling unit motors face Dubai Municipality IE4-equivalent mandates for new construction permits. Thermal management and acoustic performance specifications tighten alongside efficiency requirements.
- Robotics:Six-axis industrial arms and collaborative systems in Dubai's automated assembly plants demand compact servo motors with absolute encoders. Repeatability specifications below 0.01 millimeter justify premium positioning.
- Transportation:Metro traction motors and airport baggage handling systems prioritize reliability-centered maintenance protocols.
- Industrial Automation:Conveyor networks and packaging lines across Emirates manufacturing zones balance throughput demands with energy recovery capabilities.
HVAC Systems represents the largest addressable equipment base. Robotics exhibits the most rapid technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
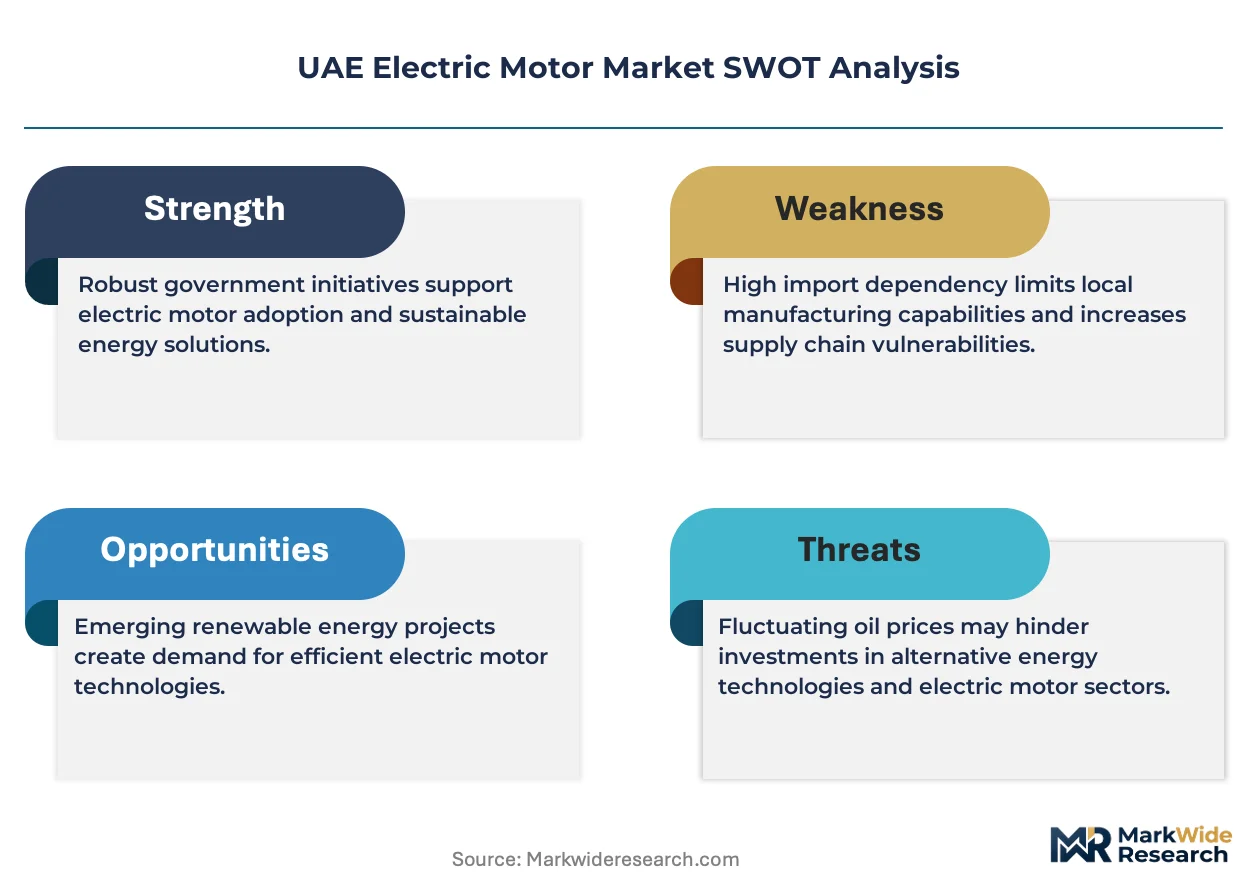
UAE's electric motor import dependency runs deep, with European and East Asian manufacturers supplying high-efficiency units while domestic assembly operations concentrate on lower-kilowage segments for construction and HVAC applications.
Dubai
Jebel Ali industrial corridor drives servo motor demand for automotive welding robots and automated paint lines. Dubai Municipality enforces IE4-equivalent green building codes for commercial HVAC permits. Al Quoz manufacturing zone hosts precision machining centers specifying absolute encoder feedback systems.
Abu Dhabi
Ruwais petrochemical complex and Taweelah desalination facilities specify premium-efficiency motors for continuous pump and compressor duty. ESMA mandates IE3 minimums for motors above 0.75 kW ratings. Khalifa Industrial Zone attracts greenfield ceramics and food processing plants with subsidized utility infrastructure.
Sharjah
Hamriyah Free Zone metal fabrication clusters retain DC motor specifications for crane hoists and rolling mill drives. The emirate's port logistics facilities prioritize high-torque low-speed systems. Mid-sized construction contractors favor cost-optimized asynchronous motors for concrete batching equipment.
Ras Al Khaimah
Saqr Port industrial zone expansion targets food processing and ceramics producers with captive power infrastructure. Asset-light motor leasing penetration runs highest here among mid-sized contractors. Greenfield facilities specify IE3-compliant corrosion-resistant enclosures for humid coastal conditions.
Northern Emirates
Ajman and Fujairah manufacturing zones concentrate on packaging and material handling automation with stepper motor systems. Lower land costs attract price-sensitive buyers from construction and light manufacturing segments. Equipment lessors bundle predictive maintenance into per-operating-hour contracts across these emirates.
UAE Electric Motor Market Key Industry Players
On the supply side, the industry is tiered between premium-efficiency technology leaders and cost-optimized volume suppliers serving distinct buyer segments. European and Japanese manufacturers anchor the high-efficiency tier with permanent magnet and synchronous technologies. Indian and Brazilian fabricators compete on asynchronous motor variants for price-sensitive construction procurement. Dominant competitive moves include long-term maintenance contract bundling and asset-light leasing model deployment.
Within the premium technology tier, Siemens AG and ABB Ltd exemplify efficiency-focused positioning through regional service network depth and permanent magnet motor leadership respectively. CG Power and Industrial Solutions occupies the cost-optimized asynchronous segment for construction sector buyers. These three anchors illustrate how supplier archetypes map to divergent buyer procurement logics across Emirates industrial zones.
| Leading Market Players |
|---|
| WEG Industries |
| CG Power and Industrial Solutions |
| ABB Ltd |
| General Electric |
| Bharat Heavy Electricals Limited |
| Siemens AG |
| Regal Rexnord Corporation |
| Tesla Inc. |
| Nidec Corporation |
| Others |
Cost & Logistics Intelligence
Jebel Ali Port freight corridors carry laminated electrical steel and neodymium magnet assemblies from East Asian foundries, with landed cost dynamics concentrating supply power among three European and Japanese manufacturers while fragmenting price-setting authority across Dubai-based distributors and Abu Dhabi utility procurement desks.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by IE3 versus IE4 certification grades and bundled predictive maintenance contracts. Pricing pressure stems from copper and magnetic steel commodity volatility transmitted through indexed supply agreements. Construction sector contractors in Sharjah and Ras Al Khaimah exhibit highest price sensitivity, while Ruwais petrochemical operators prioritize efficiency performance over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates at ABB's Czech and Finnish facilities alongside Siemens' German and Austrian motor assembly plants, with Nidec's Japanese and Chinese foundries supplying permanent magnet rotor assemblies. Raw material dependencies center on Chinese rare earth processing for neodymium-iron-boron magnets, German cold-rolled grain-oriented steel for stator laminations, and Chilean copper cathodes for winding conductors. Single-source vulnerability in rare earth magnet supply elevates safety stock requirements across Emirates distributor networks. Distribution runs through authorized service partners holding ESMA certification credentials and localized spare parts inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE electric motor demand sits in early-cycle expansion as ESMA efficiency mandates force systematic fleet turnover ahead of 2027 import restrictions, compressing replacement timelines and opening procurement windows for premium technology suppliers.
For Market Incumbents: Insulate service contract attach rates by embedding predictive maintenance diagnostics into permanent magnet motor installations before IE4 certification deadlines eliminate asynchronous alternatives. Deepen backward integration into localized rewind and repair capabilities to capture aftermarket revenue streams threatened by asset-light leasing models from Dubai-based equipment lessors. For New Entrants and Emerging Players: Establish a beachhead in Ras Al Khaimah greenfield manufacturing zones where subsidized utility infrastructure attracts food processing and ceramics producers with uncommitted motor supplier relationships. Target construction sector contractors in Ajman and Fujairah through per-operating-hour leasing partnerships that transfer obsolescence risk and bypass capital purchase approval cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from European industrial conglomerates divesting non-core motor divisions amid energy transition restructuring, particularly asynchronous motor operations serving declining brushed motor segments. Monitor ESMA testing protocol acceleration as inflection signal—compressed IE4 certification timelines favor acquirers with existing compliance documentation over development-stage entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Technology Licensing | Neodymium-iron-boron rotor designs unlock 40% efficiency gains over induction alternatives in Ruwais compressor duty. |
| ESMA Certification Fast-Track Investment | Pre-positioned IE4 testing documentation captures replacement demand ahead of 2027 regulatory phase-outs. |
| Asset-Light Leasing Platform Launch | Per-operating-hour contracts transfer obsolescence risk from Sharjah construction contractors to equipment lessors. |
| Localized Rewind Facility Acquisition | Captive aftermarket service capacity locks in maintenance revenue from Dubai desalination plant operators. |
| Ras Al Khaimah Distribution Partnership | First-motor-supplier positioning in Saqr Port industrial zone yields long-term greenfield facility maintenance contracts. |
Research Approach
The analysis maps AC induction, permanent magnet synchronous, servo, and switched reluctance motor sub-sectors, each validated through plant engineers at Ruwais petrochemical facilities, procurement directors at Dubai automotive Tier-1 suppliers, maintenance heads at Taweelah desalination plants, and service managers at Emirates-based motor distributors. Primary fieldwork combined with secondary validation against ESMA efficiency regulation filings, Dubai Municipality green building code amendments, customs import data for motor classifications, and SEC disclosures from listed motor manufacturers. Bottom-up unit demand estimates triangulated against top-down industrial energy consumption projections.
Forecast assumptions held ESMA regulatory phase-out schedules and Dubai Municipality HVAC efficiency mandates fixed while varying copper price trajectories and permanent magnet supply scenarios across the projection horizon. Segmentation dimensions modeled include motor architecture, efficiency certification tier, end-use industry, and emirate-level industrial zone concentration. CAGRs derived from replacement cycle compression analysis and greenfield capacity addition pipelines. Industry-specific inputs incorporated desalination capacity expansion timelines and Ras Al Khaimah industrial park occupancy rates.
Sensitivities concentrate around rare earth export restriction scenarios and accelerated IE4 mandate adoption. Forecasts reflect documented assumptions on regulatory compliance timelines and commodity price pass-through mechanisms. Quarterly review of ESMA certification queue lengths and Jebel Ali Port steel coil import volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
APAC Electric Drives Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Electric Traction Motor Market
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
Smart E-Drive Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Global EV Motor Controller Market