
 Stolen Vehicle Tracking System Market | 2026-2036
Stolen Vehicle Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
Stolen Vehicle Tracking System Market Analytics
Premium-grade telematics integration is bifurcating the competitive landscape as OEMs and aftermarket suppliers race to embed stolen vehicle recovery into connected-car architectures. Continental AG leverages its sensor-to-cloud vertical to sustain dominance in integrated OEM solutions. Robert Bosch GmbH anchors its position through deep R&D intensity in GNSS fusion algorithms. LoJack Corporation differentiates via specialized channel control across North American law enforcement partnerships.
A stolen vehicle tracking system comprises electronic hardware and software platforms that transmit geolocation and status data to centralized monitoring centers, typically operating through GPS, cellular, or satellite communication protocols with refresh rates under 60 seconds for real-time recovery coordination. The primary commercial purpose centers on asset recovery, insurance loss reduction, and fleet security management. GPS trackers lead installed base volume due to mature semiconductor supply chains and carrier network density, while satellite trackers represent the fastest-expanding margin pool as they penetrate remote-area commercial fleets beyond cellular coverage. Real-time monitoring technology occupies the largest revenue share among technology segments, though geofencing applications are accelerating fastest among fleet operators seeking automated perimeter breach alerts.
The US NHTSA and FCC jointly shape device certification and spectrum allocation for vehicle-integrated transmitters, while the EU Green Deal and GDPR create dual pressures for low-power hardware design and strict data governance in cross-border tracking services. Brazil's ANVISA and sectoral insurance regulators mandate telematics-linked coverage tiers, directly stimulating aftermarket installation demand. Stakeholders must monitor evolving encryption standards and cross-border data localization rules as these will determine which platform architectures achieve scalable deployment across fragmented national compliance regimes.
Market Dynamics
Insurance-linked telematics mandates through Brazil's ANVISA and sectoral directives are forcing hardware suppliers to recertify platforms for dual-use recovery and premium-tier coverage verification, compressing product development cycles across the value chain.
Growth Catalysts
- Fleet Telematics Integration:Commercial vehicle operators in the United States are embedding stolen vehicle recovery modules into unified fleet management dashboards, creating bundled procurement pull-through for integrated platforms.
- ANVISA Insurance Mandates:Brazil's national health surveillance agency and insurance regulators now require telematics-linked coverage tiers, directly stimulating aftermarket installation demand for certified tracking hardware.
- Cellular Network Density:Mature 4G and expanding 5G infrastructure across Germany and China enables sub-60-second refresh rates for real-time recovery coordination without satellite fallback costs.
Market Restraints
- Semiconductor Supply Concentration:GPS chipset fabrication concentrates in Taiwan and South Korean foundries, exposing hardware manufacturers to single-source disruption risk for location-acquisition modules.
- GDPR Cross-Border Friction:The EU's data governance framework imposes strict localization requirements on geolocation data storage, forcing platform operators to maintain separate server architectures for European fleet deployments.
- Cellular Coverage Gaps:Remote-area commercial fleets in mining and agriculture operations face dead zones where terrestrial networks fail, requiring costly dual-mode GPS-satellite hardware that inflates unit economics.
Strategic Opportunities
- Electric Vehicle Native Integration:OEMs are designing stolen vehicle recovery into battery management system architectures from the chassis-up, creating captive supply relationships for next-generation connected-car platforms.
- Geofencing Automation:Fleet operators in China are deploying automated perimeter breach alerts for high-value cargo routes, opening subscription revenue streams beyond basic recovery services.
- NHTSA Certification Harmonization:Potential alignment between US vehicle safety and communications regulators could streamline device approval pathways, reducing time-to-market for integrated transmitter designs.
Industry Challenges
- GNSS Fusion Engineering Talent:The specialized skill set combining satellite navigation algorithms with cellular modem integration remains scarce, constraining R&D velocity for algorithm-intensive platform developers.
- Multi-Regulatory Certification Timelines:Hardware must simultaneously satisfy FCC spectrum allocation, NHTSA safety integration, and GDPR data governance standards, extending validation cycles before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stolen Vehicle Tracking System Market |
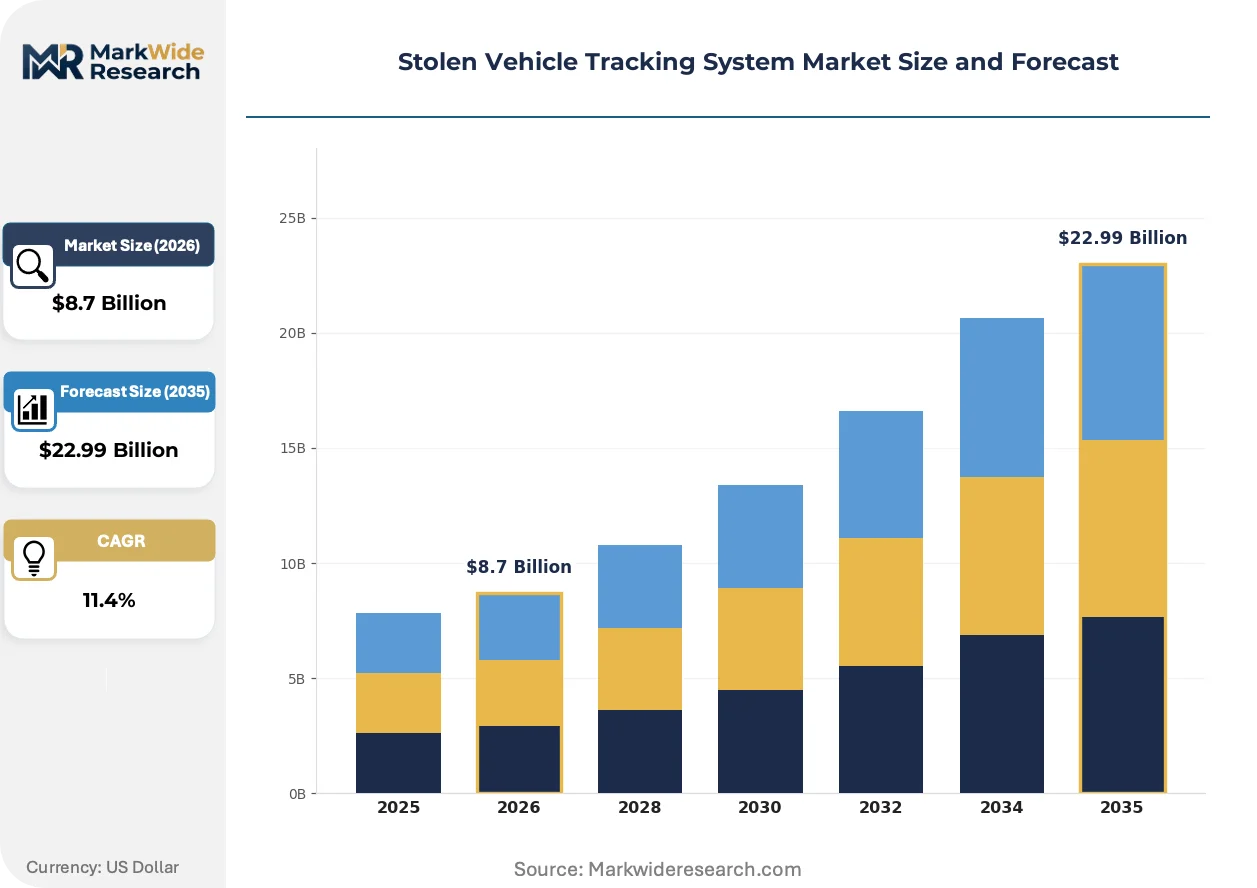
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Trackers, RFID Systems, Cellular Trackers, Satellite Trackers Technology: Real-time Monitoring, Geofencing, Alerts and Notifications, Data Analytics End User: Fleet Operators, Insurance Companies, Individual Consumers, Law Enforcement Installation Type: Professional Installation, DIY Installation, Integrated Solutions, Standalone Devices |
| Companies Covered | Continental AG, Tokai Rika, Robert Bosch GmbH, Mitsubishi Electric Corporation, OMRON Corporation, Lear Corporation, Denso Corporation, LoJack Corporation, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stolen Vehicle Tracking System Market Evolving Landscape
Hardware architectures are fragmenting between low-power cellular trackers for urban fleet density and dual-mode satellite-cellular units for remote coverage, with software layers converging toward unified fleet dashboards that embed recovery as one module among many.
Dual-frequency GNSS chipsets are bifurcating the precision tier of the tracking hardware market. These modules process both L1 and L5 satellite bands to deliver meter-level accuracy in urban canyon environments where single-frequency GPS fails. High-value cargo fleets in Germany and the United States are specifying dual-frequency as a procurement standard, compressing margins for single-band hardware suppliers unable to upgrade semiconductor content.
GDPR's cross-border data localization requirements are forcing platform operators to rearchitect cloud infrastructure. The regulation mandates that European driver location histories remain within EU jurisdiction, blocking seamless global fleet monitoring from centralized US or Asian data centers. German fleet operators are responding by demanding region-locked server deployments with encrypted handoff protocols for international route segments.
Subscription bundling is displacing standalone recovery service contracts. Fleet procurement teams in China and the United States now specify stolen vehicle tracking as one component within unified telematics suites rather than purchasing discrete recovery platforms. This consolidation favors vendors with broad sensor-to-cloud portfolios over specialized recovery-only suppliers, compressing channel margins for single-product hardware manufacturers.
Stolen Vehicle Tracking System Market Segmentation
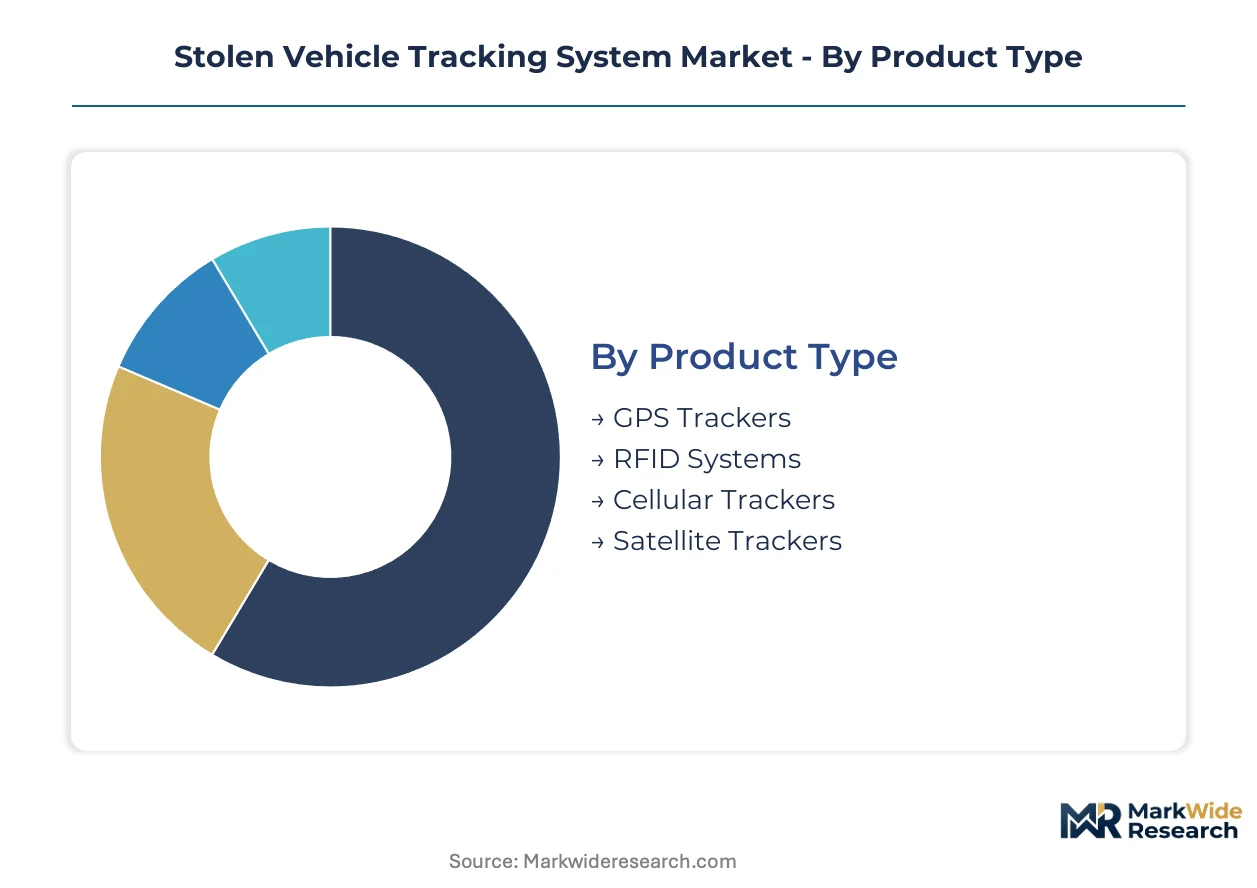
Segmentation in stolen vehicle tracking systems reveals how hardware specifications, connectivity protocols, and installation methods align with distinct regulatory environments and recovery workflows. Understanding these divisions enables stakeholders to match platform architectures against certification requirements and end-user operational constraints.
Product Type:
FCC and NHTSA certification pathways diverge sharply across hardware categories, with cellular and satellite transmitters facing distinct spectrum allocation and safety integration standards.
- GPS Trackers:Single-frequency and dual-frequency modules process L1 and L5 satellite bands for location acquisition with refresh rates under 60 seconds. Fleet operators in the United States specify these for urban commercial vehicle pools where cellular network density supports real-time coordination without satellite fallback costs.
- Satellite Trackers:Dual-mode GPS-satellite hardware maintains connectivity beyond terrestrial coverage through dedicated orbital networks. Mining and agriculture fleets in remote-area operations absorb premium unit economics to eliminate cellular dead zones, with Brazil's ANVISA mandates accelerating adoption for insurance-linked coverage verification.
- Cellular Trackers:4G and 5G modem-integrated units leverage mature carrier infrastructure for cost-effective urban deployment.
- RFID Systems:Short-range identification hardware supports localized asset verification at checkpoints and impound facilities.
Established volume favors GPS Trackers; emerging adoption favors Satellite Trackers.
Technology:
Margin concentration shifts toward software layers that unify multiple tracking modalities into subscription-based fleet dashboards.
- Real-time Monitoring:Continuous geolocation transmission with sub-60-second refresh rates enables immediate recovery coordination with law enforcement. German fleet operators specify this as baseline functionality for high-value cargo routes under GDPR-compliant data governance frameworks.
- Geofencing:Automated perimeter breach detection triggers alerts when vehicles exit defined geographic boundaries. Chinese logistics providers deploy this for automated security protocols on cross-border freight corridors, opening recurring subscription revenue beyond basic recovery services.
- Alerts and Notifications:Multi-channel status updates via SMS, push, or email inform stakeholders of unauthorized movement or tampering events.
- Data Analytics:Pattern recognition and route optimization modules transform raw location streams into operational intelligence.
Revenue concentration sits with Real-time Monitoring; steepest expansion trajectory belongs to Geofencing.
End User:
Procurement authority determines whether tracking platforms are bundled into broader telematics suites or purchased as standalone recovery services.
- Fleet Operators:Commercial vehicle pool managers embed stolen vehicle recovery into unified fleet management dashboards. United States-based operators drive bundled procurement pull-through for integrated platforms that combine tracking with fuel monitoring and driver behavior analytics.
- Insurance Companies:Underwriters mandate certified hardware installation for premium-tier coverage verification. Brazilian insurers leverage ANVISA-linked telematics directives to enforce aftermarket installation standards across personal and commercial vehicle policies.
- Individual Consumers:Personal vehicle owners purchase discrete recovery services through dealer channels or direct retail.
- Law Enforcement:Police agencies coordinate with specialized recovery providers to intercept stolen assets through dedicated communication protocols.
Contract scale favors Fleet Operators; regulatory compulsion favors Insurance Companies.
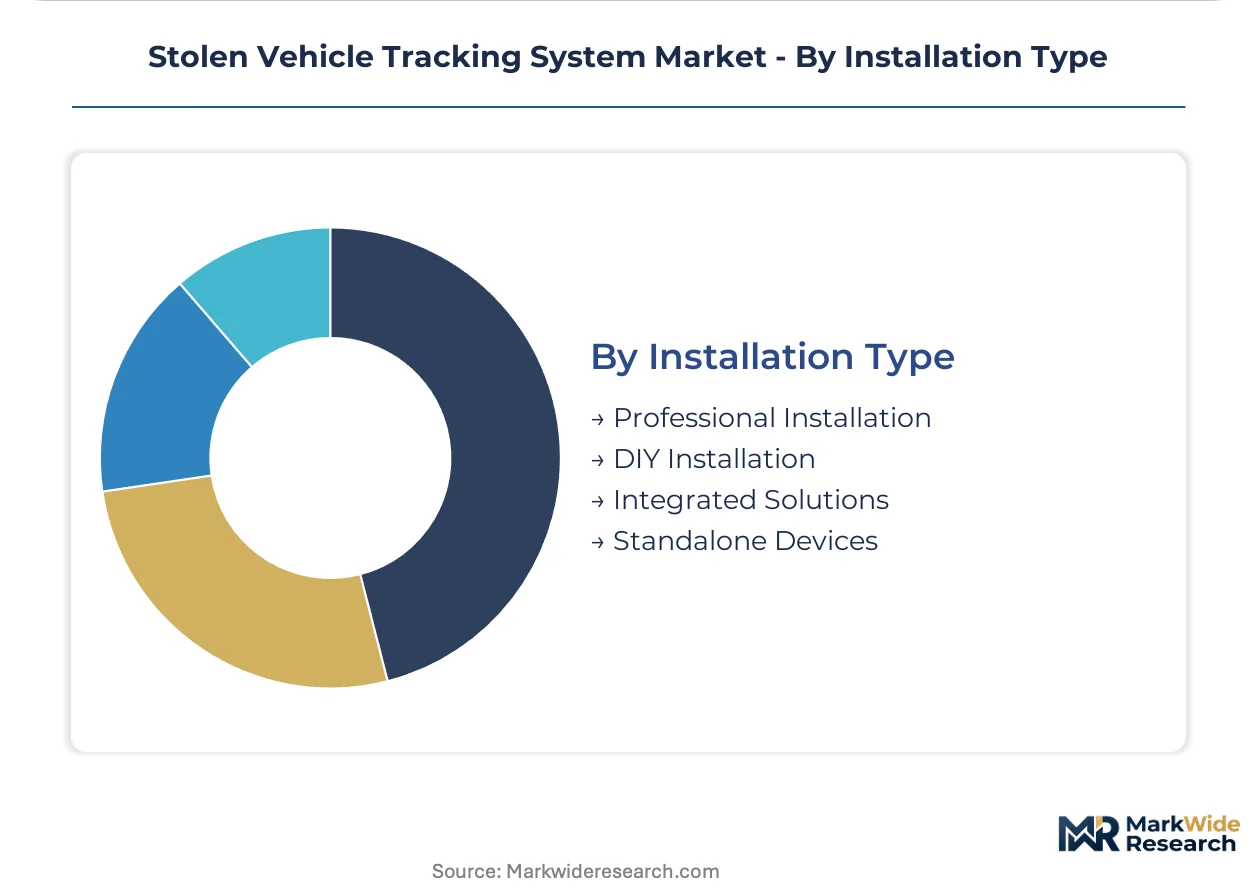
Installation Type:
Supply chain configuration separates professional integration services from consumer-direct hardware distribution.
- Integrated Solutions:OEM-designed recovery modules embedded at vehicle manufacture into battery management and connected-car architectures. Electric vehicle producers in Germany and China specify these for native platform compatibility from chassis-up design phases.
- Professional Installation:Certified technician deployment ensures concealed placement and electrical system integration. Aftermarket demand concentrates in Brazil where ANVISA mandates require verified installation for insurance compliance.
- DIY Installation:Plug-and-play devices target individual consumers through retail and e-commerce channels.
- Standalone Devices:Portable battery-powered trackers serve temporary or transferable asset protection needs.
Technology lock-in favors Integrated Solutions; compliance-driven demand favors Professional Installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication for GPS chipsets concentrates in Taiwan and South Korean foundries, creating geographic dependencies that shape hardware supply chains. End-user deployment clusters in three distinct regulatory environments with divergent certification requirements.
United States
Fleet operators in California and Texas embed stolen vehicle recovery into unified telematics dashboards, driving bundled procurement for integrated platforms. NHTSA and FCC jointly regulate device certification and spectrum allocation for vehicle-integrated transmitters. The Detroit automotive cluster anchors OEM integration programs for next-generation connected-car architectures.
Germany
German fleet operators specify real-time monitoring with sub-60-second refresh rates for high-value cargo routes traversing the Rhine-Ruhr industrial corridor. GDPR imposes strict data localization requirements, forcing platform operators to maintain EU-jurisdiction server architectures. Bavaria's automotive engineering centers drive dual-frequency GNSS chipset adoption for meter-level urban accuracy.
China
Logistics providers in the Yangtze River Delta deploy geofencing automation for automated perimeter breach alerts on cross-border freight corridors. MIIT governs telecommunications equipment certification and spectrum allocation for cellular-enabled trackers. Shenzhen's electronics manufacturing hub supplies mature 4G and 5G modem components for cost-effective urban deployment.
Brazil
ANVISA and sectoral insurance regulators mandate telematics-linked coverage tiers, stimulating aftermarket installation demand across São Paulo and Rio de Janeiro commercial vehicle pools. Certified hardware installation requires verified technician deployment for insurance compliance. The Southeast industrial belt concentrates professional installation services for ANVISA-compliant tracking systems.
Stolen Vehicle Tracking System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the stolen vehicle tracking system market. The competitive structure fragments between integrated OEM suppliers, specialized recovery service providers, and modular component fabricators. Three archetypes dominate: sensor-to-cloud vertical integrators, GNSS algorithm specialists, and law enforcement channel operators. M&A activity concentrates on telematics platform consolidation, while strategic partnerships target battery management system integration for electric vehicle native architectures.
Among German automotive suppliers, Continental AG and Robert Bosch GmbH exemplify the integrated OEM archetype through their sensor-to-cloud and GNSS fusion positioning. LoJack Corporation occupies a distinct position within the North American recovery services tier, anchoring specialized law enforcement coordination capabilities. These three players represent divergent strategic vectors: vertical integration, precision navigation engineering, and institutional channel control.
| Leading Market Players |
|---|
| Continental AG |
| Tokai Rika |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| OMRON Corporation |
| Lear Corporation |
| Denso Corporation |
| LoJack Corporation |
| Valeo |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Brazilian insurers and certified installation networks lock in both hardware supply access and price visibility for ANVISA-compliant tracking systems, insulating procurement teams from spot-market volatility in GPS chipset supply. These arrangements concentrate pricing power with vertically integrated OEMs capable of guaranteeing dual-frequency GNSS module availability through dedicated foundry capacity.
Pricing Analysis
ANVISA certification dictates the pricing tier structure across the stolen vehicle tracking system market, separating premium-grade dual-frequency hardware from standard single-band units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and after-sales service bundling. Cost compression in the standard tier is intensifying because fleet operators in the United States and China consolidate procurement into unified telematics suites. Insurance companies demonstrate the lowest price sensitivity due to regulatory compulsion, while individual consumers exhibit the highest.
Supply Chain Analysis
Strategic stockpiling of dual-frequency GNSS chipsets dominates inventory strategy as Taiwanese and South Korean foundry capacity faces allocation pressure from automotive and consumer electronics demand. Hardware assembly draws from mature 4G and 5G modem component ecosystems in Shenzhen, with final integration concentrating in Germany and China. Single-source vulnerability in GPS chipset fabrication from Taiwan and South Korea exposes manufacturers to disruption risk. Distribution runs through certified technician networks in Brazil and OEM captive channels in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of GNSS fusion engineering talent capable of combining satellite navigation algorithms with cellular modem integration constrains R&D velocity and consolidates competitive advantage among incumbent algorithm specialists. This capability gap shapes strategic positioning across all stakeholder archetypes.
For Market Incumbents: Fortify algorithm-intensive platform development through captive supply relationships with Taiwanese foundries for dual-frequency chipset allocation priority. Deepen defensive patent positioning around GNSS-cellular fusion protocols before emerging modular component suppliers achieve technical parity. The threat of subscription bundling by broad telematics portfolios compresses margins for single-product hardware manufacturers. For New Entrants and Emerging Players: Differentiate on geofencing automation software layers rather than competing in hardware volume against established OEM sensor-to-cloud verticals. Target white-space opportunities in remote-area mining and agriculture fleets across Brazil and Australia requiring dual-mode GPS-satellite hardware beyond cellular coverage. A direct-to-fleet-operator SaaS pricing model bypasses incumbent law enforcement channel control. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors algorithm-specialist acquisition targets with proven GNSS fusion engineering teams. Long-term viability over the next decade rests on electric vehicle native integration capabilities and battery management system architecture access. Watch for NHTSA-FCC certification harmonization proposals as the inflection signal for streamlined integrated transmitter approval pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Frequency GNSS Chipset Integration | Enables meter-level urban accuracy for high-value cargo fleets in Germany and the United States. |
| ANVISA Certification Investment | Unlocks mandatory insurance-linked installation demand across São Paulo commercial vehicle pools. |
| Geofencing Automation Platform | Opens recurring subscription revenue beyond basic recovery for Chinese logistics providers. |
| GDPR-Compliant Server Architecture | Secures German fleet operator contracts through EU-jurisdiction data localization compliance. |
| Electric Vehicle Native Integration | Creates captive supply relationships with OEMs designing recovery into battery management systems. |
Research Methodology
A spread of perspectives from fleet operations directors, insurance underwriting leads, GNSS hardware engineers, and certified installation technicians converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FCC device certification databases, NHTSA safety integration filings, ANVISA regulatory directives, and customs trade data on GPS chipset imports. Bottom-up unit economics modeling triangulated against top-down fleet penetration estimates across the United States, Germany, China, and Brazil.
Segmentation dimensions modeled include hardware type, connectivity protocol, installation method, end-user archetype, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed base growth trajectories and average revenue per unit expansion in subscription-based fleet dashboards. Industry-specific forecast inputs incorporated 4G and 5G network density buildout schedules and electric vehicle platform integration roadmaps from German and Chinese OEMs.
Material uncertainties — semiconductor foundry allocation shifts, encryption standard revisions, and cross-border data localization rule changes — sit outside the modeled envelope. Forecasts reflect assumptions about sustained carrier infrastructure investment and stable regulatory certification timelines. Revision becomes warranted when dual-frequency GNSS chipset supply constraints or ANVISA mandate enforcement intensity crosses thresholds that alter hardware availability or insurance compliance economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Automotive Front-End Collision Warning System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Global Airbag Systems Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Automotive Brake System Market