
 Adaptive Front Lighting Market | 2026-2036
Adaptive Front Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptive Front Lighting Market Outlook
Project finance and leasing structures for automotive lighting modules is reshaping competitive entry in the Adaptive Front Lighting Market. Valeo leverages its integrated electronics-photonics platform to sustain design wins across European premium OEMs. Continental AG anchors its position through captive software development for adaptive control algorithms. Koito Manufacturing Co., Ltd. dominates headlamp supply chains for Japanese and North American vehicle platforms.
Adaptive front lighting comprises electronically controlled headlamp assemblies that modulate beam patterns, intensity, and direction based on vehicle speed, steering angle, and ambient conditions, typically operating across 3,000 to 6,000 Kelvin color temperatures with response latencies below 100 milliseconds. LED product types now lead unit shipments due to thermal efficiency and dimming precision, while laser segments command concentrated margin pools in ultra-premium applications. Matrix lighting technology is displacing conventional dynamic bending systems as the default specification in European passenger vehicles, though glare-free architectures remain concentrated in flagship nameplates.
The European Commission's ECE R48 regulation mandates automatic levelling and cleaning for high-intensity discharge systems, while the EU General Safety Regulation requires adaptive front lighting on new vehicle categories. NHTSA in the United States maintains divergent beam pattern standards that fragment homologation requirements for suppliers serving transatlantic OEMs. Stakeholders must monitor regulatory harmonization progress between UN ECE and FMVSS frameworks to determine platform engineering investment timing.
Market Dynamics
Matrix LED architectures are compressing development cycles across the Adaptive Front Lighting Market as European OEMs mandate glare-free beam precision in next-generation platforms, forcing suppliers to consolidate photonics and software competencies under unified engineering centers.
Growth Catalysts
- EU General Safety Regulation:Mandates adaptive front lighting for new vehicle categories, creating compliance-driven replacement demand across German, French, and Italian automotive assembly lines.
- Japanese luxury export platforms:Toyota and Honda tier-one suppliers now specify matrix headlamps as standard equipment for North American and European-bound nameplates, transferring specification authority from regional to global procurement teams.
- Laser diode thermal efficiency:Enables 600-meter throw distances at reduced wattage, satisfying premium OEM requirements for high-beam performance without violating ECE R48 power consumption thresholds.
Market Restraints
- Silicon carbide substrate costs:Power electronics for adaptive beam control rely on SiC semiconductors whose foundry capacity concentrates in Taiwan and Germany, exposing module assemblers to input price volatility.
- Homologation fragmentation:NHTSA maintains FMVSS 108 beam pattern standards that diverge from UN ECE frameworks, forcing suppliers to engineer dual-specification optical assemblies for transatlantic vehicle programs.
- Dynamic bending light substitution:Lower-cost swiveling headlamp systems retain specification share in economy and mid-market segments, limiting matrix technology penetration below premium vehicle tiers.
Strategic Opportunities
- Indian premium vehicle assembly:Mercedes-Benz and BMW manufacturing hubs near Pune and Chennai currently import complete headlamp modules; localized Tier 1 sourcing mandates under the PLI scheme create entry pathways for adaptive lighting suppliers.
- Software-defined beam control:Convergence of adaptive lighting firmware with ADAS sensor fusion stacks enables over-the-air pattern updates, converting hardware sales into recurring calibration revenue streams.
- Aftermarket retrofit channels:Specialized distributors in Germany and California now offer ECE-compliant matrix upgrade kits for legacy LED platforms, extending technology reach beyond factory-installed applications.
Industry Challenges
- Optomechanical engineering scarcity:The intersection of precision optics, thermal management, and real-time control algorithm development requires talent pools concentrated in Stuttgart, Nagoya, and Detroit metropolitan clusters.
- ISO 26262 functional safety certification:Adaptive beam control systems require ASIL-B compliance documentation that extends validation timelines by 14-18 months for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptive Front Lighting Market |
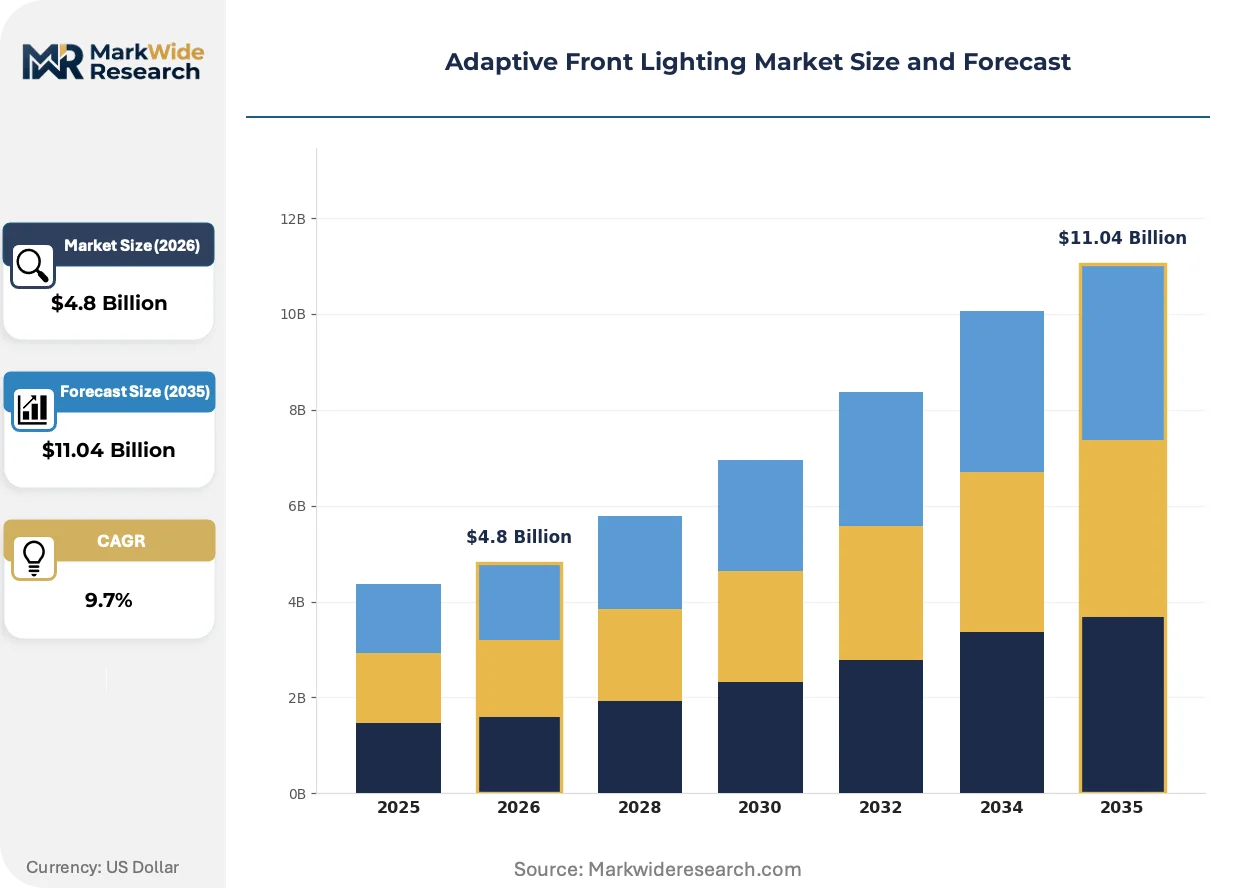
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Xenon, Halogen, Laser Application: Passenger Vehicles, Commercial Trucks, Buses, Motorcycles Technology: Adaptive Control, Dynamic Bending, Matrix Lighting, Glare-Free End User: OEMs, Aftermarket Providers, Fleet Operators, Tier-1 Suppliers |
| Companies Covered | Valeo, Continental AG, HELLA GmbH & Co. KGaA, Hyundai Mobis, Koito Manufacturing Co., Ltd., OSRAM Licht AG, Stanley Electric Co., Ltd., Magneti Marelli, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive Front Lighting Market Strategic Shifts
Digital light processing is dissolving the boundary between headlamp hardware and software-defined vehicle architectures, enabling real-time beam pattern computation that responds to cloud-updated road condition databases rather than fixed sensor inputs.
Micro-LED array technology is virtualizing the traditional reflector-projector optical stack. Premium German OEMs now specify chip-on-board LED matrices with 25,000 individually addressable pixels, replacing mechanical shutter systems with pure software-controlled illumination zones. This compression eliminates moving parts while enabling projection of navigation arrows and pedestrian warning symbols directly onto road surfaces.
ECE R48 revision 7 introduces mandatory automatic headlamp levelling for all LED systems above 2,000 lumens, extending regulatory scope beyond HID technologies. The amendment forces mid-market vehicle platforms to incorporate height sensors and servo motors previously reserved for luxury segments. Suppliers serving the Volkswagen Group and Stellantis must now engineer cost-optimized levelling mechanisms that satisfy durability requirements without premium-tier pricing.
Fleet procurement teams at German commercial vehicle operators now specify total-cost-of-ownership contracts that unbundle headlamp hardware from lifetime calibration and software update services. This purchasing model transfers technology obsolescence risk from end-users to Tier 1 suppliers, who must price predictive maintenance algorithms into initial module contracts. The shift is most visible in long-haul trucking segments where adaptive cornering illumination reduces nighttime accident rates and associated insurance liabilities.
Adaptive Front Lighting Market Segmentation
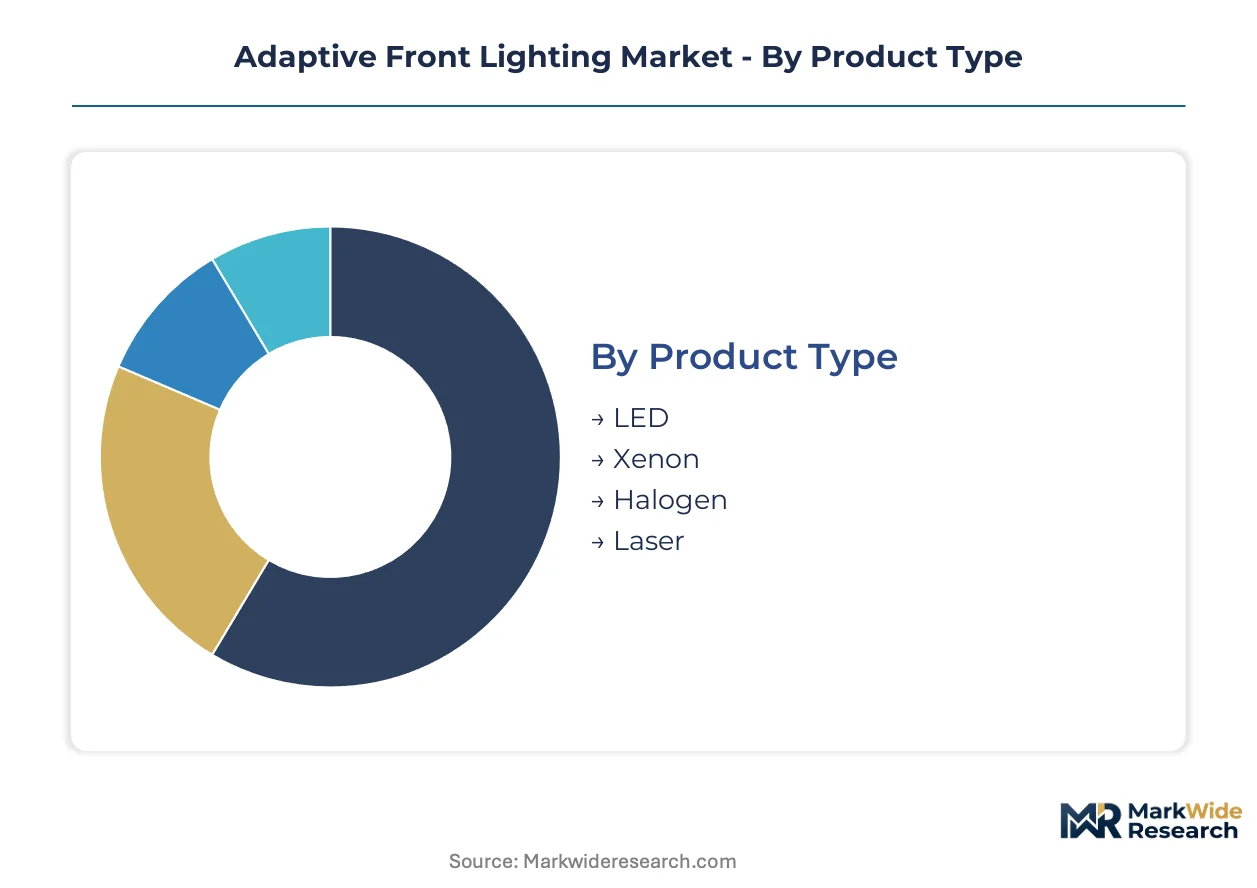
Adaptive front lighting technology fragments across multiple technical and commercial dimensions, with each segmentation axis revealing distinct margin structures and competitive entry points. Understanding these boundaries illuminates where specification authority concentrates and where supplier consolidation opportunities emerge.
Product Type:
Light source selection determines thermal management requirements, optical efficiency, and compliance thresholds across vehicle platforms.
- LED:Solid-state semiconductor emitters operating at 3,000-6,000 Kelvin with instant dimming response and 50,000-hour lifespans. German and Japanese OEMs now specify LED as baseline for matrix architectures, driven by ECE R48 revision 7 levelling mandates for systems above 2,000 lumens.
- Laser:Diode-pumped phosphor systems achieving 600-meter throw distances at reduced wattage. Ultra-premium nameplates from Stuttgart and Munich manufacturing clusters specify laser for high-beam performance without violating power consumption thresholds.
- Xenon:High-intensity discharge arc lamps requiring automatic levelling and cleaning mechanisms under legacy ECE R48 provisions. Mid-market European platforms retain xenon where LED module costs exceed platform pricing constraints.
- Halogen:Tungsten-halogen filament technology with limited adaptive functionality. Emerging market vehicle programs in India specify halogen for entry-tier nameplates where full adaptive capability remains optional.
The dominant share belongs to LED, while laser is closing the gap fastest.
Application:
Vehicle category dictates beam pattern complexity, regulatory scrutiny, and procurement authority structures.
- Passenger Vehicles:Light-duty automobiles encompassing sedans, SUVs, and crossovers with multi-zone matrix requirements. European premium OEMs mandate glare-free beam precision as standard equipment, transferring specification authority from regional to global procurement teams.
- Commercial Trucks:Heavy-duty freight vehicles operating across extended nighttime hours. German fleet operators now specify total-cost-of-ownership contracts unbundling hardware from lifetime calibration services, transferring obsolescence risk to Tier 1 suppliers.
- Buses:Urban and intercity passenger transport with asymmetric beam requirements for curb-side illumination. Municipal procurement authorities in France and Germany prioritize accident rate reduction through adaptive cornering functionality.
- Motorcycles:Two-wheeled vehicles with severe weight and packaging constraints. Japanese manufacturers dominate headlamp supply chains for North American and European-bound sport touring platforms.
Passenger vehicles command the installed base, though commercial trucks demonstrate the steepest expansion trajectory as fleet operators quantify insurance liability reductions.
Technology:
Control architecture determines software complexity, sensor integration depth, and functional safety certification burden.
- Matrix Lighting:Chip-on-board LED arrays with 25,000 individually addressable pixels replacing mechanical shutters. Premium German OEMs specify pure software-controlled illumination zones enabling road-surface projection of navigation and warning symbols.
- Glare-Free:Selective beam masking preventing oncoming driver dazzle through real-time opponent detection. Flagship nameplates concentrate this architecture where component costs support retail pricing premiums.
- Dynamic Bending:Swiveling headlamp assemblies tracking steering angle with mechanical actuators. Economy and mid-market segments retain this lower-cost specification, limiting matrix penetration below premium tiers.
- Adaptive Control:Integrated sensor-fusion systems modulating intensity and direction based on vehicle speed, ambient conditions, and navigation data. Firmware convergence with ADAS stacks enables over-the-air pattern updates.
Matrix lighting has secured the specification majority in European passenger vehicles, while adaptive control firmware is gaining share fastest through software-defined vehicle architectures.
End User:
Procurement channel determines pricing power, technical specification authority, and lifetime revenue capture mechanisms.
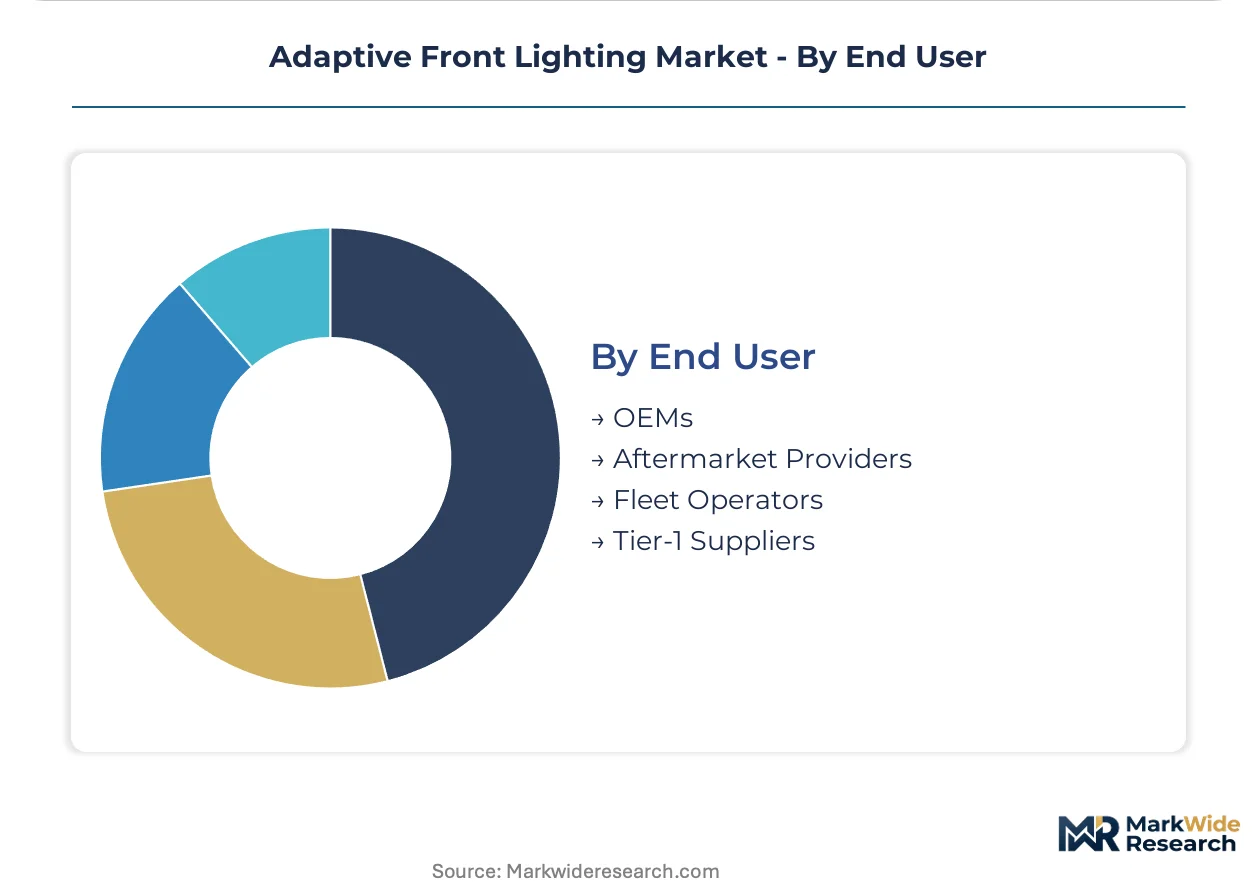
- OEMs:Original equipment manufacturers with platform-level engineering integration and multi-year supply agreements. Volkswagen Group and Stellantis procurement teams now mandate cost-optimized levelling mechanisms satisfying durability requirements without premium-tier pricing.
- Tier-1 Suppliers:Module assemblers serving as specification intermediaries between lighting specialists and vehicle platforms. Valeo, Continental AG, and Koito Manufacturing anchor positions through captive electronics, software, and supply chain control respectively.
- Fleet Operators:Commercial vehicle purchasers prioritizing total-cost-of-ownership over acquisition price. Long-haul trucking segments specify predictive maintenance algorithms priced into initial module contracts.
- Aftermarket Providers:Independent distributors serving vehicle retrofit and replacement demand. Specialized channels in Germany and California offer ECE-compliant matrix upgrade kits extending technology reach beyond factory installations.
OEMs retain the dominant procurement volume, though Tier-1 suppliers are consolidating specification authority fastest through integrated photonics-software platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports adaptive lighting modules to assembly plants across three continents, while Japan and the United States balance domestic production with selective imports for luxury nameplates. Trade flows concentrate between Stuttgart, Nagoya, and Detroit engineering centers.
Germany
Premium OEM procurement teams at BMW and Mercedes-Benz mandate matrix headlamps as standard equipment. ECE R48 revision 7 levelling requirements force mid-market platforms to adopt height sensors previously reserved for luxury segments. Stuttgart and Munich clusters host Valeo and Continental AG engineering centers serving Volkswagen Group platforms.
United States
Domestic assembly of German and Japanese luxury nameplates drives module import demand from European and Asian suppliers. NHTSA FMVSS 108 beam pattern standards diverge from UN ECE frameworks, forcing dual-specification optical engineering. Detroit metropolitan area concentrates Tier 1 supplier technical centers serving Ford and General Motors.
Japan
Toyota and Honda tier-one suppliers specify matrix headlamps as standard for North American and European export platforms. METI industrial standards coordinate with ECE frameworks to reduce homologation burden for global vehicle programs. Nagoya prefecture anchors Koito Manufacturing and Stanley Electric production and R&D facilities.
China
Domestic premium vehicle assembly by joint-venture partners creates localized sourcing pressure for adaptive lighting modules. MIIT automotive standards gradually align with UN ECE technical provisions. Yangtze River Delta clusters near Shanghai concentrate module assembly operations for SAIC and FAW platforms.
India
Mercedes-Benz and BMW manufacturing hubs near Pune and Chennai currently import complete headlamp modules. PLI scheme localization mandates create entry pathways for adaptive lighting suppliers establishing Tier 1 presence. Maharashtra state government incentives target automotive electronics component manufacturing.
Adaptive Front Lighting Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in photonics and semiconductor supply. The vendor base organizes into three layers: captive electronics divisions of major Tier 1 suppliers, independent lighting specialists with integrated software capabilities, and optical component manufacturers serving multiple module assemblers. Strategic consolidation moves center on photonics-software integration and geographic proximity to premium OEM engineering centers.
Among French and German platform integrators, Valeo and Continental AG represent the integrated electronics-photonics archetype, while Koito Manufacturing Co., Ltd. exemplifies the supply chain anchor position for Japanese and North American vehicle platforms. These three entities occupy positions that illustrate how specification authority concentrates through captive software development and regional supply chain control.
| Leading Market Players |
|---|
| Valeo |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Hyundai Mobis |
| Koito Manufacturing Co., Ltd. |
| OSRAM Licht AG |
| Stanley Electric Co., Ltd. |
| Magneti Marelli |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Stuttgart and Nagoya engineering clusters control photonics-software integration capacity for adaptive lighting modules, concentrating specification authority and compressing margin capture for downstream assemblers serving European and Japanese OEM platforms.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Adaptive Front Lighting Market. Three-tier pricing structure across premium, standard, and economy levels separates laser-equipped flagship platforms from LED matrix mid-market specifications and halogen entry-tier assemblies. Cost compression in standard LED tiers is intensifying because Volkswagen Group and Stellantis procurement teams mandate cost-optimized levelling mechanisms without premium-tier durability pricing. Fleet operators at German commercial vehicle purchasers demonstrate the highest price sensitivity through total-cost-of-ownership contracting, while ultra-premium German OEMs show the least sensitivity where beam performance justifies retail pricing premiums.
Supply Chain Analysis
Extended payment terms from German and Japanese OEM procurement teams stretch Tier 2 optical component suppliers, forcing supply-chain finance facility reliance among smaller photonics specialists. Module assembly concentrates in Germany, Japan, and China, with Yangtze River Delta clusters feeding SAIC and FAW joint-venture platforms. Silicon carbide substrates for adaptive beam control electronics draw from Taiwan and German foundry capacity. Single-source vulnerability around SiC semiconductor supply exposes module assemblers to input price volatility. Distribution runs through captive Tier 1 supplier networks with direct OEM platform integration, limiting aftermarket channel penetration outside specialized German and California retrofit distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Adaptive Front Lighting Market operates as a defensive-moat story where regulatory entrenchment through ECE R48 and EU General Safety Regulation mandates creates high switching costs for OEM platform engineering teams.
For Market Incumbents: Build captive software moats through adaptive control algorithm ownership that fuses lighting firmware with ADAS sensor fusion stacks. Deepen upstream control over silicon carbide power electronics supply through foundry partnership structures or in-house packaging capabilities. Koito Manufacturing and Valeo face emerging threat from Chinese joint-venture module assemblers capturing localized sourcing mandates under India's PLI scheme. For New Entrants and Emerging Players: Mid-market commercial truck platforms in India represent the most penetrable entry point where Mercedes-Benz and BMW manufacturing hubs near Pune and Chennai currently import complete headlamp modules. Software-defined beam control calibration services offer recurring revenue capture without full module assembly investment. Target fleet procurement teams through predictive maintenance algorithm bundling rather than hardware-only positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compounding play because ECE R48 revision 7 extends automatic levelling mandates to mid-market LED systems above 2,000 lumens, structurally expanding addressable market beyond premium tiers. Acquisition target archetype: Tier 2 photonics specialists with ISO 26262 ASIL-B certification documentation and existing supply relationships to Stuttgart or Nagoya engineering centers. Monitor NHTSA-FMVSS harmonization progress with UN ECE frameworks as inflection indicator for transatlantic platform standardization investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Beam Control Investment | Enables over-the-air pattern updates through ADAS sensor fusion convergence at BMW and Mercedes-Benz platforms. |
| Silicon Carbide Supply Agreement | Secures foundry capacity for adaptive beam control electronics amid Taiwan and Germany capacity concentration. |
| ISO 26262 ASIL-B Certification Pathway | Extends validation timelines by 14-18 months but unlocks Volkswagen Group and Stellantis platform access. |
| Indian Manufacturing Footprint Establishment | Captures PLI scheme localization mandates for Mercedes-Benz and BMW assembly hubs near Pune and Chennai. |
| Aftermarket Retrofit Channel Partnership | Extends technology reach beyond factory installations through specialized German and California distributor networks. |
Study Parameters
The analysis maps LED, laser, xenon, and halogen light source sub-sectors, each validated through Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distribution specialists, and fleet operator procurement teams. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, ECE regulatory filings, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up unit shipment modeling triangulated against top-down OEM platform content-per-vehicle estimates across passenger vehicle, commercial truck, bus, and motorcycle application categories.
Assumptions held fixed include ECE R48 revision 7 enforcement timelines and EU General Safety Regulation mandate scope, while variables included NHTSA-FMVSS harmonization progress and silicon carbide foundry capacity expansion rates. The analytical framework modeled volume and value outputs across product type, application, technology, and end-user segmentation dimensions throughout the forecast period. CAGRs derived from S-curve technology adoption modeling calibrated to premium vehicle platform refresh cycles and mid-market regulatory compliance deadlines. Industry-specific inputs encompassed beam pattern complexity indices and functional safety certification burden estimates.
Practitioners should monitor regulatory harmonization progress, SiC semiconductor supply disruptions, and Indian PLI scheme localization enforcement for early signals of forecast deviation. Macroeconomic contraction in German and Japanese luxury vehicle demand, NHTSA beam pattern standard divergence persistence, or breakthrough micro-LED cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Active Safety Sensors Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market