
 APAC Packaging Automation Market | 2026-2036
APAC Packaging Automation Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Packaging Automation Market Outlook
Skilled automation technician availability is rotating toward scarcity across Southeast Asian manufacturing hubs, forcing OEMs and system integrators to redesign machine interfaces for lower-skill operability. Fanuc Corporation leverages its regional service network to sustain long-term maintenance contracts in Thailand and Vietnam. Mitsubishi Electric Corporation anchors high-speed motion control architectures that dominate Japanese and South Korean precision packaging lines. ABB Ltd. competes on collaborative robot palletizing solutions that reduce dependency on scarce forklift-certified labor pools.
APAC packaging automation encompasses electromechanical systems that execute material handling, forming, filling, sealing, labeling, and palletizing operations at throughput rates exceeding 600 units per minute with positional repeatability within 0.1 millimeter. These systems integrate servo motors, programmable logic controllers, and machine vision to ensure seal integrity, weight accuracy, and regulatory traceability across high-volume consumer and pharmaceutical production environments. Robotic systems capture the largest installed base due to flexibility in handling irregular package geometries, while AI Integration represents the fastest-expanding technology layer as manufacturers deploy predictive maintenance algorithms to minimize unplanned downtime. IoT-based Solutions mature more slowly where legacy OPC-UA retrofit costs deter mid-tier producers.
China's SAMR enforces GB standards for food contact material safety that directly shape machine material specifications and clean-in-place protocol requirements. Japan's METI promotes JIS-compliant smart factory frameworks that accelerate domestic adoption of interconnected control architectures. India's BIS certification mandates for imported packaging machinery create market access barriers that favor localized assembly partnerships. Stakeholders must monitor how divergent national digital infrastructure readiness shapes the pace at which cloud-connected automation platforms achieve operational viability across heterogeneous factory estates.
Market Dynamics
China's dual carbon goals and tightening energy-efficiency mandates are pressuring factories to replace legacy pneumatic systems with servo-driven architectures, compressing equipment replacement cycles and reshaping vendor qualification criteria across the region.
Growth Catalysts
- EU FMD and US DSCSA traceability rules:India's pharmaceutical packaging corridors around Hyderabad and Ahmedabad require serialization-ready automation, pulling investment into track-and-trace capable filling and sealing lines.
- Food and beverage volume targets:Manufacturers accelerate deployment of automated filling and sealing lines to meet hygiene benchmarks and throughput requirements exceeding 600 units per minute.
- Servo motor adoption:China's energy-efficiency mandates favor electromechanical systems over pneumatic alternatives, creating replacement demand across legacy factory estates.
Market Restraints
- Skilled technician scarcity:Southeast Asian manufacturing hubs face rotating shortages of automation technicians, forcing OEMs to absorb training costs or redesign interfaces.
- Legacy OPC-UA retrofit costs:Mid-tier producers in heterogeneous factory estates delay IoT connectivity investments due to integration complexity and capital requirements.
- BIS certification barriers:India's Bureau of Indian Standards mandates for imported packaging machinery favor localized assembly partnerships, limiting direct market access for foreign OEMs.
Strategic Opportunities
- AI Integration layer:Predictive maintenance algorithms represent the fastest-expanding technology segment as manufacturers deploy machine learning to minimize unplanned downtime.
- Collaborative robot palletizing:Scarcity of forklift-certified labor pools in Thailand and Vietnam creates white space for cobot solutions that reduce dependency on scarce certified operators.
- PLI scheme alignment:India's production-linked incentive schemes for pharmaceuticals and food processing create capital subsidy channels for automation investments in underpenetrated secondary cities.
Industry Challenges
- Machine vision integration complexity:Ensuring seal integrity and weight accuracy across irregular package geometries requires specialized optical engineering talent that concentrates in Japanese and South Korean supplier ecosystems.
- Cloud-connected platform viability:Divergent national digital infrastructure readiness across China's industrial internet frameworks, Japan's METI-promoted JIS-compliant smart factories, and India's fragmented connectivity shapes uneven operational rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Packaging Automation Market |
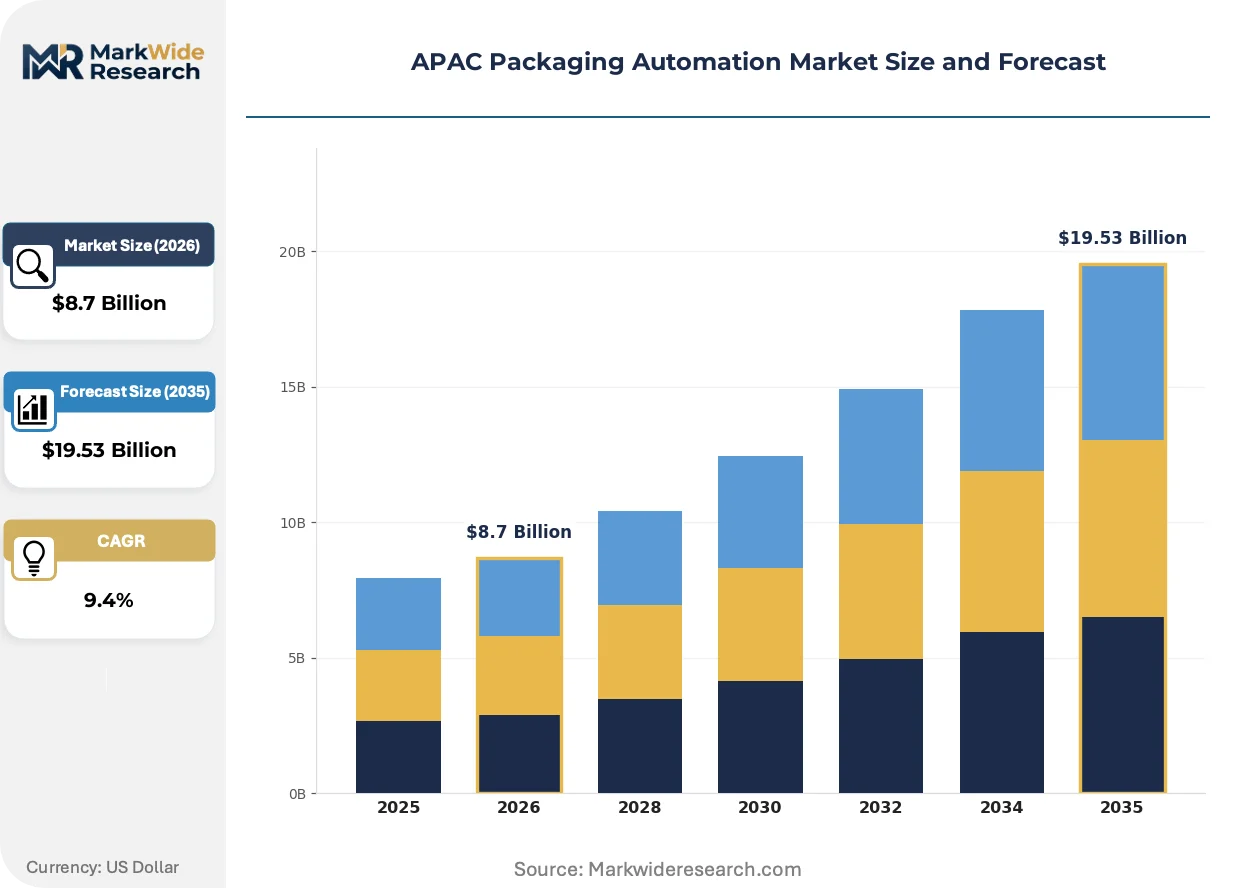
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Conveyor Systems, Palletizing Solutions, Labeling Machines Technology: AI Integration, Machine Vision, IoT-based Solutions, Control Systems End User: Food & Beverages, Pharmaceuticals, Consumer Goods, Electronics Application: Filling & Sealing, Wrapping, Sorting, Inspection |
| Companies Covered | Amcor PLC, Mitsubishi Electric Corporation, Fanuc Corporation, Rockwell Automation, Krones AG, ABB Ltd., Siemens AG, Swisslog Holding AG, Sidel Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Packaging Automation Market Strategic Shifts
Electromechanical architectures are actively displacing pneumatic systems across high-throughput packaging environments, while regulatory traceability mandates and AI-enabled predictive maintenance reshape competitive capability requirements.
Servo-driven motion control systems are supplanting legacy pneumatic actuation in precision packaging lines. Japanese and South Korean food and pharmaceutical manufacturers are adopting these architectures at accelerated replacement cycles. The technology is compressing positional repeatability tolerances to within 0.1 millimeter while enabling real-time energy consumption monitoring that satisfies tightening efficiency audits.
China's SAMR enforcement of GB standards for food contact material safety is reshaping machine material specifications and clean-in-place protocol requirements. Domestic and foreign OEMs must redesign wetted surfaces and validation documentation to satisfy these mandates. Food and beverage manufacturers in coastal provinces are responding by consolidating supplier qualifications around pre-certified equipment platforms.
After-sales service unbundling is fragmenting traditional maintenance contract structures. Thai and Vietnamese packaging operators are negotiating à la carte technical support agreements rather than comprehensive annual contracts. This behavioral shift is most visible among mid-tier producers managing mixed-vendor factory estates where standardization remains incomplete.
APAC Packaging Automation Market Segmentation
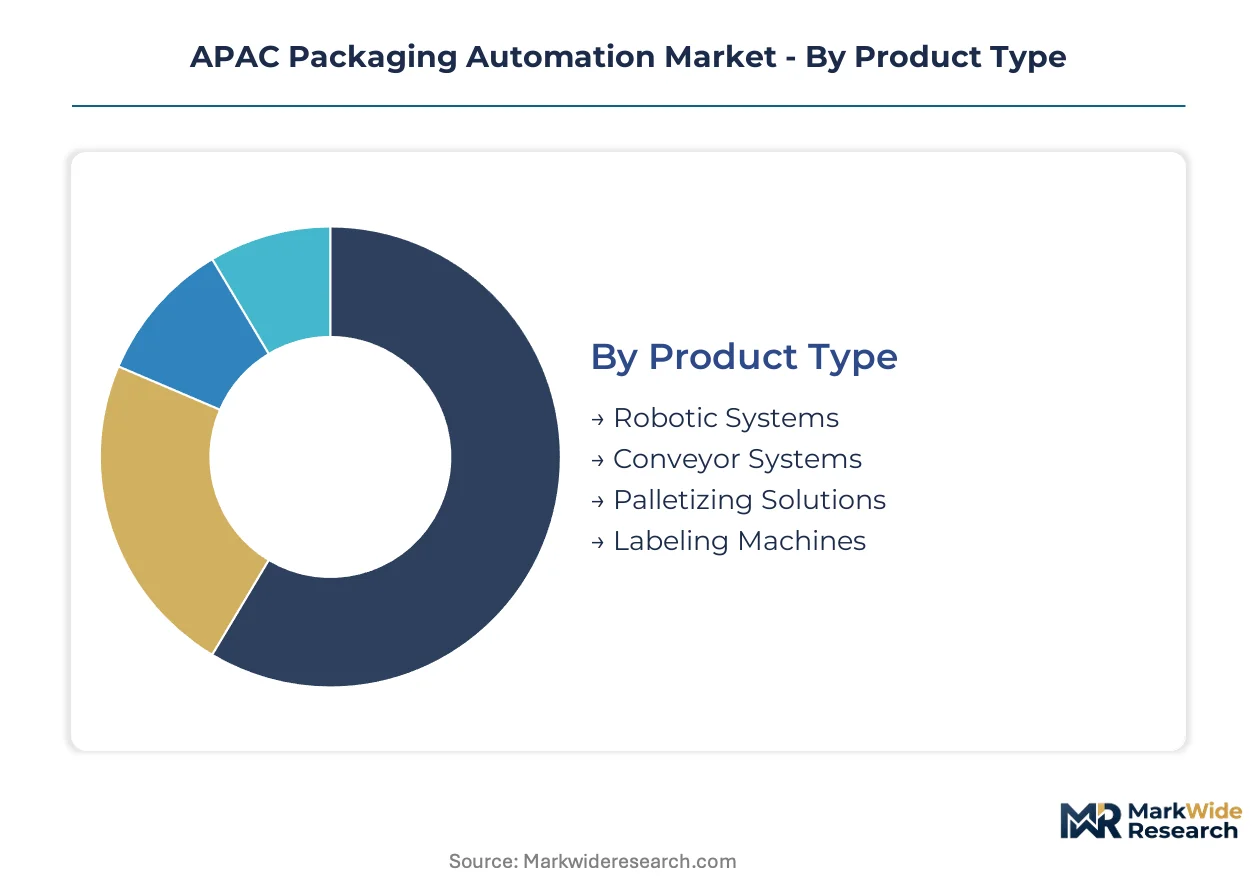
Segmentation in APAC packaging automation reveals how substitution pressures and regulatory mandates reshape investment priorities across product categories, technology layers, and end-use verticals. Manufacturers configure equipment portfolios around throughput requirements, traceability obligations, and energy-efficiency benchmarks that vary sharply by application environment.
Product Type:
Robotic Systems face intensifying substitution pressure from modular conveyor architectures in mid-tier food processing facilities seeking lower capital intensity.
- Robotic Systems:Multi-axis articulated arms and delta robots handle irregular package geometries with positional repeatability within 0.1 millimeter. Demand concentrates in Japanese and South Korean pharmaceutical corridors where serialization-ready flexibility commands premium positioning against rigid mechanical alternatives.
- Conveyor Systems:Belt and roller configurations transport materials at rates exceeding 600 units per minute. Chinese coastal food and beverage manufacturers deploy these as lower-cost substitutes for robotic handling where package uniformity permits standardized motion paths.
- Palletizing Solutions:Layer-forming and gantry systems address forklift-certified labor scarcity in Thailand and Vietnam through automated load consolidation.
- Labeling Machines:Pressure-sensitive and sleeve applicators integrate with track-and-trace databases for EU FMD and US DSCSA compliance in Indian pharmaceutical clusters.
Robotic Systems retain volume leadership; Palletizing Solutions holds the steepest expansion curve.
Technology:
Technology selection in APAC packaging automation tracks customer maturity tiers, with AI Integration commanding premium positioning against legacy control architectures in Tier-1 manufacturing estates.
- AI Integration:Predictive maintenance algorithms analyze servo motor vibration signatures and vision system defect patterns to minimize unplanned downtime. Deployment concentrates in Japanese METI-promoted smart factory frameworks where interconnected control architectures enable edge computing infrastructure.
- Machine Vision:Optical inspection systems verify seal integrity, weight accuracy, and label placement through high-speed image processing. Chinese SAMR enforcement of GB standards for food contact safety accelerates adoption in coastal province dairy and beverage facilities.
- IoT-based Solutions:Cloud-connected platforms face delayed rollout across India's fragmented digital infrastructure and heterogeneous legacy estates.
- Control Systems:Programmable logic controllers and servo drives anchor electromechanical architectures displacing pneumatic actuation under China's dual carbon mandates.
Control Systems anchor current installed base; AI Integration is climbing the fastest among new capital commitments.
End User:
End user segmentation reflects divergent regulatory exposure, with Pharmaceuticals facing the most acute substitution pressure from contract manufacturing reconfiguration.
- Food & Beverages:Automated filling and sealing lines address hygiene benchmarks and throughput targets exceeding 600 units per minute. Investment concentrates in Chinese coastal provinces where SAMR clean-in-place protocols and energy-efficiency audits compress equipment replacement cycles.
- Pharmaceuticals:Serialization-ready automation supports track-and-trace compliance for EU FMD and US DSCSA rules. Hyderabad and Ahmedabad CDMOs and generic exporters drive demand for vial filling, blister sealing, and aggregation systems.
- Consumer Goods:Flexible packaging lines accommodate SKU proliferation and seasonal volume swings in Southeast Asian manufacturing hubs.
- Electronics:Anti-static handling and precision placement systems serve semiconductor and component packaging requirements in South Korean and Taiwanese facilities.
Food & Beverages commands the largest capital deployment; Pharmaceuticals shows the most rapid technology refresh intensity.
Application:
Application segmentation tracks process criticality, with Filling & Sealing facing substitution pressure from integrated wrapping-sorting combinations in secondary packaging consolidation.
- Filling & Sealing:Aseptic and volumetric systems execute primary packaging with seal integrity validation. Indian pharmaceutical corridors and Chinese dairy processors prioritize these systems for regulatory compliance and contamination control.
- Wrapping:Stretch and shrink systems consolidate multi-unit packs for distribution efficiency. Southeast Asian consumer goods manufacturers deploy these to reduce material cost per unit shipped.
- Sorting:Weight and dimension-based diverters optimize downstream line balancing in high-throughput beverage facilities.
- Inspection:Machine vision and checkweigher integration verifies package completeness and label accuracy for export compliance.
Filling & Sealing maintains the deepest installed base; Inspection is gaining share fastest on traceability mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys packaging automation primarily for energy-efficiency compliance and carbon reduction, while India concentrates investment on pharmaceutical serialization for export markets. Japanese and South Korean manufacturers prioritize precision motion control for high-value electronics and pharmaceutical applications. Southeast Asian hubs emphasize labor substitution for palletizing and material handling operations.
China
Coastal food and beverage manufacturers drive servo-driven system adoption to satisfy SAMR-enforced GB standards for food contact safety and clean-in-place protocols. The country's dual carbon goals compress equipment replacement cycles as factories abandon pneumatic actuation for electromechanical architectures. Yangtze River Delta dairy processors consolidate supplier qualifications around pre-certified equipment platforms.
India
Pharmaceutical contract manufacturers in Hyderabad and Ahmedabad require serialization-ready automation for EU FMD and US DSCSA compliance. BIS certification mandates for imported machinery favor localized assembly partnerships over direct OEM market access. Production-linked incentive schemes for pharmaceuticals channel capital subsidies into underpenetrated secondary cities.
Japan
Precision pharmaceutical and electronics packaging lines anchor demand for high-speed motion control systems with positional repeatability within 0.1 millimeter. METI-promoted JIS-compliant smart factory frameworks accelerate domestic adoption of interconnected control architectures. Kanto and Kansai manufacturing belts concentrate investment in AI-enabled predictive maintenance deployments.
South Korea
Semiconductor and component packaging facilities demand anti-static handling and precision placement systems. Domestic pharmaceutical manufacturers adopt serialization architectures aligned with export market traceability requirements. Seoul Capital Area and Busan-Ulsan industrial corridors dominate capital deployment for high-throughput electromechanical lines.
Thailand and Vietnam
Forklift-certified labor scarcity pulls investment toward collaborative robot palletizing solutions that reduce dependency on scarce certified operators. Fanuc Corporation leverages its regional service network to sustain long-term maintenance contracts. Mid-tier producers negotiate à la carte technical support agreements rather than comprehensive annual contracts.
APAC Packaging Automation Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with Japanese and European conglomerates commanding premium positioning through bundled hardware-software-service offerings. The middle tier comprises regional system integrators and component specialists competing on customization velocity and local regulatory navigation. Two strategic archetypes dominate: full-stack automation platform providers and precision motion control specialists. Competitive moves concentrate on geographic service network expansion and predictive maintenance capability bundling.
Within the integrated automation tier, Mitsubishi Electric Corporation and ABB Ltd. exemplify contrasting geographic anchoring strategies. Mitsubishi Electric Corporation represents the precision motion control archetype dominant in Japanese and South Korean pharmaceutical corridors. ABB Ltd. occupies a position emphasizing collaborative robot palletizing solutions for Southeast Asian labor substitution scenarios. Siemens AG anchors the European-origin platform provider archetype competing on digital twin and cloud-connected architecture integration. Fanuc Corporation sits within the robotic systems specialist tier, leveraging regional service density to capture recurring maintenance revenue streams.
| Leading Market Players |
|---|
| Amcor PLC |
| Mitsubishi Electric Corporation |
| Fanuc Corporation |
| Rockwell Automation |
| Krones AG |
| ABB Ltd. |
| Siemens AG |
| Swisslog Holding AG |
| Sidel Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day servo motor lead times from Japanese suppliers concentrate pricing power among motion control specialists while forcing Chinese system integrators into strategic component stockpiles. This inventory pressure feeds directly into equipment pricing, as OEMs pass through semiconductor and rare-earth magnet cost volatility to food and pharmaceutical manufacturers facing compressed procurement windows.
Pricing Analysis
Long-term offtake agreements dominate capital equipment transactions, though mid-tier producers increasingly negotiate spot purchases for standardized conveyor modules. Three-tier pricing structure across premium, standard, and economy levels separates METI-compliant Japanese architectures from Chinese domestic brands and refurbished legacy systems. Pricing pressure stems from BIS certification compliance costs that foreign OEMs absorb to compete in Indian pharmaceutical corridors. Small-scale food processors in Vietnam exhibit highest price sensitivity, while Japanese electronics packaging facilities prioritize precision specifications over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate among Indian pharmaceutical CDMOs hedging against EU FMD compliance deadlines, while Chinese coastal manufacturers maintain just-in-time flows from Yangtze River Delta component clusters. Supply concentrates in Japan for high-precision servo drives, Germany for control systems, and China for structural frames and conveyor assemblies. Rare-earth magnet and industrial semiconductor dependencies create single-source vulnerability around Taiwanese foundry output. Distribution runs through authorized system integrator networks rather than direct OEM channels across Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indian pharmaceutical contract manufacturers consolidating automation procurement across Hyderabad and Ahmedabad clusters. This consolidation fragments pricing leverage for smaller food and beverage processors in secondary Chinese cities.
For Market Incumbents: Consolidate regional service networks to capture recurring maintenance revenue as Thai and Vietnamese operators abandon comprehensive annual contracts for à la carte technical support. Acquire localized assembly capabilities to satisfy India's BIS certification mandates without surrendering margin to domestic joint venture partners. Vertical integration into machine vision engineering talent pools in South Korea defends against Japanese precision motion control specialists.
For New Entrants and Emerging Players: Lead with collaborative robot palletizing solutions targeting forklift-certified labor scarcity in Thailand and Vietnam's mid-tier consumer goods facilities. White space concentrates in secondary Indian cities where PLI scheme subsidies channel capital toward underpenetrated pharmaceutical packaging corridors. Go-to-market leverage rests on predictive maintenance algorithm bundling rather than hardware-only positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI Integration technology layers as edge computing infrastructure commoditizes predictive maintenance deployments. Long-term viability favors platform providers with recurring software revenue streams over pure hardware manufacturers facing replacement cycle compression. Acquisition targets should demonstrate installed base density in Japanese METI-promoted smart factory frameworks. Signal to watch: cloud-connected platform adoption rates across India's fragmented digital infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Network Expansion | Captures recurring maintenance revenue as Thai and Vietnamese operators fragment contract structures. |
| Localized Assembly Partnership | Navigates India's BIS certification barriers while preserving margin against domestic joint venture requirements. |
| Predictive Maintenance Algorithm Development | Addresses AI Integration demand from Japanese METI-promoted smart factory frameworks. |
| Collaborative Robot Palletizing Launch | Targets forklift-certified labor scarcity in Thailand and Vietnam manufacturing hubs. |
| Serialization-Ready System Certification | Supports EU FMD and US DSCSA compliance for Hyderabad and Ahmedabad pharmaceutical exporters. |
Study Parameters
Desk research of customs trade databases, SAMR regulatory filings, and METI smart factory framework documentation preceded structured interviews with plant engineers at Chinese dairy processors, maintenance directors at Indian pharmaceutical CDMOs, and procurement leads at Thai consumer goods manufacturers. Primary fieldwork with Japanese precision equipment OEMs and South Korean machine vision specialists validated secondary data on servo motor adoption patterns. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure surveys across food, pharmaceutical, and electronics verticals.
Variance decomposition across product type, technology layer, end-use vertical, and application process shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include robotic system architecture, AI Integration maturity tier, pharmaceutical versus food and beverage end-use exposure, and primary versus secondary packaging application. CAGRs derived from equipment replacement cycle compression observed under China's dual carbon mandates and India's PLI scheme capital subsidy channels.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of EU FMD and US DSCSA traceability rules would require recalibration. Forecasts reflect assumptions regarding semiconductor supply normalization and rare-earth magnet price stability. Revision becomes warranted when BIS certification mandate stringency crosses thresholds that fundamentally alter foreign OEM market access economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Automatic Labeling Machine Market