
 Automatic Die Cutting Machines Market | 2026-2036
Automatic Die Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Die Cutting Machines Market Outlook
Direct OEM-to-converter sales channels is reconfiguring how automatic die cutting machines reach end users, with regional service hubs displacing traditional distributor networks in high-volume packaging corridors. Bobst leverages its Swiss engineering base to sustain premium positioning in flatbed systems for folding carton applications. Heidelberger Druckmaschinen AG anchors its competitive stance through integrated workflow software that connects prepress to finishing stages. Koenig & Bauer AG differentiates via specialization in security printing and tobacco packaging niches where registration tolerance demands exceed standard commercial grades.
Automatic die cutting machines employ hardened steel dies or rotary cylinders to cut, crease, emboss, or perforate sheet-fed substrates at speeds reaching thousands of impressions per hour with repeat accuracy below 0.1 mm. These systems serve primarily the packaging, label, and commercial printing industries where dimensional precision and throughput consistency determine line economics. Flatbed configurations occupy the mature volume tier in corrugated and folding carton plants where tooling flexibility outweighs absolute speed. Rotary systems represent the fastest-growing product category among beverage and consumer goods label converters seeking continuous-web throughput. Digital die cutting is displacing conventional mechanical methods in prototype development and short-run custom shapes where job changeover frequency renders fixed tooling uneconomical.
FDA regulations governing food-contact packaging materials shape substrate selection and die surface treatments in North American installations, while REACH compliance in Europe restricts certain lubricants and coatings used in electromechanical drive trains. CE marking under the Machinery Directive mandates specific guarding and emergency-stop architectures that influence control system design across export-oriented manufacturers. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple geographies will alter material recovery requirements for die-cut packaging waste streams.
Market Dynamics
Packaging converters in Southeast Asia are modernizing finishing lines to serve e-commerce fulfillment networks, while Europe's Ecodesign for Sustainable Products Regulation pressures OEMs to engineer lower-energy electromechanical systems. This dual pressure—volume expansion in emerging corridors and energy compliance in mature markets—defines the current competitive terrain.
Growth Catalysts
- E-commerce fulfillment networks:Corrugated board plants in Vietnam and Indonesia are upgrading to automatic die cutting machines to handle surge volumes from regional distribution centers.
- REACH lubricant restrictions:European electromechanical drive train redesigns are accelerating adoption of dry-running or sealed bearing systems that reduce maintenance intervals.
- Rotary cylinder technology:Beverage label converters are migrating from flatbed to continuous-web rotary systems for higher throughput on shrink-sleeve applications.
Market Restraints
- Hardened steel die supply concentration:Tooling fabrication capacity clusters in German and Japanese specialty metalworking centers, creating lead time vulnerability for non-integrated converters.
- CE marking Machinery Directive compliance costs:Guarding and emergency-stop architecture mandates add engineering overhead for export-oriented manufacturers targeting European installations.
- Digital die cutting substitution:Prototype development and short-run custom shapes are migrating to laser and knife-based systems where fixed tooling economics fail.
Strategic Opportunities
- Extended producer responsibility frameworks:Multiple geographies are introducing material recovery requirements for die-cut packaging waste streams, creating demand for recyclable substrate-compatible systems.
- Security printing specialization:Registration tolerance demands exceeding standard commercial grades in tobacco packaging and tax stamp applications favor precision-engineered flatbed configurations.
- Regional service hub networks:Direct OEM-to-converter sales channels are displacing traditional distributor networks in high-volume packaging corridors, enabling faster response and captive aftermarket revenue.
Industry Challenges
- Prepress-to-finishing workflow integration:Converters face complexity connecting legacy MIS systems to modern die cutting machine control architectures.
- Skilled maintenance technician scarcity:Electromechanical system diagnostics and rotary cylinder calibration expertise concentrates among aging workforces in mature manufacturing regions.
- Food-contact packaging certification timelines:FDA substrate selection and die surface treatment approvals extend commissioning schedules for North American dairy and ready-meal packaging lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Die Cutting Machines Market |
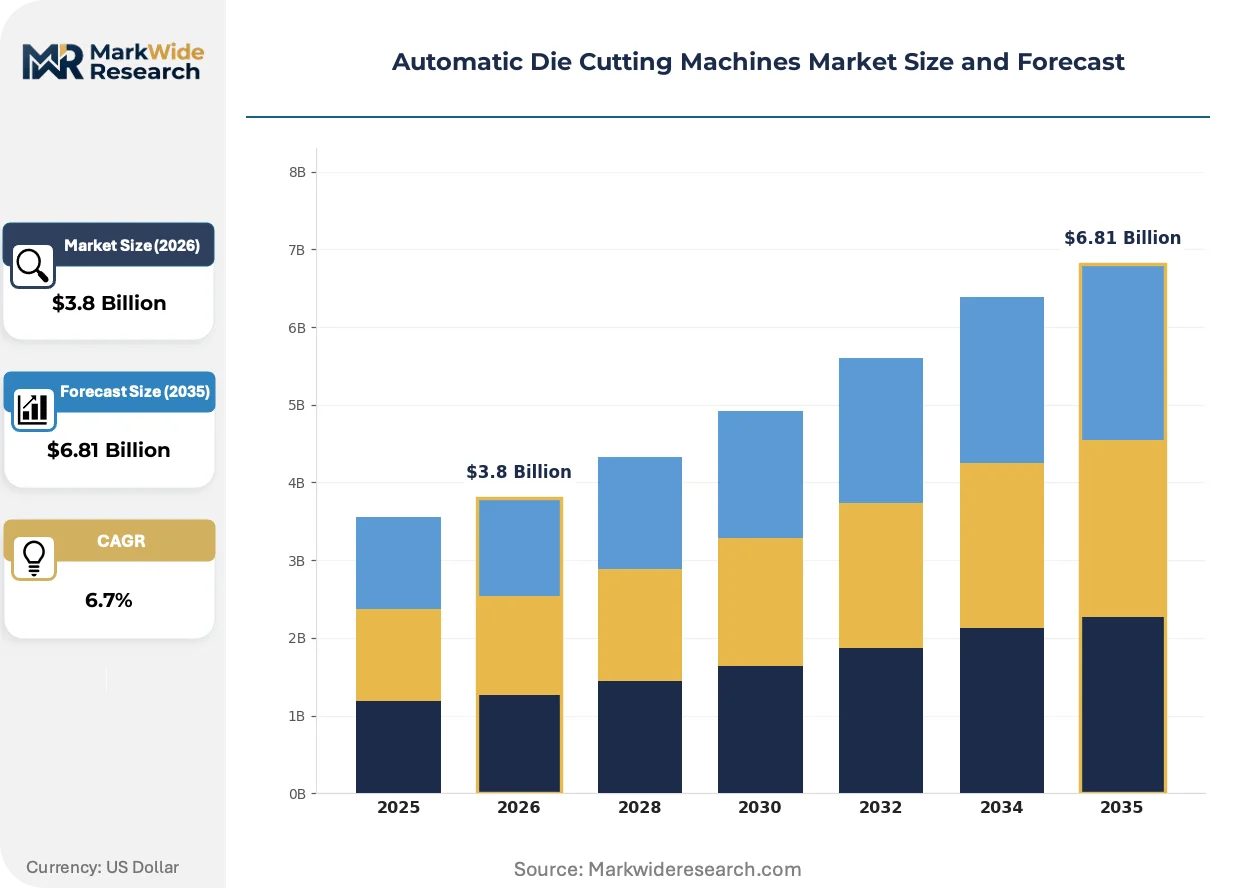
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Rotary, Laser, Digital End User: Packaging, Automotive, Aerospace, Textile Technology: Electromechanical, Hydraulic, Pneumatic, Hybrid Application: Prototype Development, Mass Production, Die Manufacturing, Custom Shapes |
| Companies Covered | Bobst, Heidelberger Druckmaschinen AG, Koenig & Bauer AG, Masterwork Machinery, Komori Corporation, Duplo International, SANWA Co., Ltd., ASAHI MACHINERY Limited, Zhejiang Feida Machinery Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Die Cutting Machines Market Strategic Shifts
Digital die cutting is collapsing the traditional boundary between prototype development and production-scale finishing, while regulatory pressure on energy consumption and material recovery is rewiring equipment specification criteria. These forces are compressing technology adoption cycles and reshaping vendor-converter relationships.
Digital die cutting systems employing laser and oscillating knife technologies are collapsing the economic viability of mechanical die preparation for job runs below five thousand impressions. Folding carton prototype shops and custom packaging startups in North America and Western Europe are adopting these systems at accelerating pace. The technology is collapsing lead times from design approval to physical sample from weeks to hours, forcing traditional die cutting OEMs to bundle digital modules or cede the short-run tier entirely.
Europe's Ecodesign for Sustainable Products Regulation is mandating measurable energy efficiency gains in industrial equipment placed on the EU market. Electromechanical drive systems must now demonstrate reduced power consumption under partial load conditions compared to legacy pneumatic or hydraulic alternatives. Flatbed die cutting installations in Germany, Italy, and the Netherlands are retrofitting servo-driven stripping and blanking units to maintain market access.
Outcome-based service contracts are replacing traditional break-fix maintenance arrangements in high-volume corrugated plants. OEMs are embedding predictive sensors in rotary die cutting cylinders and anvil covers, selling guaranteed uptime rather than spare parts. This shift is most visible in Southeast Asian board plants where line stoppage costs exceed technician labor arbitrage savings.
Automatic Die Cutting Machines Market Segmentation
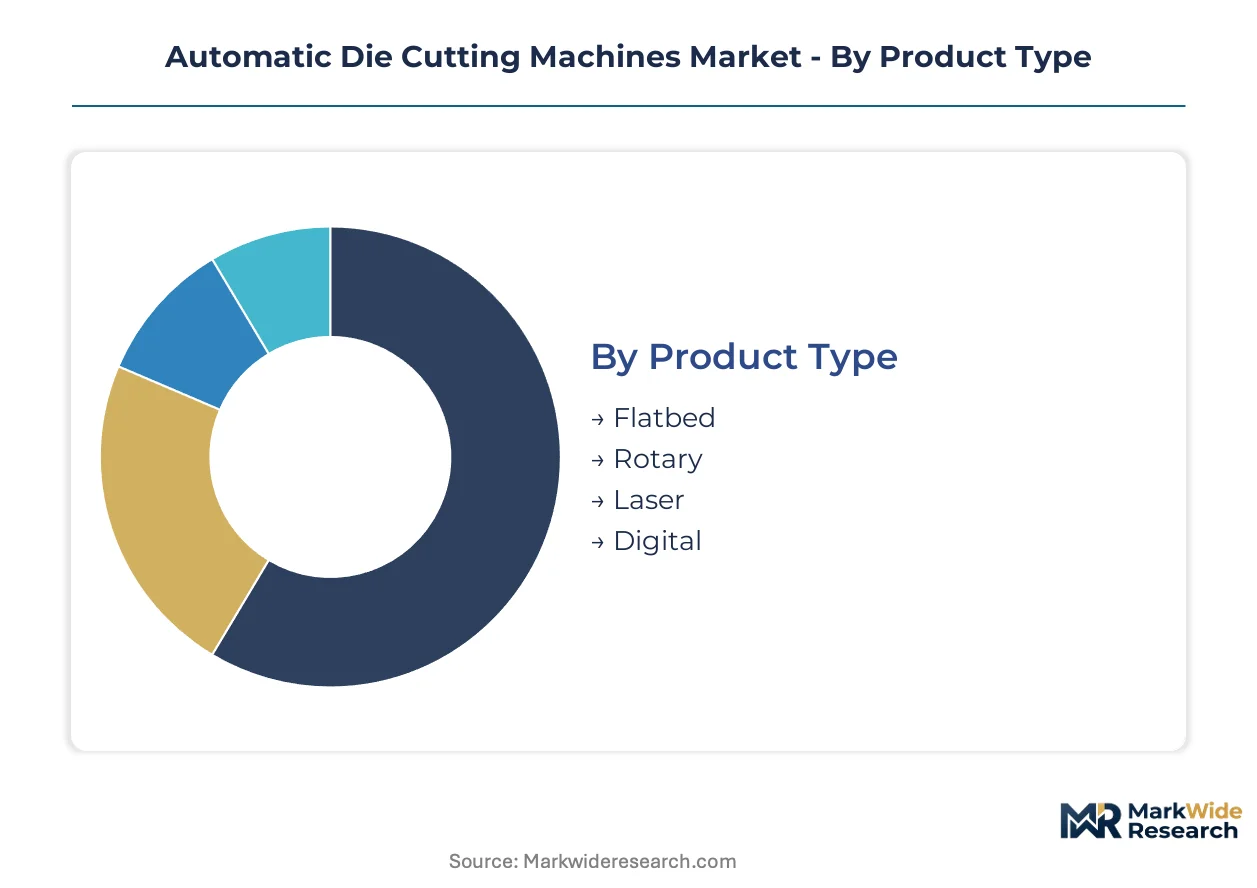
Segmentation in automatic die cutting machines reveals divergent equipment lifecycles and aftermarket revenue profiles. Flatbed systems demand intensive tooling refurbishment programs, while digital platforms shift margin capture toward software licensing and consumable substrates.
Product Type:
After-sales-service intensity varies dramatically across product architectures, with mechanical systems requiring scheduled die replacement and digital platforms leaning on remote diagnostics and software updates.
- Flatbed:Hardened steel dies mounted on reciprocating platens process sheet-fed corrugated and folding carton stock. Vietnamese and Indonesian board plants are modernizing finishing lines with these systems to serve e-commerce fulfillment networks surging through regional distribution centers.
- Rotary:Continuous-web cylinder configurations achieve higher throughput on beverage and consumer goods label applications. Beverage label converters are migrating toward these systems for shrink-sleeve production where web speed outweighs tooling flexibility.
- Laser:Non-contact beam cutting eliminates mechanical die fabrication for prototype and short-run operations. Custom packaging startups in North America are adopting these systems where job changeover frequency renders fixed tooling uneconomical.
- Digital:Integrated software-controlled knife and routing systems collapse design-to-sample lead times from weeks to hours. Folding carton prototype shops in Western Europe are deploying these platforms for sub-five-thousand-impression runs.
By volume, Flatbed leads. By growth pace, Digital is ahead.
End User:
Cost tier stratification separates capital-intensive packaging operations from precision-demanding aerospace and automotive applications with divergent procurement cycles and specification rigor.
- Packaging:Corrugated converters and folding carton plants represent the installed base core, with substrate handling systems optimized for board grammages from lightweight folding carton to heavy-duty triple-wall. Southeast Asian plants are expanding capacity to serve regional e-commerce fulfillment networks.
- Automotive:Gasket, interior trim, and insulation material cutting requires registration tolerances and nesting algorithms that maximize material yield. Tier suppliers are integrating these systems into just-in-sequence production lines feeding final assembly plants.
- Aerospace:Composite prepreg and insulation blanket cutting demands contamination-controlled environments and traceable tooling certification. The sector's low-volume, high-mix profile favors programmable digital systems over fixed mechanical dies.
- Textile:Apparel pattern and technical fabric cutting employs high-ply stack configurations with oscillating knife or ultrasonic technologies. Fast fashion cycles are compressing equipment payback period expectations in this segment.
By installed base, Packaging dominates. By specification intensity, Aerospace commands premium positioning.
Technology:
Application environment determines drive system selection, with food-contact packaging installations facing distinct lubricant and surface treatment constraints compared to industrial material processing.
- Electromechanical:Servo-driven systems with sealed bearings and dry-running components address REACH lubricant restrictions in European installations. Ecodesign for Sustainable Products Regulation mandates are accelerating adoption of these reduced-maintenance configurations.
- Hydraulic:High-tonnage systems for dense substrate stacks and thick corrugated board maintain presence in heavy-duty applications. Energy efficiency benchmarking under EU regulations is pressuring OEMs to engineer lower-power alternatives.
- Pneumatic:Compressed air actuation persists in legacy installations and explosive atmosphere environments where electrical spark risk must be eliminated. Operating cost disadvantages are eroding market share outside these niche applications.
- Hybrid:Combined electromechanical precision with pneumatic clamping or hydraulic tonnage for specialized material handling. These configurations are gaining traction in automotive interior trim operations requiring both speed and force modulation.
By new order volume, Electromechanical leads. By regulatory compliance trajectory, Hybrid systems are climbing fastest.
Application:
Customer type and production scale separate prototype service bureaus from mass production operations, with equipment specification, financing structure, and vendor relationship intensity diverging accordingly.
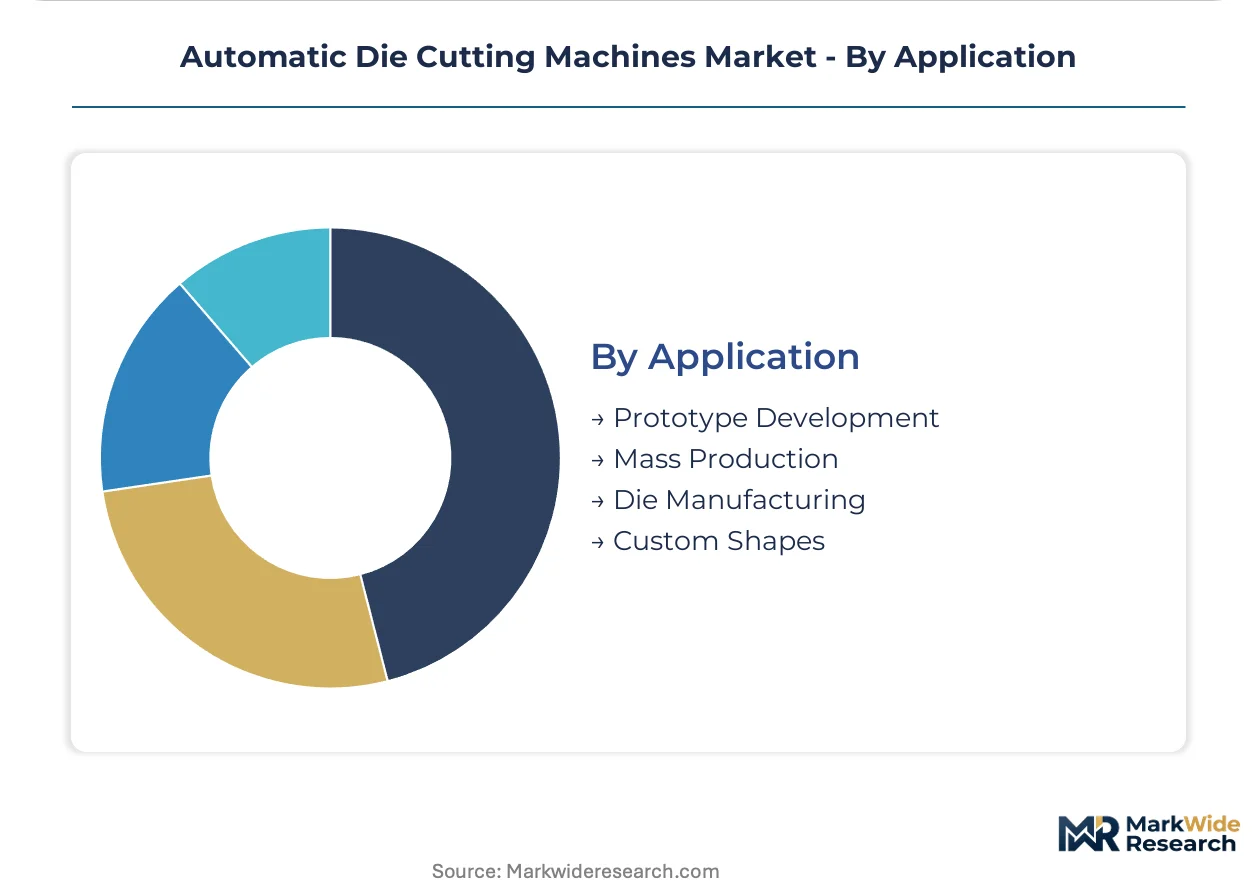
- Prototype Development:Digital die cutting platforms with rapid file-to-fabrication workflows serve packaging design agencies and brand owner innovation labs. Lead time compression from weeks to hours is collapsing traditional sample production economics.
- Mass Production:High-speed rotary and flatbed systems with automated feeding and stacking achieve thousands of impressions per hour with repeat accuracy below 0.1 mm. Corrugated board plants in Vietnam and Indonesia are upgrading these lines for e-commerce volume surges.
- Die Manufacturing:Tooling production equipment for hardened steel rule dies and rotary cylinders serves integrated converters and specialized die shops. Fabrication capacity concentrates in German and Japanese specialty metalworking centers.
- Custom Shapes:Short-run decorative and promotional packaging applications favor laser and digital knife systems where geometric complexity and order frequency defeat mechanical die economics. North American custom packaging startups are concentrating demand here.
By revenue concentration, Mass Production leads. By expansion trajectory, Custom Shapes is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss engineering centers where precision flatbed systems command premiums, while Vietnamese and Indonesian converters absorb cost pressures from capacity expansion cycles serving e-commerce fulfillment networks.
Germany
REACH lubricant restrictions and Ecodesign for Sustainable Products Regulation mandates are accelerating electromechanical drive train redesigns. CE marking Machinery Directive compliance costs add engineering overhead for export-oriented manufacturers. The Stuttgart-Karlsruhe corridor hosts specialty metalworking centers where hardened steel die fabrication capacity clusters.
Vietnam
Corrugated board plants are modernizing finishing lines to handle surge volumes from regional e-commerce distribution centers. The national industrial policy favors packaging sector automation upgrades through investment incentives. Ho Chi Minh City and Binh Duong Province concentrate new automatic die cutting machine installations serving fulfillment networks.
United States
FDA regulations governing food-contact packaging materials shape substrate selection and die surface treatments in dairy and ready-meal packaging lines. Extended producer responsibility frameworks in California and New York are altering material recovery requirements for die-cut packaging waste streams. The Midwest corrugated belt spanning Wisconsin, Illinois, and Ohio anchors domestic board production capacity.
Indonesia
Packaging converters are expanding capacity to serve e-commerce fulfillment networks penetrating the archipelago's consumer markets. Import tariff structures on finishing equipment influence OEM direct sales channel strategies. The Jakarta-Bekasi industrial corridor hosts the densest concentration of modernizing board plants.
Japan
METI energy efficiency benchmarks pressure electromechanical system redesigns in legacy installations. JIS standards certification requirements influence control system architecture for domestic and export equipment. The Nagoya-Osaka manufacturing belt maintains specialty metalworking capacity for rotary cylinder fabrication.
Automatic Die Cutting Machines Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in tooling and drive train subsystems. The vendor base organizes around three strategic archetypes: Swiss and German engineering houses with premium flatbed positioning, Japanese precision specialists in rotary cylinder technology, and Chinese scale manufacturers serving emerging market volume tiers. Consolidation pressure operates through direct OEM-to-converter sales channel expansion and regional service hub establishment displacing traditional distributor networks.
Among Swiss and German engineering houses, Bobst and Heidelberger Druckmaschinen AG occupy positions representing platform integration archetypes. Koenig & Bauer AG exemplifies specialization-driven positioning within precision-demanding application niches. These entities anchor the premium tier where registration tolerance specifications and workflow software integration determine competitive standing.
| Leading Market Players |
|---|
| Bobst |
| Heidelberger Druckmaschinen AG |
| Koenig & Bauer AG |
| Masterwork Machinery |
| Komori Corporation |
| Duplo International |
| SANWA Co., Ltd. |
| ASAHI MACHINERY Limited |
| Zhejiang Feida Machinery Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
The Stuttgart-Karlsruhe corridor anchors hardened steel die fabrication capacity, concentrating tooling supply among German and Japanese specialty metalworking centers. This geographic clustering grants incumbent OEMs pricing leverage over non-integrated converters facing lead time vulnerability, while Southeast Asian board plants absorb cost pressures from capacity expansion cycles serving e-commerce fulfillment networks.
Pricing Analysis
Configured-to-order flatbed systems command substantial premiums over standard rotary configurations, with three-tier pricing structure across premium, standard, and economy levels separating Swiss-engineered precision platforms from Chinese scale manufacturers. Price differentiation hinges on registration tolerance certification and after-sales service bundling. Cost compression in the economy tier intensifies as Vietnamese and Indonesian converters prioritize throughput volume over absolute precision. Packaging converters in emerging corridors exhibit highest price sensitivity, while aerospace and security printing applications demonstrate lowest.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms have become competitive weapons for OEMs targeting capital-constrained Southeast Asian board plants. Component sourcing draws from Germany, Japan, and China for hardened steel dies, servo drive systems, and control electronics. Single-source vulnerability concentrates in rotary cylinder fabrication where Nagoya-Osaka specialty metalworking capacity dominates. Distribution runs through direct OEM-to-converter channels displacing traditional distributor networks in high-volume packaging corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as digital die cutting platforms displace mechanical methods in prototype and short-run tiers. E-commerce fulfillment network expansion across Southeast Asia fragments demand across multiple converter archetypes with divergent specification requirements.
For Market Incumbents: Pre-empt digital substitution threats by bundling laser or knife-based modules with traditional flatbed platforms, or cede the sub-five-thousand-impression tier entirely. Pursue backward integration into hardened steel die fabrication to secure tooling supply against German and Japanese capacity bottlenecks. Establish regional service hubs in Ho Chi Minh City and Jakarta-Bekasi to capture captive aftermarket revenue from Southeast Asian board plant modernization cycles. For New Entrants and Emerging Players: Establish a beachhead in digital die cutting platforms serving North American and Western European prototype shops where job changeover frequency renders fixed tooling uneconomical. Target custom packaging startups and folding carton design agencies with software-controlled knife systems that collapse design-to-sample lead times. Lead with rapid file-to-fabrication workflows and subscription-based software licensing rather than capital equipment sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineered flatbed specialists with security printing and tobacco packaging niche exposure where registration tolerance demands exceed standard commercial grades. Long-term viability over the projection horizon rests on workflow software integration capabilities connecting prepress to finishing stages. Watch for inflection signals in extended producer responsibility framework implementation across multiple geographies altering material recovery requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Hub Establishment | Direct OEM-to-converter channels in Vietnam and Indonesia displace distributor networks and capture aftermarket revenue. |
| Digital Module Integration | Laser and knife-based platform bundling defends against substitution in prototype and short-run custom shape tiers. |
| Electromechanical Drive Redesign | Sealed bearing and dry-running configurations address REACH lubricant restrictions and Ecodesign energy mandates. |
| Workflow Software Development | Prepress-to-finishing integration connects legacy MIS systems to modern die cutting control architectures. |
| Predictive Sensor Embedding | Outcome-based service contracts with guaranteed uptime replace break-fix maintenance in Southeast Asian board plants. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at corrugated board facilities, OEM procurement teams, aftermarket service heads, and packaging converter operations directors, then refined through secondary validation. Sources included customs and trade data for die cutting equipment imports, SEC filings from publicly listed machinery manufacturers, industry association reports from packaging federations, and equipment registration databases. Bottom-up unit economics from converter installations were triangulated against top-down market sizing from OEM shipment disclosures.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled by product architecture, end-use industry, drive technology type, and application scale. CAGRs were derived from installed base turnover rates and new order intake patterns. Forecast inputs incorporated e-commerce fulfillment network expansion trajectories, regulatory compliance cost pass-through assumptions, and digital substitution elasticities in prototype development tiers.
Sensitivities concentrate around extended producer responsibility framework implementation timelines, REACH lubricant restriction enforcement stringency, and digital die cutting technology cost curves. Forecasts reflect documented assumptions about Southeast Asian capacity expansion cycles and European energy efficiency mandate compliance pathways. Macroeconomic contraction in consumer goods demand, regulatory deviation in food-contact packaging certification, or breakthrough advances in laser cutting throughput would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Europe Packaging Automation Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Automated Tray Fill and Seal Machines Market