
 Packaging Automation Solutions Market | 2026-2036
Packaging Automation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Automation Solutions Market Analysis
The EU Green Deal and its packaging waste reduction targets is realigning capital allocation across European food and beverage operations. Tetra Pak International S.A. leverages its aseptic carton expertise to anchor sustainable filling lines for dairy and plant-based producers. Krones AG competes through integrated bottle-to-pallet systems that dominate brewery and soft-drink installations worldwide. Syntegon Technology GmbH specializes in pharmaceutical containment and serialization, controlling high-margin cleanroom packaging segments.
Packaging Automation Solutions encompass electromechanical systems that execute filling, sealing, labeling, palletizing, and material handling functions at speeds exceeding 600 units per minute with positional accuracy within 0.1 millimeters. These systems integrate servo motors, programmable logic controllers, and human-machine interfaces to reduce labor dependency while ensuring lot traceability and seal integrity for regulated products. Robotic Arm deployments lead capital expenditure in flexible manufacturing environments where changeover times must compress below fifteen minutes. Filling Machines capture concentrated margin pools in aseptic and high-viscosity applications where contamination control determines compliance. AI Integration represents the fastest-expanding technology dimension as vision-guided defect rejection and predictive maintenance protocols displace manual quality stations.
The FDA enforces Current Good Manufacturing Practice requirements that mandate automated serialization and tamper-evidence verification for pharmaceutical packaging lines. EMA's Medical Device Regulation and REACH chemical compliance frameworks compel European OEMs to certify materials compatibility and eliminate restricted substances from machine surfaces and lubricants. OSHA lockout-tagout standards and EPA emissions guidelines in the United States shape equipment guarding designs and pneumatic system specifications. Stakeholders must weigh retrofit compatibility against greenfield automation investments as regulatory divergence between jurisdictions intensifies engineering complexity.
Market Dynamics
Food processing facilities are compressing changeover windows below fifteen minutes while EU F-Gas Regulation mandates refrigerant system retrofits, forcing simultaneous throughput and sustainability investments across installed base decisions.
Growth Catalysts
- EU Green Deal packaging waste targets:Dairy and beverage producers are accelerating capital allocation toward carton and bottle lines that demonstrate measurable carbon footprint reductions.
- Pharmaceutical serialization mandates:EMA Medical Device Regulation and FDA track-and-trace requirements are compelling cleanroom packaging line upgrades with integrated tamper-evidence verification.
- Robotic arm deployments:Flexible manufacturing environments in Germany and Switzerland are standardizing six-axis cobot integrations to achieve sub-ten-minute format changes.
Market Restraints
- Servo motor supply concentration:Precision motion control component sourcing clusters in Japanese and German supplier networks, exposing lead time vulnerabilities.
- Specialized technician scarcity:Commissioning engineers proficient in PLC-HMI integration and FDA validation protocols command premium wages that inflate total cost of ownership.
- REACH chemical compliance friction:ECHA substance restrictions on machine lubricants and surface coatings force reformulation cycles that delay equipment certification timelines.
Strategic Opportunities
- India PLI scheme for food processing:Central government production-linked incentives are attracting greenfield automation investments in dairy and edible oil packaging corridors.
- AI-vision convergence with predictive maintenance:Machine learning defect rejection algorithms bundled with vibration monitoring are creating premium service revenue streams.
- Pharmaceutical cold chain expansion:Biologics distribution networks in the United States and Germany are demanding aseptic filling lines with integrated temperature-controlled secondary packaging.
Industry Challenges
- Legacy SCADA integration complexity:Brownfield pharmaceutical facilities face protocol translation barriers when connecting new servo-driven equipment to decades-old control architectures.
- ISO 22000 certification timeline compression:Food safety management system audits are extending from eight to fourteen months as auditor availability constrains validation throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Automation Solutions Market |
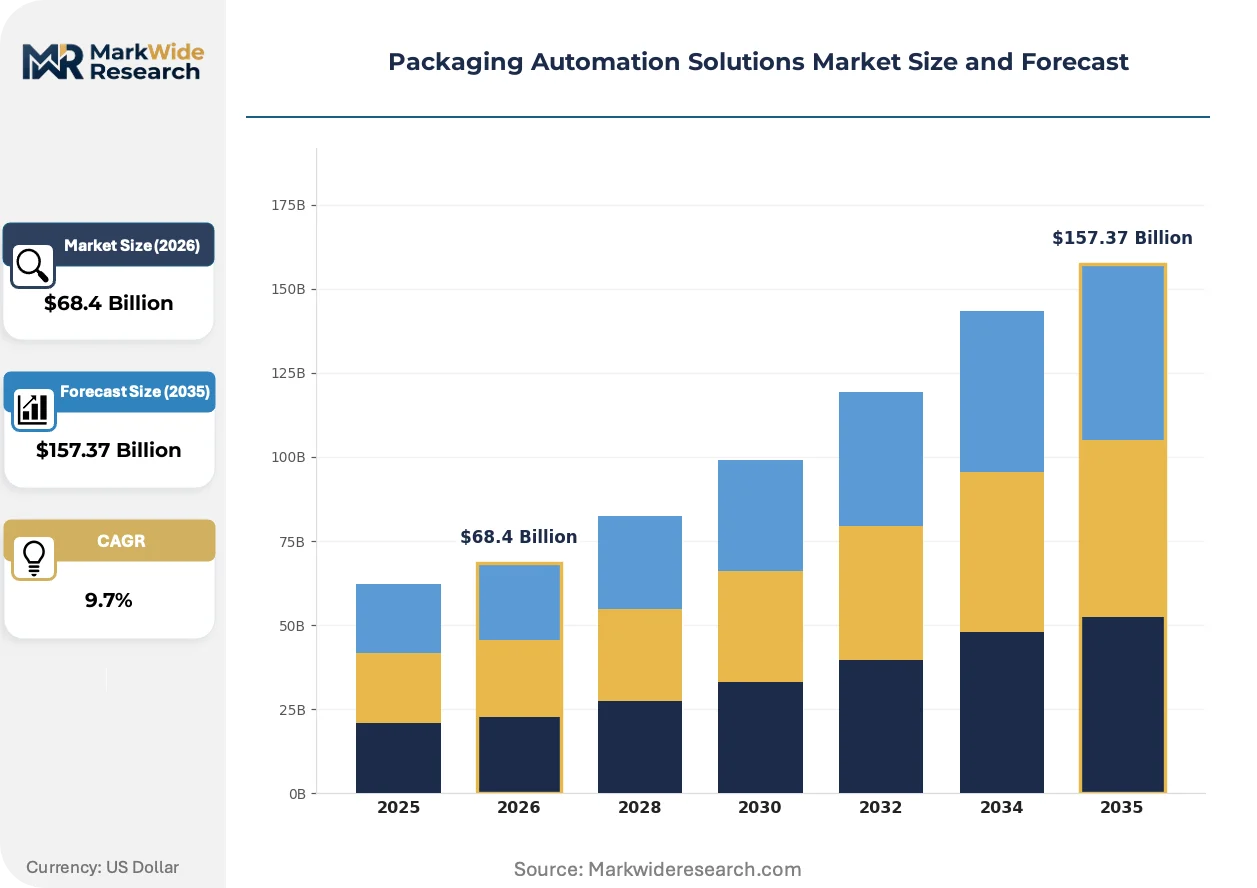
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arm, Conveyor Systems, Filling Machines, Labelling Equipment End User: Food Processing, Pharmaceuticals, Consumer Goods, Electronics Technology: AI Integration, IoT Connectivity, Vision Systems, Vacuum Packaging Application: Primary Packaging, Secondary Packaging, Tertiary Packaging, Shrink Wrapping |
| Companies Covered | Coesia S.p.A., KHS GmbH, Tetra Pak International S.A., IMA S.p.A., Syntegon Technology GmbH, Krones AG, ProMach, Inc., MULTIVAC Sepp Haggenmüller SE & Co. KG, Barry-Wehmiller Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Automation Solutions Market Emerging Trajectories
Electromechanical system architectures are displacing pneumatic actuation across high-speed filling and sealing applications, compressing energy consumption profiles while tightening positional tolerances for regulated products.
Direct-drive servo technology is electrifying motion control in rotary filling machines and robotic palletizing cells, replacing compressed air infrastructure with permanent magnet motors and precision gearboxes. Pharmaceutical and dairy producers in Germany and Switzerland are specifying all-electric lines for cleanroom environments where oil-free operation eliminates contamination vectors. This electrification is compressing maintenance intervals and enabling real-time torque monitoring for predictive bearing replacement protocols.
EU F-Gas Regulation phase-down schedules are mandating refrigerant transitions in aseptic carton filling systems that rely on chilled hydrogen peroxide sterilization. Equipment OEMs must recertify thermal systems using low-global-warming-potential alternatives before 2027 deployment deadlines. Dairy packaging corridors in Bavaria and the Netherlands are prioritizing retrofit-compatible filling machines that accommodate refrigerant technology swaps without structural frame modifications.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale food processors seeking to preserve balance sheet flexibility. Subscription structures bundle hardware, software updates, and predictive maintenance into per-unit throughput charges. This financing rotation is most visible in the United States, where private equity-backed co-manufacturers prioritize operational expenditure treatment for automation assets serving volatile CPG brand contracts.
Packaging Automation Solutions Market Segmentation
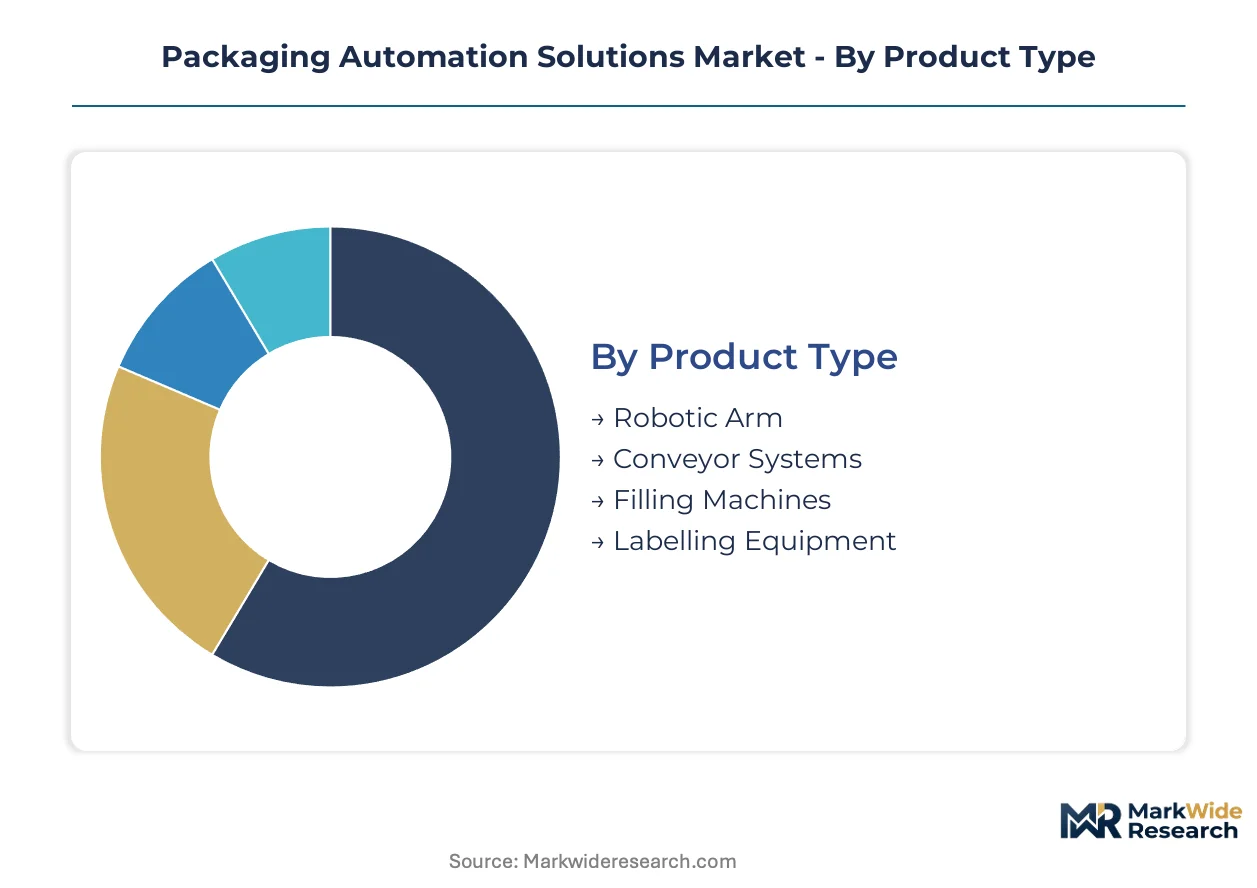
Packaging automation solutions fragment across equipment types, end-use requirements, and control architectures that determine capital allocation priorities. Equipment buyers evaluate changeover flexibility, regulatory compliance pathways, and integration complexity when selecting between standardized platforms and engineered-to-order configurations.
Product Type:
Customization intensity spans from modular conveyor assemblies to application-specific robotic cells requiring kinematic reprogramming for each deployment.
- Robotic Arm:Six-axis articulated systems execute pick-and-place, palletizing, and case-packing functions with repeatability within 0.05 millimeters. German automotive suppliers and Bavarian dairy cooperatives are standardizing cobot deployments to compress format changeover below ten minutes. Growing fastest: Robotic Arm.
- Filling Machines:Rotary and linear architectures handle liquid, powder, and viscous product streams with aseptic or clean-fill isolation. Pharmaceutical producers in Switzerland and the Netherlands prioritize servo-driven volumetric fillers with integrated CIP/SIP protocols for biologics containment. Leading the category by volume: Filling Machines.
- Conveyor Systems:Belt, roller, and chain configurations transport unit loads through accumulation, merging, and sorting zones at speeds exceeding 150 meters per minute.
- Labelling Equipment:Pressure-sensitive, sleeve, and direct-print applicators integrate vision verification for serialization compliance in FDA-regulated pharmaceutical corridors.
Leading the category by volume: Filling Machines. Growing fastest: Robotic Arm.
End User:
Regulatory stringency and lot traceability requirements create divergent specification profiles across customer verticals.
- Food Processing:Dairy, meat, and bakery operations deploy washdown-rated stainless steel equipment with IP69K sealing for high-pressure sanitation cycles. EU Green Deal packaging waste targets are redirecting capital toward carton and flexible film lines with demonstrable carbon footprint reductions in Dutch and Danish processing clusters.
- Pharmaceuticals:Aseptic filling, lyophilization handling, and serialization systems operate within ISO 5-8 cleanroom classifications with 21 CFR Part 11 electronic record compliance. EMA Medical Device Regulation and FDA track-and-trace mandates are compelling line upgrades with integrated tamper-evidence verification in German and Swiss manufacturing sites.
- Consumer Goods:Personal care and household chemical packagers prioritize rapid format changeover for seasonal SKU proliferation.
- Electronics:ESD-safe handling and moisture-barrier packaging protect semiconductor and component shipments through automated tray loading and vacuum sealing.
Pharmaceuticals commands premium pricing per installed line. Food Processing delivers largest aggregate unit volume.
Technology:
Control layer sophistication determines maintenance protocols, operator training requirements, and cybersecurity exposure profiles.
- AI Integration:Machine learning algorithms process vision system outputs for real-time defect classification and predictive bearing failure detection. United States co-manufacturers are bundling AI-vision modules with vibration monitoring to create subscription-based service revenue streams.
- Vision Systems:High-speed cameras with LED strobing capture dimensional accuracy, label placement, and seal integrity at throughput rates exceeding 600 units per minute.
- IoT Connectivity:Edge computing gateways stream OEE metrics, energy consumption, and alarm states to centralized MES platforms for remote diagnostics.
- Vacuum Packaging:Chamber and thermoforming systems evacuate atmosphere to extend shelf life for protein and cheese applications in refrigerated supply chains.
AI Integration is climbing the fastest as vision-guided quality stations displace manual inspection labor.
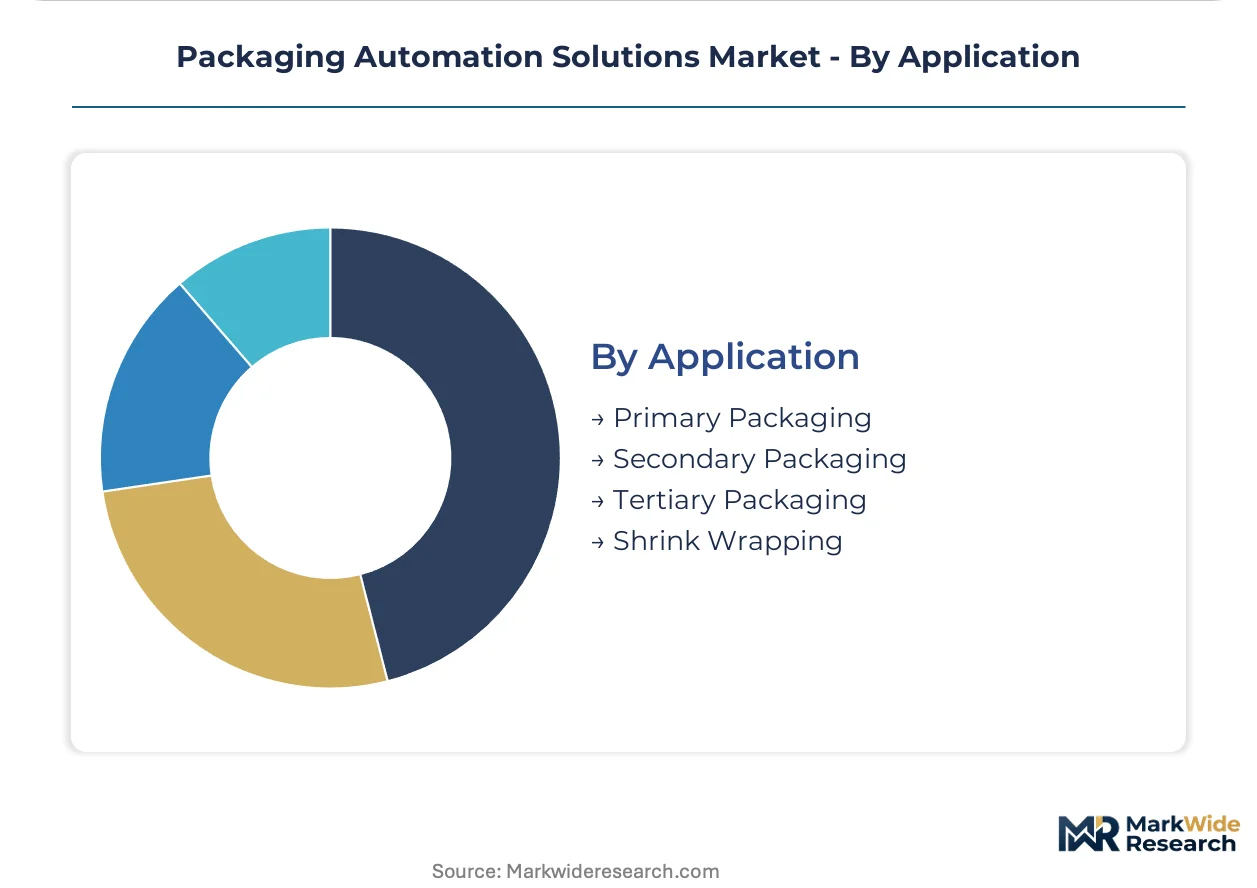
Application:
Packaging hierarchy levels dictate equipment scale, speed, and integration depth with upstream production and downstream distribution.
- Primary Packaging:Direct product contact operations including forming, filling, and sealing of bottles, cartons, pouches, and blister packs. Aseptic carton filling for dairy and plant-based beverages in Germany and the Netherlands is prioritizing refrigerant retrofit compatibility under EU F-Gas Regulation phase-down schedules.
- Secondary Packaging:Case erecting, partition inserting, and multipack collation aggregate individual units into shelf-ready or shipping configurations.
- Tertiary Packaging:Palletizing, stretch wrapping, and unitizing prepare consolidated loads for warehouse storage and over-the-road transport.
- Shrink Wrapping:Polyolefin film application with heat tunnel contraction bundles irregular shapes for retail display and moisture protection.
Primary Packaging captures the steepest margin pools where contamination control determines regulatory compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's machinery manufacturing belt anchors European capital deployment for packaging automation, with automotive-style precision engineering standards migrating into food and pharmaceutical line specifications.
Germany
Dairy cooperatives in Bavaria and pharmaceutical manufacturers in Baden-Württemberg are retrofitting aseptic filling lines for EU F-Gas Regulation refrigerant compliance. The EMA Medical Device Regulation drives cleanroom packaging upgrades in Swiss-border manufacturing zones. Stuttgart's automation engineering clusters supply servo-driven motion control systems to pharmaceutical OEMs.
United States
Co-manufacturers serving volatile CPG brand contracts are adopting equipment-as-a-service financing models to preserve balance sheet flexibility. FDA serialization mandates for pharmaceutical track-and-trace compel line upgrades in New Jersey and Puerto Rico manufacturing corridors. Chicago's food processing automation vendors integrate AI-vision modules for defect rejection at throughput rates exceeding 600 units per minute.
Switzerland
Biologics containment and aseptic filling specifications from Basel pharmaceutical headquarters propagate downstream to machinery procurement standards. Swissmedic certification requirements for cleanroom equipment surface materials shape vendor qualification protocols. Zurich automation engineering firms specialize in pharmaceutical serialization and tamper-evidence verification systems.
India
Central government PLI scheme incentives are attracting greenfield automation investments in Maharashtra and Gujarat dairy packaging corridors. FSSAI food safety regulations mandate lot traceability systems for edible oil and processed food lines. Bangalore's industrial automation integrators deploy robotic palletizing cells for export-oriented food processing parks.
Netherlands
Dairy and plant-based beverage producers in Friesland and Noord-Brabant prioritize carton filling lines with demonstrable carbon footprint reductions under EU Green Deal targets. REACH chemical compliance frameworks restrict machine lubricant formulations used in food contact zones. Eindhoven's high-tech systems engineering clusters develop vision-guided quality stations for pharmaceutical secondary packaging.
Packaging Automation Solutions Market Vendor Landscape
The competitive structure tilts toward diversified machinery conglomerates with integrated bottle-to-pallet capabilities. Tiered specialization separates aseptic carton specialists from pharmaceutical containment engineers and flexible packaging generalists. Strategic archetypes include European precision-engineering OEMs, North American packaging line integrators, and Asian cost-optimized fabricators. Dominant competitive moves encompass refrigerant system retrofit certifications under EU F-Gas Regulation and predictive maintenance service bundling through AI-vision convergence.
Among diversified European machinery groups, Krones AG and Tetra Pak International S.A. exemplify integrated system architectures spanning filling through tertiary packaging. Syntegon Technology GmbH occupies a specialist position in pharmaceutical containment and cleanroom serialization. These entities represent distinct strategic postures: end-to-end line integration versus high-margin regulated segment focus.
| Leading Market Players |
|---|
| Coesia S.p.A. |
| KHS GmbH |
| Tetra Pak International S.A. |
| IMA S.p.A. |
| Syntegon Technology GmbH |
| Krones AG |
| ProMach, Inc. |
| MULTIVAC Sepp Haggenmüller SE & Co. KG |
| Barry-Wehmiller Inc. |
| Others |
Supply Flow & Price Mechanics
Mid-scale food processors adopting equipment-as-a-service financing concentrate procurement leverage among co-manufacturers seeking operational expenditure treatment, compressing capital purchase premiums and elevating subscription-based throughput pricing across volatile CPG contract portfolios.
Pricing Analysis
Per-unit throughput charges anchored to line uptime and defect rejection rates dominate equipment-as-a-service contracting, displacing upfront capital outlays. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cleanroom certifications from washdown-rated food processing configurations. Pricing pressure stems from REACH chemical compliance reformulation cycles that delay equipment certification timelines. Food processing cooperatives exhibit highest price sensitivity due to seasonal volume volatility, while pharmaceutical serialization mandates insulate cleanroom line premiums.
Supply Chain Analysis
Freight costs for precision servo motors and permanent magnet drives concentrate exposure in Japanese and German supplier networks, extending lead time vulnerabilities across rotary filling machine deployments. Component sourcing draws from Germany, Japan, and Switzerland for motion control systems, with stainless steel framing and hydrogen peroxide sterilization modules feeding from EU fabricators. Single-source vulnerability in precision gearbox manufacturing threatens commissioning schedules for Bavarian dairy retrofits. Distribution runs through OEM-direct channels for pharmaceutical lines and systems integrators for mid-scale food processing installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU F-Gas Regulation retrofit deadlines force smaller fabricators lacking refrigerant recertification capabilities toward distressed exits or strategic absorption by integrated line suppliers.
For Market Incumbents: Anticipate refrigerant technology swap demands by securing retrofit-compatible filling machine architectures before 2027 deployment deadlines. Backward integration into permanent magnet motor sourcing reduces exposure to Japanese supplier lead time volatility. Prioritize predictive maintenance service bundling to lock in recurring revenue streams as capital purchase models erode. For New Entrants and Emerging Players: Enter via AI-vision module specialization for defect rejection systems serving United States co-manufacturers seeking subscription-based quality automation. White-space concentration exists in Indian dairy packaging corridors where PLI scheme incentives attract greenfield automation without incumbent entrenchment. Lead with vibration monitoring and machine learning algorithm bundles rather than hardware-centric positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap pharmaceutical containment specialists in Swiss-border manufacturing zones facing Swissmedic certification timeline compression. Long-term viability centers on cleanroom serialization capabilities insulated from commodity food processing margin erosion. Monitor auditor availability constraints for ISO 22000 certification as inflection indicator for validation service demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Retrofit Certification | EU F-Gas Regulation compliance secures aseptic filling line eligibility in Bavarian dairy corridors. |
| AI-Vision Service Bundling | Predictive maintenance subscriptions create recurring revenue from United States co-manufacturer contracts. |
| Backward Integration into Servo Motors | In-house production of precision motion control reduces dependency on Japanese supplier networks. |
| Pharmaceutical Serialization Investment | EMA Medical Device Regulation compliance commands premium pricing in German cleanroom installations. |
| India PLI Scheme Localization | Maharashtra and Gujarat dairy packaging corridors attract greenfield automation with government incentive backing. |
Methodological Framework
Multi-period observation of capital expenditure flows, refrigerant retrofit timelines, and equipment-as-a-service contract proliferation anchored the trend analysis, supplemented by interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers. Secondary validation drew from SEC filings of listed machinery conglomerates, EU ECHA substance restriction updates, FDA serialization guidance documents, and customs data on precision motion control component trade flows. Bottom-up line installation tracking and top-down sectoral spend analysis were triangulated against manufacturer order backlogs.
Segment-weighting across equipment type, end-use vertical, technology layer, and application hierarchy determined value allocation throughout the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle compression, and greenfield automation intensity across dairy, pharmaceutical, and co-manufacturing corridors. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and FDA track-and-trace mandate compliance timelines as demand pull factors.
Revisions become necessary when refrigerant technology transitions accelerate beyond equipment recertification capacity, or when servo motor supply concentration triggers allocation rationing among machinery OEMs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Pre-Assembled Packaging Market